
 Vacuum Insulated Pipe Market | 2026-2036
Vacuum Insulated Pipe Market Size, Share, and Industry Trends Forecast 2026-2036
Vacuum Insulated Pipe Market Analysis
Multi-source procurement for cryogenic-grade stainless steel is shifting toward vertically integrated suppliers with in-house vacuum jacketing capability. Chart Industries leverages captive helium leak testing to sustain its position in LNG distribution systems. Cryotherm GmbH and Co. KG anchors European hydrogen liquefaction projects with German-engineered vacuum insulation technology. Demaco Holland BV differentiates through modular skid-mounted pipe assemblies that reduce field installation labor.
Vacuum insulated pipe consists of an inner product tube and outer jacket maintained under high vacuum with multi-layer insulation to minimize radiative and conductive heat transfer, achieving thermal conductivity values below 0.0002 W/m·K. This construction enables cryogenic fluids such as liquid nitrogen, LNG, and liquid hydrogen to transport over long distances with boil-off rates under 0.5% per kilometer. Metal pipe dominates current installations due to established welding protocols and pressure vessel code compliance, while flexible pipe represents the fastest-growing product category as hydrogen refueling networks require routing around existing infrastructure. Cryogenic applications command the largest application share, though energy storage installations for liquid air energy storage systems are emerging as a high-margin segment.
ASME B31.3 process piping codes and ISO 20485 vacuum insulation standards govern product qualification, while the EPA's New Source Performance Standards for LNG facilities mandate leak detection that favors double-wall vacuum insulated construction. The EU's F-Gas Regulation and hydrogen backbone initiatives under the EU Green Deal are redirecting procurement specifications toward hydrogen-compatible materials and extended vacuum lifetimes. Stakeholders must monitor evolving hydrogen purity specifications from national metrology institutes and assess whether existing vacuum insulation warranties transfer to pure hydrogen service.
Market Dynamics
US LNG export terminal operators are scaling kilometer-length vacuum insulated piping orders as the EPA tightens methane emission standards for liquefaction facilities, compressing procurement timelines and favoring double-wall construction.
Growth Catalysts
- EPA New Source Performance Standards:Methane leak detection mandates for LNG facilities are accelerating specification of double-wall vacuum insulated pipe over single-wall alternatives.
- Liquid hydrogen transport infrastructure:Hydrogen backbone initiatives under the EU Green Deal are pulling demand for extended vacuum lifetime specifications and hydrogen-compatible materials.
- Texas-Louisiana Gulf Coast cluster expansion:New liquefaction trains at multiple export terminals require cryogenic distribution systems spanning multiple kilometers per facility.
Market Restraints
- Helium supply concentration:Captive helium leak testing capacity concentrates among vertically integrated suppliers, creating bottlenecks for quality assurance.
- Cryogenic-grade stainless steel volatility:Nickel and chromium input costs fluctuate with mining supply disruptions, compressing fabrication margins.
- Flexible pipe substitution in hydrogen refueling:Polymer-composite flexible lines compete for short-run applications below 500 meters.
Strategic Opportunities
- Liquid air energy storage:Cryogenic energy storage installations represent an emerging high-margin application segment with distinct thermal cycling requirements.
- Modular skid-mounted assemblies:Pre-fabricated pipe systems reduce field installation labor and accelerate project commissioning timelines.
- ISO 20485 vacuum lifetime extension:Certification to extended vacuum maintenance protocols opens hydrogen liquefaction project eligibility.
Industry Challenges
- ASME B31.3 welder certification scarcity:Qualified cryogenic pressure vessel welders command premium wages and extended lead times.
- Multi-layer insulation installation precision:Radiation shield spacing tolerances below 0.1 millimeters require specialized cleanroom fabrication environments.
- Legacy system integration:Retrofit projects must interface with existing cryogenic infrastructure using incompatible flange specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vacuum Insulated Pipe Market |
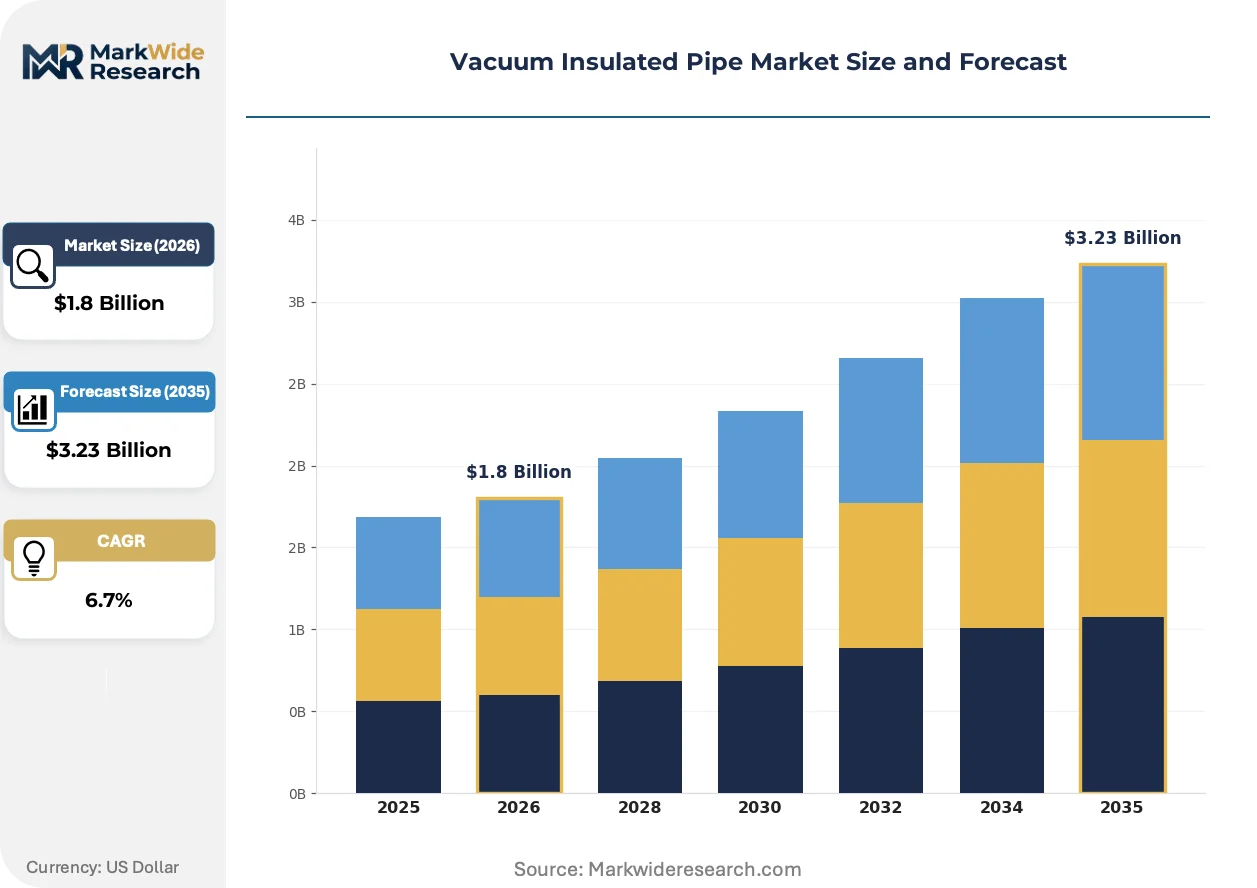
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multi-Layered Pipe, Composite Pipe, Metal Pipe, Flexible Pipe Application: Cryogenic Applications, Industrial Insulation, Energy Storage, Refrigeration Systems End User: Oil & Gas, Food & Beverage, Pharmaceuticals, Aerospace Installation: Above Ground, Below Ground, Indoor, Outdoor |
| Companies Covered | Senior Flexonics Inc., PHPK Technologies, Chart Industries, Cryotherm GmbH and Co. KG, Thames Cryogenics Ltd., Demaco Holland BV, Acme Cryogenics Inc., Ability Engineering Technology, Cryofab Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vacuum Insulated Pipe Market Emerging Trajectories
Flexible vacuum insulated pipe technology is compressing installation timelines for hydrogen refueling networks while regulatory pressure on methane emissions reshapes material specifications across LNG infrastructure.
Flexible vacuum insulated pipe is decentralizing hydrogen distribution architecture by enabling routing around existing utility corridors and congested industrial zones. Hydrogen refueling station developers in Germany and Japan are specifying corrugated stainless steel inner tubes with polymer outer jackets for runs under one kilometer. This flexibility is compressing civil engineering costs and accelerating site permitting by avoiding excavation of dedicated trenching.
The EU F-Gas Regulation is restricting high-global-warming-potential blowing agents in insulation systems, forcing reformulation of multi-layer insulation spacers. Vacuum insulated pipe manufacturers are transitioning to aerogel and glass fiber alternatives to maintain thermal performance. LNG terminal projects in the Netherlands and Belgium are requiring F-Gas-compliant documentation for all cryogenic piping procurement.
Integrated service contracts bundling installation, vacuum maintenance, and thermal performance guarantees are displacing component-only sales in large-scale LNG projects. Terminal operators in the United States and Qatar are negotiating decade-long performance contracts with vacuum integrity warranties. This shift compresses supplier margins upfront while locking in long-term aftermarket revenue streams.
Vacuum Insulated Pipe Market Segmentation
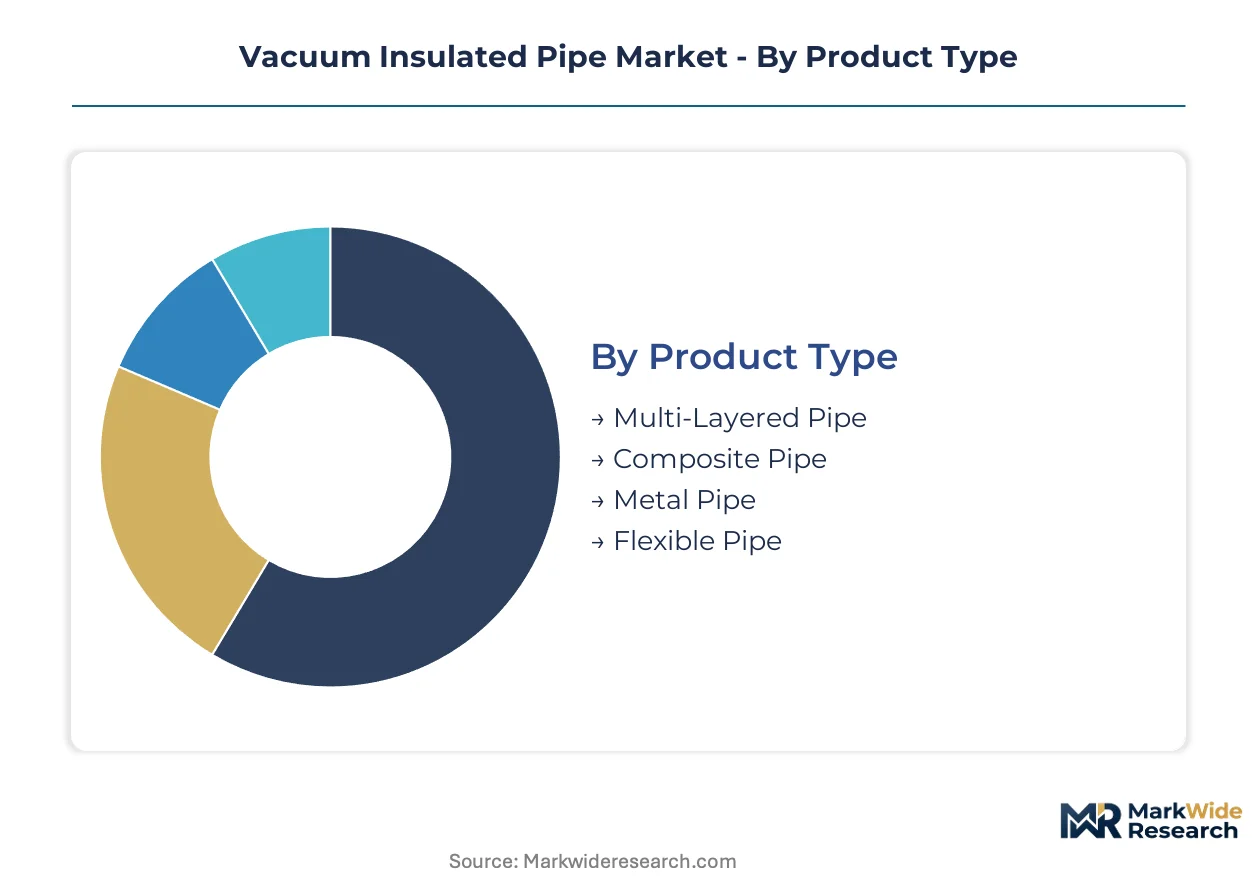
Vacuum insulated pipe segmentation reflects divergent engineering requirements across cryogenic temperature ranges, pressure ratings, and installation environments. Specification decisions cascade through material selection, insulation architecture, and warranty terms.
Product Type:
Customization intensity spans from rigid, code-certified metal systems to highly adaptable flexible configurations engineered for congested infrastructure corridors.
- Metal Pipe:Stainless steel inner tubes with vacuum-jacketed outer shells dominate LNG export terminal installations across Texas and Louisiana Gulf Coast clusters. ASME B31.3 compliance and established welding protocols anchor procurement specifications for kilometer-scale cryogenic distribution systems at liquefaction facilities.
- Flexible Pipe:Corrugated stainless steel inner cores with polymer outer jackets enable hydrogen refueling station developers in Germany and Japan to route around existing utility corridors. This adaptability compresses civil engineering costs and accelerates permitting timelines for sub-kilometer runs.
- Multi-Layered Pipe:Radiation shield assemblies with sub-millimeter spacing tolerances achieve thermal conductivity below 0.0002 W/m·K.
- Composite Pipe:Hybrid material constructions target liquid air energy storage installations with distinct thermal cycling demands.
Leading the category by volume: Metal Pipe. Expanding most quickly: Flexible Pipe.
Application:
Margin profiles diverge sharply between mature cryogenic fluid transport and emerging energy storage architectures with unproven duty cycles.
- Cryogenic Applications:Liquid nitrogen, LNG, and liquid hydrogen transport command the largest application share through boil-off rate guarantees under 0.5% per kilometer. EPA methane emission standards for liquefaction facilities are accelerating specification of double-wall vacuum insulated construction over single-wall alternatives.
- Energy Storage:Liquid air energy storage systems represent an emerging high-margin segment with distinct thermal cycling requirements and extended vacuum lifetime specifications. EU Green Deal hydrogen backbone initiatives are pulling demand for hydrogen-compatible materials in this nascent category.
- Industrial Insulation:Process cooling and thermal management applications span chemical manufacturing and semiconductor fabrication facilities.
- Refrigeration Systems:Cold chain logistics and superconducting magnet cooling drive specialized compact diameter specifications.
Dominant by revenue: Cryogenic Applications. Steepest expansion trajectory: Energy Storage.
End User:
Procurement sophistication ranges from commodity-driven food processing specifications to aerospace qualification protocols requiring traceability documentation.
- Oil & Gas:LNG export terminal operators in the United States are scaling kilometer-length vacuum insulated piping orders as liquefaction train expansions compress procurement timelines. Double-wall construction mandates under EPA New Source Performance Standards favor suppliers with captive helium leak testing capacity.
- Pharmaceuticals:Cryogenic biologics storage and distribution require validated thermal performance documentation and extended vacuum integrity warranties.
- Food & Beverage:Liquid nitrogen freezing systems and cold chain infrastructure drive standardized diameter specifications.
- Aerospace:Launch vehicle propellant loading and satellite ground support equipment demand ultra-lightweight, high-reliability configurations.
Primary volume driver: Oil & Gas. Gaining share fastest: Pharmaceuticals.
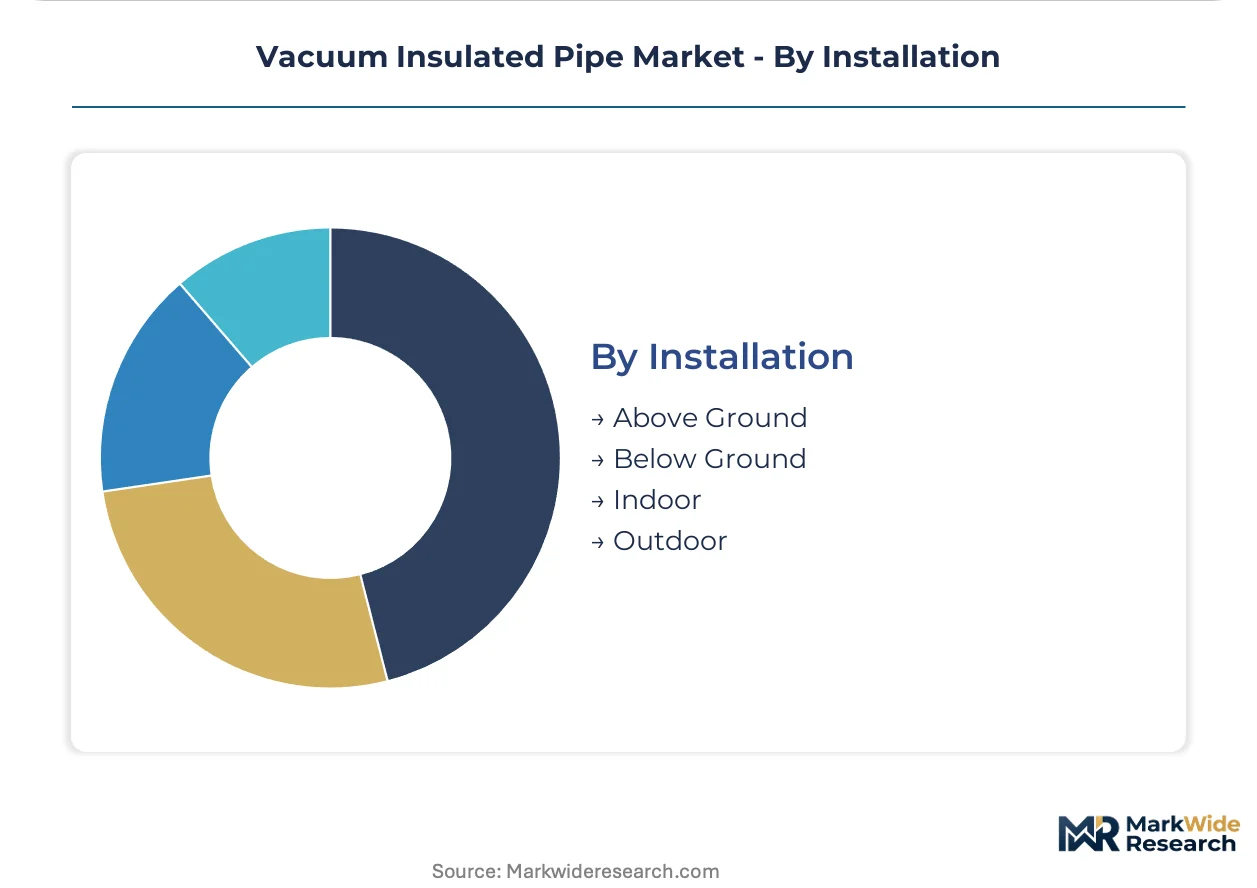
Installation:
Field conditions dictate vacuum maintenance protocols, with below-ground installations requiring enhanced corrosion protection and extended warranty structures.
- Below Ground:Trench installations across Texas and Louisiana Gulf Coast LNG terminals demand cathodic protection integration and soil chemistry compatibility assessments. Modular skid-mounted assemblies are displacing field fabrication to reduce installation labor and accelerate commissioning.
- Above Ground:Elevated pipe racks and structural supports enable inspection access and simplified leak detection integration.
- Indoor:Controlled environments accommodate cleanroom fabrication tolerances for multi-layer insulation precision.
- Outdoor:Weather exposure drives outer jacket material selection and UV stabilization requirements.
Maximum project scale: Below Ground. Fastest specification growth: Above Ground.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for vacuum insulated pipe concentrates in liquefaction clusters along the US Gulf Coast, European hydrogen backbone corridors, and Asian hydrogen refueling networks. Procurement timelines compress where emission regulations tighten. Installation scale varies from kilometer-length terminal distribution to sub-kilometer station feeds.
United States
EPA New Source Performance Standards for methane leak detection are accelerating double-wall vacuum insulated pipe specifications at LNG export terminals. Liquefaction train expansions in Texas and Louisiana Gulf Coast clusters require cryogenic distribution systems spanning multiple kilometers per facility. Terminal operators favor suppliers with captive helium leak testing capacity to compress quality assurance timelines.
Germany
Hydrogen backbone initiatives under the EU Green Deal are pulling demand for extended vacuum lifetime specifications and hydrogen-compatible materials. The F-Gas Regulation restricts high-global-warming-potential blowing agents, forcing reformulation of multi-layer insulation spacers. Hydrogen refueling station developers in industrial zones specify corrugated stainless steel flexible configurations to route around congested utility corridors.
Netherlands
LNG terminal projects in Rotterdam and Antwerp require F-Gas-compliant documentation for all cryogenic piping procurement. Modular skid-mounted pipe assemblies reduce field installation labor and accelerate commissioning timelines for below-ground trench installations. National hydrogen import strategies are extending vacuum integrity warranty requirements for liquid hydrogen transport infrastructure.
Japan
Hydrogen refueling network expansion drives specification of flexible vacuum insulated pipe for sub-kilometer routing around existing infrastructure. METI hydrogen roadmap targets compress civil engineering costs and accelerate site permitting by avoiding dedicated trenching. Corrugated stainless steel inner tubes with polymer outer jackets dominate station connection specifications.
Qatar
LNG export capacity expansion projects negotiate decade-long integrated service contracts bundling installation, vacuum maintenance, and thermal performance guarantees. Integrated contracts displace component-only sales and lock in long-term aftermarket revenue streams for suppliers. Above-ground elevated pipe racks enable inspection access and simplified leak detection integration at scale.
Vacuum Insulated Pipe Market Vendor Landscape
Capacity expansion dominates the current landscape as LNG terminal operators compress procurement timelines for kilometer-scale cryogenic distribution systems. The vendor base stratifies between vertically integrated suppliers with captive testing capability and specialized fabricators focused on modular assembly. Three archetypes occupy distinct positions: integrated cryogenic system houses, flexible pipe specialists, and regional fabrication shops with cleanroom MLI capability. M&A activity and strategic partnerships concentrate helium leak testing capacity and vacuum jacketing expertise among fewer hands.
Among US-based integrated suppliers, Chart Industries and Acme Cryogenics Inc. exemplify the vertically integrated archetype with in-house vacuum jacketing and quality assurance capability. Cryotherm GmbH and Co. KG represents German-engineered vacuum insulation technology positioned for European hydrogen liquefaction projects. Demaco Holland BV occupies a specialist position in modular skid-mounted pipe assemblies that reduce field installation labor. These three companies anchor distinct competitive vectors: captive testing, regional hydrogen infrastructure, and pre-fabricated system delivery.
| Leading Market Players |
|---|
| Senior Flexonics Inc. |
| PHPK Technologies |
| Chart Industries |
| Cryotherm GmbH and Co. KG |
| Thames Cryogenics Ltd. |
| Demaco Holland BV |
| Acme Cryogenics Inc. |
| Ability Engineering Technology |
| Cryofab Inc. |
| Others |
Supply Flow & Price Mechanics
Captive helium leak testing capacity among vertically integrated suppliers anchors both supply security and pricing power in vacuum insulated pipe procurement. Terminal operators in Texas and Louisiana Gulf Coast clusters pay premiums for suppliers with in-house vacuum jacketing capability, compressing margins for fabricators dependent on outsourced quality assurance.
Pricing Analysis
Performance-guarantee bundling separates integrated service contracts from component-only sales in LNG terminal procurement. Three-tier pricing structure across premium, standard, and economy levels reflects vacuum lifetime certification, with ISO 20485 extended-warranty specifications commanding substantial premiums over baseline offerings. Cost compression in standard-tier metal pipe is intensifying because nickel and chromium input volatility squeezes fabrication margins. Hydrogen refueling station developers exhibit highest price sensitivity, while LNG export terminal operators prioritize thermal performance guarantees over unit economics.
Supply Chain Analysis
Multi-supplier qualification mandates from major LNG terminal operators require dual-sourcing of cryogenic-grade stainless steel across Germany, Japan, and the United States. Fabrication draws from nickel and chromium feedstocks, multi-layer insulation spacers, and specialized vacuum pumps. Single-source vulnerability concentrates in captive helium leak testing capacity among Chart Industries and Acme Cryogenics. Distribution runs through direct terminal operator contracts and EPC contractor specifications for modular skid-mounted assemblies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
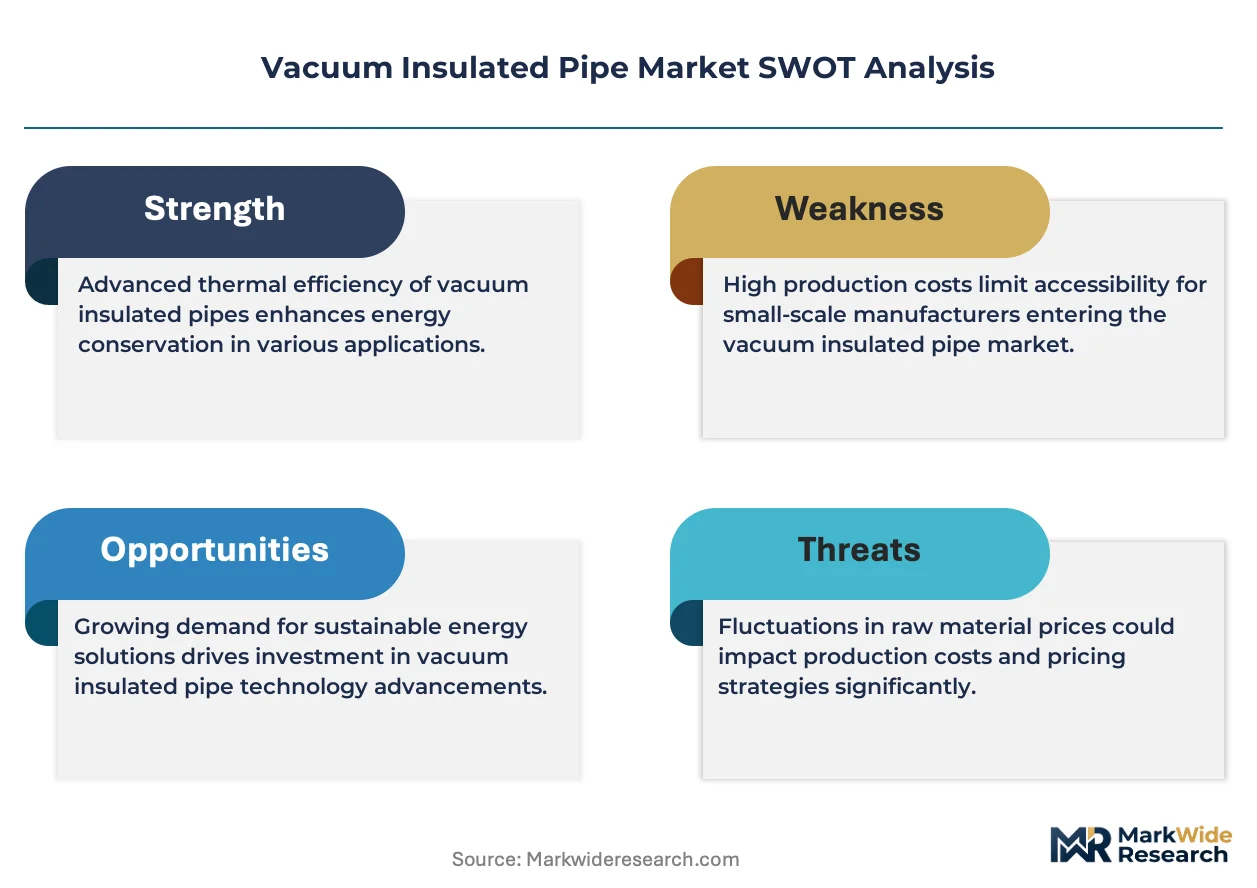
EPA New Source Performance Standards for methane leak detection erect a cost-of-compliance barrier that favors incumbent suppliers with established double-wall construction capability and captive testing infrastructure.
For Market Incumbents: Deepen backward integration into cryogenic-grade stainless steel supply to buffer nickel and chromium price volatility. Expand captive helium leak testing capacity to capture compressed procurement timelines at Texas and Louisiana Gulf Coast LNG terminals. Secure decade-long integrated service contracts with Qatar and US terminal operators to lock in aftermarket revenue streams against flexible pipe substitution threats.
For New Entrants and Emerging Players: Liquid air energy storage developers represent an underserved buyer archetype with distinct thermal cycling requirements and limited incumbent penetration. Target German and Dutch hydrogen liquefaction projects requiring F-Gas-compliant multi-layer insulation reformulation. Pursue modular skid-mounted assembly partnerships with Demaco Holland BV to bypass field welder certification scarcity.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated cryogenic system houses seeking vacuum jacketing capability. Long-term viability hinges on hydrogen backbone infrastructure deployment across EU Green Deal corridors. Watch for national metrology institutes publishing pure hydrogen service warranty transfer protocols as the inflection signal for hydrogen-compatible material valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stainless Steel Supply | Mitigates nickel and chromium price volatility for Texas and Louisiana Gulf Coast LNG terminal contracts. |
| ISO 20485 Extended Vacuum Lifetime Certification | Opens eligibility for EU Green Deal hydrogen liquefaction projects with decade-long performance requirements. |
| Modular Skid-Mounted Assembly Expansion | Reduces field installation labor and accelerates commissioning timelines for below-ground trench installations. |
| F-Gas-Compliant Multi-Layer Insulation Reformulation | Enables Rotterdam and Antwerp LNG terminal procurement under EU F-Gas Regulation restrictions. |
| Flexible Pipe Manufacturing Scale-Up | Captures hydrogen refueling network demand in Germany and Japan for sub-kilometer routing applications. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this vacuum insulated pipe market assessment. Primary interviews with LNG terminal procurement directors, EPC contractor specification engineers, cryogenic equipment plant managers, and hydrogen refueling station developers combined with EPA enforcement records, EU F-Gas Regulation compliance databases, and ASME certification registries. Bottom-up project pipeline analysis and top-down industrial gas infrastructure spending triangulated volume estimates.
Segmentation granularity spanned product type, application temperature range, pressure rating, and installation environment across the projection horizon. Metal pipe, flexible pipe, multi-layered pipe, and composite pipe categories were modeled separately with distinct thermal performance assumptions. Cryogenic applications, energy storage, industrial insulation, and refrigeration systems each carried unique margin and growth trajectories. CAGR derivation incorporated liquefaction train expansion timelines, hydrogen backbone deployment schedules, and liquid air energy storage project announcements.
Revisions become necessary when EPA methane emission standards tighten beyond current New Source Performance Standards, EU hydrogen purity specifications shift, or helium supply disruptions materialize. Deviation in nickel and chromium mining output would shift fabrication cost assumptions materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Global Automotive Valves Market
Valves
Valve Sack Market
Valves
Steam Trap Valve Market
Valves
Carbon Seal Rings Market
Valves
Large Bore Vacuum Insulated Pipe Market
Valves
Global Valves in Chemical Market
Valves
Middle East and Africa Machined Seals Market
Valves
Explosion Isolation Valves Market
Valves
Lined Valves Market
Valves
Mooring Inspection Market
Valves
Global Globe Valve Market
Valves
Global Plastic Valves Market
Valves
Wind Energy Fasteners Market
Valves
Pneumatic Needle Valves Market
Valves
Pup Joint Market
Valves
Industrial Vacuum Valves Market