
 Large Bore Vacuum Insulated Pipe Market | 2026-2036
Large Bore Vacuum Insulated Pipe Market Size, Share, and Industry Trends Forecast 2026-2036
Large Bore Vacuum Insulated Pipe Market Analysis
The capital-intensity divergence between cryogenic system specialists and diversified industrial conglomerates is rotating competitive advantage toward vertically integrated gas handlers. Linde AG leverages captive helium and hydrogen project pipelines to anchor long-term pipe supply agreements. Chart Industries sustains manufacturing scale across bilayer and multilayer configurations. Demaco Holland B.V. specializes in custom-engineered transfer solutions for European LNG import terminals.
Large bore vacuum insulated pipe consists of concentric tubular assemblies with annular vacuum spaces, typically employing stainless steel inner and outer shells separated by low-conductivity spacers, designed to minimize heat ingress during cryogenic fluid transport over extended distances. The coaxial segment dominates installed base in LNG baseload terminals due to proven thermal performance below minus 160 degrees Celsius, while multilayer configurations capture expanding share in hydrogen distribution pilots where hydrogen embrittlement resistance demands material stratification. Aerospace end users prioritize carbon steel and copper material grades for weight-critical launch vehicle applications, whereas energy sector procurement gravitates toward stainless steel for offshore durability.
ASME Section VIII and ISO 20485 vacuum standards govern design qualification and quality assurance protocols, with the EU F-Gas Regulation indirectly shaping demand through fluorinated gas phase-down timelines that elevate cryogenic recovery economics. The US DOT PHMSA oversees interstate hydrogen and natural gas liquid pipeline safety, creating compliance thresholds for large-diameter vacuum systems crossing federal jurisdiction. Stakeholders must monitor evolving hydrogen pipeline codes and carbon border adjustment mechanisms to anticipate specification shifts and qualification investments.
Market Dynamics
The US DOT PHMSA's pending hydrogen pipeline safety rules are forcing terminal operators to pre-qualify vacuum insulated pipe systems before federal jurisdiction triggers, compressing vendor selection timelines and elevating specification rigor across LNG and hydrogen infrastructure projects.
Growth Catalysts
- Qatar North Field East expansion:The world's largest LNG project is commissioning cryogenic transfer systems exceeding 48-inch diameters, creating precedent-setting demand for multilayer vacuum insulation configurations in extreme-scale liquefaction.
- EU F-Gas Regulation phase-down:The 2030 fluorinated gas reduction targets are elevating boil-off gas recovery economics, mandating vacuum insulated pipe retrofits at European LNG import terminals to minimize methane slip.
- Stainless steel 316L cryogenic grades:Advanced austenitic alloys with enhanced hydrogen embrittlement resistance are enabling extended-duration hydrogen transport pilots in Germany and the Netherlands.
Market Restraints
- Helium supply concentration:Qatar and the United States control over 75% of global helium production, creating input cost volatility for leak detection protocols essential to vacuum integrity validation.
- ASME Section VIII qualification timelines:The pressure vessel code's extended certification cycles for large-diameter systems delay project commissioning by 14-18 months, freezing capital deployment.
- Conventional foam-insulated pipe:Polyurethane foam systems retain cost advantages in short-distance, above-ground applications, capturing budget-constrained industrial gas distribution projects.
Strategic Opportunities
- Australia hydrogen export hubs:The Pilbara and Gladstone clusters are designing 100% hydrogen-ready LNG terminals, specifying vacuum insulated pipe for dual-use cryogenic service from project inception.
- Carbon border adjustment mechanisms:The EU CBAM's phased implementation is incentivizing boil-off gas minimization investments at LNG receiving terminals in Algeria and Nigeria to preserve market access.
- Digital twin integration:Real-time thermal performance monitoring fused with predictive maintenance algorithms is opening service contract revenue streams for pipe system vendors.
Industry Challenges
- Vacuum technician scarcity:Specialized skills for annular space evacuation and long-term seal integrity testing are concentrated among aging workforces in Germany and Japan, constraining manufacturing scale-up.
- ISO 20485 audit complexity:The vacuum technology standard's evolving quality assurance protocols require redundant documentation systems that extend project engineering phases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Large Bore Vacuum Insulated Pipe Market |
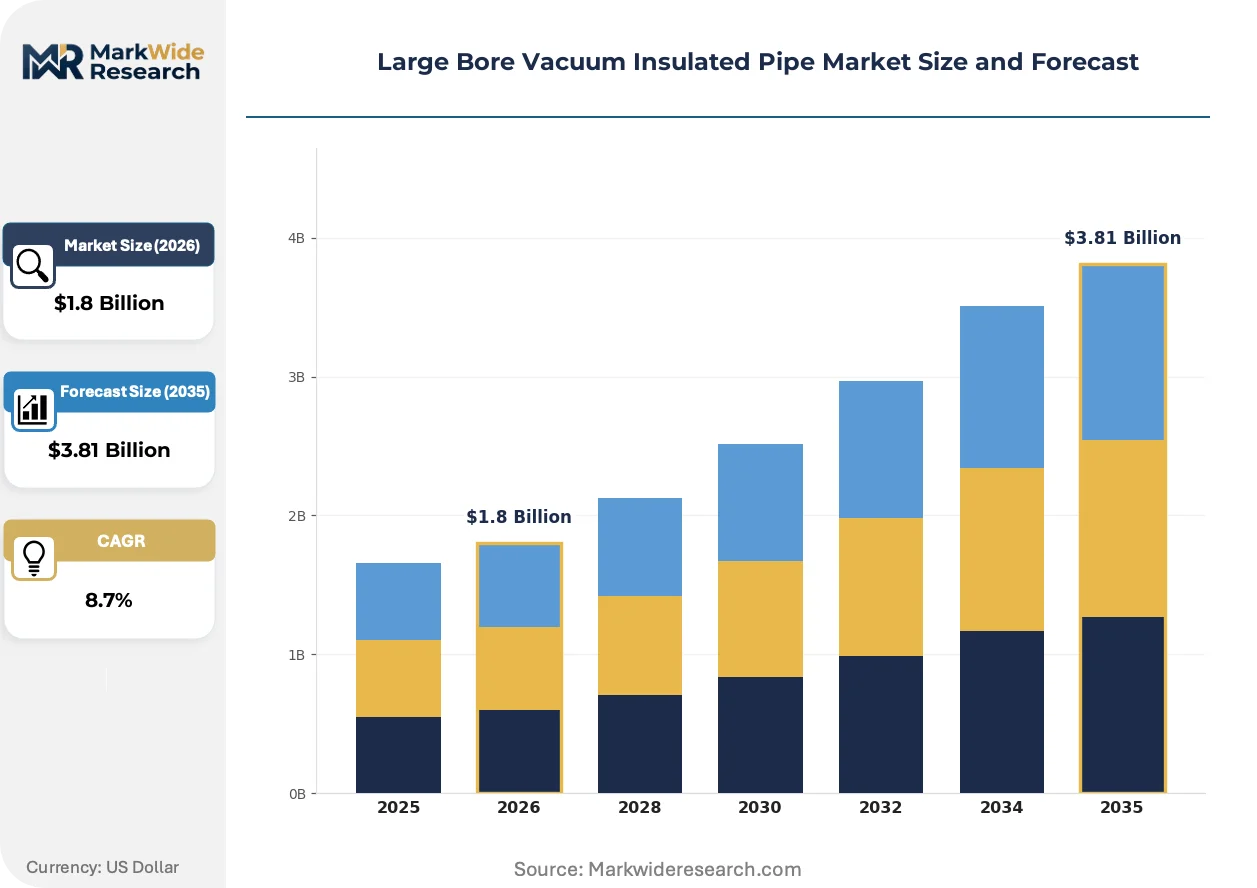
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Pipe Type: Coaxial, Bilayer, Multilayer, Single Layer Material: Stainless Steel, Carbon Steel, Copper, Plastic Application: Cryogenic Storage, Thermal Transfer, Industrial Process, Transportation End User: Oil & Gas, Chemical Processing, Energy Sector, Aerospace |
| Companies Covered | Linde AG, Air Products and Chemicals, Inc., Parker Hannifin Corporation, Chart Industries, Cryogenic Industries, InTech GmbH, Demaco Holland B.V., Perma-Pipe International Holdings Inc., CRYOSPAIN, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Large Bore Vacuum Insulated Pipe Market Emerging Trajectories
Materials science breakthroughs and regulatory code evolution are converging to redefine performance benchmarks for cryogenic fluid containment, with hydrogen service requirements now driving specification changes faster than traditional LNG applications.
Multilayer insulation systems employing alternating reflective shields and fiberglass paper are displacing conventional perlite powder fill in hydrogen distribution pilots. Japanese hydrogen station operators are specifying these configurations for 700-bar gaseous hydrogen precooling lines. The shift is compressing acceptable heat leak thresholds by 40% versus legacy LNG baseload standards.
The EU F-Gas Regulation's 2024 tightening of fluorinated gas reporting obligations is mandating continuous leak monitoring at LNG terminals. Terminal operators in Rotterdam and Zeebrugge are retrofitting vacuum insulated pipe corridors with integrated sensor networks. The compliance burden is accelerating replacement cycles for pre-2015 installed base systems.
Long-term thermal performance guarantees are displacing upfront equipment sales in terminal operator procurement. Engineering-procurement-construction contractors in the United States are negotiating 20-year service agreements bundling pipe supply, installation, and vacuum maintenance. The model concentrates vendor risk in Gulf Coast liquefaction clusters where project finance covenants demand operational certainty.
Large Bore Vacuum Insulated Pipe Market Segmentation
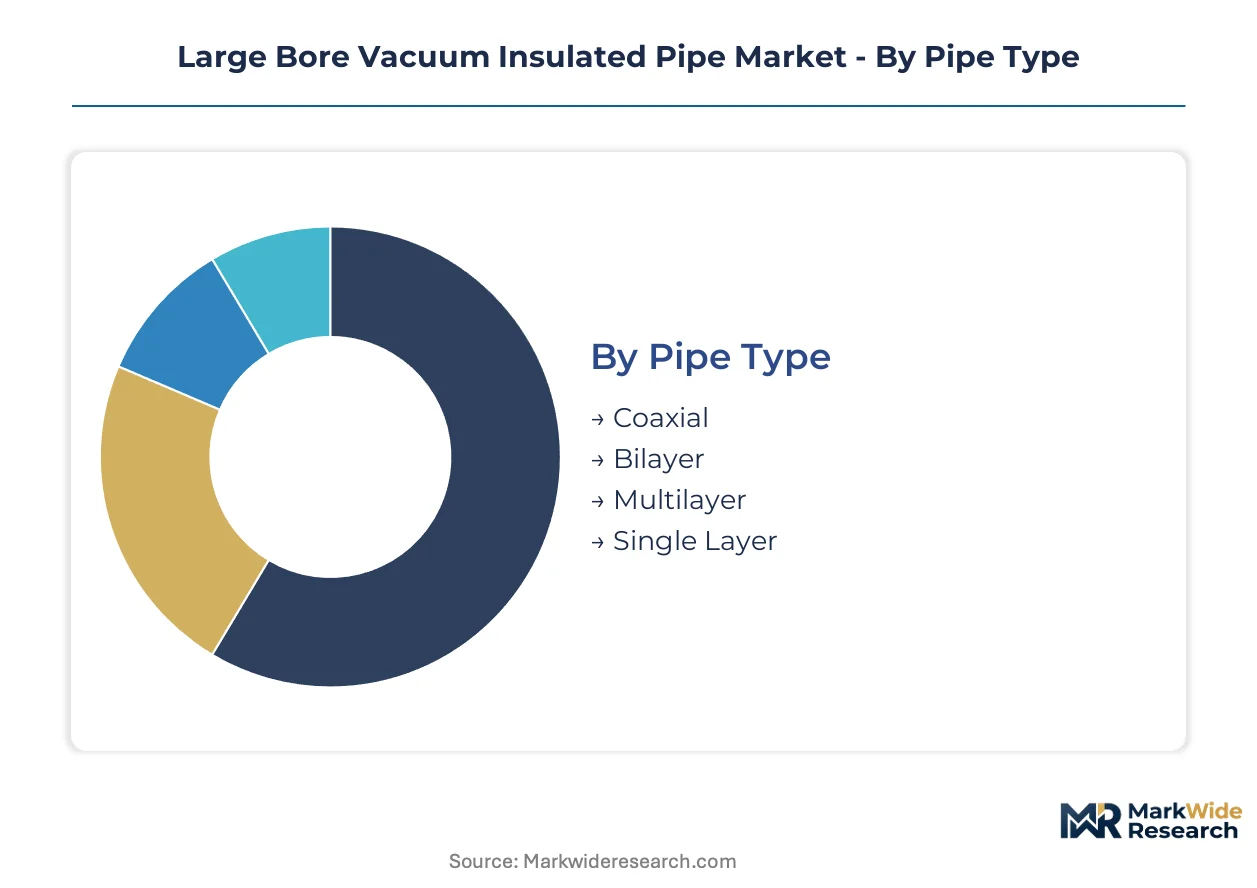
Cryogenic infrastructure procurement requires precise matching of pipe architecture to fluid properties, thermal duty cycles, and regulatory exposure. Segmentation discipline separates commodity replacement demand from engineered system specifications where lifecycle cost dominates capital outlay.
Pipe Type:
Margin pools concentrate in multilayer configurations where hydrogen embrittlement resistance and extreme-scale diameters command engineering premiums.
- Coaxial:Concentric stainless steel tubes with annular vacuum space and low-conductivity spacers deliver proven thermal performance below minus 160 degrees Celsius. Baseload LNG terminals in Qatar, the United States, and Australia specify this architecture for liquefaction train interconnections where boil-off gas management dictates pipe specifications.
- Multilayer:Alternating reflective shields and fiberglass paper displace conventional perlite fill, compressing heat leak thresholds by 40% versus legacy standards. German and Dutch hydrogen transport pilots are specifying these configurations for 700-bar gaseous hydrogen precooling lines where material stratification resists embrittlement.
- Bilayer:Simplified dual-wall construction serves medium-duty industrial gas distribution with shorter transport distances.
- Single Layer:Basic insulated pipe retains niche presence in budget-constrained above-ground applications.
Coaxial holds installed capacity. Multilayer is rotating up the share rankings.
Material:
Specification rigor escalates fastest in austenitic grades where hydrogen service codes are rewriting qualification protocols.
- Stainless Steel:316L cryogenic grades with enhanced hydrogen embrittlement resistance enable extended-duration hydrogen transport. Offshore LNG terminals specify this material for salt-air durability.
- Carbon Steel:Weight-critical aerospace launch vehicle applications prioritize this grade for propellant feed systems where mass reduction overrides corrosion concerns.
- Copper:Thermal conductivity advantages serve specialized heat exchanger integration in Japanese hydrogen station infrastructure.
- Plastic:Polymer composites capture limited share in non-cryogenic thermal transfer where cost minimization dominates.
Stainless steel anchors current procurement volumes. Carbon steel is climbing the fastest in aerospace specification.
Application:
Customer type determines whether procurement optimizes for capital efficiency or operational certainty over multi-decade service life.
- Cryogenic Storage:Vacuum-insulated pipe corridors connect liquefaction trains to storage tanks, with EU F-Gas Regulation compliance mandating continuous leak monitoring retrofits at Rotterdam and Zeebrugge terminals.
- Thermal Transfer:Long-distance hydrogen distribution pilots in the Netherlands and Germany require heat ingress minimization across extended pipeline networks.
- Industrial Process:Short-distance above-ground systems compete with foam-insulated alternatives on capital cost.
- Transportation:Mobile cryogenic transfer systems for LNG bunkering and hydrogen road delivery.
Cryogenic storage dominates capital deployment. Thermal transfer is gaining share fastest as hydrogen infrastructure scales.
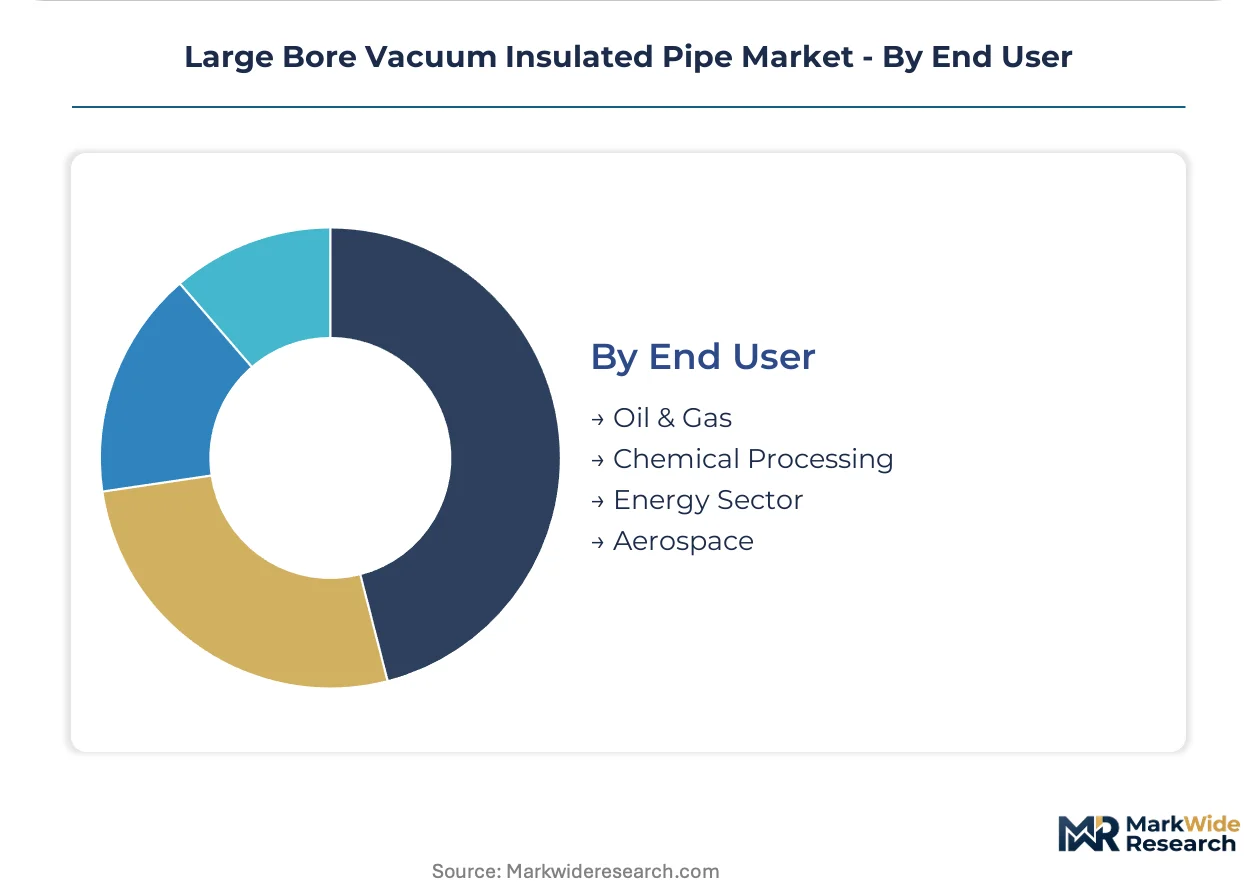
End User:
Project finance covenants in energy infrastructure are compressing vendor selection timelines and elevating long-term performance guarantee requirements.
- Oil & Gas:LNG export terminal operators in Qatar, the United States, and Australia are scaling cryogenic infrastructure investments with 20-year service agreements bundling pipe supply and vacuum maintenance.
- Energy Sector:Dual-use hydrogen-ready terminal designs in Australia's Pilbara and Gladstone clusters specify vacuum insulated pipe from project inception.
- Chemical Processing:Industrial gas producers prioritize reliability in high-volume oxygen and nitrogen distribution.
- Aerospace:Launch vehicle manufacturers specify carbon steel and copper grades for weight-critical propellant systems.
Oil & Gas commands the revenue base. Energy sector procurement is expanding most quickly as hydrogen export hubs advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The export-import balance between liquefaction capacity and regasification demand is redrawing procurement geography. Qatar, the United States, and Australia anchor liquefaction investments, while European and Asian import terminals drive retrofit demand for boil-off gas containment.
United States
Gulf Coast LNG export terminals in Texas and Louisiana are commissioning record-scale cryogenic transfer corridors. US DOT PHMSA's pending hydrogen pipeline safety rules are compressing vendor pre-qualification timelines. The Sabine Pass and Corpus Christi clusters specify multilayer vacuum insulated configurations for dual-use hydrogen-ready service.
Qatar
The North Field East expansion is commissioning transfer systems exceeding 48-inch diameters, creating precedent-setting demand for extreme-scale multilayer insulation. Qatar's national helium production dominance supports leak detection protocols essential to vacuum integrity validation. Ras Laffan Industrial City concentrates engineering procurement for the world's largest LNG project.
Germany
Hydrogen transport pilots in the Netherlands-Germany corridor are specifying 316L austenitic grades with enhanced embrittlement resistance. EU F-Gas Regulation phase-down targets mandate continuous leak monitoring retrofits at Wilhelmshaven and Brunsbüttel LNG terminals. The Ruhr industrial cluster is integrating vacuum insulated pipe into extended-duration hydrogen distribution networks.
Australia
The Pilbara and Gladstone hydrogen export hubs are designing 100% hydrogen-ready LNG terminals from project inception. Australian federal hydrogen strategy funding is accelerating dual-use cryogenic infrastructure specifications. The Port of Rotterdam partnership is driving technology transfer to Gladstone's emerging liquefaction cluster.
Netherlands
Rotterdam and Zeebrugge terminal operators are retrofitting vacuum insulated pipe corridors with integrated sensor networks for EU F-Gas compliance. The 2030 fluorinated gas reduction targets are elevating boil-off gas recovery economics. The Port of Rotterdam hydrogen backbone is specifying multilayer configurations for 700-bar gaseous hydrogen precooling.
Large Bore Vacuum Insulated Pipe Market Vendor Landscape
Concentration sits with diversified industrial gas handlers and cryogenic system specialists. The vendor base spans vertically integrated conglomerates with captive project pipelines and independent fabricators with custom-engineering capabilities. Two strategic archetypes dominate: industrial gas majors leveraging long-term supply agreements, and specialized cryogenic engineers capturing premium specifications. Competitive moves center on 20-year service contract bundling and hydrogen-ready qualification investments.
Among German-based industrial gas majors, Linde AG exemplifies the captive-project archetype, anchoring supply agreements through helium and hydrogen infrastructure ownership. Chart Industries occupies a position in the scale-driven tier, sustaining manufacturing breadth across pipe configurations. Demaco Holland B.V. represents the custom-engineering specialists, serving European LNG import terminals with transfer solution specialization. These three illustrate the competitive spectrum from integrated gas handlers to focused cryogenic fabricators.
| Leading Market Players |
|---|
| Linde AG |
| Air Products and Chemicals, Inc. |
| Parker Hannifin Corporation |
| Chart Industries |
| Cryogenic Industries |
| InTech GmbH |
| Demaco Holland B.V. |
| Perma-Pipe International Holdings Inc. |
| CRYOSPAIN |
| Others |
Supply Flow & Price Mechanics
Long-term service contracts bundling pipe supply, installation, and vacuum maintenance anchor procurement economics across Gulf Coast liquefaction clusters, locking in supply access while compressing price visibility for competing vendors. This structure concentrates buyer leverage with vertically integrated gas handlers and elevates barriers for independent fabricators seeking terminal operator qualification.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing stratification across premium ASME-certified systems, standard ISO-compliant configurations, and economy-grade above-ground alternatives. Price differentiation rests on certification grade and after-sales service bundling, with 20-year thermal performance guarantees commanding substantial premiums over transactional equipment sales. Cost compression in the economy tier intensifies as polyurethane foam-insulated pipe retains budget-constrained industrial gas projects. Chemical processing operators exhibit highest price sensitivity due to high-volume oxygen and nitrogen distribution economics, while LNG export terminal operators prioritize operational certainty over capital outlay minimization.
Supply Chain Analysis
Strategic stockpiling of 316L austenitic grades and specialized helium reserves characterizes procurement behavior among established cryogenic system vendors confronting input volatility. Manufacturing concentration centers on Germany, the United States, and Japan, drawing from Qatari helium production, South Korean specialty steel output, and domestic vacuum technician labor pools. Single-source vulnerability in helium supply creates exposure to geopolitical disruption and price spikes essential to leak detection protocols. Distribution runs through engineering-procurement-construction contractors with direct terminal operator relationships, bypassing traditional industrial distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent vendors must defend against substitution by conventional foam-insulated pipe in short-distance applications where capital efficiency trumps thermal performance, requiring strategic repositioning toward hydrogen-ready qualification investments.
For Market Incumbents: Compound hydrogen embrittlement resistance capabilities through 316L cryogenic grade certification investments and backward integration into specialty steel supply. Anchor long-term service agreements with Qatar North Field East and Australia Pilbara operators before federal hydrogen jurisdiction triggers compress vendor selection timelines. Prioritize vacuum technician training partnerships with German and Japanese technical institutes to alleviate workforce scarcity constraining manufacturing scale-up.
For New Entrants and Emerging Players: Differentiate on digital twin integration and predictive maintenance algorithms for EU F-Gas compliance retrofit demand at Rotterdam and Zeebrugge terminals. Target bilayer configuration white space in medium-duty industrial gas distribution where shorter transport distances reduce specification rigor. Pursue joint development partnerships with Australian hydrogen export hub developers seeking 100% hydrogen-ready terminal designs from project inception.
For Investors and Strategic Acquirers: Capital is best deployed toward custom-engineering specialists with European LNG import terminal relationships and established ISO 20485 qualification track records. Long-term viability hinges on hydrogen infrastructure scaling velocity across the Netherlands-Germany corridor and Gulf Coast dual-use terminal conversions. Watch ASME Section VIII certification timeline compression as inflection indicator for vendor consolidation acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen-Ready Qualification Investment | ASME Section VIII certification for dual-use LNG-hydrogen service captures Qatar and Australia terminal procurement. |
| Backward Integration into Specialty Steel | In-house 316L austenitic grade sourcing mitigates hydrogen embrittlement resistance supply risk. |
| Digital Twin Platform Development | Real-time thermal monitoring aligns with EU F-Gas continuous leak monitoring mandates at Rotterdam terminals. |
| Long-Term Service Contract Bundling | 20-year performance guarantees satisfy project finance covenants in Gulf Coast liquefaction clusters. |
| Vacuum Technician Training Partnership | German and Japanese technical institute collaboration alleviates workforce scarcity constraining manufacturing scale-up. |
Methodological Framework
A standing panel of LNG terminal engineering directors, cryogenic system procurement leads, ASME certification auditors, and EPC contractor project managers provided ongoing calibration against secondary validation from FERC filings, IEA hydrogen infrastructure databases, SEC 10-K industrial gas disclosures, and EU F-Gas Regulation compliance records. Bottom-up project pipeline tracking across Qatar North Field East, US Gulf Coast terminals, and Australia hydrogen hubs converged with top-down macroeconomic scenario modeling.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled encompass pipe type architecture, material grade specification, cryogenic storage versus thermal transfer application, and end-user industry vertical. CAGRs were derived from project commissioning schedules, infrastructure investment announcements, and regulatory code evolution timelines. Hydrogen pipeline safety rule development velocity and carbon border adjustment mechanism implementation pace served as industry-specific forecast sensitivity inputs.
Forecasts assume regulatory continuity in US DOT PHMSA jurisdiction, EU F-Gas phase-down timelines, and Australian federal hydrogen strategy funding; material policy shifts would require re-modeling of terminal operator procurement acceleration. Revision becomes warranted when helium supply disruption or ASME certification timeline extension crosses thresholds that freeze capital deployment in liquefaction clusters.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Pipeline Pigging Valves Market
Valves
HVAC Valves Market
Valves
Sliding Sleeves Market
Valves
Global Control Valves Market
Valves
Europe Vacuum Insulated Pipe Market
Valves
Wind Energy Fasteners Market
Valves
Thermal Power Valve Market
Valves
Global Gate Valve Market
Valves
Tank Hydrogen Valve Market
Valves
North America Valves Market
Valves
Valve Remote Control System Market
Valves
Pipeline Pigging System Market
Valves
Oil Drain Valves Market
Valves
Valve Driver Market
Valves
Flare Stack Monitoring Systems Market
Valves
Reciprocating Compressor Components Market