
 Global Automotive Valves Market | 2026-2036
Global Automotive Valves Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Valves Market Analysis
Market Context
Aftermarket service revenue is rewriting profit allocation across the valve value chain as extended vehicle lifespans shift replacement demand toward independent channels. Eaton Corporation leverages its hydraulic actuator integration to capture recurring maintenance contracts in North American heavy-duty fleets. Schaeffler AG anchors European OEM supply through its camshaft-valvetrain system bundling, while Denso Corporation dominates thermal management valve production for Japanese hybrid platforms.
Technical Definition and Segment Structure
Automotive valves are precision-engineered flow-control devices, typically manufactured from austenitic stainless steel or titanium alloys with stem diameters ranging from 5 to 8 millimeters, designed to regulate air-fuel mixture intake and exhaust gas expulsion in internal combustion engines. Engine valves occupy the largest revenue pool due to replacement-cycle density across legacy fleets, though control valves for thermal and emissions management represent the fastest-expanding segment as electrified powertrains multiply auxiliary fluid circuits. Electric vehicle application demand is accelerating fastest among vehicle categories, driven by battery thermal management and cabin heat-pump valve requirements that differ fundamentally from combustion-era specifications.
Regulatory Frame and Outlook
EPA tailpipe standards, Euro 7 emission frameworks, and China's MIIT fuel consumption regulations are collectively mandating tighter valve leakage tolerances and faster actuation response times, forcing material upgrades across supplier tiers. Japan's METI carbon neutrality roadmap and India's BIS automotive component standards are adding certification layers for imported valve assemblies. Stakeholders must monitor how battery-electric platform standardization reshapes valve specification volumes and whether solid-state battery thermal architectures eliminate or transform coolant valve roles.
Market Dynamics
The transition from mechanical to electromechanical valve actuation is compressing traditional supplier margins while opening new revenue pools in sensor-integrated smart valve systems for hybrid and electric powertrains.
Growth Catalysts
- EPA Tier 3 emission mandates:Tighter exhaust valve sealing tolerances are forcing material upgrades to Inconel and titanium alloys across North American engine production.
- Battery thermal management circuits:Electric vehicle platforms require multi-port coolant control valves with response times under 50 milliseconds, expanding addressable component value per vehicle.
- German powertrain clusters:Stuttgart and Munich anchor precision valve machining capacity, concentrating OEM procurement relationships and technical specification authority.
Market Restraints
- Titanium sponge supply concentration:Russian and Chinese smelters control over 60% of aerospace-grade titanium feedstock, exposing valve manufacturers to alloy price volatility and export restriction risk.
- Euro 7 certification timelines:The European Commission's extended validation protocols for exhaust valve durability are stretching new product introduction cycles by 8-14 months.
- Solid-state battery thermal architectures:Elimination of liquid coolant loops in next-generation battery designs threatens to displace entire categories of coolant control valves.
Strategic Opportunities
- India BIS component standards:Mandatory localization requirements for automotive valves under the PLI scheme create captive demand for domestic manufacturing investments.
- Heat pump valve convergence:Integration of cabin climate and battery thermal management circuits enables single-supplier capture of multiple fluid control functions per vehicle.
- Independent aftermarket channels:Extended vehicle lifespans in the United States and Japan are redirecting replacement valve demand away from dealer networks toward specialized distributors.
Industry Challenges
- Electromechanical actuation expertise scarcity:Valve suppliers lack embedded software and motor control engineering capacity for smart actuator development.
- Dual certification burden:Simultaneous compliance with EPA tailpipe standards and China's MIIT fuel consumption regulations requires parallel testing streams.
- Legacy engine platform support:Maintaining production lines for cast iron exhaust valves while scaling titanium intake valve capacity strains capital allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Valves Market |
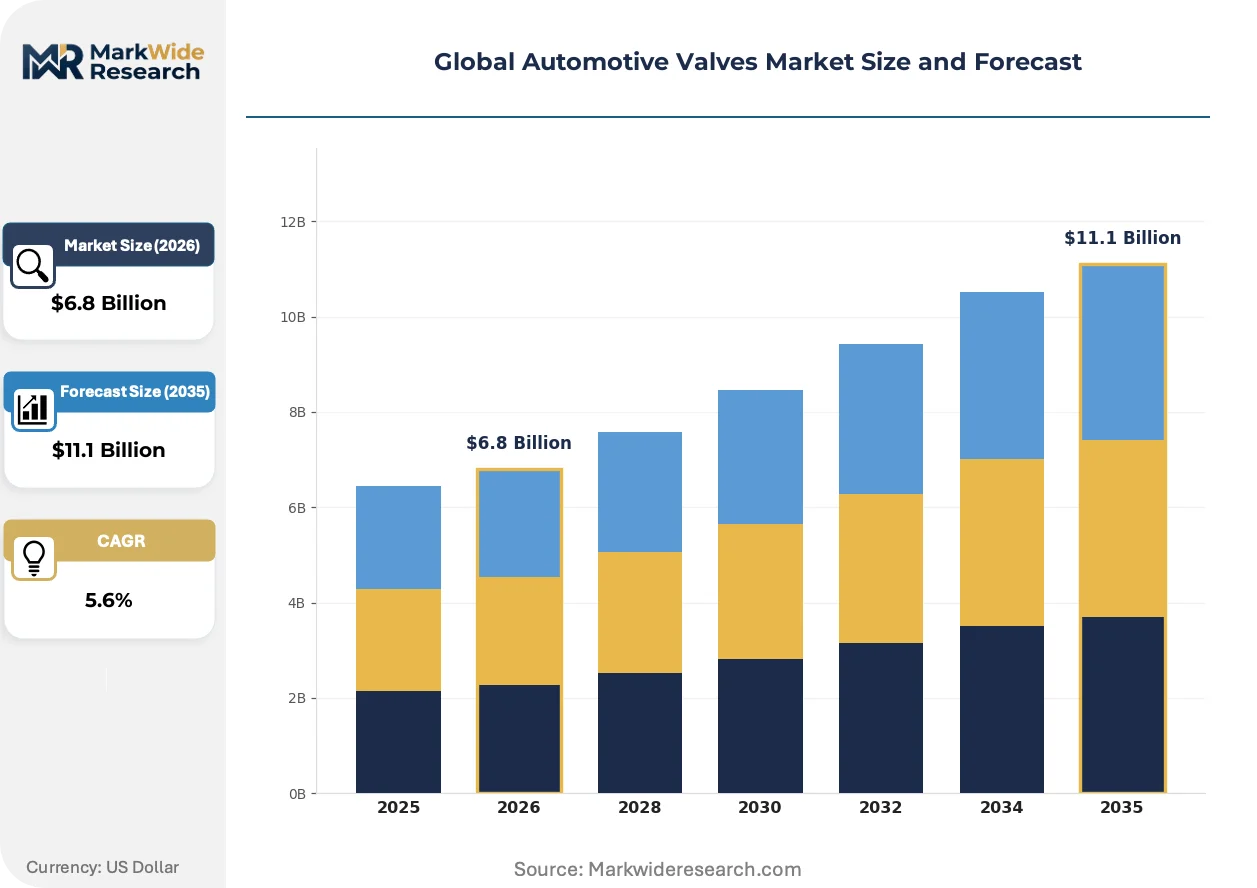
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.1 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Valves, Fuel Valves, Exhaust Valves, Control Valves Material: Aluminum, Steel, Titanium, Composite Application: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Racing Vehicles End User: OEMs, Aftermarket Providers, Fleet Operators, Tier-1 Suppliers |
| Companies Covered | Eaton Corporation, Schaeffler AG, Denso Corporation, BorgWarner Inc., Mahle Group, Robert Bosch GmbH, Aisin Corporation, Valeo SA, Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Valves Market Emerging Trajectories
Valve technology is bifurcating between precision refinement for remaining combustion applications and fundamental redesign for electrified thermal systems, with material science and embedded intelligence as the common threads.
Electromechanical valve actuation is migrating from camshaft-driven mechanical systems in high-performance combustion engines. BMW and Porsche engineering teams are validating fully variable lift systems for next-generation six-cylinder architectures. This migration is compressing the traditional camshaft supplier value chain while expanding demand for position sensors and motor controllers.
REACH restrictions on hexavalent chromium plating are forcing conversion to plasma-transferred wire arc coatings for valve stem wear resistance. The European Chemicals Agency's sunset date for hard chrome in automotive components falls in 2027, accelerating supplier qualification of alternative surface engineering. German and Italian valve manufacturers are consolidating coating capacity to amortize new capital equipment across higher volumes.
Fleet operators in North America are unbundling valve maintenance from full-service leasing contracts, creating direct procurement relationships with component suppliers. Heavy-duty truck operators now specify valve replacement intervals and brand preferences independently of vehicle OEM service agreements. This disintermediation is most visible in long-haul logistics corridors between Texas and California, where independent service networks capture valve replacement revenue previously retained by Detroit-based truck manufacturers.
Global Automotive Valves Market Segmentation
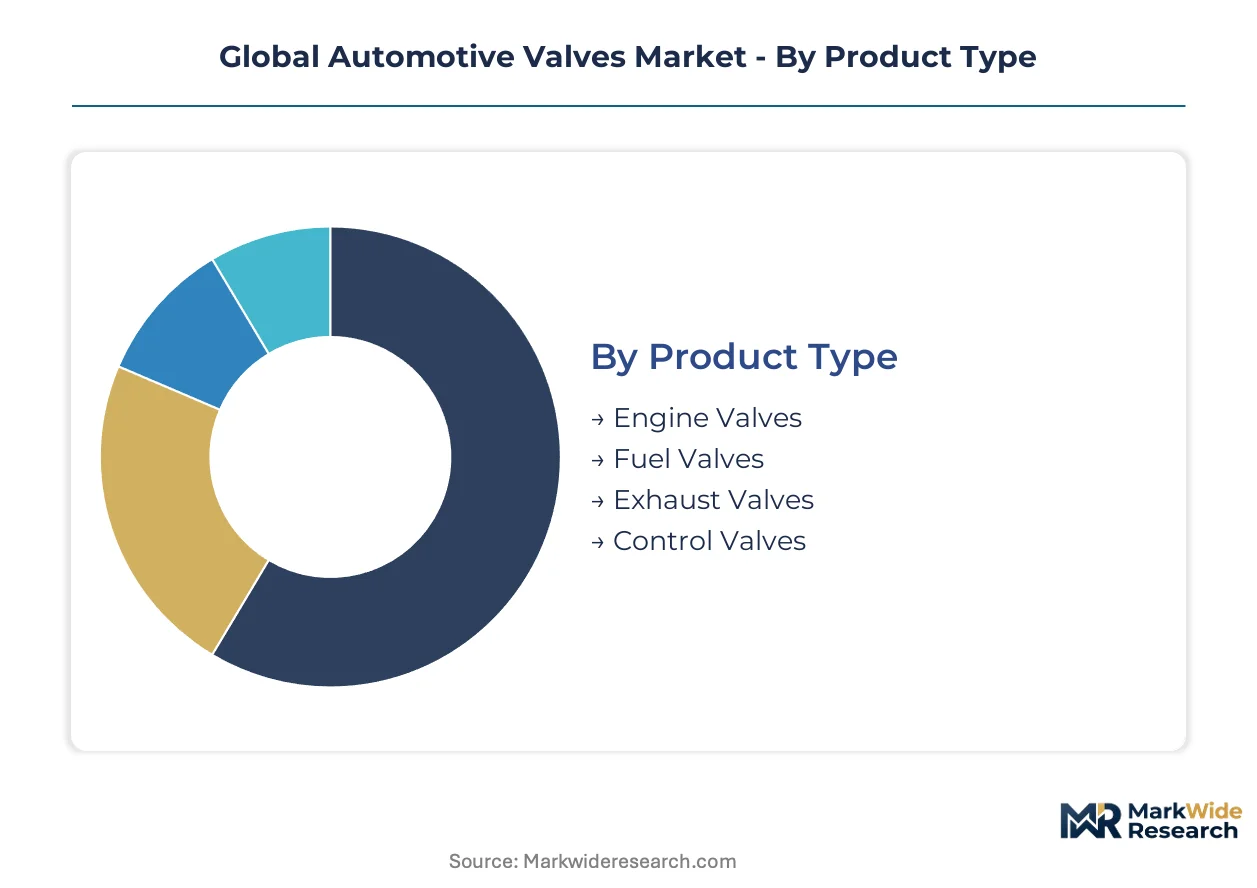
Valve segmentation determines procurement patterns across radically different service intervals. Combustion engine valves demand intensive aftermarket maintenance, while electric vehicle thermal valves require minimal replacement but command premium unit pricing.
Product Type:
After-sales-service intensity varies dramatically by valve function, with combustion-cycle components requiring scheduled replacement and thermal management valves offering extended operational lifespans.
- Engine Valves:Precision-machined poppet valves in austenitic stainless steel or titanium alloys regulate cylinder intake and exhaust. Replacement cycles concentrate in German and Japanese independent service networks as legacy fleets age beyond warranty coverage.
- Control Valves:Multi-port solenoid-actuated devices manage coolant, refrigerant, and heat-transfer fluid routing in battery thermal systems. Demand is accelerating fastest in California and Shanghai as electric vehicle production scales.
- Fuel Valves:High-pressure direct injection components with piezoelectric actuation.
- Exhaust Valves:Inconel-superalloy valves with sodium-filled stems for high-temperature durability.
Engine valves hold the largest share; momentum sits with control valves.
Material:
Cost tier differentiation separates aerospace-grade alloys from commodity metallurgy, with pricing spreads reflecting feedstock scarcity and machining complexity.
- Titanium:Ti-6Al-4V alloy intake valves reduce reciprocating mass by 40% versus steel equivalents. German OEMs specify titanium for high-revving four-cylinder architectures, though Russian sponge supply concentration creates procurement risk.
- Steel:Austenitic and martensitic grades dominate exhaust valve production. Volume concentrates in Indian and Chinese forging shops serving cost-sensitive commercial vehicle platforms.
- Aluminum:Cast and forged alloys for low-load auxiliary valve applications.
- Composite:Polymer-matrix and ceramic-reinforced materials for specialized thermal isolation.
Steel retains volume leadership; titanium is expanding most quickly.
Application:
Customer type determines specification authority, with fleet operators wielding direct procurement power in commercial segments while OEMs control passenger vehicle valve selection.
- Passenger Vehicles:Light-duty OEMs specify valve trains as integrated camshaft-valvetrain systems. Japanese and German manufacturers bundle procurement through Schaeffler and Denso for gasoline direct injection platforms.
- Electric Vehicles:Battery thermal management and cabin heat-pump circuits require entirely new valve architectures. Michigan and Bavaria engineering centers are validating coolant valves with sub-50-millisecond response specifications.
- Commercial Vehicles:Heavy-duty diesel and natural gas engines with extended service intervals.
- Racing Vehicles:Bespoke titanium and Inconel valves for motorsport homologation.
Passenger vehicles command current revenue; electric vehicles are gaining share fastest.
End User:
Supply concentration shapes margin distribution, with OEM relationships offering volume certainty and aftermarket channels delivering superior returns per unit.
- OEMs:Original equipment manufacturers specify valve systems at powertrain design freeze. Stuttgart and Detroit procurement offices bundle valve orders with camshaft and actuator contracts.
- Aftermarket Providers:Independent distributors and service chains capture replacement demand as vehicle lifespans extend. Texas-to-California logistics corridors concentrate heavy-duty valve service revenue.
- Fleet Operators:Direct procurement relationships for scheduled maintenance programs.
- Tier-1 Suppliers:System integrators purchasing valves for subassembly incorporation.
OEMs dominate unit volume; aftermarket providers offer steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. German and Japanese OEMs prioritize titanium intake valves for high-revving gasoline architectures, while Indian and Chinese production remains anchored to cost-optimized steel exhaust valves for commercial vehicle platforms.
United States
EPA Tier 3 mandates are accelerating material upgrades to Inconel and titanium alloys across Detroit powertrain engineering centers. Heavy-duty fleet operators in the Texas-to-California logistics corridor now specify valve replacement intervals independently of OEM service agreements. Michigan-based engineering centers validate coolant valves with sub-50-millisecond response specifications for emerging battery thermal management applications.
Germany
Stuttgart and Munich anchor precision valve machining capacity, concentrating OEM procurement relationships for camshaft-valvetrain system bundling. REACH restrictions on hexavalent chromium plating are forcing conversion to plasma-transferred wire arc coatings for valve stem wear resistance by 2027. Baden-Württemberg suppliers consolidate coating capacity to amortize new capital equipment across higher volumes.
Japan
METI's carbon neutrality roadmap adds certification layers for imported valve assemblies, favoring domestic thermal management valve production for hybrid platforms. Toyota City and Nagoya engineering clusters specify integrated camshaft-valvetrain systems from tier-1 suppliers. Extended vehicle lifespans redirect replacement valve demand toward independent service networks in Osaka and Tokyo metropolitan areas.
China
MIIT fuel consumption regulations mandate tighter valve leakage tolerances and faster actuation response times, forcing material upgrades across supplier tiers. Shanghai and Beijing battery thermal management circuits require multi-port coolant control valves with response times under 50 milliseconds. Yangtze River Delta manufacturing clusters scale production for domestic electric vehicle platforms and export markets simultaneously.
India
BIS automotive component standards under the PLI scheme create captive demand for domestic valve manufacturing investments. Tamil Nadu and Maharashtra forging shops serve cost-sensitive commercial vehicle platforms with austenitic and martensitic steel exhaust valves. Localization requirements are redirecting procurement relationships away from imported assemblies toward domestic precision machining capacity.
Global Automotive Valves Market Vendor Landscape
Capability concentration sits with precision-machining specialists; scale advantage sits with integrated powertrain system suppliers. The vendor base organizes into three tiers: multinational tier-1s bundling valve trains with camshaft and actuator contracts, mid-cap specialists dominating specific material grades or thermal applications, and regional fabricators serving cost-optimized commercial vehicle platforms. Dominant competitive moves include backward integration into titanium alloy feedstock sourcing and geographic expansion through joint ventures in Indian and Chinese manufacturing clusters.
Among German-based integrated suppliers, Schaeffler AG and Continental AG exemplify the camshaft-valvetrain system bundling archetype that anchors European OEM procurement. Denso Corporation represents the thermal management specialization tier, occupying a position in Japanese hybrid platform supply. Eaton Corporation sits within the North American heavy-duty fleet service tier, capturing recurring maintenance contracts through hydraulic actuator integration.
| Leading Market Players |
|---|
| Eaton Corporation |
| Schaeffler AG |
| Denso Corporation |
| BorgWarner Inc. |
| Mahle Group |
| Robert Bosch GmbH |
| Aisin Corporation |
| Valeo SA |
| Continental AG |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese titanium sponge smelters is compressing alloy feedstock premiums while simultaneously enabling aggressive pricing postures among valve manufacturers with captive material access. German precision-machining clusters leverage this input cost advantage to defend margin structures against South Asian forging competitors.
Pricing Analysis
Long-term offtake contracts dominate procurement relationships between Stuttgart OEMs and Baden-Württemberg valve suppliers, insulating premium tiers from spot-market volatility. Price differentiation rests on EPA Tier 3 certification grade and titanium alloy content per valve. Cost compression in steel exhaust valve tiers is intensifying because Indian forging shops are scaling martensitic-grade capacity. Fleet operators in North American heavy-duty segments exhibit highest price sensitivity, while German passenger vehicle OEMs prioritize performance specifications over unit cost.
Supply Chain Analysis
Export-control regimes restricting aerospace-grade titanium flows from Russian smelters are forcing valve manufacturers toward Chinese and Japanese sponge suppliers. Geographic supply concentrates in Germany, China, and Japan for precision-machined components. Raw material dependencies encompass titanium sponge, Inconel superalloy bar stock, and austenitic stainless steel billet. Single-source vulnerability in Russian titanium feedstock exposes European suppliers to alloy price spikes. Distribution runs through tier-1 system integrators bundling valves with camshaft and actuator assemblies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from thermal management valve calibration and electromechanical actuator maintenance contracts is expanding faster than hardware unit sales across electric vehicle platforms. This recurring layer justifies reorienting commercial models toward lifecycle value capture.
For Market Incumbents: Insulate premium positioning by backward integration into titanium alloy feedstock sourcing and by consolidating coating capacity to amortize REACH-compliant plasma-transferred wire arc equipment across higher volumes. Solid-state battery thermal architectures threaten coolant valve demand, making captive supply of sensor-integrated smart actuators essential for platform continuity.
For New Entrants and Emerging Players: Establish a beachhead in Indian domestic manufacturing under BIS automotive component standards and the PLI scheme localization requirements. The most penetrable white space sits in multi-port coolant control valves for Shanghai and California battery thermal management circuits. A direct procurement relationship with Yangtze River Delta electric vehicle engineering centers offers the clearest go-to-market path.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across electromechanical valve actuation development as embedded software and motor control engineering capacity becomes decisive. Five-to-ten-year viability favors mid-cap specialists with demonstrated thermal management valve qualification rather than legacy combustion-engine component portfolios. The signal to watch is OEM platform standardization announcements for battery-electric architectures, which will determine specification volumes for next-generation coolant valve categories.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Titanium Feedstock | Captive supply from Chinese sponge smelters insures against Russian export restrictions and price volatility. |
| REACH-Compliant Coating Capacity Consolidation | Baden-Württemberg suppliers amortize plasma-transferred wire arc equipment across higher valve volumes before 2027 sunset. |
| Smart Actuator R&D Investment | Embedded position sensors and motor controllers capture electromechanical valve actuation revenue pools. |
| Indian Manufacturing Joint Ventures | BIS certification and PLI scheme localization requirements create captive demand for domestic precision machining capacity. |
| Aftermarket Channel Disintermediation | Direct relationships with Texas-to-California fleet operators capture valve replacement revenue from Detroit OEM service networks. |
Methodological Framework
A spread of perspectives from OEM platform engineers, tier-1 supplier procurement leads, aftermarket distributors, and thermal management system architects converged on the working assumptions. Primary fieldwork combined with secondary validation from vehicle production databases, EPA certification filings, MIIT fuel consumption disclosures, and IHS Markit registration data. Bottom-up segmentation modeling and top-down market sizing triangulated volume and value estimates.
Demand-supply balance dynamics across propulsion architectures anchored the analytical framework over the projection horizon. Segmentation dimensions encompassed product type, material grade, vehicle class, propulsion architecture, content per vehicle, and regional production cluster. CAGRs derived from fitted growth curves applied to segment-level baseline data. Industry-specific forecast inputs included battery thermal management circuit proliferation rates and Euro 7 certification timeline delays.
Sensitivities concentrate around solid-state battery commercialization schedules, Russian titanium export policy shifts, and OEM platform standardization decisions. Forecasts reflect documented assumptions regarding electrification penetration curves and regulatory enforcement intensity. Material shifts in thermal architecture requirements or alloy feedstock availability would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Global Gas Pressure Regulator Market
Valves
Tank Hydrogen Valve Market
Valves
One-Way Valve Market
Valves
Global Marine Actuators and Valves Market
Valves
Global Valves in Oil and Gas Industry Market
Valves
Valve Remote Control System Market
Valves
China Explosion-Proof Equipment Market
Valves
Valve Sack Market
Valves
Diaphragm Valve Market
Valves
Expansion Valves Market
Valves
Middle East and Africa Machined Seals Market
Valves
Backflow Preventers Market
Valves
Cathodic Protection Market
Valves
Emergency Venting System Market
Valves
Air Jet Ejectors Market
Valves
Rising Stem Ball Valve Market