
 Gas Insulated Switchgears (GIS) Market | 2026-2036
Gas Insulated Switchgears (GIS) Market Size, Share, and Industry Trends Forecast 2026-2036
Gas Insulated Switchgears (GIS) Market Foresight
Software-defined condition monitoring is shifting how GIS vendors monetize installed base relationships. Siemens AG leverages predictive maintenance platforms to extend customer lifetime value across European utility fleets. ABB Ltd. anchors its competitive position through integrated digital twin offerings for substation operators. Hitachi Energy differentiates via AI-driven thermal diagnostics that reduce unplanned outage frequency.
Gas insulated switchgear encloses electrical conductors and switching mechanisms within sealed metal compartments pressurized with sulfur hexafluoride gas, achieving dielectric strength roughly three times that of air at equivalent pressure while reducing footprint by up to ninety percent versus air-insulated alternatives. Outdoor GIS dominates capital deployment for high-voltage transmission corridors where environmental exposure demands robust encapsulation. SF6 Gas technology still occupies the majority of installed capacity despite accelerating regulatory pressure on fluorinated greenhouse gas emissions. Renewable Energy Integration represents the fastest-growing application vector as offshore wind and solar parks require compact, weather-resistant switching infrastructure.
The European Union's F-Gas Regulation and the EPA's greenhouse gas reporting mandates in the United States are forcing manufacturers to accelerate SF6-free and reduced-emission designs. IEC 62271-203 and IEEE C37.122 standards govern type testing and operational performance, creating compliance barriers for new market entrants. Stakeholders must weigh stranded asset risk against the capital intensity of next-generation hybrid insulation platforms.
Market Dynamics
SF6 phase-down mandates are compressing product development cycles across the Gas Insulated Switchgears landscape. Manufacturers face stranded asset exposure on legacy platforms while utilities demand proven alternatives for high-voltage corridors.
Growth Catalysts
- Urban densification:Coastal Chinese megacities including Shanghai and Shenzhen deploy compact GIS to resolve acute land scarcity in substation siting.
- Offshore wind buildout:North Sea and Baltic Sea projects require weather-resistant switching infrastructure for turbine interconnection and export cabling.
- India's CEA reliability mandates:Stricter substation performance standards drive replacement of aging air-insulated infrastructure in Delhi and Mumbai metropolitan zones.
Market Restraints
- SF6 regulatory friction:The EU F-Gas Regulation imposes escalating emission quotas that constrain inventory management for installed base servicing.
- Technical limitation:Hybrid insulation platforms using fluoronitrile mixtures achieve only 70-80% of SF6 dielectric performance at equivalent pressure ratings.
- Supply concentration risk:Specialty gas purification and precision casting capacity for high-voltage enclosures clusters in German and Japanese industrial corridors.
Strategic Opportunities
- Underpenetrated geography:Vietnam's power sector expansion creates first-mover positioning for 145kV and 245kV GIS deployments in Ho Chi Minh City load centers.
- Regulatory tailwind:The US EPA greenhouse gas reporting mandate accelerates utility procurement timelines for reduced-emission switchgear in coastal transmission zones.
- Technology convergence:Digital twin platforms integrating thermal imaging and dissolved gas analysis compress fault detection intervals for substation operators.
Industry Challenges
- Skill gap in SF6-free commissioning:Field engineering expertise for fluoronitrile handling and leak detection remains concentrated among original equipment manufacturer service teams.
- Capex intensity of type testing:IEC 62271-203 short-circuit and internal arc qualification requires dedicated high-power laboratory access with multi-year booking queues.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gas Insulated Switchgears (GIS) Market |
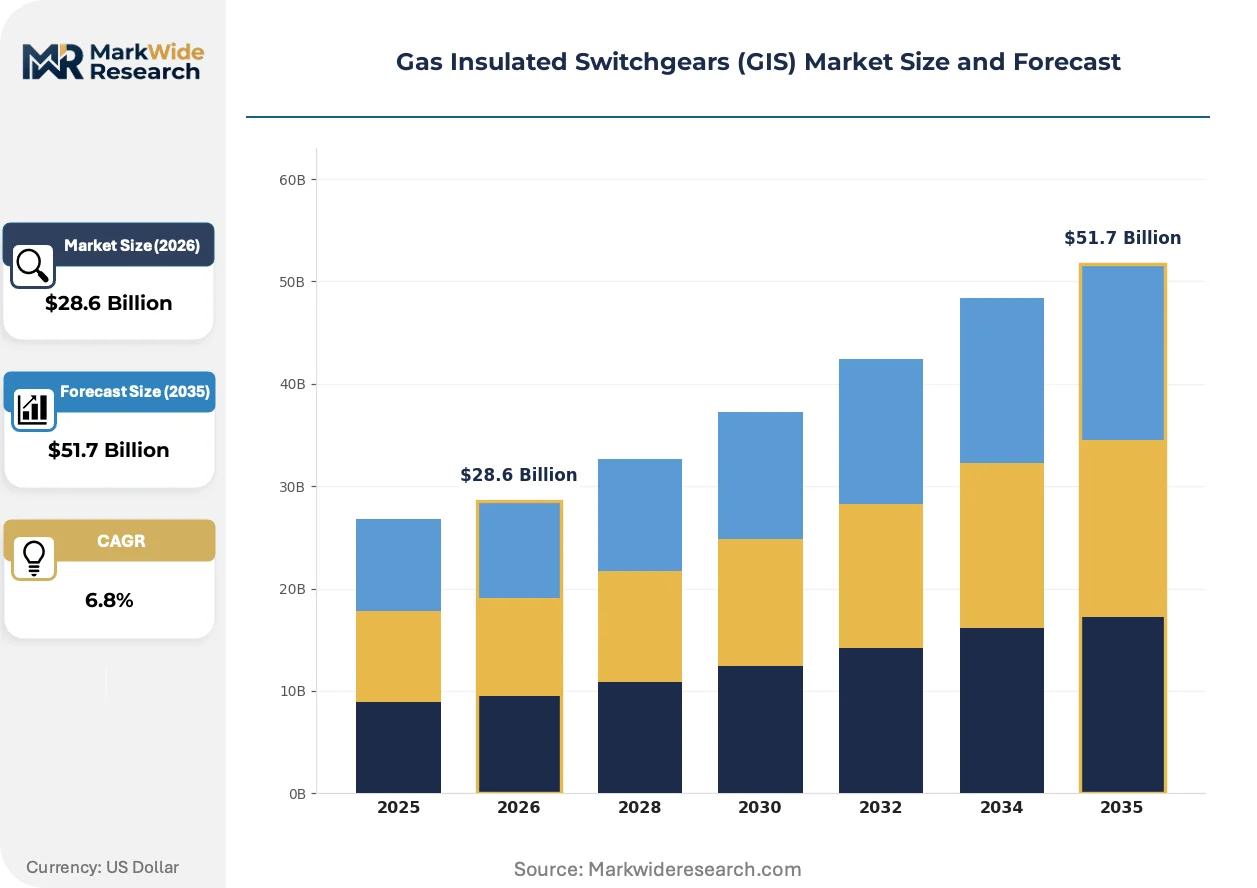
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Indoor GIS, Outdoor GIS, Metal-Enclosed GIS, Gas-Circuit Breaker GIS, Dead Tank GIS Technology: SF6 Gas, Vacuum Interruption, Air Insulation, Oil Insulation, Hybrid Insulation Application: Power Transmission, Electrical Substations, Renewable Energy Integration, Railways Electrification, Data Centers End User: Utility Providers, Electrical Contractors, Manufacturing Plants, Telecom Operators, Infrastructure Developers |
| Companies Covered | ABB Ltd., Siemens AG, General Electric, Schneider Electric, Hitachi Energy, Mitsubishi Electric, Eaton Corporation, CG Power & Industrial Solutions Ltd., CHINT Group Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gas Insulated Switchgears (GIS) Market Shifts & Advancements
Software-defined asset management is displacing scheduled maintenance paradigms across utility fleets. Predictive platforms now govern capital allocation for switchgear lifecycle extension.
AI-driven thermal diagnostics is automating fault anticipation in high-voltage GIS installations. European transmission operators deploy continuous infrared monitoring arrays across 420kV substations. The technology compresses unplanned outage frequency by enabling pre-emptive contact inspection scheduling.
The EU F-Gas Regulation tightens fluorinated gas emission quotas through 2030. Manufacturers must certify alternative insulation mixtures under accelerated IEC protocols. High-voltage product lines face compressed certification timelines as utilities defer SF6 procurement decisions pending proven hybrid platform availability.
After-sales service unbundling disrupts traditional OEM-captive maintenance relationships. Independent service providers in the US Northeast now compete for dissolved gas analysis and partial discharge monitoring contracts. This fragmentation pressures manufacturer margin structures while expanding third-party certification demand for field engineering competence.
Gas Insulated Switchgears (GIS) Market Segmentation
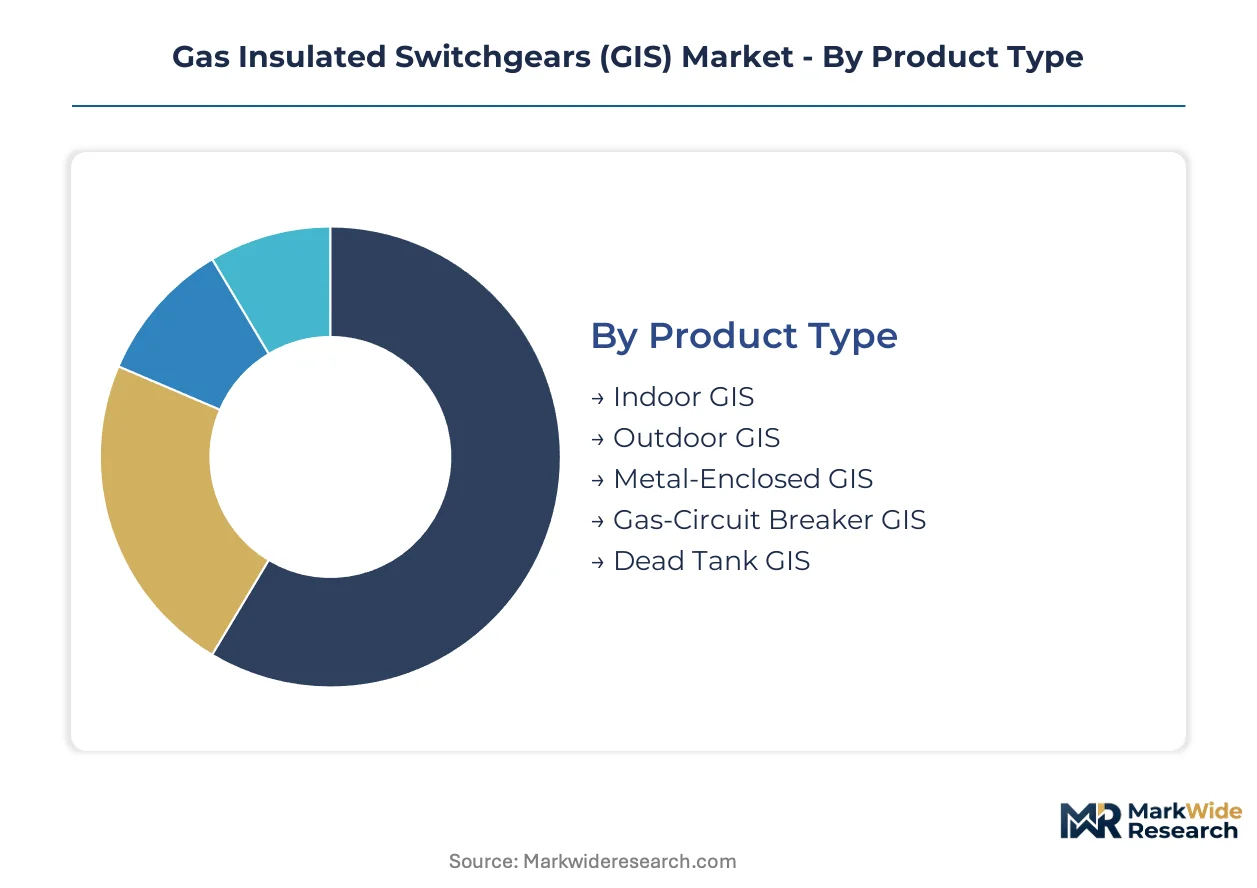
Segmentation in gas insulated switchgear reveals how capital allocation patterns diverge across voltage classes, insulation technologies, and end-use environments. Upgrade cycles and replacement timelines vary dramatically by segment, with some categories facing accelerated obsolescence from regulatory pressure while others extend service life through digital retrofit.
Product Type:
Replacement cycles for aging air-insulated infrastructure are compressing procurement timelines across product categories, with utilities weighing stranded asset risk against proven platform reliability.
- Indoor GIS:Sealed metal compartments pressurized with dielectric gas occupy minimal building footprint, achieving footprint reductions up to ninety percent versus conventional alternatives. Demand concentrates in Japanese urban substations where Tokyo Electric Power and Osaka Gas navigate severe land constraints in metropolitan load centers.
- Outdoor GIS:Robust encapsulation withstands environmental exposure across high-voltage transmission corridors. Deployment accelerates in Norwegian offshore wind export stations where Equinor and Statnett require weather-resistant switching infrastructure for North Sea interconnection hubs.
- Metal-Enclosed GIS:Compact modular designs suit indoor substation retrofits with limited civil works.
- Gas-Circuit Breaker GIS:Integrated interruption chambers reduce maintenance intervals in high-duty cycle applications.
- Dead Tank GIS:Grounded tank construction simplifies seismic certification for earthquake-prone zones.
Outdoor GIS sits at the top of the volume ranking, with Indoor GIS climbing the fastest.
Technology:
Cost tiers for insulation platforms stratify sharply, with SF6-based systems commanding premium pricing against emerging alternatives that trade performance for regulatory compliance.
- SF6 Gas:Sulfur hexafluoride delivers dielectric strength roughly three times that of air at equivalent pressure, enabling compact high-voltage designs. Procurement concentrates in German transmission corridors where TenneT and 50Hertz defer replacement decisions pending proven hybrid alternatives, constrained by EU F-Gas Regulation emission quotas.
- Hybrid Insulation:Fluoronitrile mixtures reduce greenhouse gas emissions while maintaining partial dielectric performance. Adoption accelerates in California utility procurement where Pacific Gas & Electric and Southern California Edison face EPA greenhouse gas reporting mandates for coastal transmission infrastructure.
- Vacuum Interruption:Ceramic-enclosed vacuum bottles eliminate gas handling entirely in medium-voltage applications.
- Air Insulation:Conventional designs persist in cost-sensitive retrofit projects with available land.
- Oil Insulation:Legacy installations dominate rural Indian substations awaiting CEA-mandated reliability upgrades.
SF6 Gas retains the dominant volume position, though Hybrid Insulation is expanding most quickly.
Application:
Application-driven margin structures reflect divergent technical requirements, with offshore and renewable integration commanding price premiums over conventional substation deployment.
- Renewable Energy Integration:Compact weather-resistant switching infrastructure serves offshore wind turbine interconnection and solar park export cabling. Deployment concentrates in Danish Baltic Sea projects where Ørsted and Energinet require 420kV GIS for Kriegers Flak and subsequent wind complex grid integration.
- Power Transmission:Ultra-high-voltage corridors above 300kV demand proven insulation platforms with extensive service histories. Procurement localizes in Chinese coastal megacities where State Grid Shanghai Municipal Electric Power resolves acute land scarcity through compact 500kV GIS deployment.
- Electrical Substations:Urban densification drives indoor retrofit demand across legacy metropolitan infrastructure.
- Railways Electrification:Traction power supply requires frequent switching duty with minimal maintenance access.
- Data Centers:Hyperscale facilities in Northern Virginia and Frankfurt prioritize compact indoor designs for on-site substation integration.
Power Transmission holds the volume lead, while Renewable Energy Integration shows the steepest expansion trajectory.
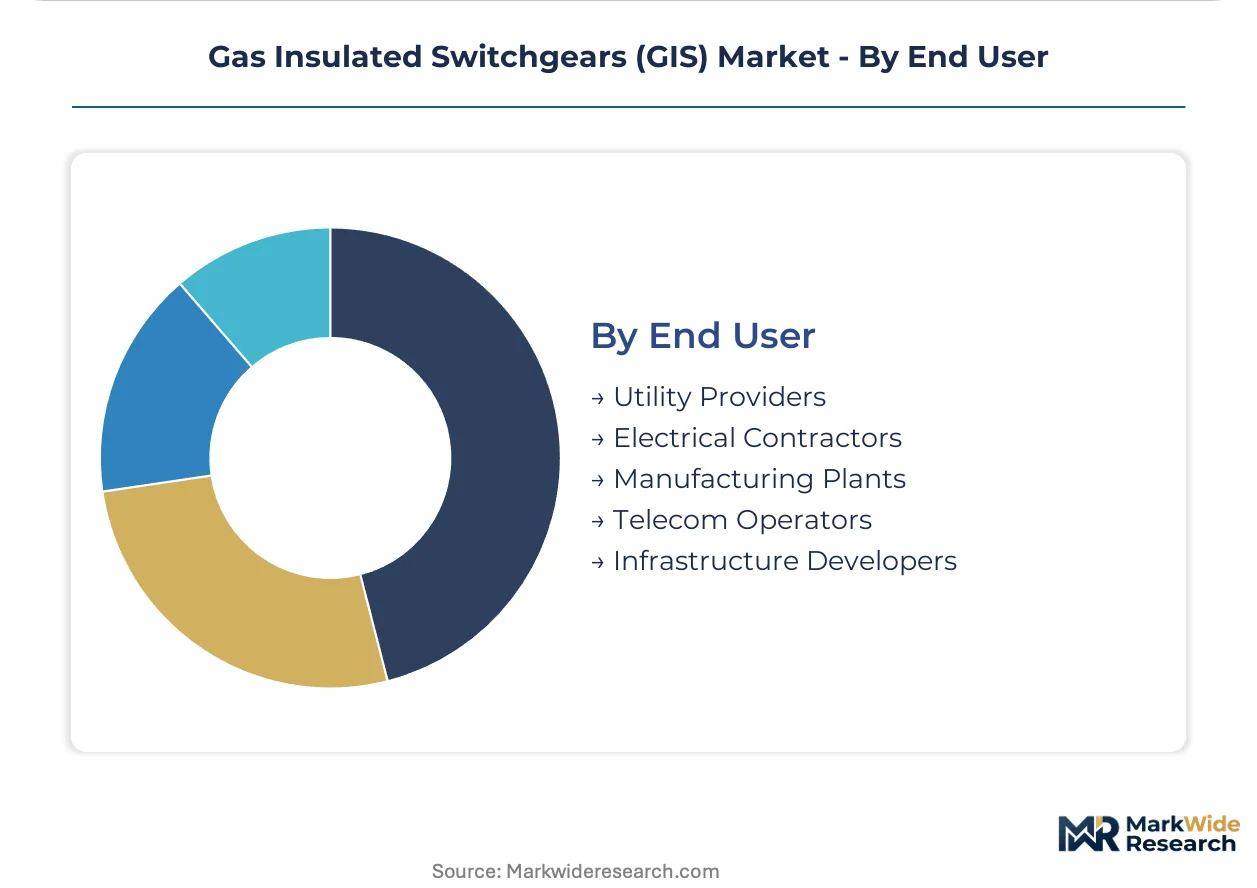
End User:
Customer-type concentration shapes service bundling strategies, with utility providers demanding lifecycle partnerships that electrical contractors and industrial users often bypass.
- Utility Providers:Integrated grid operators prioritize predictive maintenance platforms and extended warranty structures over upfront capital cost. Procurement concentrates in French transmission where RTE deploys digital twin diagnostics across 400kV substations in the Paris metropolitan ring.
- Infrastructure Developers:Greenfield project sponsors favor turnkey procurement with performance guarantees and accelerated commissioning timelines. Demand localizes in Vietnamese power sector expansion where EVN and private IPPs create first-mover positioning for 145kV GIS in Ho Chi Minh City load centers.
- Electrical Contractors:Installation-focused procurement emphasizes standardization and interoperability across multiple vendor platforms.
- Manufacturing Plants:Captive substation operators prioritize indoor compact designs for process-critical power reliability.
- Telecom Operators:Edge data center power requirements drive small-footprint indoor GIS specifications.
Utility Providers dominate volume rankings, with Infrastructure Developers gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as compliance cost gaps between jurisdictions widen. German and Japanese industrial corridors retain specialty gas purification and precision casting capacity for high-voltage enclosures. Utilities in emission-stringent markets defer procurement pending certified SF6-free alternatives.
China
State Grid Shanghai Municipal Electric Power deploys compact 500kV GIS to resolve acute land scarcity in coastal megacities. The country's dual carbon goals accelerate hybrid insulation platform development. Yangtze River Delta manufacturing clusters supply precision-cast enclosures for domestic and export markets.
Germany
TenneT and 50Hertz defer high-voltage corridor replacement decisions pending proven SF6 alternatives under tightening EU F-Gas Regulation quotas. ECHA oversight of fluorinated gas handling elevates compliance costs for installed base servicing. Bavarian industrial corridors concentrate specialty gas purification capacity for European utility fleets.
India
CEA-mandated substation reliability standards drive replacement of aging air-insulated infrastructure in Delhi and Mumbai metropolitan zones. Central Electricity Authority enforcement compresses procurement timelines for urban utilities. Maharashtra and Gujarat load centers anchor deployment growth for 145kV and 245kV systems.
United States
EPA greenhouse gas reporting mandates accelerate utility procurement timelines for reduced-emission switchgear in coastal transmission zones. Pacific Gas & Electric and Southern California Edison face disclosure requirements for SF6 inventory management. Northern Virginia data center clusters drive demand for compact indoor substation designs.
Vietnam
EVN and private IPPs create first-mover positioning for 145kV GIS deployments in Ho Chi Minh City load centers. National power sector expansion outpaces domestic manufacturing capacity. Infrastructure developers favor turnkey procurement with accelerated commissioning timelines for greenfield substation projects.
Gas Insulated Switchgears (GIS) Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated OEMs commanding premium positioning in high-voltage corridors while regional fabricators compete on cost for medium-voltage retrofits. Market structure tilts toward consolidation at the top tier where type testing barriers and certification backlogs limit new entrant viability. Three archetypes dominate: full-service multinationals with predictive maintenance platforms, mid-scale specialists in hybrid insulation technologies, and regional system integrators serving utility procurement frameworks. Competitive moves center on digital twin integration partnerships and backward integration into specialty gas supply chains.
Among European-headquartered multinationals, Siemens AG and ABB Ltd. exemplify the full-service archetype through integrated lifecycle offerings. Hitachi Energy occupies a position bridging Japanese precision manufacturing with global digital service deployment. These three represent contrasting geographic origins—German, Swiss-Swedish, and Japanese—while sharing strategic emphasis on software-defined asset management to extend customer lifetime value.
| Leading Market Players |
|---|
| ABB Ltd. |
| Siemens AG |
| General Electric |
| Schneider Electric |
| Hitachi Energy |
| Mitsubishi Electric |
| Eaton Corporation |
| CG Power & Industrial Solutions Ltd. |
| CHINT Group Co., Ltd. |
| Others |
Supply & Pricing Matrix
Specialty gas purification costs for sulfur hexafluoride and fluoronitrile mixtures cascade through three distinct pricing tiers, with German and Japanese precision casting capacity commanding premium positioning against emerging Chinese Yangtze River Delta suppliers subject to EU F-Gas Regulation compliance certification requirements.
Pricing Analysis
Distributor margins for high-voltage GIS compress as direct-to-utility procurement expands across European transmission operators. Three-tier pricing structure across premium, standard, and economy levels separates OEM-integrated digital twin platforms from standalone hardware and regional fabricator alternatives. Pricing pressure stems from hybrid insulation certification backlogs that delay premium-tier qualification. Infrastructure developers exhibit highest price sensitivity due to turnkey procurement constraints, while utility providers prioritize lifecycle value over upfront capital cost.
Supply Chain Analysis
Freight costs for precision-cast aluminum enclosures and ceramic vacuum interrupters escalate with Red Sea routing disruptions affecting European-bound shipments from Chinese manufacturing clusters. Supply concentrates in Germany, Japan, and China for high-voltage enclosure casting and specialty gas purification. Raw material dependencies span aluminum alloys, sulfur hexafluoride gas, and fluoronitrile mixtures. Single-source vulnerability characterizes IEC 62271-203 type testing laboratory access with multi-year booking queues. Distribution runs through OEM-direct channels for utility fleets and electrical contractor networks for retrofit projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Gas Insulated Switchgears Market functions as a stable compounder anchored by irreplaceable urban densification demand in coastal megacities where land scarcity mandates compact substation infrastructure.
For Market Incumbents: Cement predictive maintenance platform dominance through backward integration into dissolved gas analysis sensor supply chains. Defend against independent service provider fragmentation by captive certification of field engineering competence for SF6-free commissioning protocols. Prioritize IEC 62271-203 type testing slot reservation to compress hybrid insulation product launch timelines ahead of EU F-Gas Regulation quota tightening. For New Entrants and Emerging Players: The EPA greenhouse gas reporting mandate in the United States opens a window for reduced-emission switchgear positioning among Pacific Gas & Electric and Southern California Edison procurement frameworks. Target Vietnamese power sector expansion where EVN and private IPPs seek first-mover 145kV GIS partnerships. Pursue digital twin integration partnerships as the primary go-to-market angle to bypass OEM service bundling advantages. For Investors and Strategic Acquirers: Consolidation pressure builds where type testing barriers and certification backlogs limit new entrant viability across high-voltage corridors. Long-term viability favors full-service multinationals with predictive maintenance platforms and mid-scale hybrid insulation specialists with proven fluoronitrile handling expertise. Watch for utility deferral of SF6 procurement decisions as the inflection signal for hybrid platform market share acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Gas Supply | OEMs secure captive fluoronitrile purification capacity ahead of EU F-Gas Regulation quota constraints. |
| Digital Twin Platform Partnership | ABB Ltd. and Siemens AG extend customer lifetime value through predictive maintenance subscriptions. |
| IEC 62271-203 Type Testing Investment | Manufacturers compress certification timelines for hybrid insulation platforms under regulatory pressure. |
| Independent Service Provider Certification | Third-party dissolved gas analysis contracts fragment traditional OEM-captive maintenance relationships. |
| Geographic Manufacturing Footprint Expansion | Yangtze River Delta clusters supply precision-cast enclosures for domestic Chinese and export utility demand. |
Research Methodology
Direct dialogue with utility planning officers, EPC contractors, OEM procurement teams, and aftermarket service heads grounded the qualitative foundation for this analysis. Secondary validation drew from IEC standards documentation, EPA greenhouse gas reporting disclosures, EU F-Gas Regulation compliance databases, and customs trade records for high-voltage electrical equipment. Bottom-up unit economics triangulated against top-down utility capex allocation patterns to produce volume and value estimates.
Segment-level outputs across voltage class, insulation technology, application environment, and end-user archetype fed into the analytical framework over the projection horizon. CAGRs derived from utility replacement cycle analysis, regulatory mandate implementation timelines, and renewable energy interconnection project pipelines. Offshore wind buildout schedules and urban densification project pipelines provided industry-specific forecast anchors.
Revisions become necessary when EU F-Gas Regulation quota tightening accelerates, hybrid insulation dielectric performance thresholds advance, or type testing laboratory capacity constraints ease. Forecasts reflect documented assumptions about regulatory implementation pace and technology substitution curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Magnetic Ballast Market
Electrical Power Equipment
Alternators Market
Electrical Power Equipment
Global Electric Power Substation Automation Market
Electrical Power Equipment
North America Protective Relays Market
Electrical Power Equipment
United States Electric Space Heaters Market
Electrical Power Equipment
Asia-Pacific Air-Insulated Switchgear Market
Electrical Power Equipment
Protective Relay Market
Electrical Power Equipment
GCC Induction Motor Market
Electrical Power Equipment
Europe Brushless DC Motors Market
Electrical Power Equipment
Fuse Link Market
Electrical Power Equipment
Middle East and Africa Hazardous Location Motor Starters Market
Electrical Power Equipment
AV Power Conditioners Market
Electrical Power Equipment
Alternator Regulator Market
Electrical Power Equipment
Magneto Optic Current Transformer Market
Electrical Power Equipment
Utility Equipment Market
Electrical Power Equipment
Global Switchgear Monitoring Market