
 Pup Joint Market | 2026-2036
Pup Joint Market Size, Share, and Industry Trends Forecast 2026-2036
Pup Joint Market Analysis
Asset-light leasing models for premium OCTG inventories is fragmenting competitive dynamics in the pup joint sector. National Oilwell Varco leverages its rental fleet network to compete without full manufacturing ownership. Texas Pipe Works Inc anchors its position through captive heat-treatment capacity for high-grade alloy pup joints. TPS-Technitube Röhrenwerke GmbH specializes in European threading standards that differentiate its export catalog from API-centric rivals.
A pup joint is a short length of casing or tubing, typically manufactured to precise lengths between two and six feet, with threaded connections at both ends to extend or adjust tubular strings in oilfield operations. These components must withstand internal pressures exceeding 10,000 psi and comply with API 5CT dimensional tolerances to ensure seal integrity in sour gas environments. Standard pup joints in steel occupy the mature volume tier where margin compression is most acute, while heavy duty alloy variants command premium positioning due to HT/HP well complexity. Thermoplastic pup joints represent the emerging technology fringe with nascent adoption in corrosive offshore tiebacks where metallic fatigue limits operational life.
API 5CT standards enforced by the US Department of Transportation's PHMSA and state-level oilfield regulators in Texas and Oklahoma dictate material certification and threading inspection protocols for all downhole tubulars. The EPA's methane emissions rules indirectly shape demand by accelerating well completion schedules that consume more pup joints per pad. Buyers must monitor how BIS import substitution mandates in India and NORSOK offshore standards in Norway reshape supplier qualification requirements outside North America.
Market Dynamics
Horizontal drilling programs in the Permian Basin are consuming premium threaded pup joints at rates that outstrip conventional vertical well replacement cycles, compressing inventory turns across distributor networks.
Growth Catalysts
- API 5CT specification updates:Enhanced threading standards are mandating material traceability upgrades that favor certified suppliers with captive heat-treatment capacity.
- Shale operators:Texas and Oklahoma drilling pads are extending lateral lengths beyond 15,000 feet, multiplying pup joint consumption per completion.
- EPA methane emissions rules:Accelerated well completion schedules are reducing downtime between stages, increasing tubular turnover rates.
Market Restraints
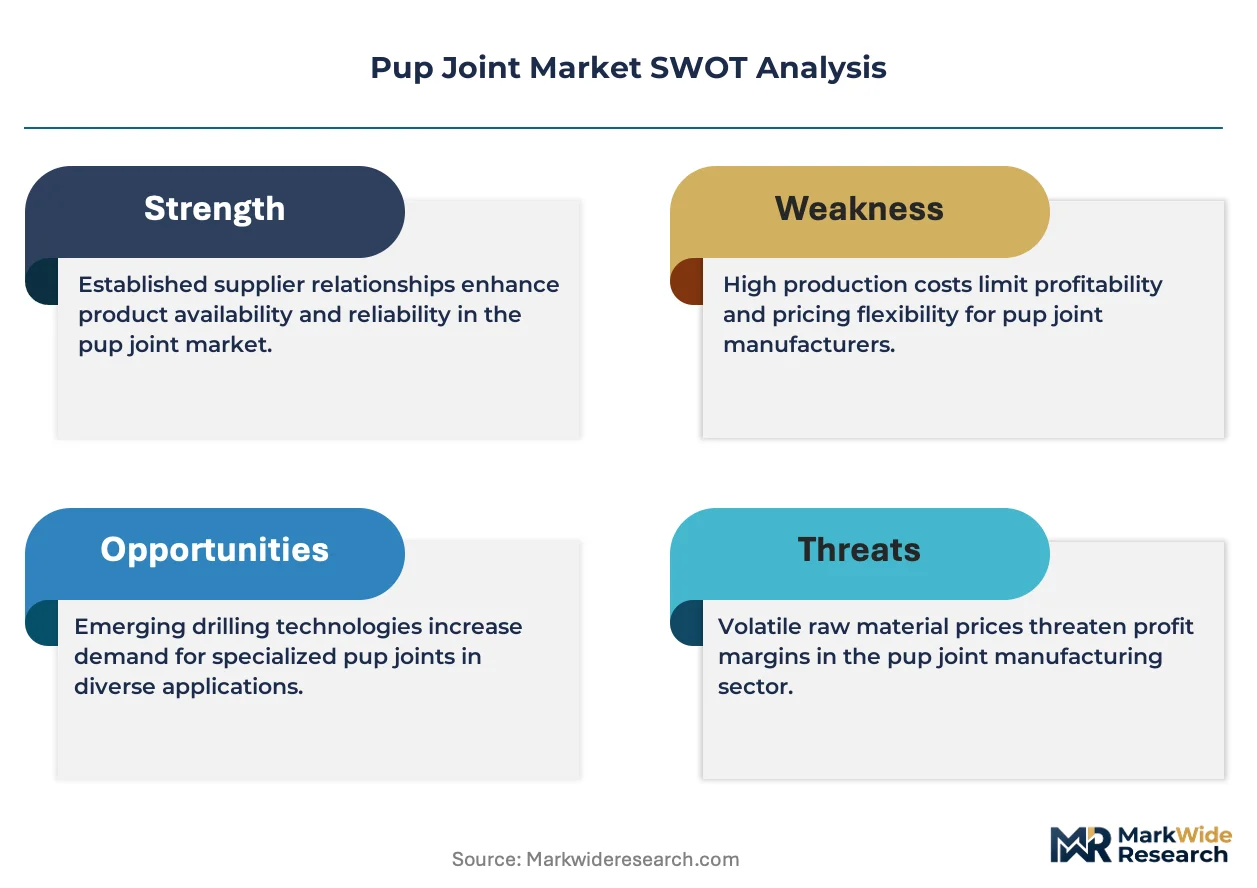
- Alloy input cost volatility:Chrome and molybdenum price swings compress margins on high-grade pup joints faster than producers can renegotiate term contracts.
- Supply concentration in Texas:Heat-treatment and threading capacity clusters within 200 miles of Houston, creating hurricane exposure and logistics bottlenecks.
- Steel substitution ceiling:Thermoplastic alternatives face pressure-rating limitations above 7,500 psi that block deployment in HP/HT zones.
Strategic Opportunities
- Offshore tieback corrosion resistance:Thermoplastic pup joints are penetrating subsea environments where metallic fatigue drives replacement frequency.
- NORSOK M-001 compliance:Norwegian offshore standards create qualification barriers that reward early certification investments with platform operator lock-in.
- Asset-light rental models:Leasing premium OCTG inventories reduces capital intensity for mid-size operators while generating recurring revenue streams.
Industry Challenges
- API threading inspector certification lag:Qualified ultrasonic evaluation technicians command wage premiums that inflate quality assurance overhead.
- Heat-treatment furnace capex cycles:Adding captive normalizing capacity requires 18-24 month lead times that mismatch drilling demand spikes.
- Legacy ERP integration:Material traceability systems must interface with decade-old field ticketing platforms that lack API 5CT data fields.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pup Joint Market |
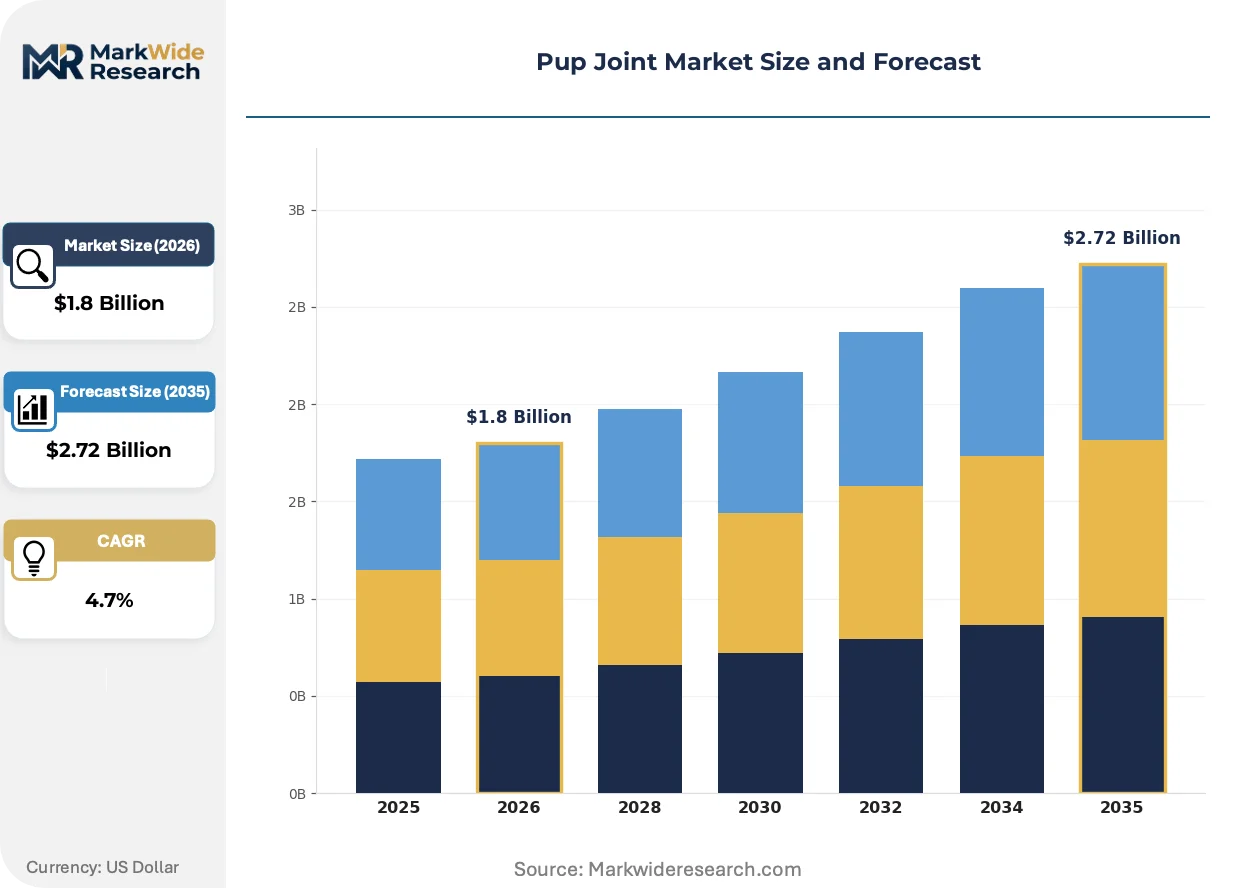
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Pup Joint, Heavy Duty Pup Joint, Swivel Pup Joint, Thermoplastic Pup Joint End User: Oil & Gas, Marine, Mining, Construction Size: 2 inch, 3 inch, 4 inch, 6 inch Material: Steel, Alloy, Composite, Others |
| Companies Covered | Anvil International, AZZ Inc, National Oilwell Varco, Forum Energy Technologies, Inc., Oil Country Tubular Limited, Sledgehammer Oil Tools Pvt. Ltd, Stewart Tubular Products, Texas Pipe Works Inc, TPS-Technitube Röhrenwerke GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pup Joint Market Emerging Trajectories
Digital threading inspection protocols and alternative material formulations are bifurcating the pup joint market between premium-certified and commodity-replacement tiers.
Ultrasonic phased-array inspection systems are virtualizing traditional magnetic particle testing workflows. Operators in the Permian Basin are adopting these systems at pad-scale deployment rates. The technology is virtualizing quality assurance labor pools by enabling remote analysis of thread integrity without on-site specialist presence.
EPA methane emissions enforcement is compressing well completion windows. Drillers in Texas and Oklahoma are pre-staging pup joint inventories closer to pads. This regulatory pressure is fragmenting procurement patterns as operators bypass distributors for direct mill relationships.
After-sales service unbundling is separating threading reconditioning from original equipment supply. Independent repair shops in Midland-Odessa are capturing refurbishment volume that mills previously retained. This channel shift concentrates in the Permian Basin where logistics costs favor local rethreading over replacement shipments.
Pup Joint Market Segmentation
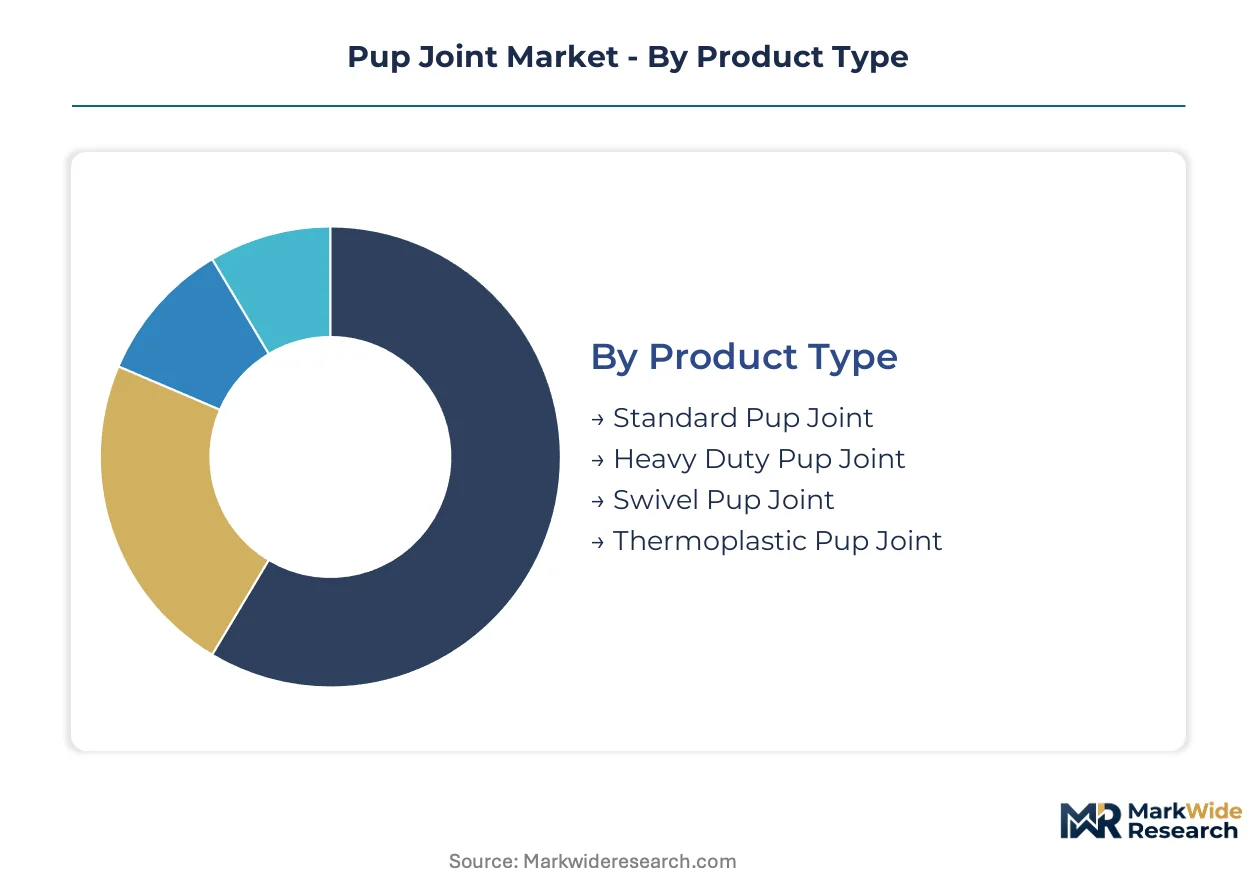
Pup joint procurement patterns diverge sharply across product grades and operational environments. Material certification requirements and pressure ratings create tiered demand structures that reshape supplier qualification hurdles.
Product Type:
Cost tier differentiation separates commodity replacement volume from premium-certified positioning in this category.
- Standard Pup Joint:Carbon steel construction meeting baseline API 5CT dimensional tolerances for vertical well programs. Demand concentrates in Oklahoma's SCOOP/STACK plays where operators prioritize inventory velocity over performance margins, though margin compression is most acute in this tier.
- Heavy Duty Pup Joint:High-grade alloy formulations with captive heat-treatment capacity for sour gas containment above 10,000 psi. Texas Permian Basin shale operators consume these at rates outpacing conventional replacement cycles as lateral lengths extend beyond 15,000 feet.
- Swivel Pup Joint:Rotational connection hardware for directional drilling assemblies requiring torque transmission through threaded interfaces.
- Thermoplastic Pup Joint:Corrosion-resistant polymer formulations penetrating offshore tiebacks where metallic fatigue limits operational life, currently blocked from HP/HT zones above 7,500 psi.
Standard pup joints command the established base. The steepest expansion runs through thermoplastic variants.
End User:
Application environment dictates material specification, threading standard, and inspection protocol intensity.
- Oil & Gas:Downhole pressure containment in drilling, completion, and production operations. EPA methane emissions rules in Texas and Oklahoma are compressing well completion windows and accelerating tubular turnover rates across shale pads.
- Marine:Subsea tieback and platform riser applications. NORSOK M-001 compliance in Norwegian offshore fields creates qualification barriers that reward early certification investments with operator lock-in.
- Mining:Slurry transport and dewatering infrastructure requiring abrasion-resistant threaded connections.
- Construction:Geotechnical drilling and foundation piling applications with lower pressure ratings than hydrocarbon extraction.
Oil & gas anchors procurement volume. Marine applications are gaining share fastest through corrosion-resistant material substitution.
Size:
Volume concentration tracks horizontal wellbore diameter standardization and completion design evolution.
- 2 inch:Coiled tubing and slim-hole interventions. Midland-Odessa repair shops capture refurbishment volume that mills previously retained for this diameter tier.
- 3 inch:Production tubing strings in marginal conventional fields.
- 4 inch:Intermediate casing programs in Permian Basin horizontal wells. Pre-staging inventories closer to drilling pads is fragmenting procurement patterns as operators bypass distributors.
- 6 inch:Surface casing and conductor pipe applications.
4 inch dimensions dominate horizontal program consumption. 2 inch sizes are climbing fastest through intervention service expansion.
Material:
Supply concentration and input cost volatility shape margin structures across metallurgical tiers.
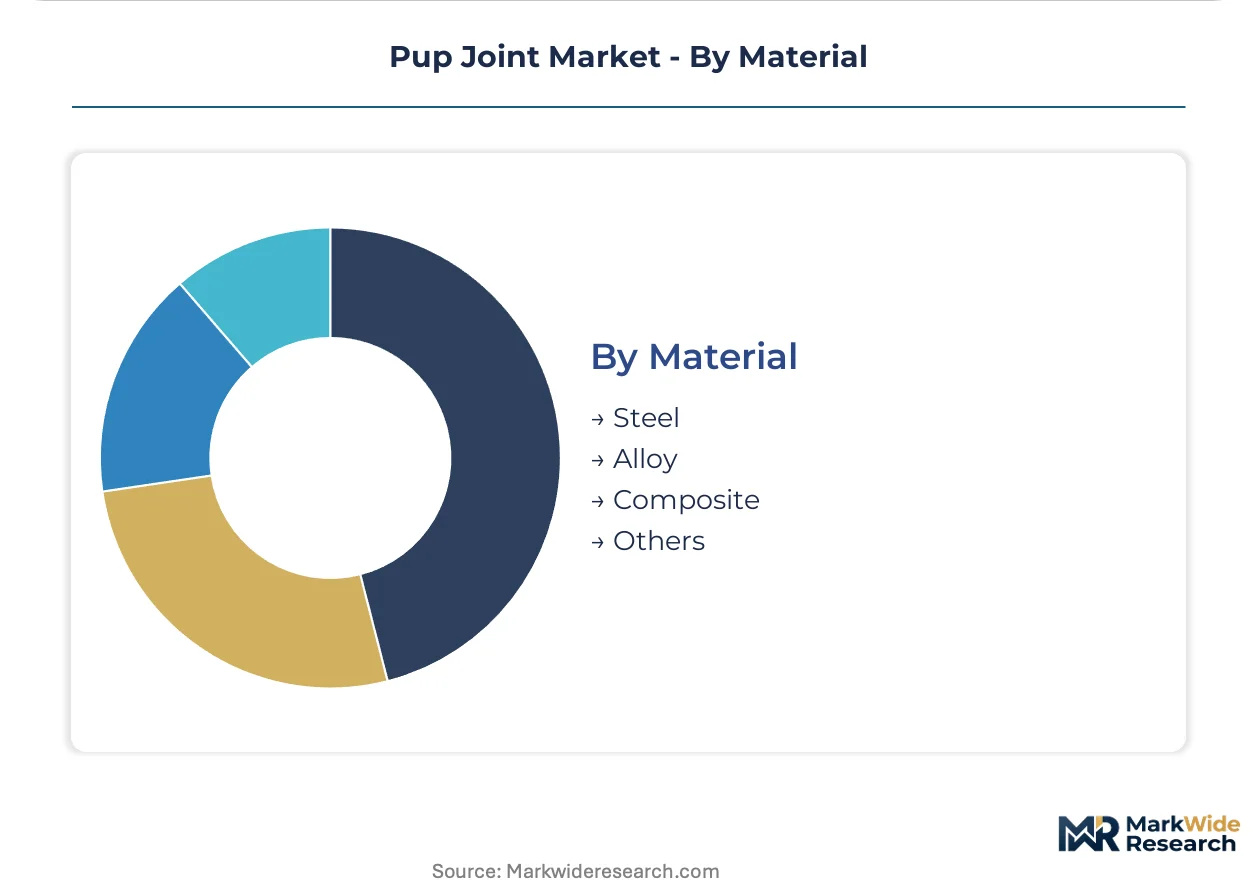
- Steel:Standard carbon grades occupying mature volume tiers where heat-treatment and threading capacity clusters within 200 miles of Houston create hurricane exposure.
- Alloy:Chrome-molybdenum formulations for sour service. Price swings in input metals compress margins faster than producers can renegotiate term contracts.
- Composite:Fiber-reinforced polymer matrices for lightweight corrosion resistance in specific offshore environments.
- Others:Specialty metallurgical blends including nickel-based superalloys for extreme temperature service.
Steel retains the volume base. Alloy grades show the steepest expansion trajectory through HP/HT well complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production-linked incentive schemes and import substitution mandates are redirecting capital flows across pup joint manufacturing clusters. National regulators are tightening material certification protocols that reshape supplier qualification requirements. Drilling intensity in shale basins and offshore frontiers is concentrating procurement decisions in specific geographic corridors.
United States
EPA methane emissions enforcement is compressing well completion schedules across Texas and Oklahoma shale pads. The Department of Transportation's PHMSA administers API 5CT compliance inspections for downhole tubulars. Heat-treatment and threading capacity clusters within 200 miles of Houston, creating hurricane exposure risks that operators mitigate through pre-staged inventory buffers.
Norway
NORSOK M-001 offshore standards are creating qualification barriers for platform operators in the North Sea. The Norwegian Petroleum Safety Authority enforces material traceability protocols that exceed baseline API requirements. Stavanger-based engineering clusters reward early certification investments with long-term operator lock-in for subsea tieback applications.
India
Bureau of Indian Standards import substitution mandates are redirecting procurement toward domestic threading and heat-treatment facilities. The Directorate General of Foreign Trade administers phased manufacturing programs for OCTG components. Gujarat-based steel fabricators are expanding captive normalizing capacity to serve upstream operators in the Mumbai High basin.
Saudi Arabia
Saudi Aramco's in-kingdom total value add program is localizing pup joint supply chains for unconventional gas developments. The Saudi Standards, Metrology and Quality Organization enforces technical regulations for oilfield tubulars. Eastern Province industrial cities near Dammam are attracting alloy processing investments to serve Jafurah shale drilling programs.
Brazil
Pre-salt layer development is consuming heavy-duty alloy pup joints for high-pressure subsea completions. ANP regulatory frameworks mandate material certification for deepwater tubulars deployed beyond 2,000 meters. Macaé service bases in Rio de Janeiro state are consolidating threading reconditioning capacity to reduce replacement logistics costs.
Pup Joint Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. Asset-light rental networks fragment competitive dynamics against captive manufacturing operators with in-house heat-treatment capacity. Three archetypes dominate: integrated OCTG distributors with logistics scale, regional threading specialists with local reconditioning presence, and alloy-focused mills with metallurgical differentiation. M&A activity concentrates on threading facility acquisitions, while capacity expansion targets captive normalizing furnaces to shorten lead times.
Among North American service companies, National Oilwell Varco exemplifies the rental-network archetype through asset-light inventory deployment. Texas Pipe Works Inc represents regional manufacturing concentration with captive heat-treatment infrastructure. TPS-Technitube Röhrenwerke GmbH occupies a position as a European threading specialist with standards differentiation from API-centric competitors.
| Leading Market Players |
|---|
| Anvil International |
| AZZ Inc |
| National Oilwell Varco |
| Forum Energy Technologies, Inc. |
| Oil Country Tubular Limited |
| Sledgehammer Oil Tools Pvt. Ltd |
| Stewart Tubular Products |
| Texas Pipe Works Inc |
| TPS-Technitube Röhrenwerke GmbH |
| Others |
Supply Flow & Price Mechanics
Heat-treatment furnace capacity concentrated within 200 miles of Houston anchors margin pools downstream at threading specialists and alloy mills with captive normalizing infrastructure. Chrome and molybdenum input cost volatility feeds directly into pricing power asymmetries between commodity carbon steel suppliers and certified sour-service providers.
Pricing Analysis
Certification level under API 5CT threading standards creates the primary spread between commodity replacement tiers and premium-qualified positioning. Three-tier pricing structure across premium-certified, standard-grade, and economy-replacement levels dominates transactional dynamics. Cost compression in carbon steel segments is intensifying because Oklahoma SCOOP/STACK operators prioritize inventory velocity over performance margins. Distributors serving Texas Permian Basin shale programs exhibit the least price sensitivity due to pre-staging requirements and accelerated completion schedules.
Supply Chain Analysis
Contract threading capacity at Midland-Odessa repair shops and Houston-area heat-treatment facilities holds the majority of North American value-add infrastructure. Raw material flows draw from domestic steel mills, specialty alloy suppliers, and polymer composite feedstock channels. Single-source vulnerability concentrates in hurricane-exposed Gulf Coast furnace clusters. Distribution runs through OCTG distributor networks, direct mill relationships, and asset-light rental fleet deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermoplastic material substitution and ultrasonic phased-array inspection protocols are disrupting established certification hierarchies. EPA methane emissions enforcement compressing well completion windows creates structural urgency for inventory positioning.
For Market Incumbents: Harden threading inspector certification pipelines against wage inflation and technician scarcity pressures. Expand captive heat-treatment capacity in geographically dispersed locations to mitigate hurricane exposure risks. Secure API 5CT material traceability system upgrades ahead of PHMSA enforcement intensification. For New Entrants and Emerging Players: Build out thermoplastic pup joint fabrication capabilities targeting Norwegian NORSOK M-001 compliance for North Sea platform operator lock-in. Penetrate offshore tieback corrosion-resistance applications where metallic fatigue drives replacement frequency. Pursue direct relationships with Permian Basin operators bypassing legacy distributor channels. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across heavy-duty alloy segments requiring captive normalizing infrastructure. Long-term viability favors suppliers with metallurgical differentiation and certification moats rather than commodity replacement volume. Target threading facility acquisitions with established API inspector networks. Watch EPA enforcement cadence and lateral length extension trends as demand inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Heat-Treatment Capacity Expansion | Reduces lead times for high-grade alloy pup joints serving Permian Basin HP/HT programs. |
| API 5CT Threading Inspector Certification Investment | Addresses qualified ultrasonic evaluation technician scarcity inflating quality assurance overhead. |
| Thermoplastic Material R&D Partnership | Unlocks subsea tieback applications beyond current 7,500 psi pressure-rating limitations. |
| NORSOK M-001 Compliance Qualification | Creates platform operator lock-in for Norwegian offshore corrosion-resistant deployments. |
| Asset-Light Rental Fleet Network Buildout | Generates recurring revenue streams while reducing capital intensity for mid-size operators. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of API specification documents, PHMSA enforcement records, and state-level oilfield regulatory filings. Drilling contractors, OCTG procurement managers, heat-treatment facility operators, threading inspection technicians, and distributor inventory planners provided structured input. Trade data from the Department of Commerce, EIA drilling activity reports, and Bureau of Labor Statistics occupational employment data supplied secondary validation. Bottom-up segment sizing triangulated against top-down energy sector capex analysis.
Forecast inputs incorporate drilling permit trajectories, lateral length evolution, and regulatory enforcement intensity across the projection horizon. Product type, end-use application, material grade, and geographic drilling cluster segmentation dimensions anchor the analytical framework. CAGRs derived from regression against historical tubular consumption patterns and forward drilling schedule projections. Alloy input cost volatility and EPA compliance timeline uncertainty represent key forecast sensitivity parameters.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by integrated steel mills or rapid thermoplastic technology breakthroughs would shift outcomes. Quarterly review of drilling permit issuance rates, heat-treatment furnace utilization indices, and API inspector certification pipeline throughput is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Vaneometer Market
Valves
Compressor Valves Market
Valves
Valve Seat Inserts Market
Valves
Aerospace Valves Market
Valves
Ball Valves Market
Valves
Rising Stem Ball Valve Market
Valves
Hybrid Valve Market
Valves
Float Traps Market
Valves
Tank Hydrogen Valve Market
Valves
Asia-Pacific Industrial Valves Market
Valves
Manual Control Valve Market
Valves
Rupture Discs Market
Valves
APAC Valves Market
Valves
Blow - Off Valves Market
Valves
Pipeline Pigging System Market
Valves
Sanitary Valves Market