
 Pneumatic Needle Valves Market | 2026-2036
Pneumatic Needle Valves Market Size, Share, and Industry Trends Forecast 2026-2036
Pneumatic Needle Valves Market Insights
The EU Green Deal is decoupling pneumatic needle valve procurement from legacy high-bleed designs across European process industries. Emerson Electric Co. leverages its vertical integration into valve actuation electronics to sustain pricing power in automatic configurations. Parker Hannifin Corporation anchors North American aftermarket channels through its distribution network of maintenance providers and OEMs. Festo competes on precision miniaturization for semiconductor tooling applications where flow control tolerances tighten.
Pneumatic needle valves are precision flow-control devices utilizing a tapered needle plunger and threaded stem to regulate gas or liquid flow through small orifices, typically achieving throttling accuracy within 0.5% of full scale. They operate on compressed air signals between 3 and 15 psi, serving primary industrial purposes in analytical instrumentation, process sampling lines, and pneumatic logic circuits where minute flow adjustments prevent system instability. Automatic product types command the widest margin pools as plant operators replace manual configurations with remotely actuated valves for unmanned facilities. Oil and Gas industry verticals absorb the largest volume share due to wellhead choke manifold requirements, though Pharmaceuticals represents the fastest-expanding demand segment as aseptic processing lines adopt single-use pneumatic manifolds. Threaded connection types dominate installed bases, yet quick connect formats are displacing legacy fittings in mobile maintenance applications where swap speed reduces turnaround time.
The EPA's New Source Performance Standards constrain fugitive emissions from pneumatic controllers, compelling valve manufacturers to certify products under ISO 15848-1 leakage class BH. REACH compliance in Europe restricts chromium plating on needle valve stems, accelerating adoption of nitride-hardened stainless steel alternatives. OSHA's Process Safety Management standard mandates documented flow control integrity in covered chemical facilities, creating recurring inspection demand that benefits maintenance providers. Stakeholders must monitor how dual carbon goals in China and the EU AI Act's industrial automation provisions reshape certification requirements for smart pneumatic networks.
Market Dynamics
The EU F-Gas Regulation is decoupling procurement from high-bleed pneumatic designs, forcing process industries toward low-emission actuation architectures that compress legacy valve margins while opening premium positions for certified low-leakage alternatives.
Growth Catalysts
- Oil and Gas Wellhead Modernization:Producers are expanding pneumatic needle valve procurement for choke manifold control systems in unmanned facilities, replacing manual configurations with remotely actuated alternatives.
- EU Green Deal Implementation:The F-Gas Regulation mandates phase-down of fluorinated greenhouse gases, compelling manufacturers to certify low-emission actuation technologies for European process industries.
- Semiconductor Tooling Precision:German automation clusters around Stuttgart and Mannheim are absorbing precision miniaturized valves for lithography and deposition equipment where flow tolerances tighten below 0.5% full scale.
Market Restraints
- Stainless Steel Input Volatility:Nitride-hardened 316L stainless steel prices fluctuate with nickel and molybdenum commodity cycles, compressing margin predictability for precision-machined needle valve stems.
- REACH Compliance Friction:Chromium plating restrictions on valve stems force rapid material transitions, straining European supply chains and extending qualification timelines for hardened surface treatments.
- Electromechanical Substitution:Piezoelectric and servo-electric actuators are capturing applications below 1-inch line size in cleanroom environments, narrowing pneumatic valve addressable market in semiconductor front-end processes.
Strategic Opportunities
- Pharmaceutical Aseptic Processing:Single-use pneumatic manifolds are penetrating biologics fill-finish lines where stainless steel cleaning validation costs drive disposable architecture adoption.
- China Dual Carbon Alignment:Provincial emissions trading schemes in Jiangsu and Zhejiang are creating procurement preference for ISO 15848-1 certified low-leakage valves in petrochemical expansions.
- Quick-Connect Distribution Innovation:Mobile maintenance channels are displacing threaded legacy fittings through rapid-swap connection formats that reduce field turnaround time in upstream oilfield services.
Industry Challenges
- Pneumatic-Electronic Integration Complexity:Plant operators struggle to integrate smart position feedback and network-enabled diagnostics into legacy compressed air infrastructures without full manifold replacement.
- ISO 15848-1 Certification Timeline:Extended third-party testing cycles for fugitive emissions classification delay product launches, compressing competitive windows for new low-leakage designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pneumatic Needle Valves Market |
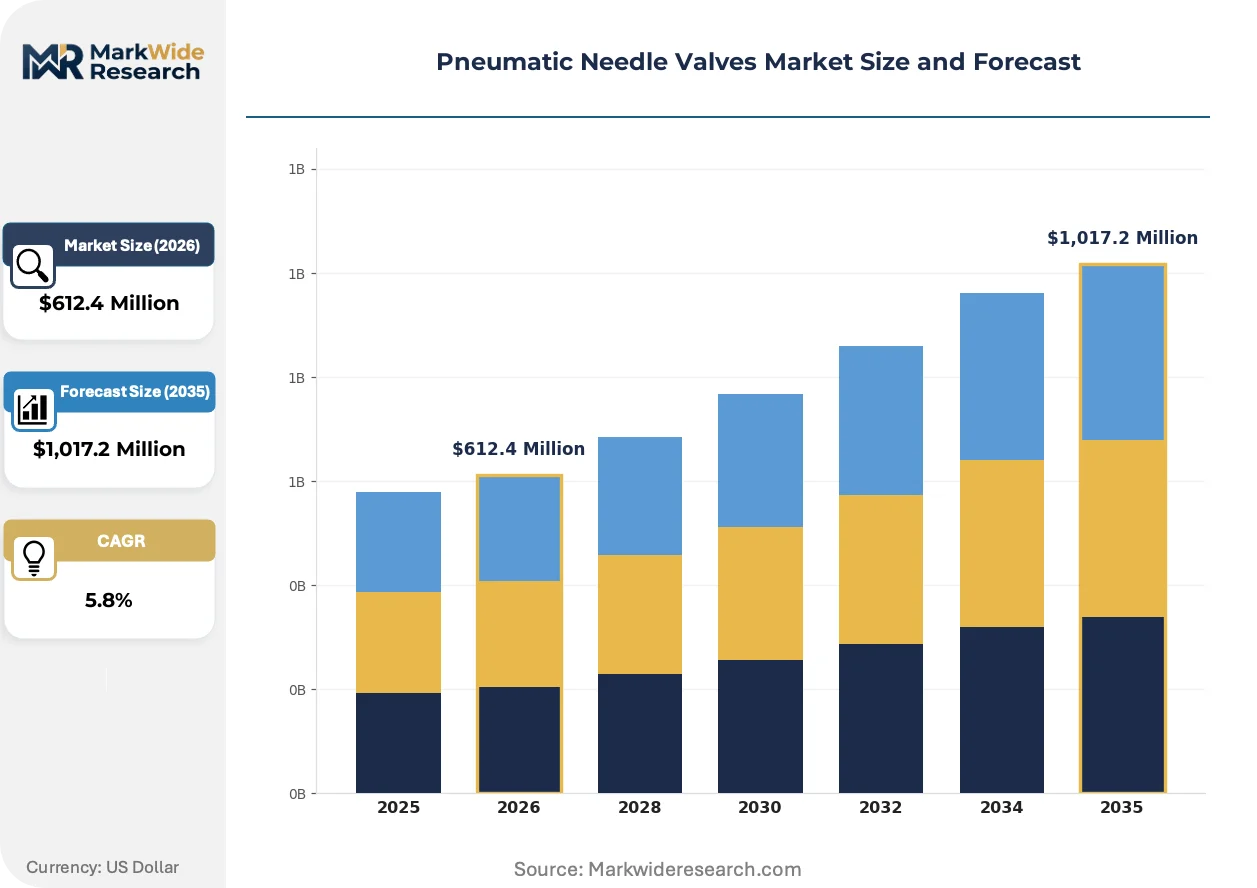
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,017.2 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Automatic, Electric, Gas Industry Vertical: Manufacturing, Oil & Gas, Aerospace, Pharmaceuticals End User: OEMs, Maintenance Providers, Construction Firms, Energy Producers Connection Type: Threaded, Flanged, Welded, Quick Connect |
| Companies Covered | Emerson Electric Co., Flowserve Corporation, IMI, Crane Company, Parker Hannifin Corporation, Festo, KSB SE & Co. KGaA, Alfa Laval, EMVAfrica, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pneumatic Needle Valves Market Trends and Innovations
Digital position sensing and network diagnostics are embedding into pneumatic valve architectures, compressing the gap between electromechanical and pneumatic intelligence while regulatory emissions frameworks reshape material and design priorities.
Smart positioners with integrated HART and IO-Link communication are consolidating distributed pneumatic networks into unified asset management platforms. Process operators in chemical and refining verticals are retrofitting these devices at accelerated pace to enable predictive maintenance without compressed air infrastructure replacement. The technology is consolidating aftermarket service margins into valve-positioner bundles that displace standalone maintenance contracts.
EPA New Source Performance Standards for pneumatic controllers are tightening fugitive emissions thresholds across US oil and gas basins. The regulation compels valve manufacturers to redesign packing sets and stem seals for sub-500 ppm methane leakage certification. Onshore shale producers in the Permian and Bakken formations are most affected, accelerating procurement of ISO 15848-1 Class BH certified alternatives ahead of enforcement phase-in.
Buyers are unbundling valve supply from installation and commissioning services, fragmenting historical OEM-captive revenue streams. Distributor networks and independent maintenance providers are capturing lifecycle service contracts through localized technical support capabilities. This pattern concentrates most visibly in North American upstream oilfield services where operator cost discipline favors component sourcing flexibility over integrated supply agreements.
Pneumatic Needle Valves Market Segmentation
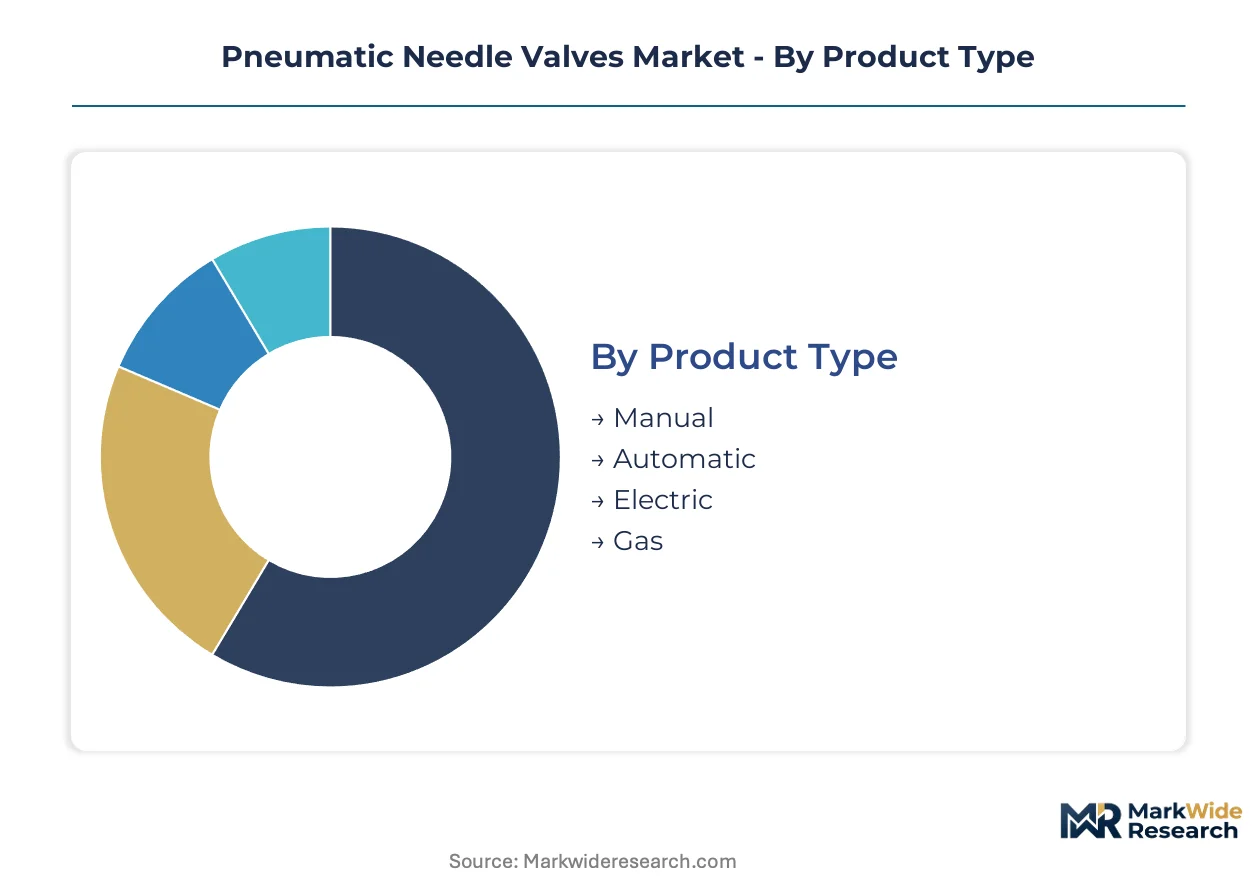
Pneumatic needle valve procurement patterns diverge sharply across product configurations and end-use environments, with certification requirements and integration complexity reshaping segment economics. Understanding these fault lines reveals where margin pools concentrate and where substitution threats loom.
Product Type:
ISO 15848-1 fugitive emissions certification burdens automatic configurations most heavily, while manual designs face lighter qualification timelines but shrinking addressable market in unmanned facilities.
- Automatic:Remote actuation via 3-15 psi pneumatic signals enables unmanned facility operation. Oil and gas producers in the Permian Basin are replacing manual choke manifold configurations, though smart positioner integration extends commissioning cycles. Automatic configurations sit at the top of the volume ranking, with Gas climbing the fastest.
- Manual:Threaded stem and tapered needle plunger deliver 0.5% full-scale throttling accuracy without external power. Maintenance providers in North American upstream oilfield services favor manual designs for swap-speed in mobile applications where network infrastructure is absent.
- Electric:Solenoid-actuated variants bridge pneumatic and electromechanical domains, requiring IEC 61508 functional safety certification in process industries. Semiconductor front-end tool builders specify electric actuation for sub-1-inch line sizes where piezoelectric alternatives compete.
- Gas:High-pressure natural gas actuation serves wellhead control systems in remote shale formations. EPA New Source Performance Standards constrain methane leakage thresholds, compelling packing set redesigns for sub-500 ppm certification.
Manual configurations retain installed base dominance in legacy facilities, though Automatic is gaining share fastest as remote operations expand.
Industry Vertical:
Cost tier stratification separates precision-intensive applications willing to absorb premium pricing from price-sensitive commodity procurement.
- Oil & Gas:Wellhead choke manifolds and production control systems absorb the largest procurement volumes. Fugitive emissions regulations from EPA and China's MEE are forcing rapid replacement of high-bleed pneumatic controllers with low-leakage alternatives.
- Pharmaceuticals:Aseptic processing lines for biologics fill-finish operations are expanding fastest. Single-use pneumatic manifolds displace stainless steel in cleaning-validation-sensitive applications, though EU GMP Annex 1 compliance extends qualification timelines.
- Manufacturing:Industrial automation clusters around Stuttgart and Mannheim deploy precision miniaturized valves for assembly line pneumatics. REACH chromium plating restrictions accelerate nitride-hardened stainless steel adoption.
- Aerospace:Flight control and fuel system applications demand MIL-STD-810 environmental qualification. Extended testing cycles and small batch requirements compress margin predictability relative to process industry volumes.
Oil & Gas commands the steepest expansion trajectory, with Pharmaceuticals expanding most quickly on single-use architecture adoption.
End User:
Customer type determines service bundling preferences and lifecycle contract structures, fragmenting historical OEM-captive revenue models.
- Maintenance Providers:Mobile field service operations prioritize quick-connect formats and rapid swap capabilities. North American upstream oilfield distributors are capturing lifecycle contracts through localized technical support.
- OEMs:Original equipment manufacturers specify integrated valve-actuator bundles for semiconductor tooling and analytical instrumentation. Backward integration into positioner electronics sustains pricing power in automatic configurations.
- Energy Producers:Unmanned facility operators demand network-enabled diagnostics and predictive maintenance capabilities without compressed air infrastructure replacement. Procurement is shifting toward component sourcing flexibility over integrated supply agreements.
- Construction Firms:Greenfield project procurement favors threaded legacy fittings in budget-constrained installations, though quick-connect penetration is rising in modular skid fabrication.
Maintenance Providers anchor aftermarket channel volume, with Energy Producers climbing fastest on unmanned facility expansion.
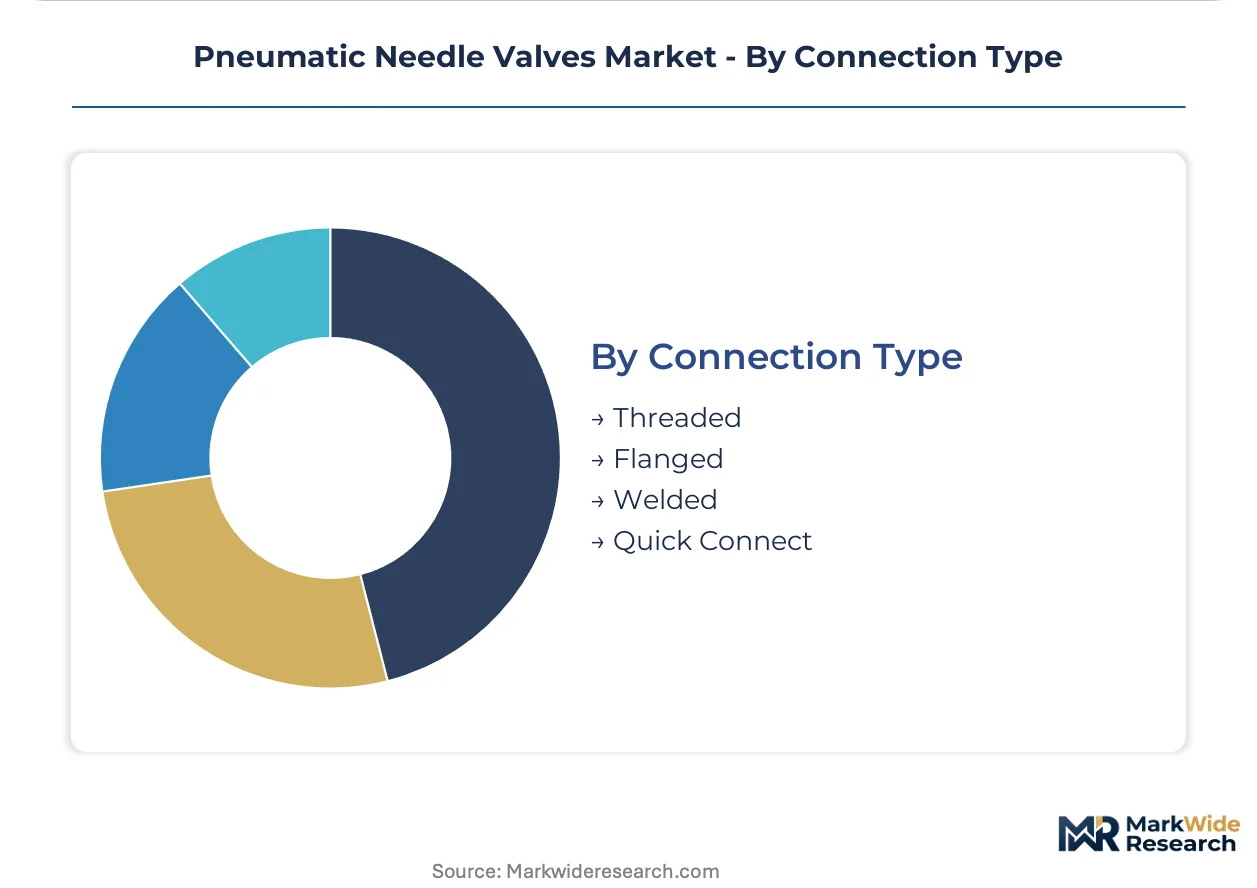
Connection Type:
Supply concentration in precision-machined fitting manufacturing shapes regional availability and field turnaround economics.
- Threaded:NPT and BSPP standards dominate installed bases across process industries. German industrial automation clusters maintain dense supplier networks for precision-machined stainless steel fittings.
- Quick Connect:Push-to-connect and camlock formats reduce field turnaround time in mobile maintenance applications. Upstream oilfield service operators in the Bakken formation are displacing legacy threaded fittings.
- Flanged:ANSI and DIN flange specifications serve high-pressure wellhead manifolds. Extended procurement lead times for forged alloy flanges compress project scheduling flexibility.
- Welded:Permanent socket weld and butt weld connections serve high-integrity applications in chemical process lines. OSHA Process Safety Management mandates drive documented weld qualification demand.
Threaded connections retain installed base dominance, with Quick Connect gaining share fastest on mobile maintenance channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered precision pneumatic instrumentation during the post-war industrial automation wave, establishing Stuttgart and Mannheim as enduring clusters for needle valve fabrication and process control engineering.
United States
Permian Basin shale operators are retrofitting wellhead choke manifolds with low-bleed pneumatic controllers ahead of EPA enforcement timelines. The EPA's New Source Performance Standards constrain methane emissions from pneumatic devices, compelling ISO 15848-1 certification. Houston anchors North American distribution networks for upstream oilfield maintenance providers.
Germany
Industrial automation OEMs around Stuttgart consume precision miniaturized valves for semiconductor lithography equipment. The EU F-Gas Regulation mandates phase-down of fluorinated greenhouse gases in process industries. Mannheim hosts dense supplier ecosystems for nitride-hardened stainless steel valve components.
China
Provincial emissions trading schemes in Jiangsu and Zhejiang are redirecting petrochemical procurement toward certified low-leakage valve architectures. The Ministry of Ecology and Environment enforces fugitive emissions standards in chemical process expansions. Shanghai's automation corridor concentrates demand for smart positioner integration in unmanned chemical facilities.
Japan
Semiconductor front-end tool builders specify sub-1-inch precision valves for deposition and etch equipment. METI industrial automation incentives support pneumatic-electronic hybrid architectures in cleanroom environments. The Chubu region around Nagoya maintains specialized fabrication capacity for ultra-high-purity gas handling components.
India
Pharmaceutical fill-finish operations in Maharashtra and Gujarat are piloting single-use pneumatic manifolds to eliminate stainless steel cleaning validation. CDSCO aseptic processing guidelines extend qualification timelines for disposable architectures. The Pune industrial belt is absorbing quick-connect valve formats for mobile biologics manufacturing skids.
Pneumatic Needle Valves Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification complexity and integration depth, with automatic configurations commanding wider spreads than manual alternatives. The vendor base stratifies into three tiers: diversified industrial conglomerates with captive actuator electronics, specialized pneumatic component houses, and regional fabrication shops serving maintenance channels. Two competitive moves dominate: backward integration into positioner electronics and rapid qualification of low-emission designs under tightening regulatory windows.
Among diversified industrial groups, Emerson Electric Co. and Parker Hannifin Corporation exemplify scale-driven positions spanning valve actuation and distribution infrastructure. Festo occupies a specialist tier focused on precision miniaturization for tooling applications. Regional fabricators including EMVAfrica anchor aftermarket channels through localized technical support capabilities rather than integrated supply agreements.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Flowserve Corporation |
| IMI |
| Crane Company |
| Parker Hannifin Corporation |
| Festo |
| KSB SE & Co. KGaA |
| Alfa Laval |
| EMVAfrica |
| Others |
Pricing and Supply Chain Analysis
EPA New Source Performance Standards for methane emissions are compelling Permian Basin operators to specify ISO 15848-1 Class BH certified valves, forcing suppliers to absorb extended third-party testing costs and compressing margins on legacy high-bleed designs while opening premium positions for qualified alternatives.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates pneumatic needle valve procurement, with ISO 15848-1 certification grade and smart positioner integration serving as primary price differentiation drivers. Cost compression in economy manual configurations is intensifying because REACH chromium plating restrictions force rapid material transitions to nitride-hardened stainless steel. Maintenance providers in North American upstream oilfield services exhibit highest price sensitivity, while semiconductor OEMs in German automation clusters absorb premium positioning for sub-0.5% precision tolerances.
Supply Chain Analysis
Workforce availability for precision machining of tapered needle plungers concentrates in Germany's Stuttgart-Mannheim corridor, China's Jiangsu-Zhejiang manufacturing belt, and Japan's Chubu region around Nagoya. Nitride-hardened 316L stainless steel, precision-machined valve seats, and HART-enabled positioner electronics constitute critical input dependencies. Single-source vulnerability looms in European nitride-hardening capacity as REACH compliance strains qualified surface treatment suppliers. Distribution runs through Houston-anchored oilfield service networks, Mannheim-centered industrial automation channels, and Shanghai's chemical process equipment corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: European F-Gas Regulation compliance costs exceed China's dual carbon alignment enforcement intensity, creating procurement preference windows for certified low-leakage valves in Jiangsu and Zhejiang petrochemical expansions relative to margin-compressed EU supply.
For Market Incumbents: To counter piezoelectric actuator substitution in semiconductor front-end processes below 1-inch line size, Emerson Electric Co. and Parker Hannifin Corporation should deepen backward integration into captive positioner electronics and accelerate ISO 15848-1 Class BH certification pipelines. Channel control through Houston-anchored maintenance provider networks sustains aftermarket revenue capture against distributor fragmentation. For New Entrants and Emerging Players: EPA New Source Performance Standards in the United States open a window for low-leakage pneumatic controller specialists to penetrate Permian Basin wellhead retrofit cycles ahead of enforcement phase-in. Quick-connect format innovation for mobile oilfield maintenance channels represents the most penetrable white-space, with localized technical support capabilities as the essential go-to-market angle against integrated OEM supply agreements. For Investors and Strategic Acquirers: Asymmetric upside sits with precision miniaturization specialists serving German semiconductor tooling clusters, where flow tolerance requirements below 0.5% full scale sustain pricing power against commodity valve fabricators. Long-term viability over the next decade hinges on pneumatic-electronic hybrid architecture capabilities for unmanned facility diagnostics. Watch for inflection when China's MEE extends fugitive emissions standards beyond Jiangsu and Zhejiang to northern petrochemical corridors.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 15848-1 Certification Acceleration | EPA enforcement timelines in Permian and Bakken formations compel sub-500 ppm methane leakage qualification. |
| Backward Integration into Positioner Electronics | Smart HART and IO-Link integration captures predictive maintenance margins in unmanned chemical facilities. |
| Quick-Connect Distribution Expansion | Mobile maintenance channels in North American upstream oilfield services displace legacy threaded fitting economics. |
| Nitride-Hardened Stainless Steel Transition | REACH chromium plating restrictions force material qualification investments across European supply chains. |
| Single-Use Manifold Development | EU GMP Annex 1 compliance requirements in pharmaceutical fill-finish lines extend disposable architecture adoption. |
Research Methodology
Multiple input streams — structured interviews with plant engineers and maintenance directors at oil and gas producers, procurement leads at semiconductor OEMs, and aftermarket service heads at industrial distributors, alongside customs data for nitride-hardened stainless steel valve components, EPA regulatory filings, and SEC 10-K disclosures from diversified industrial conglomerates — were reconciled through bottom-up volume modeling and top-down value triangulation.
Data-stream reconciliation across product type, industry vertical, end user category, and connection format dimensions produced volume and value outputs across the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macro industrial automation capex indicators, with specific weighting applied to F-Gas Regulation phase-down schedules and China's provincial emissions trading scheme expansion patterns.
Revisions become necessary when EPA enforcement timeline acceleration, REACH material restriction scope expansion, or piezoelectric actuator cost parity breakthroughs materialize beyond modeled assumptions. Material deviation in named regulatory triggers or substitution technology cost curves warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Expansion Valves Market
Valves
Valve Manifold Box (VMB) Market
Valves
Pressure Control Equipment Market
Valves
Deluge Valve Market
Valves
Global Valves Market
Valves
Choke and Kill Manifold Market
Valves
Manual Control Valve Market
Valves
Tank Hydrogen Valve Market
Valves
North America Residential Ball Valves Market
Valves
Electronic Expansion Valves Market
Valves
Air Jet Ejectors Market
Valves
Pinch Valve Market
Valves
North America Industrial Valves Market
Valves
Steel Cylinder Market
Valves
GCC and MENA Valves Market
Valves
Water Draw Off Valves Market