
 Industrial Vacuum Pumps Market | 2026-2036
Industrial Vacuum Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Vacuum Pumps Market Foresight
Specialized vacuum engineering talent is rotating toward dry pump and semiconductor-grade system design, tightening supply for conventional oil-sealed expertise. Atlas Copco leverages its compressor aftermarket network to cross-sell vacuum solutions across process industries. Busch Vacuum Solutions anchors European demand through captive service infrastructure and application engineering centers. Pfeiffer Vacuum specializes in turbo pump architectures for analytical instrumentation and research end uses.
Industrial vacuum pumps are mechanical devices that remove gas molecules from sealed volumes to create partial or high vacuum conditions, typically achieving ultimate pressures from rough vacuum through ultra-high vacuum regimes using rotary, reciprocating, or momentum transfer mechanisms. These systems serve critical functions in degassing, distillation, coating, drying, and semiconductor wafer handling where controlled atmospheric exclusion determines process yield. Liquid ring pumps dominate pulp and paper dewatering applications where tolerance for moisture-laden process streams offsets efficiency trade-offs. Dry technology leads growth in electronics manufacturing as fabs enforce hydrocarbon-free environments for sub-7nm chip production. Oil-sealed rotary vane systems retain cost advantages in general manufacturing where maintenance accessibility outweighs contamination sensitivity.
EPA NESHAP standards and EU REACH restrictions on mineral oil emissions are accelerating capital replacement cycles toward dry and hybrid pump platforms. FDA cGMP guidelines for pharmaceutical freeze-drying and semiconductor cleanroom protocols further segment product certification tiers. China's GB standards and NMPA equipment registrations add compliance layers for imported systems serving domestic drug manufacturing. Stakeholders must calibrate R&D allocation between legacy oil-sealed cost optimization and dry platform scalability as regulatory thresholds tighten across major demand centers.
Market Dynamics
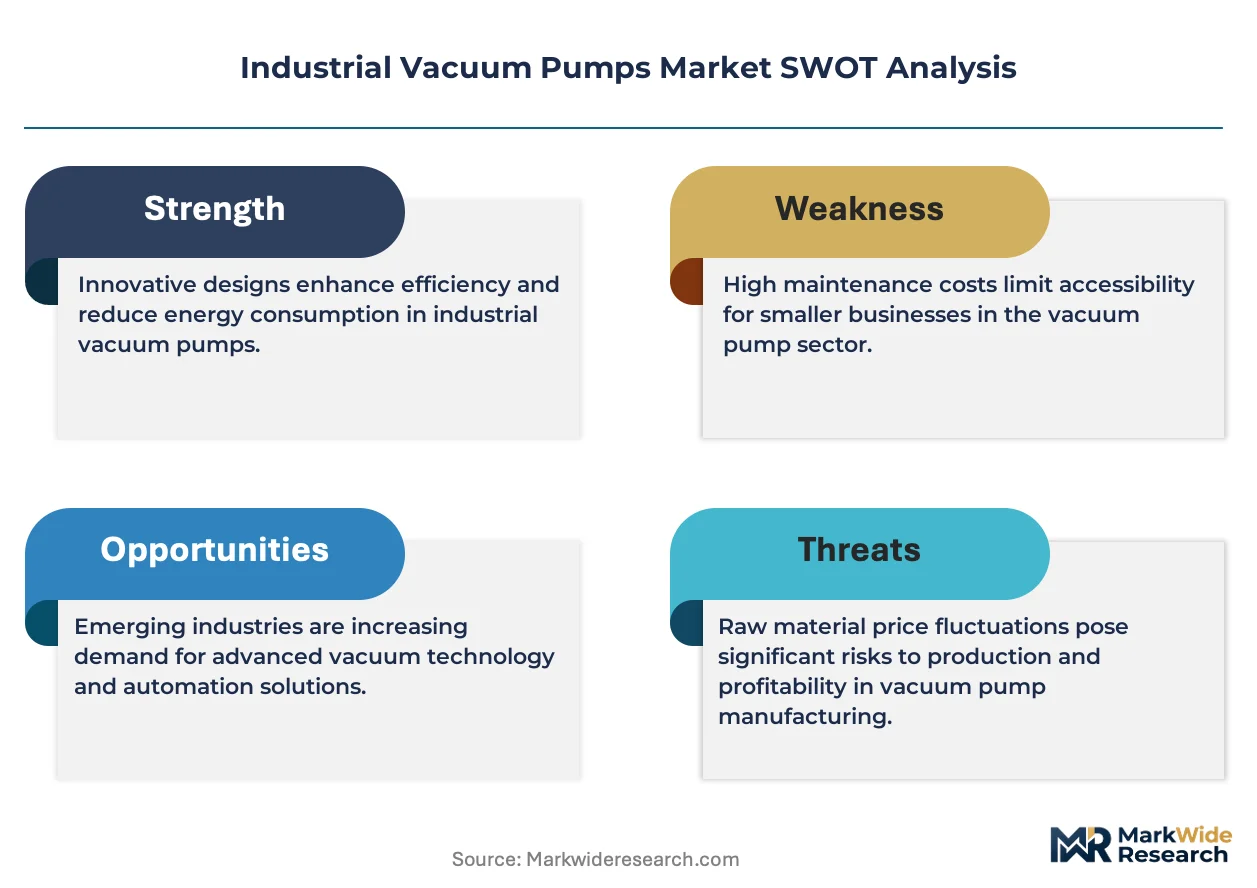
Dry pump architectures are compressing oil-sealed installed bases as semiconductor fabs enforce hydrocarbon-free wafer environments, while EPA NESHAP and EU REACH protocols accelerate capital replacement cycles across process industries.
Growth Catalysts
- Semiconductor node advancement:Taiwan and South Korea fabs are scaling vacuum pump deployments for sub-7nm production, creating sustained demand for contamination-free dry systems.
- EPA NESHAP emission limits:US mineral oil discharge restrictions are forcing chemical processors toward hybrid and dry pump platforms ahead of compliance deadlines.
- Chemical processing corridor concentration:Yangtze River Delta facilities are expanding vacuum capacity for specialty chemical and pharmaceutical manufacturing.
Market Restraints
- Rare earth magnet supply vulnerability:Permanent magnet dependencies for high-efficiency dry pumps concentrate in limited upstream sources, exposing manufacturers to input cost volatility.
- Technical performance ceiling:Dry screw and claw pumps face ultimate pressure limitations below 10⁻³ mbar that oil-sealed systems achieve routinely, restricting addressable applications.
- EU F-Gas Regulation friction:Restrictions on fluorinated sealing fluids complicate hybrid pump designs targeting medium vacuum regimes.
Strategic Opportunities
- India pharmaceutical manufacturing expansion:CDSCO equipment registration requirements for imported vacuum systems create first-mover advantages for certified dry pump suppliers.
- Service unbundling and predictive maintenance:IoT-enabled condition monitoring allows vendors to monetize aftermarket contracts separate from hardware sales.
- Hydrogen economy infrastructure:Electrolyzer and fuel cell manufacturing requires specialized vacuum drying and leak detection applications.
Industry Challenges
- Vacuum engineering talent scarcity:Specialized dry pump and semiconductor-grade system design expertise is rotating from conventional oil-sealed disciplines, tightening field service capacity.
- Multi-jurisdiction certification complexity:Simultaneous FDA cGMP, EU ATEX, and China NMPA approvals extend product launch timelines by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Vacuum Pumps Market |
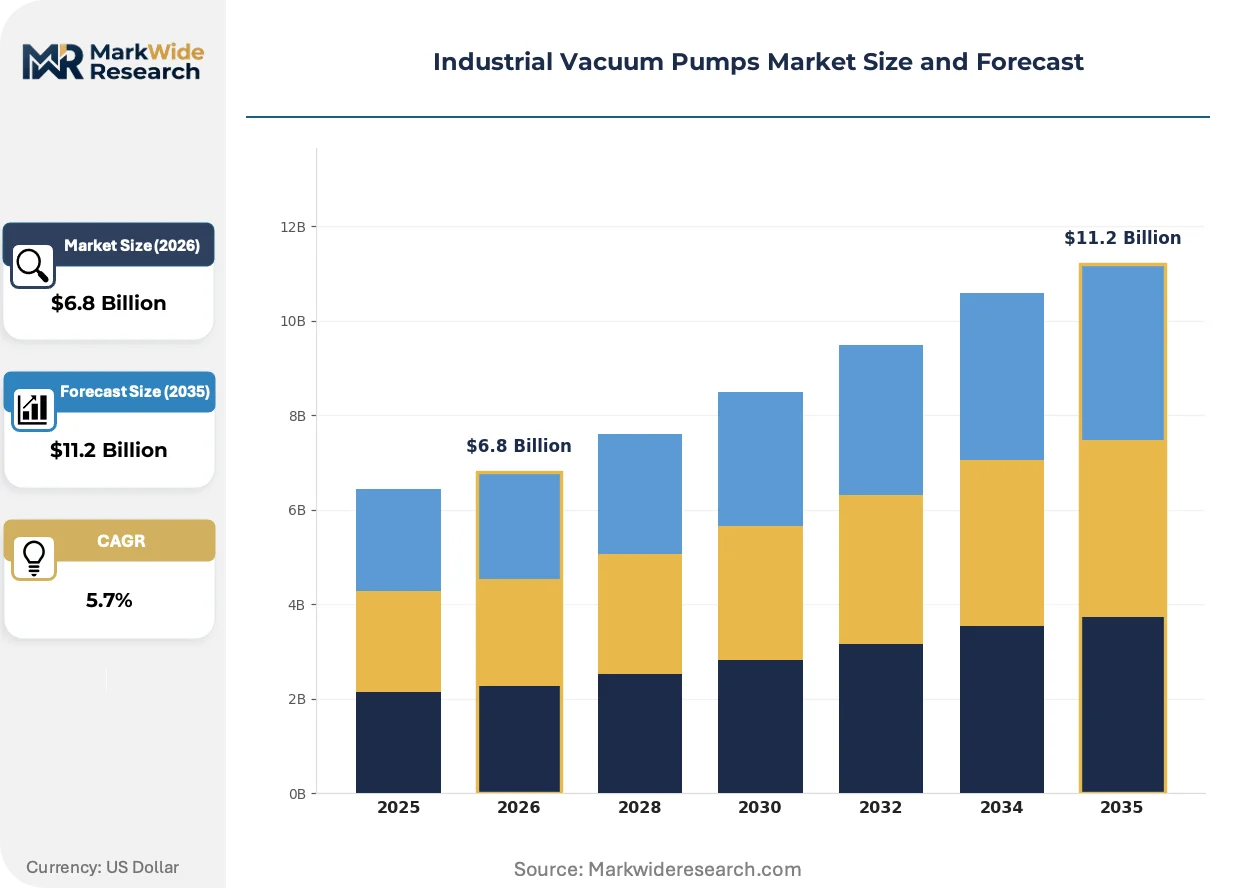
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rotary Vane, Diaphragm, Liquid Ring, Screw Application: Pulp & Paper, Food Processing, Plastics, Electronics End User: Manufacturing, Pharmaceuticals, Chemical Processing, Energy Technology: Oil-Sealed, Dry, Turbo, Hybrid |
| Companies Covered | Edwards Vacuum, Becker Pumps, Atlas Copco, Ingersoll Rand, Ebara Corporation, Busch Vacuum Solutions, ULVAC, Gardner Denver, Pfeiffer Vacuum, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Vacuum Pumps Market Shifts & Advancements
Technology trajectories in vacuum engineering are splitting between contamination-sensitive high-value applications and cost-optimized general manufacturing, with regulatory pressure acting as the primary segmentation mechanism.
Magnetic levitation turbo pump designs are fragmenting traditional bearing-dependent architectures. These systems eliminate lubrication contamination risks entirely. Semiconductor metrology and analytical instrumentation OEMs are adopting them for 24/7 operation cycles. The technology is fragmenting competitive positioning between premium dry platforms and legacy oil-sealed cost leaders.
EU REACH Annex XVII restrictions on mineral oil emissions are tightening allowable discharge thresholds for industrial vacuum systems. Chemical processors in Germany and the Netherlands face accelerated replacement schedules. Dry and hybrid pump categories are capturing specification share in project engineering documents.
Buyer consolidation among contract manufacturing organizations is compressing vendor qualification lists. Large pharmaceutical CDMOs now mandate single-source vacuum system standards across multi-site networks. This concentration is visible most acutely in North American and European drug substance manufacturing facilities.
Industrial Vacuum Pumps Market Segmentation
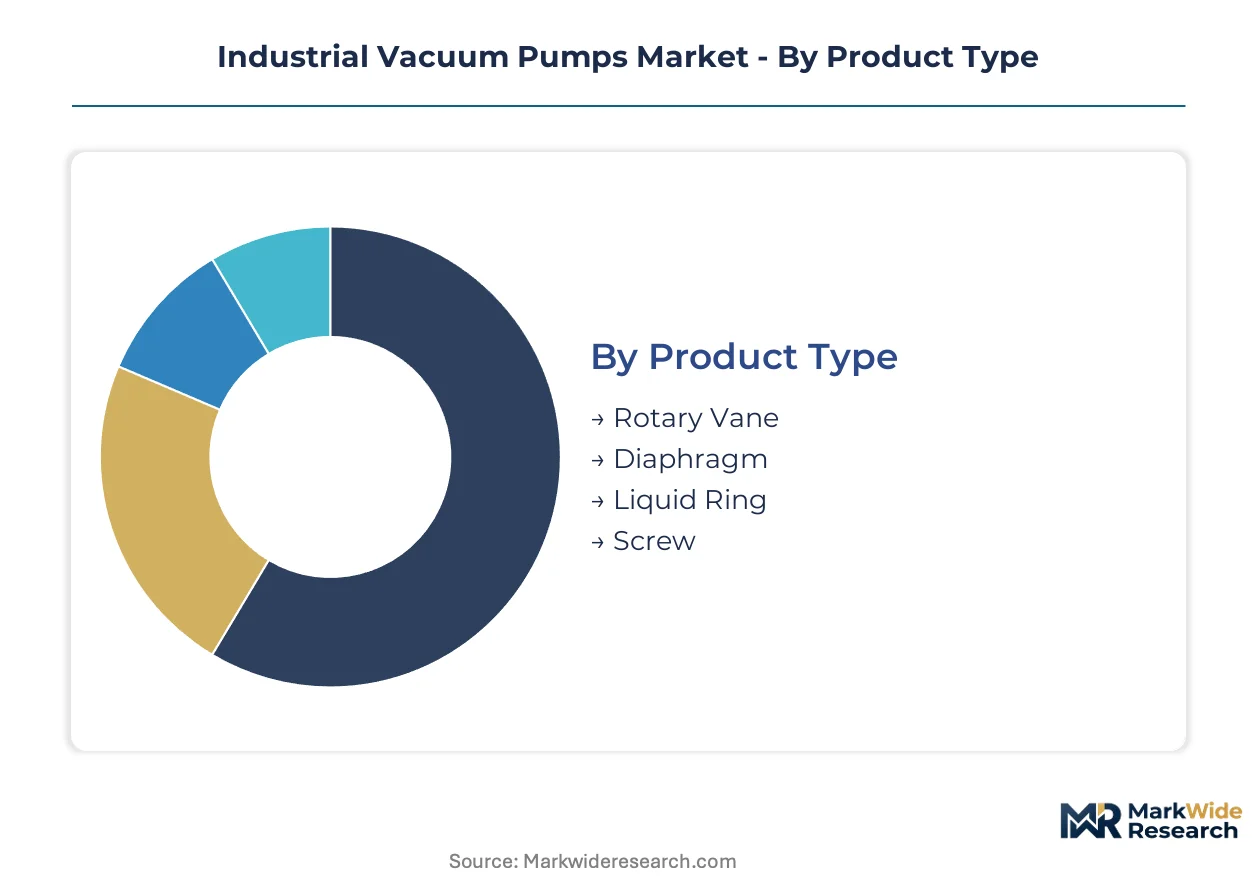
Technology substitution pressures and regulatory compliance tiers fragment procurement patterns across vacuum pump categories. End-users segment investments by contamination sensitivity, maintenance accessibility, and emission thresholds rather than upfront capital alone.
Product Type:
Oil-sealed rotary vane architectures face the steepest substitution threat from dry alternatives, while liquid ring systems defend niche positions through moisture tolerance advantages.
- Rotary Vane:Oil-sealed rotary vane pumps achieve ultimate pressures below 10⁻³ mbar through eccentric rotor-in-stator compression with mineral oil sealing and lubrication. Semiconductor fabs in Taiwan and South Korea are phasing out these systems for sub-7nm wafer production due to hydrocarbon contamination risks, though they retain cost advantages in general manufacturing maintenance cycles.
- Screw:Dry screw pumps eliminate sealing fluids entirely through intermeshing helical rotors with precision timing gears, achieving rough to medium vacuum without contamination. Yangtze River Delta chemical processors specify these for specialty chemical manufacturing under tightening EPA NESHAP and EU REACH discharge protocols.
- Diaphragm:Reciprocating elastomer diaphragm designs provide oil-free compression for laboratory and medical applications requiring absolute contamination control.
- Liquid Ring:Impeller-driven water-seal systems tolerate saturated process streams in pulp and paper dewatering where moisture-laden inlet conditions would damage dry pump internals.
Rotary vane anchors the volume base while screw configurations gain share at the steepest rate.
Application:
Electronics manufacturing commands premium pricing tiers through contamination-free requirements, while pulp and paper procurement prioritizes moisture tolerance over efficiency metrics.
- Electronics:Semiconductor wafer handling, flat panel display fabrication, and solar cell manufacturing require ultra-clean vacuum environments with zero hydrocarbon presence. Taiwan and South Korea fab expansions for advanced node production specify dry and turbo pump architectures exclusively.
- Pulp & Paper:Black liquor evaporation, stock dewatering, and felt conditioning applications tolerate liquid ring pump inefficiencies in exchange for reliable operation with saturated inlet streams.
- Food Processing:Vacuum packaging, freeze-drying, and dehydration applications balance oil-free requirements with cost constraints through hybrid pump selections.
- Plastics:Extruder degassing, thermoforming, and resin drying operations utilize rotary vane and liquid ring systems where contamination sensitivity remains moderate.
Pulp and paper anchors the volume base while electronics climbs the fastest on value terms.
End User:
Pharmaceutical procurement applies the most stringent certification requirements through FDA cGMP and EU GMP Annex 1 compliance, filtering vendor qualification lists aggressively.
- Pharmaceuticals:Freeze-drying, solvent recovery, and sterile processing operations mandate oil-free vacuum with validated cleanability. CDSCO equipment registrations in India and China NMPA approvals extend product launch timelines for imported systems.
- Chemical Processing:Distillation, reaction control, and solvent recovery across the Yangtze River Delta corridor face accelerated replacement cycles under EPA NESHAP mineral oil discharge limits.
- Manufacturing:General industrial degassing, clamping, and material handling applications retain cost-optimized rotary vane selections where maintenance accessibility outweighs contamination concerns.
- Energy:Transformer drying, geothermal gas extraction, and emerging hydrogen electrolyzer manufacturing require specialized vacuum drying and leak detection capabilities.
Manufacturing anchors the volume base while pharmaceuticals expands most quickly on specification intensity.
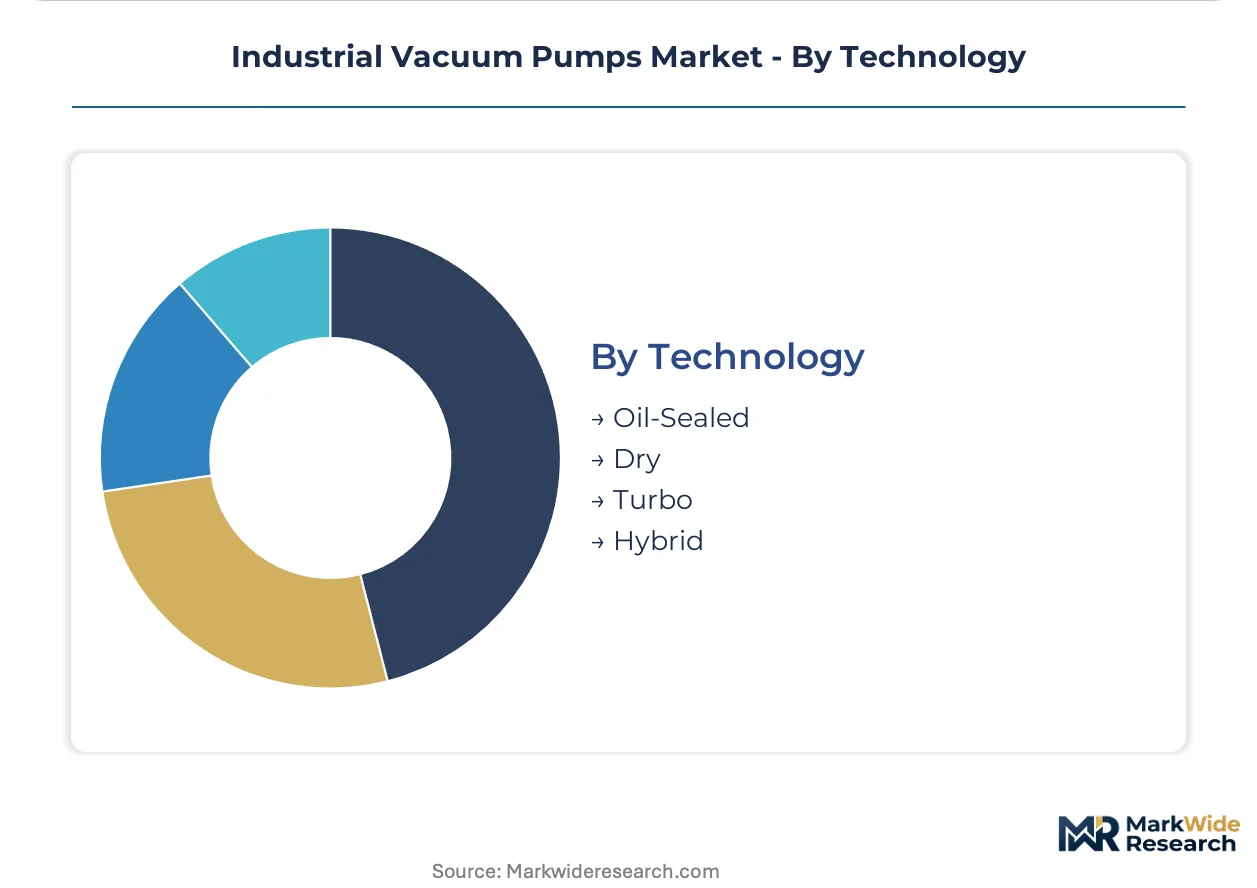
Technology:
Regulatory emission thresholds are compressing oil-sealed installed bases toward dry and hybrid architectures, with turbo systems capturing ultra-high vacuum niches.
- Dry:Screw, claw, and scroll mechanisms eliminate sealing fluids entirely through precision mechanical compression. EU REACH Annex XVII restrictions on mineral oil emissions accelerate specification share capture in German and Dutch chemical project engineering.
- Oil-Sealed:Rotary vane and piston designs retain installed base dominance in general manufacturing where EPA NESHAP compliance deadlines have not yet triggered replacement mandates.
- Turbo:Molecular drag and turbomolecular pumps achieve ultra-high vacuum through high-speed rotor momentum transfer, serving analytical instrumentation and research applications.
- Hybrid:Combined dry backing and turbo or diffusion stages bridge medium vacuum regimes, though EU F-Gas Regulation restrictions on fluorinated sealing fluids complicate design choices.
Oil-sealed technology anchors the volume base while dry platforms gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial vacuum pump consumption patterns diverge sharply by geography: semiconductor fabs in Taiwan and South Korea demand hydrocarbon-free dry systems, while chemical processors in Germany and the Netherlands face accelerated replacement cycles under EU REACH mineral oil restrictions.
United States
EPA NESHAP emission limits on mineral oil discharge are forcing chemical processors toward hybrid and dry pump platforms ahead of compliance deadlines. The Gulf Coast petrochemical corridor and Midwest manufacturing belt concentrate replacement demand. Houston-area refineries and specialty chemical facilities are retrofitting vacuum systems to meet tightened discharge thresholds.
Germany
EU REACH Annex XVII restrictions on mineral oil emissions are compressing oil-sealed installed bases toward dry architectures. The country's analytical instrumentation and pharmaceutical manufacturing sectors sustain premium turbo pump demand. Baden-Württemberg and North Rhine-Westphalia host the densest concentrations of chemical processing and automotive component manufacturing requiring vacuum capacity.
China
Yangtze River Delta facilities are expanding vacuum capacity for specialty chemical and pharmaceutical manufacturing under tightening GB standards. NMPA equipment registrations add compliance layers for imported systems serving domestic drug manufacturing. Shanghai and Jiangsu province clusters dominate procurement for electronics and chemical processing applications.
South Korea
Semiconductor fabs are scaling vacuum pump deployments for sub-7nm production, creating sustained demand for contamination-free dry systems. The country's national semiconductor regulator coordinates equipment certification with fab expansion timelines. The Gyeonggi-Seoul corridor anchors advanced node manufacturing with strict hydrocarbon-free environment protocols.
India
CDSCO equipment registration requirements for imported vacuum systems create first-mover advantages for certified dry pump suppliers in pharmaceutical manufacturing expansion. Maharashtra and Gujarat states concentrate chemical processing and active pharmaceutical ingredient production. Mumbai-Pune and Ahmedabad-Vadodara industrial belts are upgrading vacuum infrastructure for export-compliant drug manufacturing.
Industrial Vacuum Pumps Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with cross-border compressor and vacuum technology conglomerates leveraging aftermarket networks against focused vacuum engineering houses. The market structure rewards captive service infrastructure and application engineering depth over pure manufacturing scale. Two strategic archetypes dominate: diversified industrial equipment conglomerates with compressor-vacuum cross-selling capabilities, and pure-play vacuum specialists with semiconductor-grade certification depth. Competitive moves concentrate on geographic expansion through application engineering centers and technology licensing for dry pump architectures.
Among diversified industrial equipment conglomerates, Atlas Copco and Ingersoll Rand occupy positions leveraging compressor aftermarket networks to cross-sell vacuum solutions across process industries. Within the vacuum specialist tier, Pfeiffer Vacuum exemplifies turbo pump architecture focus for analytical instrumentation and research end uses, while Busch Vacuum Solutions anchors European demand through captive service infrastructure. Edwards Vacuum represents the semiconductor-grade system design archetype with dry pump technology leadership for contamination-sensitive fab environments.
| Leading Market Players |
|---|
| Edwards Vacuum |
| Becker Pumps |
| Atlas Copco |
| Ingersoll Rand |
| Ebara Corporation |
| Busch Vacuum Solutions |
| ULVAC |
| Gardner Denver |
| Pfeiffer Vacuum |
| Others |
Supply & Pricing Matrix
Capacity utilization at German and Japanese precision manufacturing clusters shapes both supply concentration and price floors for dry pump architectures. Scale economies in permanent magnet sourcing and precision machining concentrate bargaining power among integrated conglomerates, while EPA NESHAP compliance deadlines compress margin buffers for oil-sealed system suppliers.
Pricing Analysis
Contract-based long-term offtake agreements dominate semiconductor fab procurement, with project-based pricing capturing chemical processing and general manufacturing segments. Price differentiation rests on certification grade—FDA cGMP and EU ATEX tiers command substantial premiums over standard industrial specifications—and volume scale, with multi-site pharmaceutical CDMOs extracting favorable terms through consolidated purchasing. Cost compression in mid-range dry screw configurations is intensifying because rare earth magnet input volatility and precision manufacturing bottlenecks squeeze converter margins. General manufacturing buyers exhibit highest price sensitivity, prioritizing maintenance accessibility and upfront capital over lifecycle cost, while semiconductor fabs show least sensitivity due to contamination-free requirements.
Supply Chain Analysis
Inventory buffers for precision-machined rotors and rare earth magnet assemblies extend lead times for high-performance dry pump configurations, compressing responsiveness to demand spikes. Manufacturing concentration centers on Germany, Japan, and China, with precision machining capabilities for semiconductor-grade systems anchored in Baden-Württemberg and Tokyo-Osaka corridors. Raw material dependencies draw from neodymium-iron-boron magnet supply chains concentrated in limited upstream sources, precision cast iron and specialty alloys from European and Japanese foundries, and high-performance coatings from German chemical suppliers. Single-source vulnerability in permanent magnet feedstock exposes manufacturers to input cost volatility and geopolitical friction. Distribution runs through captive service infrastructure for premium tiers and authorized distributor networks for standard industrial applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive maintenance contracts and IoT-enabled condition monitoring are expanding faster than hardware sales, converting capital equipment relationships into recurring revenue streams. This service-attach opportunity rewards vendors with installed base visibility and application engineering depth.
For Market Incumbents: Secure semiconductor-grade certification depth against emerging Asian competitors by accelerating EU ATEX and China NMPA approval timelines. Lock in rare earth magnet supply through backward integration or long-term offtake agreements with Japanese and Australian mining consortiums. Expand captive service infrastructure in the Yangtze River Delta to defend share against local challengers.
For New Entrants and Emerging Players: Predictive maintenance analytics for legacy oil-sealed installed bases represents the most penetrable service-layer gap, as incumbents prioritize dry pump R&D over aftermarket digitization. Target India's pharmaceutical manufacturing expansion by front-running CDSCO equipment registration requirements ahead of Maharashtra and Gujarat facility upgrades. Partner with regional compressor distributors to leverage existing plant maintenance relationships for vacuum system cross-selling.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among pure-play vacuum specialists with semiconductor-grade certification depth and captive service infrastructure spanning German and Asian manufacturing corridors. Long-term viability over the next decade hinges on regulatory tailwinds accelerating oil-sealed displacement and hydrogen economy infrastructure buildout. Acquisition targets should demonstrate dry pump architecture scalability and established fab qualification relationships. Monitor EU F-Gas Regulation amendments as an inflection indicator for hybrid pump design viability and stranded asset risk in fluorinated sealing fluid dependencies.
| Strategic Initiative | Industry Significance |
|---|---|
| Service Infrastructure Expansion | Captive maintenance networks in Taiwan and South Korea defend semiconductor fab relationships against price competition. |
| Regulatory Certification Investment | Simultaneous FDA cGMP and China NMPA approvals compress product launch timelines for pharmaceutical vacuum systems. |
| Rare Earth Supply Securement | Long-term magnet offtake agreements with Australian and Japanese sources mitigate input cost volatility for dry pump manufacturing. |
| Predictive Maintenance Platform Launch | IoT-enabled condition monitoring converts hardware sales into recurring aftermarket contracts across chemical processing installations. |
| Hydrogen Economy Application Development | Electrolyzer and fuel cell manufacturing requirements open specialized vacuum drying and leak detection market segments. |
Research Methodology
Initial hypotheses were tested against primary input from plant engineers at semiconductor fabs and chemical processing facilities, aftermarket service heads at vacuum system OEMs, and procurement leads at pharmaceutical CDMOs, and refined through secondary validation against SEC 10-K filings, EU ECHA regulatory databases, and customs trade data for vacuum pump imports. Bottom-up demand modeling across technology segments, application verticals, and regional manufacturing clusters was triangulated against top-down macroeconomic indicators and industry association reports.
Variance decomposition across the projection horizon isolates technology substitution effects, regulatory compliance deadlines, and geographic demand shifts as primary forecast drivers. Segmentation dimensions modeled include pump technology type, contamination sensitivity tier, end-use industry vertical, and regional regulatory cluster. CAGRs were derived from fitted growth curves calibrated to historical replacement cycle data and announced fab expansion timelines. Industry-specific inputs incorporate semiconductor node advancement roadmaps and EPA NESHAP compliance phase-in schedules.
Forecasts assume regulatory continuity in EPA emission protocols and EU REACH restrictions; material policy shifts would require re-modeling of capital replacement cycle assumptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Lubrication Pump Systems Market
Pumps and Control Devices
Cryogenic Pump Market
Pumps and Control Devices
Grease Pump Market
Pumps and Control Devices
Magnetic Drive Pumps Market
Pumps and Control Devices
Electric Submersible Pump Market
Pumps and Control Devices
In Pipe Hydro Systems Market
Pumps and Control Devices
Europe Subsea Pumps Market
Pumps and Control Devices
Mud Pumps Market
Pumps and Control Devices
Asia Pacific Side Channel Pumps Market
Pumps and Control Devices
High Power Air Pump Market
Pumps and Control Devices
Asia Pacific Submersible Pump Market
Pumps and Control Devices
India Industrial Pump Market
Pumps and Control Devices
Global Piston Pumps Market
Pumps and Control Devices
Industrial Pumps Market
Pumps and Control Devices
Global Mobile Hydraulic Pump Market
Pumps and Control Devices
Pumps and Trigger Spray Market