
 Steam Trap Valve Market | 2026-2036
Steam Trap Valve Market Size, Share, and Industry Trends Forecast 2026-2036
Steam Trap Valve Market Outlook
Aftermarket service revenue is reshaping margin distribution across the Steam Trap Valve industry. Spirax-Sarco Engineering leverages its global service network to capture recurring calibration and replacement cycles. Emerson Electric Co. anchors its position through instrumentation integration that ties trap performance into broader plant automation systems. TLV Co., Ltd. specializes in compact thermostatic designs that dominate Asian manufacturing installations.
A steam trap valve is a self-acting temperature and pressure-sensitive discharge device, typically constructed with stainless steel or brass bodies and precision-seated internal mechanisms, designed to automatically purge condensate and non-condensable gases from steam lines while blocking live steam loss. Its primary industrial purpose centers on thermal efficiency protection and equipment longevity across pressurized steam systems. Mechanical traps retain the largest installed base due to proven reliability in heavy-cycle environments, though thermostatic variants gain share in light industrial and commercial heating where space constraints and cost sensitivity dominate specification decisions. Electric traps occupy a niche but expanding position where digital monitoring and remote diagnostics justify premium positioning.
The EPA enforces efficiency benchmarks under the Clean Air Act that compel boiler operators to minimize steam leakage and fuel waste, directly elevating replacement demand for failed or undersized traps. ISO standards for pressure equipment and the EU F-Gas Regulation on fluorinated greenhouse gases indirectly shape material selection and sealing technology requirements for export-oriented manufacturers. Stakeholders must weigh captive maintenance capabilities against third-party service partnerships as margin pools migrate from unit sales toward lifecycle performance contracts.
Market Dynamics
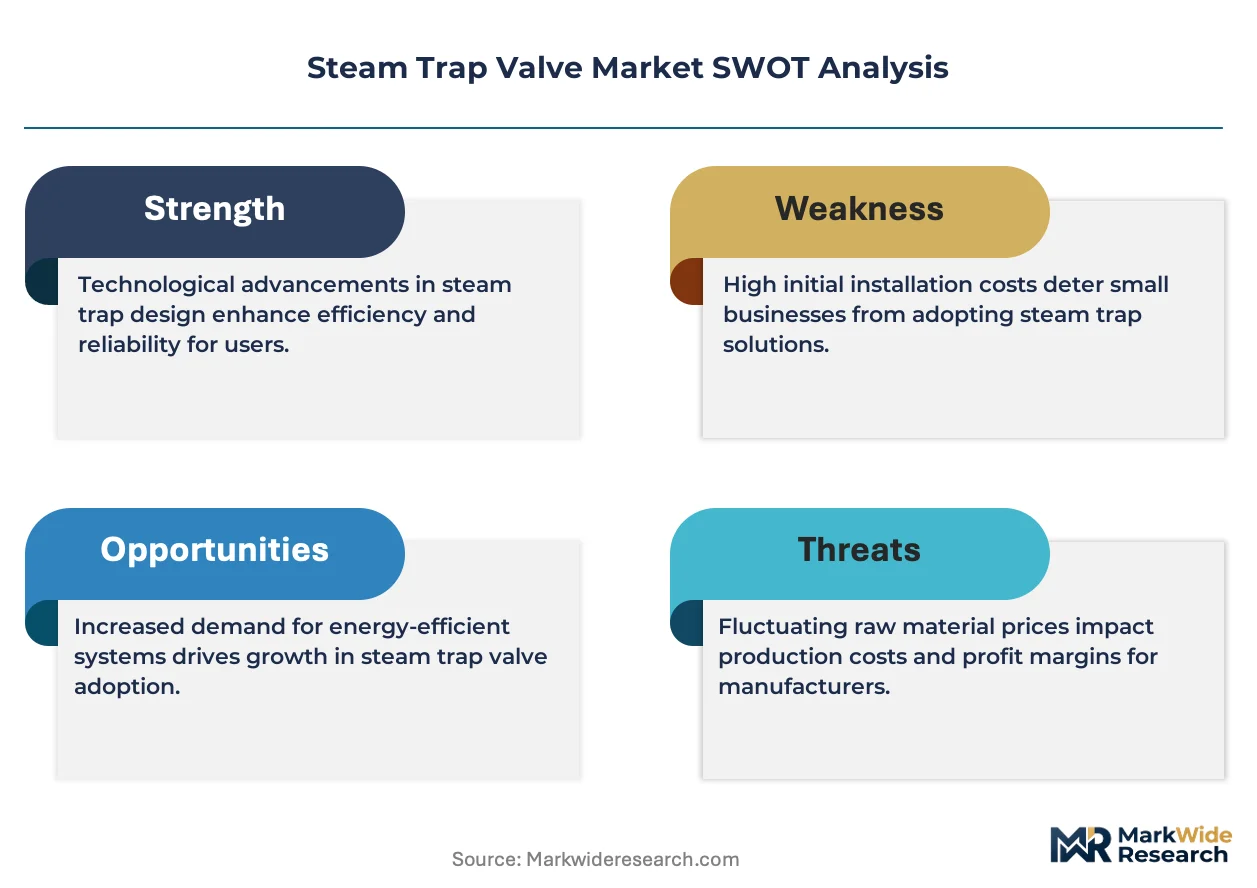
The steam trap valve market is undergoing structural recalibration as predictive maintenance services capture margin pools that historically accrued to original equipment manufacturers. Refurbishment contracts and steam system audits are displacing straightforward replacement sales, forcing suppliers to reconfigure revenue models around lifecycle performance rather than unit shipment volume.
Growth Catalysts
- EPA Clean Air Act enforcement:Boiler emission standards in the United States compel facilities to eliminate steam leakage, accelerating replacement cycles for inefficient or failed trap installations.
- Food processing expansion:Thermal-intensive operations in Germany's chemical and pharmaceutical clusters sustain intensive steam infrastructure investment and systematic trap audit programs.
- Instrumentation integration:Plant automation architectures now embed trap performance monitoring, creating specification pull for smart-enabled valve designs.
Market Restraints
- Stainless steel price volatility:Raw material cost swings compress fabrication margins and destabilize project quoting for large-scale industrial contracts.
- EU F-Gas Regulation compliance:Sealing technology requirements for fluorinated greenhouse gas containment add certification overhead for export-oriented manufacturers.
- Mechanical trap reliability:Proven heavy-cycle performance of established designs slows thermostatic and electric variant penetration in conservative buyer segments.
Strategic Opportunities
- Asian manufacturing densification:Compact thermostatic designs address space-constrained installations in high-growth industrial zones.
- ISO pressure equipment standards harmonization:Unified certification pathways reduce market entry friction for multi-region suppliers.
- Digital twin convergence:Integration of trap diagnostics with predictive analytics platforms enables premium positioning for connected product portfolios.
Industry Challenges
- Steam system engineering expertise scarcity:Specialized knowledge required for proper trap sizing and placement constrains service network expansion.
- Legacy infrastructure integration complexity:Retrofit installations face compatibility barriers with aging boiler control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steam Trap Valve Market |
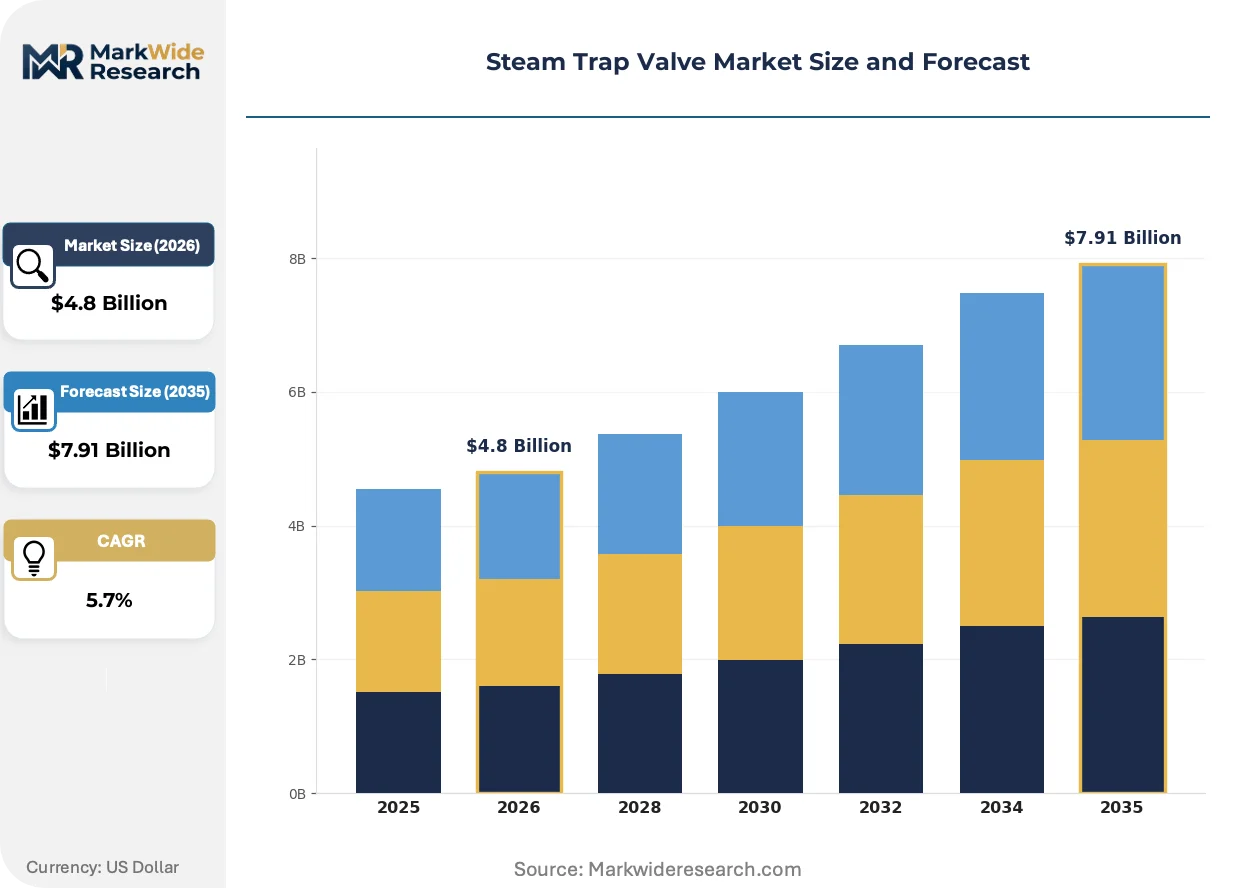
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermostatic Traps, Mechanical Traps, Float Traps, Electric Traps Installation Type: Vertical, Horizontal, In-line, Arched Material: Cast Iron, Stainless Steel, Brass, Plastic End User: Manufacturing, Power Generation, Oil & Gas, Food Processing |
| Companies Covered | Spirax-Sarco Engineering, Emerson Electric Co., TLV Co., Ltd., Thermax Limited, Velan Inc., Armstrong International Inc., Watts Water Technologies Inc., Flowserve Corporation, Pentair Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steam Trap Valve Market Strategic Shifts
Steam trap technology is pivoting toward intelligence and miniaturization as efficiency mandates intensify and plant footprint constraints tighten. Three interconnected developments are redefining competitive positioning.
Smart trap instrumentation is migrating from standalone monitoring devices to integrated plant automation nodes. Chemical processing facilities in Germany and the United States are specifying valves with embedded sensors that feed directly into distributed control systems. This convergence compresses the addressable market for purely mechanical alternatives while elevating supplier technical requirements.
REACH and the EU F-Gas Regulation are reshaping material selection protocols for sealing components and valve bodies. Manufacturers serving European export markets must reformulate elastomer specifications and document substance compliance across extended supply chains. Thermostatic trap variants with alternative bellows materials are gaining specification share as legacy formulations face registration sunset.
Lifecycle contracting is displacing transactional procurement in thermal-intensive process industries. Food processing and pharmaceutical facilities are unbundling trap replacement from comprehensive steam system performance agreements. Germany's chemical corridor exhibits the most advanced adoption, with operators transferring inventory risk to service-integrated suppliers.
Steam Trap Valve Market Segmentation
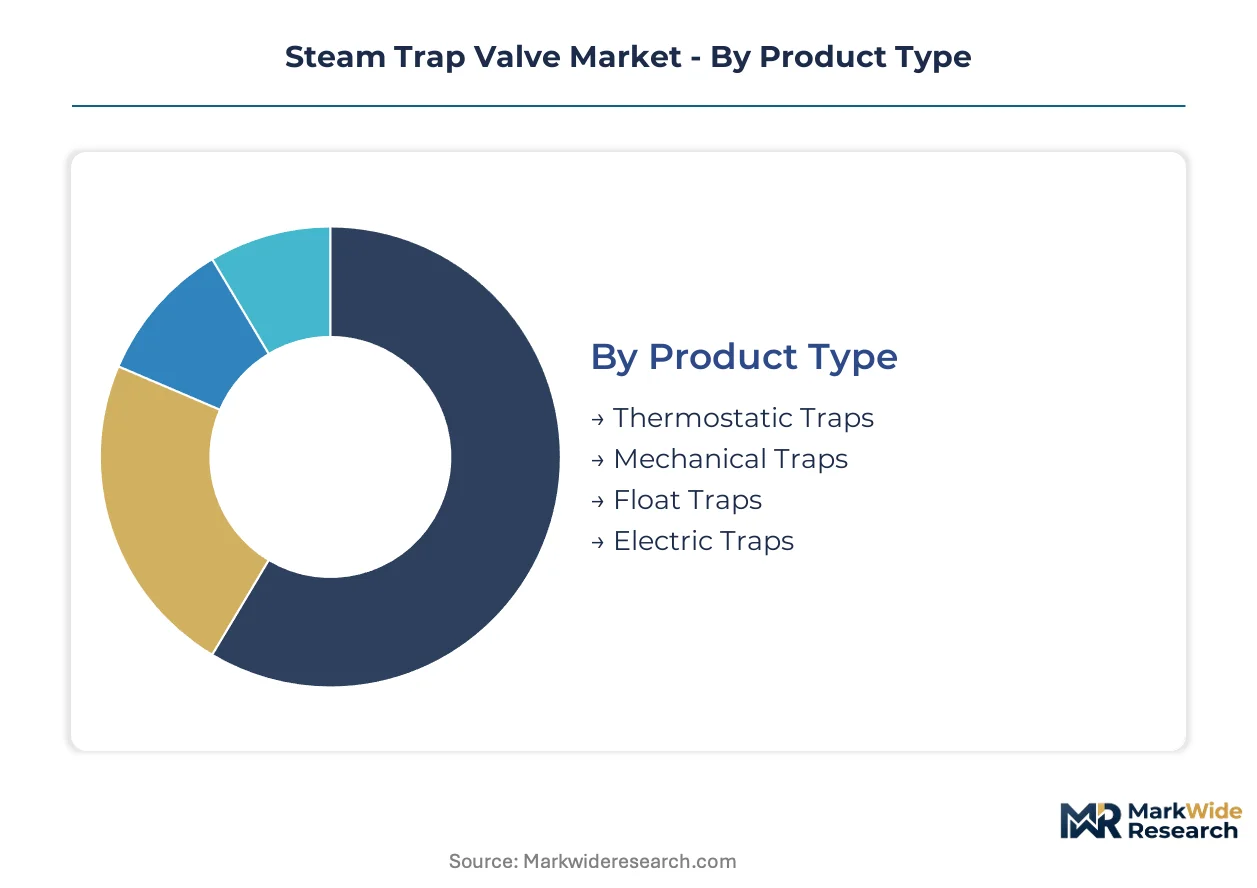
Steam trap valve segmentation reveals how specification choices cascade through system design, maintenance protocols, and regulatory compliance pathways. Product architecture, installation geometry, material selection, and end-use intensity each create distinct commercial lanes with diverging margin and service attachment profiles.
Product Type:
Use-case spectrum spans from passive thermal response to active digital control, with each architecture optimizing for specific condensate loads and monitoring requirements.
- Mechanical Traps:Leverage buoyancy and lever mechanisms to discharge condensate without external power. Chemical processing facilities in Germany specify these for heavy-cycle environments where proven uptime outweighs efficiency premiums. The EPA's Clean Air Act enforcement on boiler emissions sustains replacement demand as facilities eliminate leakage from aging installations.
- Thermostatic Traps:Employ temperature-sensitive bellows or bimetallic elements to modulate discharge. Asian manufacturing installations favor compact variants where space constraints and cost sensitivity dominate procurement decisions. REACH compliance requirements are accelerating reformulation of legacy bellows materials across European export supply chains.
- Float Traps:Continuous-discharge design suits steady condensate loads in pharmaceutical clean steam systems.
- Electric Traps:Embedded sensors enable remote diagnostics and predictive maintenance in digitally integrated plants.
Established volume favors Mechanical Traps; emerging adoption favors Electric Traps.
Installation Type:
Orientation constraints derive from piping topology, maintenance access, and condensate drainage physics in retrofit versus greenfield contexts.
- Horizontal:Dominates legacy industrial infrastructure with side-entry mounting on steam mains. Power generation facilities in the United States maintain extensive horizontal trap populations requiring systematic audit programs. Stainless steel price volatility compresses margin on large-scale replacement contracts for these standardized configurations.
- In-line:Axial flow geometry minimizes pressure drop and simplifies piping runs. Oil & gas processing in the North Sea favors in-line thermostatic designs where compact footprint reduces platform weight. ISO pressure equipment standards harmonization is reducing certification friction for multi-region suppliers serving these projects.
- Vertical:Top-mount or bottom-mount variants address condensate collection at riser terminations.
- Arched:Specialized geometry for steam jacketing and tracer line applications in food processing thermal loops.
Horizontal maintains the largest installed base; In-line configurations are climbing the fastest in new capital projects.
Material:
Cost tier and corrosion resistance requirements segment procurement between commodity castings and premium alloys.
- Stainless Steel:Austenitic and duplex grades deliver corrosion resistance for aggressive condensate chemistries. Pharmaceutical manufacturing in Switzerland mandates stainless construction for clean steam validation protocols. Raw material cost swings destabilize project quoting and compress fabrication margins for large industrial contracts.
- Cast Iron:Lowest first-cost option for low-pressure heating and commercial applications with benign condensate. District heating networks in Poland specify cast iron float traps where replacement cycles are budget-driven rather than efficiency-optimized. EU F-Gas Regulation compliance adds certification overhead for sealing technology in export-oriented supply chains.
- Brass:Machinability and thermal conductivity suit precision thermostatic elements and small-bore installations.
- Plastic:Polymer bodies address corrosive condensate in specialized chemical processing and laboratory steam.
Cast Iron dominates unit volume; Stainless Steel commands premium positioning in regulated process industries.
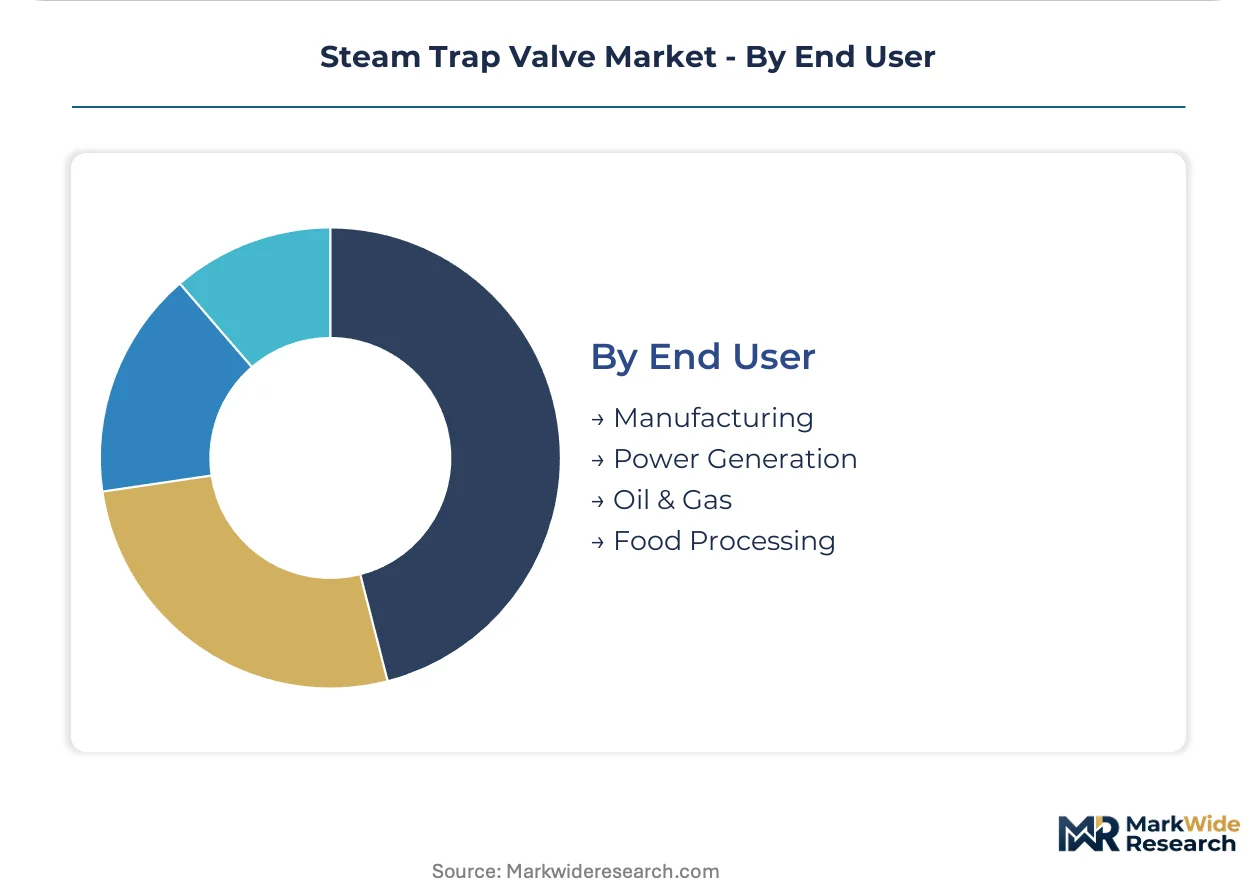
End User:
Customer type determines service intensity, specification authority, and lifecycle contracting sophistication.
- Food Processing:Thermal-intensive operations with stringent hygiene protocols and systematic steam system audit programs. Facilities in Germany's chemical corridor are transferring inventory risk to service-integrated suppliers through performance-based contracts. The EU F-Gas Regulation shapes sealing technology requirements for export-oriented equipment manufacturers.
- Manufacturing:Diverse base spanning automotive, textiles, and general industrial with varying maintenance capabilities. Japanese automotive plants specify TLV compact thermostatic designs for space-constrained press and drying applications. Predictive maintenance services are capturing margin pools that historically accrued to original equipment sales.
- Power Generation:Centralized utilities and industrial cogen with continuous operation and high availability requirements.
- Oil & Gas:Upstream, midstream, and downstream facilities with hazardous area classifications and remote monitoring needs.
Food Processing leads service contract penetration; Manufacturing represents the broadest volume base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steam trap valve consumption patterns diverge sharply between mature industrial economies prioritizing predictive maintenance retrofits and emerging manufacturing centers emphasizing first-cost minimization on new installations. Germany and the United States anchor replacement-driven demand through regulatory enforcement on boiler efficiency, while Asian industrial corridors favor compact thermostatic designs for space-constrained greenfield projects.
United States
Power generation utilities and chemical processing facilities sustain extensive horizontal trap populations requiring systematic audit programs. EPA Clean Air Act enforcement on industrial boiler emissions compels facilities to eliminate steam leakage, accelerating replacement cycles for failed or undersized installations. The Gulf Coast petrochemical corridor exhibits concentrated demand for smart-enabled valve designs feeding into distributed control systems.
Germany
Chemical and pharmaceutical clusters in the Rhine-Ruhr and Bavaria regions maintain intensive steam infrastructure with sophisticated lifecycle contracting. REACH compliance requirements and the EU F-Gas Regulation reshape material selection protocols for sealing components and valve bodies. Food processing facilities in Baden-Württemberg are transferring inventory risk to service-integrated suppliers through performance-based agreements.
China
Manufacturing densification in the Yangtze River Delta and Pearl River Delta drives specification of compact thermostatic designs for space-constrained installations. The country's national environmental regulator encloses industrial boiler efficiency standards that elevate replacement demand. Shandong Province's chemical processing base exhibits concentrated procurement of stainless steel construction for aggressive condensate chemistries.
Japan
Automotive and precision manufacturing plants specify compact thermostatic designs for press and drying applications with severe space constraints. METI industrial efficiency guidelines shape procurement protocols for steam system upgrades. The Chubu region around Nagoya anchors domestic demand through integrated instrumentation and plant automation architectures.
India
Pharmaceutical manufacturing in Maharashtra and Gujarat mandates stainless steel construction for clean steam validation protocols. The country's national standards body enforces pressure equipment certification that filters import supply chains. Tamil Nadu's textile processing clusters represent emerging specification pull for cost-optimized float trap configurations in thermal-intensive operations.
Steam Trap Valve Market Competitive Environment
Capability concentration sits with specialized service-integrated suppliers; scale advantage sits with diversified industrial conglomerates with broad valve portfolios. The market structures around three tiers: global service networks capturing lifecycle contracts, instrumentation specialists embedding trap diagnostics into automation architectures, and regional fabricators competing on first-cost for standardized mechanical designs. Dominant competitive moves include backward integration into precision casting operations and strategic partnerships with predictive analytics platforms.
Among UK-based engineering groups, Spirax-Sarco Engineering occupies a position exemplifying the service-integrated archetype through recurring calibration and replacement cycle capture. Emerson Electric Co. and TLV Co., Ltd. represent contrasting geographic anchors within the instrumentation tier, with the former sitting within North American automation ecosystems and the latter exemplifying compact thermostatic specialization for Asian manufacturing installations. These three entities collectively illustrate how competitive positioning fragments across service intensity, digital integration depth, and regional manufacturing density.
| Leading Market Players |
|---|
| Spirax-Sarco Engineering |
| Emerson Electric Co. |
| TLV Co., Ltd. |
| Thermax Limited |
| Velan Inc. |
| Armstrong International Inc. |
| Watts Water Technologies Inc. |
| Flowserve Corporation |
| Pentair Inc. |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Chinese stainless steel casting facilities compresses fabrication margins for export-oriented valve manufacturers while simultaneously elevating pricing leverage for buyers with volume consolidation power. This utilization asymmetry drives divergent supplier behavior: integrated service networks absorb margin compression through lifecycle contracts, while commodity fabricators face destabilized project quoting.
Pricing Analysis
Long-term performance contracts dominate procurement in Germany's chemical corridor, displacing transactional unit sales as food processing facilities transfer inventory risk to service-integrated suppliers. Price differentiation rests on certification tier and after-sales bundling intensity, with ISO pressure equipment validation commanding measurable premiums. Cost compression in cast iron mechanical traps intensifies due to raw material volatility, though pharmaceutical clean steam applications exhibit minimal price sensitivity.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculus for brass and stainless steel component sourcing. Manufacturing concentrates in China, Germany, and Japan, with precision-seated internal mechanisms drawing from Swiss and Japanese specialty machining. Single-source vulnerability persists for REACH-compliant elastomer formulations. Distribution runs through authorized service networks in regulated process industries and industrial distributors in general manufacturing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive maintenance service revenue is expanding faster than original equipment sales, converting transactional hardware procurement into recurring performance contracts with superior margin durability.
For Market Incumbents: Entrench lifecycle service capabilities through backward integration into precision casting and captive calibration infrastructure. The EPA's Clean Air Act enforcement accelerates replacement cycles, but thermostatic and electric variants threaten mechanical trap incumbency in digitally integrated plants. Prioritize instrumentation partnerships that embed trap diagnostics into distributed control architectures. For New Entrants and Emerging Players: Establish a beachhead in India's pharmaceutical clean steam segment where stainless steel validation requirements filter import competition. White-space exists in compact electric trap designs for Asian manufacturing densification. Pursue OEM partnerships with boiler manufacturers to secure specification pull before plant commissioning. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among service-integrated suppliers with captive maintenance networks. Long-term viability favors entities with backward integration into specialty materials and predictive analytics platform partnerships. Monitor EPA enforcement intensity and EU F-Gas Regulation implementation as demand inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Lifecycle Service Contract Expansion | Captures recurring calibration revenue from Germany's chemical processing clusters. |
| Smart Instrumentation Integration | Embeds trap diagnostics into Emerson and Yokogawa distributed control ecosystems. |
| REACH-Compliant Material Reformulation | Ensures European market access as legacy bellows formulations face registration sunset. |
| Compact Thermostatic Design Localization | Addresses space constraints in Yangtze River Delta manufacturing installations. |
| Predictive Analytics Platform Partnership | Converts trap performance data into premium-positioned digital twin offerings. |
Study Parameters
Initial hypotheses were tested against primary input from plant maintenance directors, OEM procurement teams, aftermarket service heads, and steam system audit specialists and refined through secondary validation. Sources included customs and trade data for valve and casting imports, EPA enforcement action databases, SEC 10-K filings from diversified industrial conglomerates, and ISO certification registry extracts. Bottom-up unit shipment estimates triangulated against top-down steam infrastructure investment flows.
Demand-supply balance modeling anchored volume projections, with segmentation across product architecture, material grade, installation geometry, and end-use intensity. CAGRs derived from regression against industrial boiler efficiency regulation timelines and manufacturing capacity expansion announcements. Industry-specific inputs included steam trap failure rate assumptions from insurance underwriting data and predictive maintenance adoption curves from automation vendor disclosures.
Stress conditions across stainless steel price volatility, EPA enforcement intensity, and EU F-Gas Regulation implementation timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory persistence and service contract penetration rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Global Level Gauge Market
Valves
Global Thermostatic Radiator Valve Market
Valves
Compressor Valves Market
Valves
Steam Safety Valve Market
Valves
Choke and Kill Manifold Market
Valves
Global Fluid Management Systems Market
Valves
APAC Valves Market
Valves
Middle East and Africa Machined Seals Market
Valves
Safety Valve Market
Valves
High-Purity Fluoropolymer Valves Market
Valves
Hybrid Valve Market
Valves
Hydraulic Valves Market
Valves
Global Control Valves Market
Valves
Industrial Valves and Actuators Market
Valves
Gas Equipment Market
Valves
Safety Valve Test Benches Market