
 Global Globe Valve Market | 2026-2036
Global Globe Valve Market Size, Share, and Industry Trends Forecast 2026-2036
Global Globe Valve Market Foresight
The divergence between premium and commodity tiers is shifting toward sealing technology and pressure ratings rather than basic port geometry. Emerson Electric leverages integrated digital positioners and predictive diagnostics to command premium positioning in critical service applications. Flowserve Corporation anchors its portfolio through backward integration into alloy casting and specialized coating processes for sour gas environments. Crane Co. competes aggressively on delivery speed and aftermarket parts availability for standard HVAC and water treatment replacements.
A globe valve employs a movable disk-type element and a stationary ring seat in a generally spherical body to regulate, throttle, or isolate fluid flow through linear stem motion, with typical pressure ratings spanning ANSI Class 150 through 2500 and temperature capabilities from cryogenic to over 538 degrees Celsius depending on material selection. Rising stem globe valves retain dominant share in power generation and petrochemical applications where visual position indication satisfies safety protocols, while balanced plug designs are gaining fastest in high-pressure hydrocarbon service because reduced operating torque permits smaller actuators and lower installation costs. Stainless steel and alloy steel materials capture the deepest margin pools due to nuclear certification requirements and corrosion-resistant specifications in offshore marine engineering.
The US EPA enforces stringent fugitive emissions standards under New Source Performance Standards that compel valve manufacturers to certify packing systems to API 622 and API 641 test protocols. The EU F-Gas Regulation and REACH framework restrict fluorinated polymer use in seals, pushing European operators toward graphite-based packing and low-emission bonnet designs. China's SAMR and GB standards mandate domestic content ratios and pressure equipment safety certifications that shape import competitiveness. Stakeholders must monitor how diverging regional testing regimes for methane leakage reshape product development roadmaps and factory certification investments.
Market Dynamics
The divergence between pressure-sealed bonnet designs and conventional bolted bonnet constructions now structures competitive positioning across power generation and hydrocarbon processing, as fugitive emissions regulations harden procurement specifications and compress the viable supplier base.
Growth Catalysts
- EPA NSPS methane rules:US power utilities must replace legacy packing systems with API 622-certified low-emission designs, forcing systematic valve replacement cycles at coal and gas-fired plants.
- China refinery expansion:State-backed Sinopec and PetroChina megaprojects require large-diameter alloy steel globe valves for high-pressure catalytic cracking units, concentrating demand in domestic foundry capacity.
- Graphite-based sealing:REACH restrictions on fluorinated polymers accelerate European adoption of flexible graphite packing for steam and hydrocarbon service, displacing PTFE in temperature-critical applications.
Market Restraints
- Alloy steel input volatility:Nickel and molybdenum price swings compress margin predictability for nuclear-certified valve manufacturers dependent on ASTM A351 CF8M castings.
- Foundry concentration:Premium alloy casting capacity clusters in eastern China and western Germany, creating single-source vulnerability for sour gas valve bodies requiring NACE MR0175 compliance.
- Butterfly valve substitution:Triple-offset butterfly designs encroach on globe valve territory in clean service throttling applications below ANSI Class 600, eroding standard-grade market share.
Strategic Opportunities
- India municipal water infrastructure:Jal Jeevan Mission distribution networks require corrosion-resistant bronze and stainless steel globe valves for pressure regulation in rural pipeline systems.
- Digital positioner convergence:Integration of HART-enabled smart positioners with predictive diagnostics creates aftermarket service revenue streams beyond hardware margins.
- Hydrogen service certification:Emerging ISO 19880-3 testing protocols for high-pressure hydrogen valves open positioning for manufacturers with materials science capabilities in embrittlement-resistant alloys.
Industry Challenges
- Nuclear N-stamp certification timelines:ASME III qualification cycles extend 18-24 months, freezing supplier rosters and blocking new entrants from safety-critical reactor coolant applications.
- Legacy DCS integration friction:Digital valve positioners must interface with 1980s-era distributed control systems through proprietary protocol gateways, complicating smart valve deployment at brownfield petrochemical sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Globe Valve Market |
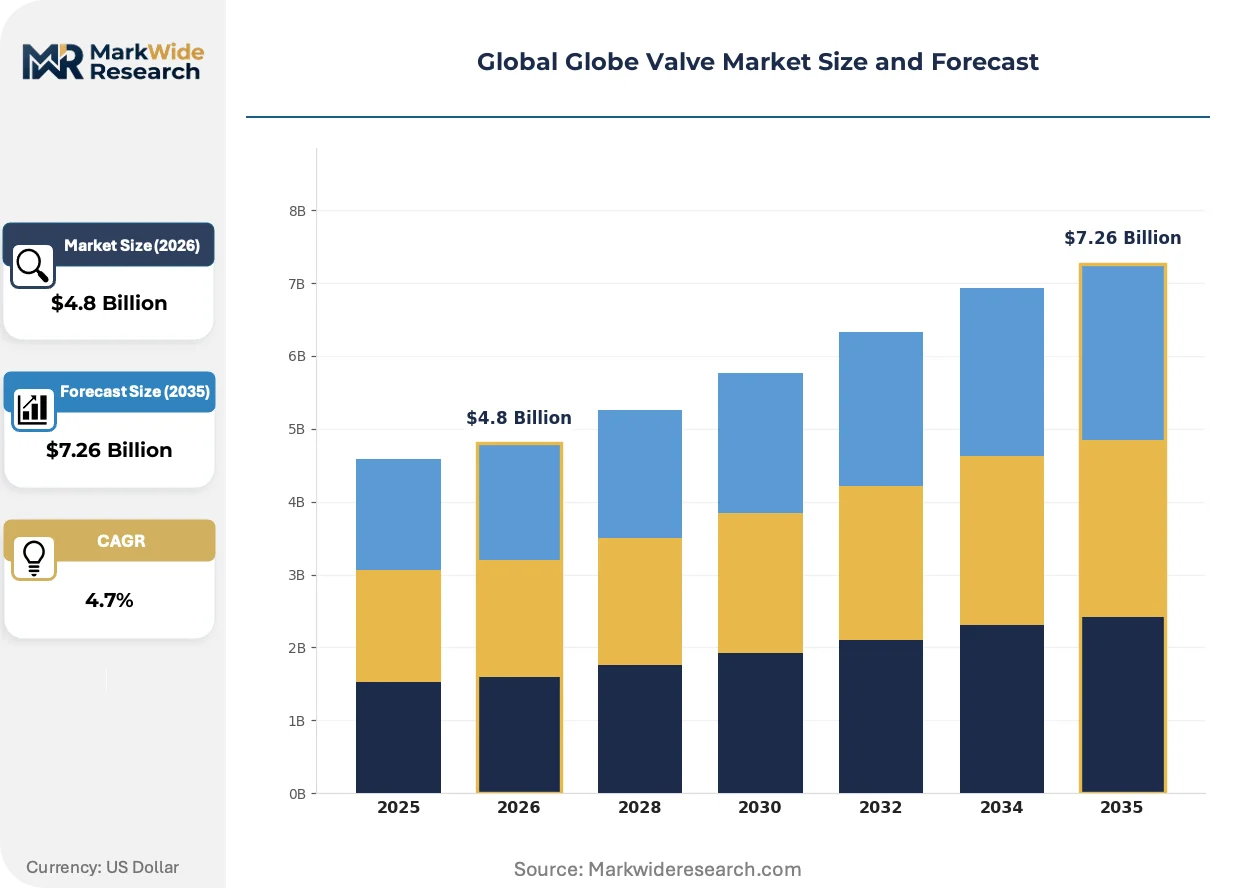
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.26 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rising Stem Globe Valve, Balanced Plug Globe Valve, Angle Globe Valve, Pressure Seal Bonnet Globe Valve Application: Power Generation, Petrochemical Plants, Water Treatment, HVAC Systems, Pulp & Paper, Marine Engineering End User: Oil & Gas Producers, Chemical Manufacturers, Municipal Utilities, Shipbuilding Firms Material: Cast Steel, Stainless Steel, Bronze, Alloy Steel, Carbon Steel |
| Companies Covered | Baker Hughes, Curtiss-Wright Corporation, Emerson Electric, Honeywell International Inc., Schlumberger Ltd., Flowserve Corporation, Danfoss AS, The Weir Group PLC, Crane Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Globe Valve Market Shifts & Advancements
Sealing technology and materials science now absorb the bulk of product development investment, as emission containment performance separates viable suppliers from commodity competitors across regulated industries.
Additive manufacturing is absorbing qualification protocols for complex internal flow passages in severe service valve bodies. Siemens Energy and Baker Hughes pilot laser powder bed fusion for Inconel 625 cage components in high-pressure steam letdown applications. The technology is absorbing prototyping timelines from months to weeks while compressing minimum viable production runs.
EU F-Gas Regulation phase-down schedules tighten fluorinated greenhouse gas containment requirements through 2030. Industrial valve packings fall under extended producer responsibility frameworks, forcing reformulation of traditional PTFE-based systems. German chemical operators now specify graphite-only packing for all new steam service installations to preempt compliance exposure.
Integrated valve-actuator-positioner packages are displacing discrete component procurement at North American LNG export terminals. EPC contractors specify factory-tested assemblies to reduce field commissioning risk and accelerate startup schedules. This bundling concentrates specification authority with valve OEMs and marginalizes independent actuator distributors.
Global Globe Valve Market Segmentation
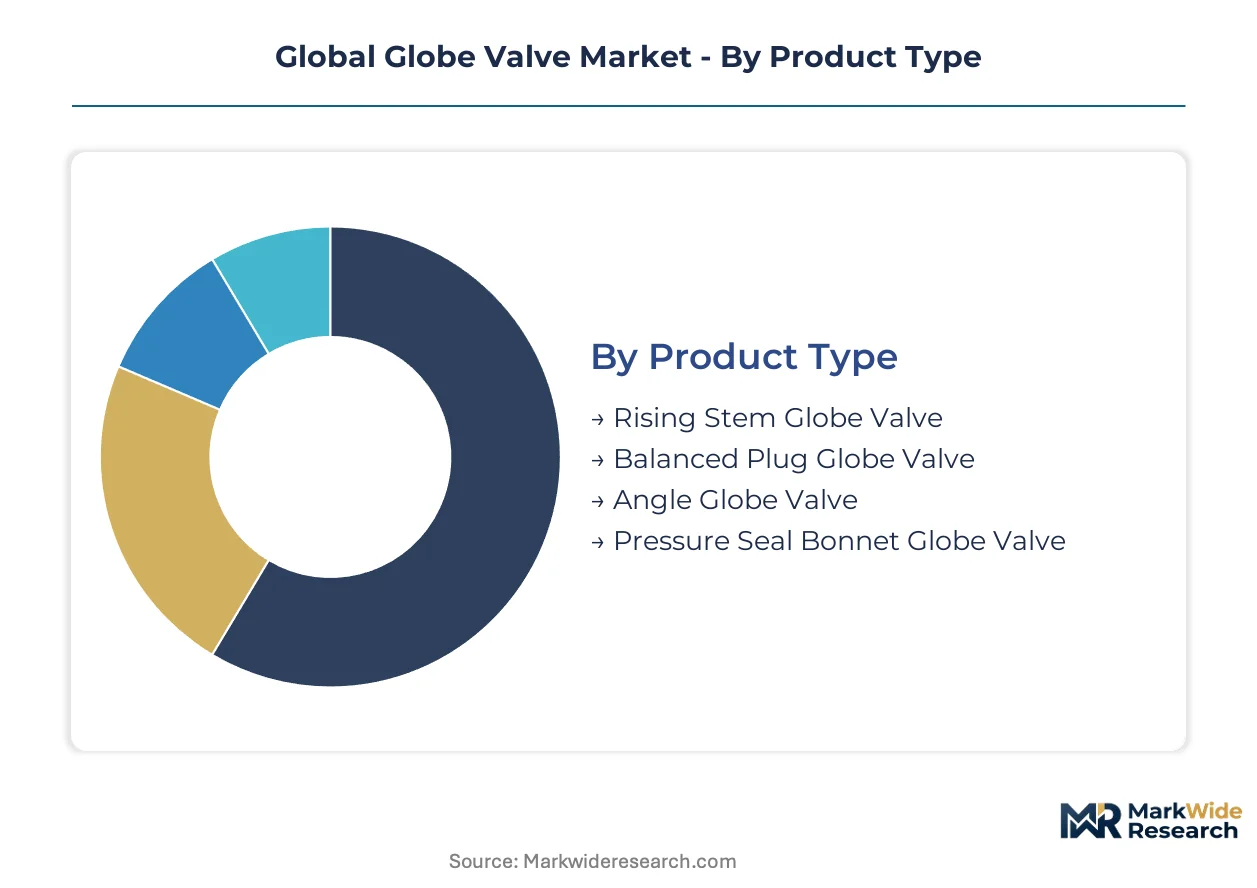
Valve selection in process industries now hinges on emission containment performance and pressure rating compatibility with existing piping systems. Procurement teams segment specifications by bonnet design, material certification, and actuator integration rather than basic flow geometry.
Product Type:
Upgrade cycles from conventional bolted bonnet designs to pressure-sealed configurations now dominate capital planning at US power utilities and European petrochemical complexes.
- Rising Stem Globe Valve:External stem position provides visual confirmation of open/closed status required by OSHA lockout-tagout protocols at coal and gas-fired generating stations. Demand clusters in US Midwest utility fleets where legacy boiler feedwater systems require ANSI Class 600-900 replacements to meet EPA methane rules.
- Pressure Seal Bonnet Globe Valve:Self-energizing seal geometry tightens under internal pressure, eliminating through-bolts and reducing fugitive emission pathways. Sinopec and PetroChina refinery expansions in Shandong and Zhejiang provinces specify large-bore alloy steel units for catalytic cracking unit isolation.
- Balanced Plug Globe Valve:Reduced unbalanced area permits smaller pneumatic actuators in high-pressure hydrocarbon throttle service.
- Angle Globe Valve:90-degree flow path suits compact skid-mounted process units where piping envelope constraints limit straight-run valve accommodation.
Rising Stem Globe Valve sits at the top of the volume ranking, with Pressure Seal Bonnet Globe Valve climbing the fastest.
Application:
End-use concentration tracks regional industrial infrastructure age and regulatory enforcement intensity rather than absolute plant counts.
- Power Generation:Coal and combined-cycle gas turbine plants in the US, Germany, and India drive replacement demand for API 622-certified low-emission packings. FERC pipeline safety advisories and EPA NSPS enforcement compel systematic valve surveys and upgrade scheduling at facilities exceeding 50-year operational life.
- Petrochemical Plants:Steam cracking and aromatic complexes require NACE MR0175-compliant sour gas valves with Inconel 625 trim. Gulf Coast US and Rotterdam-Antwerp corridor operators specify pressure-sealed bonnets for high-temperature catalytic reforming service.
- Water Treatment:Municipal filtration and reverse osmosis plants specify bronze and stainless steel rising stem designs for corrosion resistance in chlorinated environments.
- HVAC Systems:Central plant steam distribution and chilled water circuits utilize standard cast iron and bronze globe valves for throttling and isolation.
- Pulp & Paper:Digester blow heat recovery and black liquor processing demand stainless steel construction for alkaline corrosion resistance.
- Marine Engineering:Ballast water treatment and cargo tank isolation aboard LNG carriers and chemical tankers require cryogenic and sour gas certifications.
Power Generation commands the largest installed base, while Petrochemical Plants show the steepest expansion trajectory.
End User:
Procurement authority centralization varies sharply by sector, with integrated oil majors consolidating specifications while municipal utilities delegate to engineering contractors.
- Oil & Gas Producers:Supermajors and national oil companies in the US, Saudi Arabia, and Brazil mandate supplier qualification through IOGP standards and site-specific technical audits. Offshore platform projects specify alloy steel pressure-sealed designs for wellhead isolation and production manifold service.
- Chemical Manufacturers:BASF, Dow, and SABIC operate centralized valve specification databases that lock out uncertified suppliers from greenfield and turnaround procurement.
- Municipal Utilities:US water authorities and India's Jal Jeevan Mission implementing agencies prioritize lowest life-cycle cost over first cost, favoring bronze and stainless steel rising stem designs with established local service networks.
- Shipbuilding Firms:Korean and Chinese yards specify integrated valve-actuator packages to compress commissioning schedules for LNG carrier and container ship newbuild programs.
Oil & Gas Producers account for the deepest specification requirements, with Shipbuilding Firms expanding specification influence fastest.
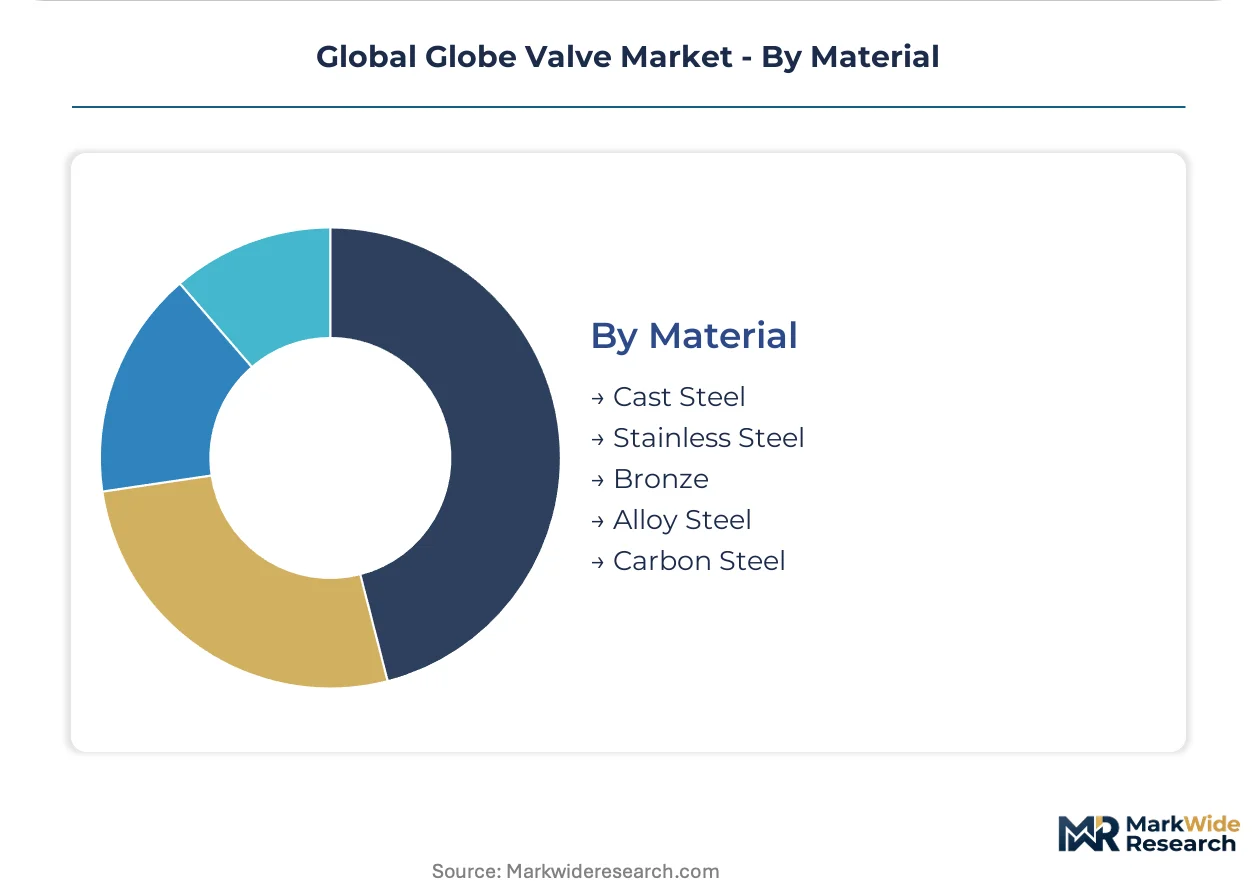
Material:
Raw material cost volatility and certification lead times now structure supplier margins more than fabrication labor or assembly complexity.
- Stainless Steel:ASTM A351 CF8M castings dominate nuclear, pharmaceutical, and food-grade applications requiring ASME III N-stamp or 3A sanitary certifications. Japanese and Korean foundry capacity constraints extend delivery timelines for super-austenitic grades in seawater desalination service.
- Alloy Steel:ASTM A217 WC6 and WC9 chrome-moly grades withstand temperatures exceeding 538 degrees Celsius in power plant superheat and reheat steam circuits. Nickel and molybdenum price exposure compress margin predictability for independent valve manufacturers without captive foundry operations.
- Cast Steel:ASTM A216 WCB carbon steel serves general industrial steam and hydrocarbon isolation where corrosion resistance requirements permit lower alloy content.
- Bronze:C83600 and C95800 alloys provide galvanic compatibility with copper piping in marine and potable water systems.
- Carbon Steel:Forged A105 bodies with hard-faced seats satisfy ANSI Class 800-1500 requirements in standard refinery and chemical plant service.
Stainless Steel leads material value contribution, with Alloy Steel gaining specification share fastest in high-temperature power generation applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized foundry workforces in eastern China and western Germany anchor global supply for high-pressure alloy valve bodies. US utility engineers and Indian municipal procurement officers drive specification authority across their respective infrastructure programs. Korean shipyard technicians concentrate demand for integrated valve-actuator packages.
United States
Midwest coal and gas-fired generating stations require ANSI Class 600-900 rising stem replacements under EPA NSPS methane enforcement. FERC pipeline safety advisories compel systematic valve surveys at facilities exceeding 50-year operational life. Houston-Gulf Coast petrochemical clusters specify pressure-sealed bonnets for catalytic reforming service.
Germany
Chemical operators in the Rhine-Ruhr corridor specify graphite-only packing for new steam installations to preempt EU F-Gas Regulation exposure. REACH restrictions on fluorinated polymers accelerate displacement of PTFE in temperature-critical applications. Düsseldorf-area engineering consultancies centralize procurement specifications for BASF and Evonik turnaround projects.
China
State-backed Sinopec and PetroChina megaprojects in Shandong and Zhejiang provinces require large-bore alloy steel pressure-sealed units for catalytic cracking isolation. SAMR domestic content ratios and GB pressure equipment certifications shape import competitiveness. Foundry capacity concentrates in Jiangsu and Zhejiang for ASTM A217 WC6 and WC9 chrome-moly castings.
India
Jal Jeevan Mission rural distribution networks require corrosion-resistant bronze and stainless steel rising stem designs for pressure regulation. Municipal utilities prioritize life-cycle cost over first cost, favoring established local service networks. Gujarat and Maharashtra industrial corridors anchor fabrication capacity for water treatment and power plant procurement.
South Korea
DSME and Hyundai Heavy Industries yards specify integrated valve-actuator packages to compress commissioning schedules for LNG carrier newbuilds. Ulsan and Geoje shipbuilding clusters concentrate demand for cryogenic and sour gas certifications. Korean foundries face capacity constraints extending delivery timelines for super-austenitic grades.
Global Globe Valve Market Competitive Landscape
Top-tier vendors anchor premium-tier specification authority, while mid-scale fabricators compete on delivery speed and aftermarket availability. The supplier base structures around three tiers: integrated industrial conglomerates with captive foundry operations, specialized valve manufacturers with NACE and nuclear certifications, and regional fabricators serving standard HVAC and water treatment replacements. Dominant competitive moves include backward integration into alloy casting capacity and factory-tested valve-actuator bundling for LNG terminal contractors.
Within the integrated industrial tier, Baker Hughes and Flowserve Corporation exemplify archetypes combining energy-sector positioning with materials science capabilities. Emerson Electric occupies a position representing predictive diagnostics and digital positioner convergence. Among these, Flowserve Corporation anchors the backward-integrated foundry model, while Emerson Electric exemplifies smart valve platform strategies. Curtiss-Wright Corporation sits within the nuclear and defense certification specialist tier.
| Leading Market Players |
|---|
| Baker Hughes |
| Curtiss-Wright Corporation |
| Emerson Electric |
| Honeywell International Inc. |
| Schlumberger Ltd. |
| Flowserve Corporation |
| Danfoss AS |
| The Weir Group PLC |
| Crane Co. |
| Others |
Supply & Pricing Matrix
Additive manufacturing adoption for Inconel 625 cage components simultaneously compresses prototyping timelines and concentrates premium valve production among laser powder bed fusion-capable facilities in Germany and China, reshaping both cost structures and supplier tiering.
Pricing Analysis
Bundled valve-actuator-positioner packages command 15-25% premiums over discrete component procurement at North American LNG terminals, while unbundled replacement valves for municipal water systems compete on first-cost metrics. Price differentiation rests on API 622 certification status and foundry backward integration depth. Cost compression in standard cast steel tiers intensifies as triple-offset butterfly valves erode share below ANSI Class 600. Municipal utilities exhibit highest price sensitivity; nuclear-certified fabricators face lowest.
Supply Chain Analysis
Single-source vulnerability sits with ASTM A217 WC6 and WC9 chrome-moly casting capacity concentrated in Jiangsu and Zhejiang provinces, plus western German foundries serving NACE MR0175 sour gas specifications. Raw material dependencies draw from nickel, molybdenum, and graphite feedstock markets. Tariff exposure on Chinese alloy castings threatens margin predictability for non-integrated manufacturers. Distribution runs through EPC contractors at greenfield projects and aftermarket service networks for replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EPA NSPS methane enforcement and EU F-Gas Regulation phase-downs systematically expand addressable demand for low-emission sealing technologies.
For Market Incumbents: Deepen captive foundry investments in Inconel 625 and super-austenitic grades to insulate against nickel price volatility and Korean capacity constraints. Lock EPC contractors into long-term valve-actuator bundling agreements before independent actuator distributors consolidate. Triple-offset butterfly substitution below ANSI Class 600 demands accelerated pressure-sealed bonnet differentiation in throttling applications. For New Entrants and Emerging Players: Enter via hydrogen service certification under emerging ISO 19880-3 protocols, where incumbent N-stamp timelines create 18-24 month qualification gaps. Target India's Jal Jeevan Mission rural distribution networks with bronze rising stem designs through established local service partnerships. Factory-tested smart positioner integration offers the most penetrable go-to-market angle against legacy DCS integration friction. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale fabricators with NACE certification but without captive alloy casting, positioned for backward integration premiums. Long-term viability hinges on materials science capabilities in embrittlement-resistant alloys as hydrogen infrastructure scales. Watch ASME III N-stamp approval velocity as the signal separating consolidatable suppliers from stranded capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Casting | Captive ASTM A217 WC9 capacity insulates Flowserve against nickel volatility and German foundry bottlenecks. |
| API 622 Certification Investment | Low-emission packing qualification opens EPA NSPS-driven replacement cycles at US Midwest coal and gas plants. |
| Smart Positioner Platform Convergence | HART-enabled predictive diagnostics create recurring aftermarket revenue beyond Emerson's hardware margins. |
| Hydrogen Service Qualification | ISO 19880-3 certification positions Baker Hughes for high-pressure embrittlement-resistant valve demand. |
| Factory-Tested Valve-Actuator Bundling | Integrated packages reduce field commissioning risk for Bechtel and McDermott at LNG export terminals. |
Research Methodology
Bottom-up power generation and petrochemical modeling reconciled against top-down foundry capacity tracking forms the analytical core. Primary interviews with plant maintenance directors, EPC procurement leads, valve OEM technical directors, and aftermarket service heads combined with secondary validation from EPA enforcement databases, FERC pipeline safety advisories, API certification registries, and customs alloy casting trade data. Triangulation across stakeholder inputs and documentary sources anchors volume estimates.
Input-output matrices map alloy steel consumption by ANSI pressure class against end-use replacement cycles across the projection horizon. Segmentation dimensions span bonnet design type, material certification tier, actuator integration level, and regional regulatory enforcement intensity. CAGRs derive from installed base aging curves and compliance-driven upgrade scheduling. Nuclear N-stamp approval timelines and REACH fluorinated polymer restrictions constitute industry-specific forecast inputs.
Inputs from API certification registries and SAMR domestic content filings were available through the study window; gaps in real-time foundry utilization rates introduce uncertainty bands around capacity-constrained scenarios. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and alloy price normalization. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Sandblast Valves Market
Valves
Global Fluid Management Systems Market
Valves
North America Butterfly Valve Market
Valves
Air Heated Vaporizer Market
Valves
Railway Emergency Valves Market
Valves
Valve Manifold Box (VMB) Market
Valves
Off-Highway Hydraulic Valve Actuator Systems Market
Valves
Actuators and Valves Market
Valves
Electro Pneumatic Positioner Market
Valves
Industrial Valves Market
Valves
US Water & Wastewater Valves Market
Valves
Hybrid Valve Market
Valves
Air Jet Ejectors Market
Valves
Liner Regulators Market
Valves
Choke Valves Market
Valves
Pipeline Pigging Equipment Market