
 Netherlands Wind Energy Market | 2026-2036
Netherlands Wind Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Netherlands Wind Energy Market Foresight
The divergence between premium offshore installations and commodity onshore turbines is hardening across Dutch procurement channels. Siemens Gamesa Renewable Energy SA dominates the offshore nacelle segment through its direct-drive permanent magnet platform. Ørsted A/S anchors project development pipelines across the Hollandse Kust licensing zones with integrated construction management. Vestas Wind Systems A/S competes aggressively on onshore repowering contracts where blade recycling economics determine bid viability.
Wind energy in the Netherlands encompasses the kinetic-to-electrical conversion systems deployed across North Sea maritime zones and coastal lowlands, with offshore platforms now routinely exceeding 15 MW per turbine unit and foundation depths surpassing 50 meters to exploit stronger, steadier air streams. The technology serves baseload displacement for Dutch industrial clusters and hydrogen electrolysis feedstock supply. Offshore wind leads capital deployment given seabed lease scarcity and grid connection priority rights, while distributed generation applications remain constrained by land-use planning restrictions in densely populated provinces. Utility-scale installations command the dominant share of annual capacity additions, though hybrid systems pairing turbines with battery storage or electrolyzers represent the fastest-growing configuration as grid balancing requirements intensify.
The Dutch Enterprise Agency (RVO) administers offshore subsidy tenders through the SDE++ scheme, while the Netherlands Authority for Consumers and Markets (ACM) regulates grid access tariffs and connection queue prioritization. EU Green Deal targets and the Dutch Klimaatakkoord mandate 21 GW offshore capacity by 2030, forcing developers to accelerate supply chain localization or face penalty exposure. Stakeholders must monitor seabed lease auction timing against turbine installation vessel availability to avoid capital commitment mismatches.
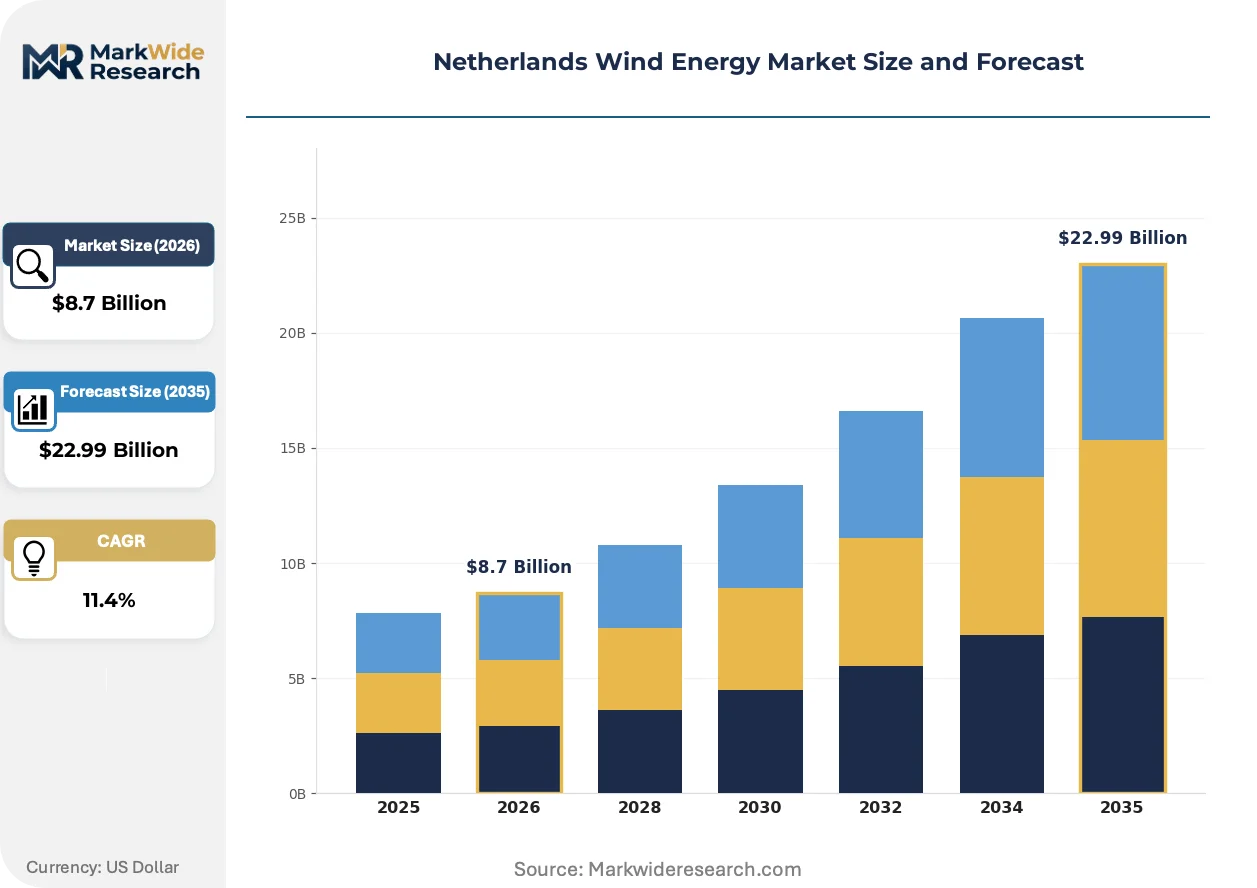
Market Dynamics
Seabed lease scarcity in the Dutch North Sea is compressing project timelines and forcing developers to secure turbine installation vessel contracts before final investment decisions, creating capital commitment mismatches that favor balance-sheet-heavy operators.
Growth Catalysts
- SDE++ subsidy tenders:The Dutch Enterprise Agency allocates competitive offshore support payments that de-risk early-phase development capital and accelerate construction starts in the Hollandse Kust zones.
- Industrial hydrogen electrolysis:Dutch chemical clusters in Rotterdam and Zeeland are contracting dedicated offshore wind capacity to power green hydrogen production, creating anchor demand for baseload power purchase agreements.
- IJmuiden-Ver zone leasing:New seabed allocations at greater distances from shore unlock higher-capacity factor resources and justify 15+ MW turbine deployments with dedicated grid infrastructure.
Market Restraints
- Specialized vessel shortage:The global fleet of turbine installation vessels capable of handling next-generation nacelle weights remains concentrated among three European operators, creating queue bottlenecks.
- Copper and rare earth price volatility:Permanent magnet generators depend on neodymium-dysprosium supply chains dominated by Chinese processing capacity, exposing direct-drive platforms to input cost swings.
- Grid connection queue prioritization:Netherlands Authority for Consumers and Markets tariff structures favor early queue entrants, disadvantaging late-stage developers in Hollandse Kust West.
Strategic Opportunities
- Zeeland onshore repowering:Aging 2-3 MW turbines in southwestern provinces face end-of-life decisions, creating retrofit demand for larger rotor diameters within existing permitting envelopes.
- Battery-wind hybrid configurations:Grid balancing requirements from TenneT are incentivizing co-located storage that captures price arbitrage and reduces curtailment penalties.
- Klimaatakkoord localization mandates:Domestic content requirements for foundation fabrication and cable manufacturing are creating captive supply opportunities for Dutch port infrastructure.
Industry Challenges
- Offshore commissioning technician scarcity:High-voltage electrical specialists and marine coordination personnel command premium wages, extending project handover timelines.
- Blade recycling infrastructure gaps:Thermoset composite disposal regulations under EU Waste Framework Directive implementation lack scaled processing capacity, raising end-of-life liability costs.
- Foundation geotechnical survey delays:Seabed characterization campaigns at IJmuiden-Ver depths exceed 50 meters, requiring extended vessel charters that compress installation weather windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Netherlands Wind Energy Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Onshore Wind, Offshore Wind, Vertical Axis Wind, Horizontal Axis Wind Application: Utility-Scale, Distributed Generation, Hybrid Systems, Community Projects End User: Energy Producers, Government, Commercial Users, Residential Consumers Installation: New Projects, Retrofitting, Upgrades, Maintenance Services |
| Companies Covered | Enercon GmbH, Siemens Gamesa Renewable Energy SA, General Electric Company, Lagerwey Wind BV, Ørsted A/S, Vattenfall AB, RWE AG, Eneco, Vestas Wind Systems A/S, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Netherlands Wind Energy Market Shifts & Advancements
Turbine scale escalation and system hybridization are restructuring competitive requirements across Dutch offshore development, with technology choices now locking in decades of operational economics.
Direct-drive permanent magnet generators are absorbing the mechanical complexity eliminated from geared drivetrains, reducing offshore maintenance intervals and enabling remote monitoring architectures. Dutch project developers favor these platforms for Hollandse Kust installations where helicopter access costs dominate operational expenditure models. The technology is absorbing service contract premiums that previously flowed to gearbox overhaul specialists.
The EU Green Deal's 21 GW offshore mandate for 2030 is compressing Dutch permitting timelines through coordinated environmental assessment procedures that batch multiple zone approvals. This regulatory acceleration is displacing sequential project-by-project approval cycles that previously stretched to 48 months. Hollandse Kust Noord and West projects are responding with standardized foundation designs that streamline manufacturing and installation sequencing.
Corporate power purchase agreements are displacing traditional utility offtake structures as Dutch industrial clusters seek direct renewable supply contracts with additionality guarantees. Chemical and data center operators in Rotterdam and Amsterdam are contracting dedicated offshore capacity, bypassing wholesale market exposure. This procurement evolution is most visible in the IJmuiden-Ver zone where dedicated grid connections enable physical delivery matching.
Netherlands Wind Energy Market Segmentation
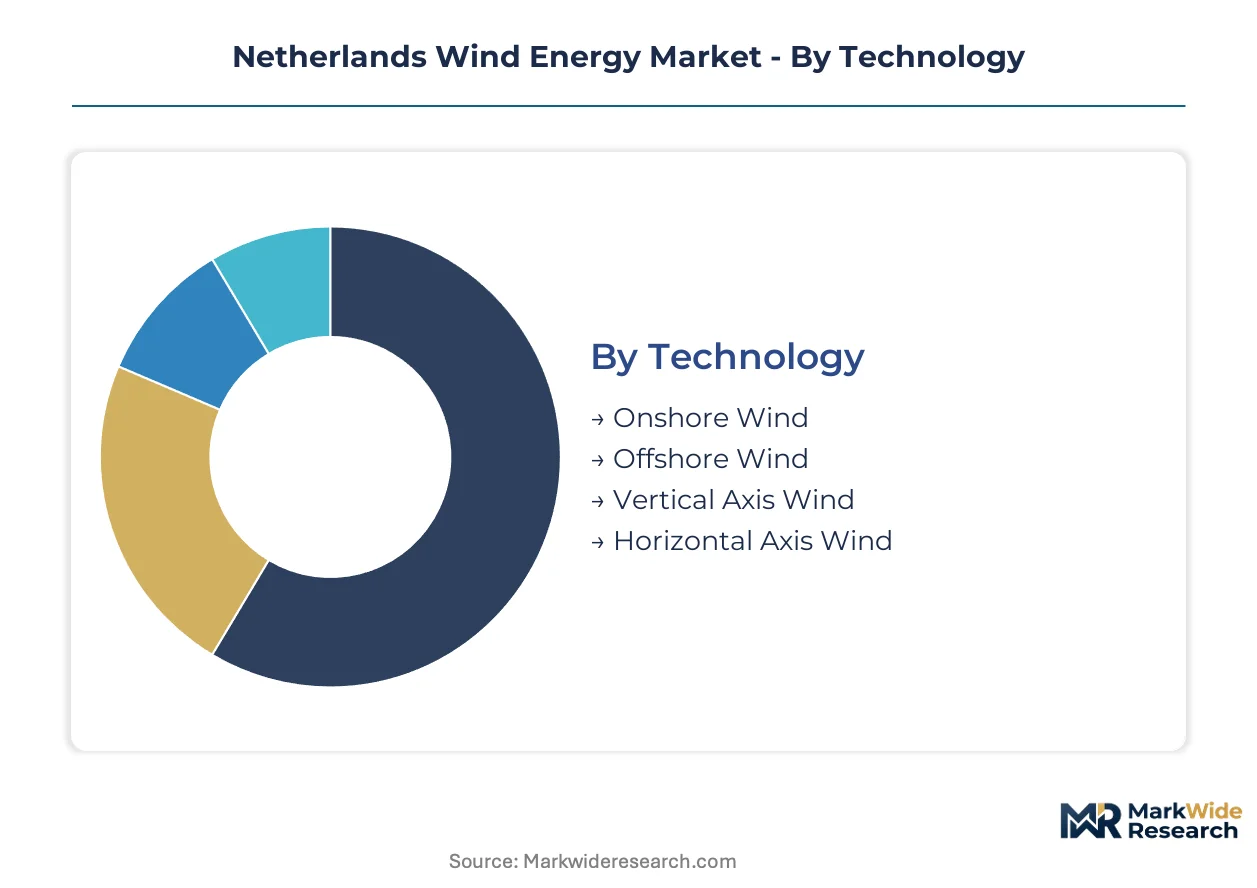
Dutch wind procurement channels diverge sharply between capital-intensive offshore platforms and distributed onshore installations, with technology choice locking in decades of operational economics and grid access rights. Segmentation reveals how foundation depth, rotor scale, and connection priority determine developer returns across the North Sea and coastal provinces.
Technology:
Foundation engineering costs and seabed lease scarcity drive technology selection, with water depth and distance-to-shore dictating drivetrain architecture and turbine scale.
- Offshore Wind:Fixed-bottom and floating platforms in the Hollandse Kust and IJmuiden-Ver zones deploy turbines exceeding 15 MW with direct-drive permanent magnet generators. Rotterdam chemical clusters and hydrogen electrolysis facilities anchor power purchase agreements here, drawn by baseload reliability and dedicated grid connections.
- Onshore Wind:Horizontal-axis turbines dominate Zeeland and northern provinces, where repowering of aging 2-3 MW units with larger rotors fits within existing permitting envelopes. Land-use planning restrictions in densely populated Randstad provinces constrain greenfield expansion, concentrating retrofit demand in southwestern corridors.
- Horizontal Axis Wind:The prevailing rotor architecture across both offshore and onshore installations, optimized for Dutch wind shear profiles through variable pitch control and advanced blade aerodynamics.
- Vertical Axis Wind:Niche urban and distributed applications in port industrial zones, where omni-directional capture suits turbulent wind regimes near container terminals and logistics facilities.
Offshore Wind leads on scale; Hybrid Systems leads on momentum.
Application:
Grid balancing requirements from TenneT and corporate procurement mandates are restructuring how capacity reaches offtakers, bypassing traditional utility intermediation.
- Utility-Scale:Grid-connected arrays exceeding 100 MW dominate annual capacity additions, with Hollandse Kust West and Noord projects securing SDE++ subsidy tenders through the Dutch Enterprise Agency. These installations command priority connection queue positions and long-term power purchase agreements with industrial clusters.
- Hybrid Systems:Co-located battery storage and electrolyzer pairings represent the steepest expansion trajectory, capturing price arbitrage and supplying green hydrogen feedstock to Rotterdam and Zeeland chemical plants. TenneT balancing requirements incentivize this configuration as curtailment penalties intensify.
- Distributed Generation:Behind-the-meter installations for commercial campuses and port facilities, constrained by local grid capacity and municipal planning approvals in dense provinces.
- Community Projects:Municipality-led cooperatives in rural northern provinces, leveraging simplified permitting for turbines under 5 MW with local ownership structures.
Utility-Scale commands capital deployment; Hybrid Systems gains share fastest.
End User:
Procurement authority concentrates with balance-sheet-heavy entities capable of absorbing long-dated construction risk and seabed lease commitments.
- Energy Producers:Ørsted and integrated utilities anchor project development pipelines, leveraging construction management capabilities and turbine installation vessel contracts to secure Hollandse Kust licensing zones. These developers bear capital commitment mismatches between vessel charter and final investment decision timelines.
- Commercial Users:Data center operators in Amsterdam and chemical processors in Rotterdam are contracting dedicated offshore capacity with additionality guarantees, bypassing wholesale market exposure through corporate power purchase agreements.
- Government:The Dutch Enterprise Agency administers SDE++ tenders and RVO subsidy allocations, while provincial authorities enforce Klimaatakkoord localization mandates for foundation fabrication.
- Residential Consumers:Limited direct procurement through community cooperative structures, with most supply intermediated by retail energy providers.
Energy Producers lead on scale; Commercial Users lead on momentum.
Installation:
Vessel availability and geotechnical survey timelines compress project execution windows, favoring contractors with integrated marine logistics capabilities.
- New Projects:Greenfield developments at IJmuiden-Ver depths exceeding 50 meters require extended seabed characterization campaigns and specialized jack-up vessels. Foundation fabrication lead times and cable manufacturing capacity constrain construction sequencing.
- Retrofitting:Blade replacement and nacelle upgrades on aging onshore turbines in Zeeland and northern provinces, extending asset life within existing environmental permits.
- Upgrades:Control system modernization and rotor diameter extensions for mid-life offshore platforms, improving capacity factors without foundation replacement.
- Maintenance Services:Helicopter-accessible offshore platforms and onshore technician networks, with high-voltage electrical specialists commanding premium wages that extend handover timelines.
New Projects lead on scale; Maintenance Services leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Marine engineering specialists and offshore construction crews cluster around Rotterdam and IJmuiden ports, anchoring the Netherlands' position in North Sea wind development. This workforce concentration draws turbine manufacturers and foundation fabricators to Dutch coastal zones.
Germany
North Sea port cities Bremerhaven and Cuxhaven host turbine component factories serving Dutch offshore zones. The German Federal Maritime and Hydrographic Agency coordinates cross-border cable routing with TenneT. Industrial clusters along the Lower Saxony coast manufacture transition pieces for Hollandse Kust installations.
United Kingdom
Norfolk and Humberside ports supply installation vessels and crew transfer fleets to Dutch wind zones. The UK Offshore Petroleum Regulator for Environment and Decommissioning shares seabed survey protocols with Dutch authorities. Grimsby marine logistics firms charter jack-up units for IJmuiden-Ver foundation campaigns.
Denmark
Copenhagen-headquartered developers pioneered North Sea offshore construction methodologies now applied in Dutch waters. The Danish Energy Agency's tender design influenced the SDE++ auction structure administered by RVO. Esbjerg port infrastructure serves as a staging hub for rotor blade transport to Hollandse Kust West.
Belgium
Ostend and Zeebrugge ports fabricate monopile foundations for Dutch zone installations. The Belgian federal energy administration coordinates grid synchronization with TenneT's North Sea corridor planning. Flemish steel processors supply secondary steel for transition piece manufacturing bound for IJmuiden-Ver.
Netherlands Wind Energy Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the offshore wind value chain. Balance-sheet strength determines access to turbine installation vessel charters and seabed lease commitments. Three archetypes dominate: integrated energy majors with construction management capabilities, pure-play developers relying on project finance, and turbine OEMs capturing service contract premiums. Consolidation pressure intensifies through vessel scarcity and foundation fabrication bottlenecks.
Among Danish-origin integrated developers, Ørsted A/S anchors the project development archetype through construction management capabilities. Siemens Gamesa Renewable Energy SA occupies the turbine supply tier with direct-drive platform specialization. Vestas Wind Systems A/S exemplifies the onshore repowering specialist position within Dutch retrofit markets.
| Leading Market Players |
|---|
| Enercon GmbH |
| Siemens Gamesa Renewable Energy SA |
| General Electric Company |
| Lagerwey Wind BV |
| Ørsted A/S |
| Vattenfall AB |
| RWE AG |
| Eneco |
| Vestas Wind Systems A/S |
| Others |
Supply & Pricing Matrix
Integrated energy producers with construction management capabilities command the dominant pricing model through bundled full-scope contracts that wrap turbine supply, installation, and long-term service agreements into single-source arrangements. This buyer concentration forces component suppliers to absorb price risk through fixed-price EPC commitments while competing for vessel charter slots.
Pricing Analysis
Full-scope bundled contracts dominate premium offshore segments while unbundled component procurement persists in onshore repowering markets. Price differentiation rests on foundation depth certification tiers and grid connection priority queue position, with IJmuiden-Ver zone projects commanding premiums over Hollandse Kust West. Cost compression in onshore retrofits is intensifying because blade recycling economics determine bid viability. Municipal cooperatives exhibit highest price sensitivity; Rotterdam chemical clusters show lowest sensitivity due to hydrogen electrolysis feedstock requirements.
Supply Chain Analysis
Reverse-logistics flows for end-of-life blade disposal and nacelle refurbishment are creating secondary material markets that reshape procurement economics. Supply concentrates in Denmark, Germany, and China for drivetrain components and rare earth processing. Raw material dependencies include neodymium-dysprosium permanent magnets, copper power cables, and specialized marine steel grades. Single-source vulnerability in turbine installation vessel availability presents structural risk. Distribution runs through Rotterdam and IJmuiden port infrastructure with TenneT grid synchronization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Netherlands wind energy market offers margin expansion through direct-drive platform standardization and service contract premiums that capture decades of operational expenditure. Foundation fabrication localization under Klimaatakkoord mandates creates captive supply advantages for integrated operators.
For Market Incumbents: Lock in vessel charter commitments before seabed lease auction timing to eliminate capital commitment mismatches. Secure long-term service contracts on direct-drive permanent magnet platforms to absorb maintenance premiums previously flowing to gearbox overhaul specialists. Counter emerging pure-play developers by controlling turbine installation vessel availability through exclusive operator agreements. For New Entrants and Emerging Players: Zeeland onshore repowering cooperatives represent an underserved buyer archetype with simplified permitting pathways and local ownership structures. Target battery-wind hybrid configurations for Rotterdam chemical clusters seeking price arbitrage and curtailment penalty reduction. Enter through control system modernization partnerships that extend mid-life offshore asset capacity factors without foundation replacement. For Investors and Strategic Acquirers: Integrated European utilities with construction management capabilities are the most active acquirer in this space, consolidating project development pipelines to secure Hollandse Kust licensing zones. Long-term viability centers on balance-sheet strength to absorb vessel scarcity and geotechnical survey delays. Monitor TenneT grid connection queue prioritization announcements as inflection indicators for developer returns.| Strategic Initiative | Industry Significance |
|---|---|
| Vessel Charter Pre-Commitment | Secures installation capacity before SDE++ tender outcomes determine project viability. |
| Direct-Drive Platform Specialization | Reduces offshore maintenance intervals and enables remote monitoring architectures for Hollandse Kust. |
| Foundation Fabrication Localization | Captures Klimaatakkoord domestic content requirements through Rotterdam port infrastructure investment. |
| Battery-Wind Hybrid Deployment | Captures TenneT price arbitrage opportunities and supplies green hydrogen feedstock to chemical clusters. |
| Blade Recycling Infrastructure Buildout | Addresses EU Waste Framework Directive compliance gaps and reduces end-of-life liability costs. |
Research Methodology
Direct dialogue with offshore project developers, turbine OEM procurement directors, TenneT grid planning officers, and Rotterdam port logistics managers grounded the qualitative assessment. Secondary validation drew from RVO SDE++ tender documentation, ACM tariff rulings, EU Green Deal implementation reports, and North Sea seabed lease auction records. Bottom-up project pipeline analysis triangulated with top-down capacity target modeling.
Bottom-up segmentation analysis across technology, application, end user, and installation type dimensions combined with top-down regulatory mandate tracking across the analysis window. CAGRs were derived from capacity addition trajectories against Klimaatakkoord 21 GW offshore targets. Forecast inputs incorporated turbine installation vessel fleet availability curves and geotechnical survey campaign timelines.
Inputs from RVO tender databases and TenneT grid connection queues were available through the study window; gaps in vessel charter rate transparency introduce uncertainty bands around project cost assumptions. Forecasts reflect documented assumptions on seabed lease auction timing and foundation fabrication lead times. Practitioners should monitor ACM queue prioritization rulings and rare earth price indices for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Wind Turbine Lenses Market
Wind Energy Systems
Belgium Wind Energy Market
Wind Energy Systems
Wind Turbine Pitch System Sales Market
Wind Energy Systems
New Zealand Wind Energy Market
Wind Energy Systems
Wind Energy Foundation Market
Wind Energy Systems
Wind Turbine Scrap Market
Wind Energy Systems
Thailand Wind Energy Market
Wind Energy Systems
Wind Turbine Pitch Systems Market
Wind Energy Systems
India Wind Energy Market
Wind Energy Systems
Multi-Rotor Wind Turbine Market
Wind Energy Systems
Wind Electric Power Generation Market
Wind Energy Systems
United Kingdom Wind Energy Market
Wind Energy Systems
Wind Tower Market
Wind Energy Systems
Vertical Axis Wind Turbine Market
Wind Energy Systems
Floating Wind Turbine Market
Wind Energy Systems
Europe Wind Power Market