
 Carbon Seal Rings Market | 2026-2036
Carbon Seal Rings Market Size, Share, and Industry Trends Forecast 2026-2036
Carbon Seal Rings Market Outlook
API-standard and aerospace-grade specification tiers is redrawing competitive boundaries in carbon seal rings. Trelleborg leverages its polymer compounding depth to dominate high-temperature rotary applications. John Crane anchors its position through backward integration into graphite substrate production. EagleBurgmann differentiates via specialized service networks in oil and gas field operations.
Carbon seal rings are precision-machined components manufactured from graphite, carbon fiber, or PTFE composites, engineered to maintain fluid containment across pressure differentials exceeding 200 bar in rotating equipment. Their primary purpose is to prevent leakage of process fluids in pumps, compressors, and turbine engines while tolerating thermal cycling and chemical exposure. Mechanical seal rings command the deepest margin pools due to replacement frequency in continuous-process industries. Rotary seal rings represent the fastest-growing product type as OEMs specify longer service intervals in aerospace propulsion systems. PTFE-based formulations are displacing traditional graphite in hydraulic systems where chemical compatibility requirements have tightened.
EPA emissions enforcement and FAA airworthiness directives jointly elevate material traceability requirements for carbon seal rings sold into U.S. markets. REACH substance restrictions in Europe constrain certain graphite impregnation chemistries, redirecting formulation investment toward certified carbon fiber prepregs. The EU Green Deal carbon border adjustments will add compliance layers for imported seal rings from non-EU manufacturing bases. Stakeholders must monitor divergence between EPA and ECHA substance lists to avoid stranded inventory positions.
Market Dynamics
Specification intensity for mechanical seal rings in Germany's precision engineering clusters is forcing material traceability upgrades across the entire supply base, compressing lead times for certified carbon fiber prepregs.
Growth Catalysts
- FAA airworthiness directives:Aerospace OEMs in the United States are mandating material certification upgrades for turbine engine seal rings, accelerating specification tier migrations.
- REACH substance restrictions:ECHA constraints on graphite impregnation chemistries are redirecting European formulation investment toward certified carbon fiber prepregs with full supply chain documentation.
- Rotary seal ring demand:OEM specifications for extended service intervals in aerospace propulsion systems are pulling volume toward PTFE-composite formulations.
Market Restraints
- Graphite substrate concentration:Backward integration into specialty graphite production anchors competitive position, locking out mid-scale processors lacking captive supply.
- EU Green Deal carbon border adjustments:Compliance layering for imported seal rings from non-EU manufacturing bases adds landed cost penalties and documentation burden.
- PTFE chemical compatibility limits:Hydraulic system operators face formulation switching costs where traditional graphite seals still outperform fluoropolymer alternatives in extreme pressure cycling.
Strategic Opportunities
- EPA-ECHA regulatory divergence:Stakeholders monitoring substance list misalignment can capture stranded inventory arbitrage positions in cross-border distribution.
- Service network specialization:Oil and gas field operations require localized technical support for high-temperature rotary applications, creating channel differentiation potential.
- Continuous-process replacement cycles:Mechanical seal ring replacement frequency in chemical processing plants generates recurring revenue pools for specification-compliant suppliers.
Industry Challenges
- Material certification timelines:EPA emissions enforcement and FAA directives jointly extend qualification periods for new carbon seal ring formulations, delaying revenue recognition.
- Polymer compounding expertise scarcity:High-temperature rotary applications require specialized formulation knowledge concentrated among limited technical personnel pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbon Seal Rings Market |
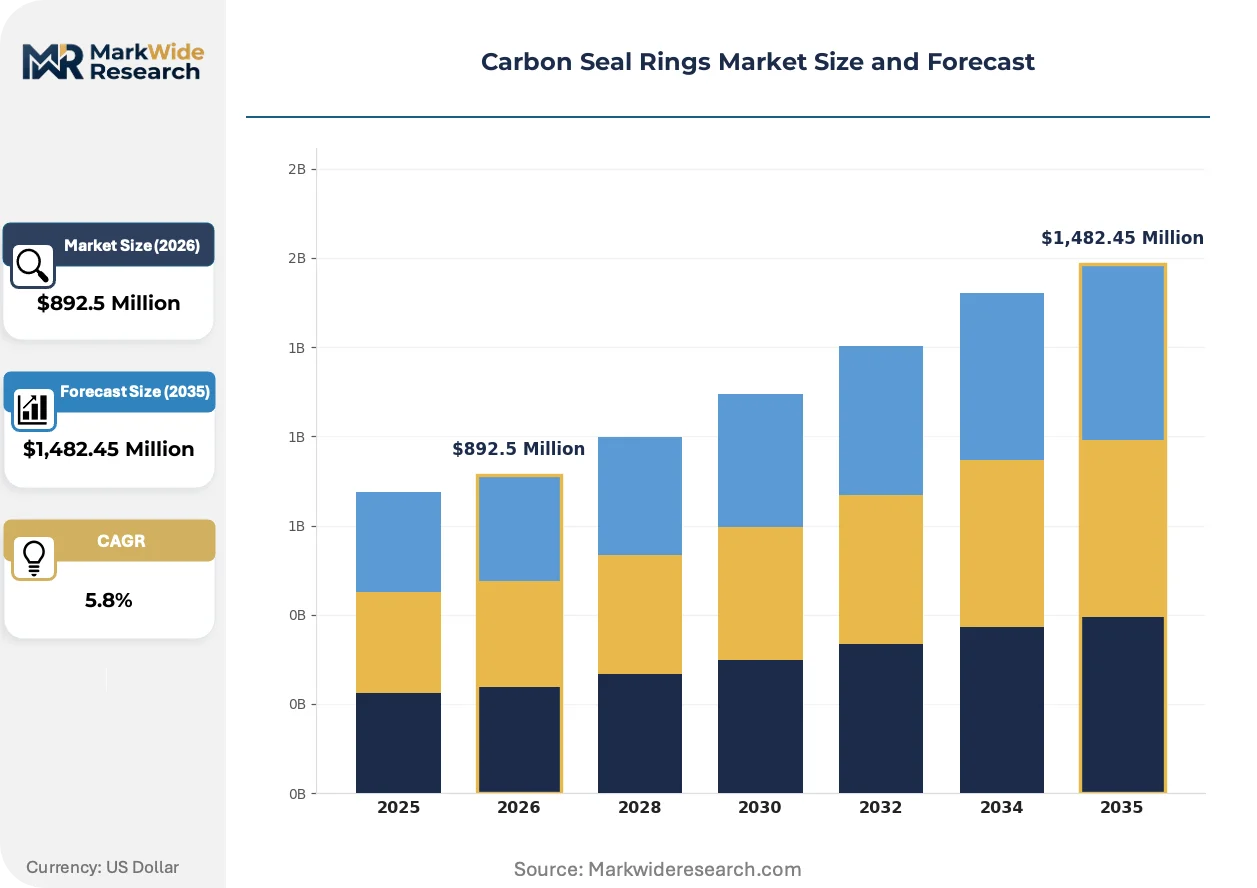
| Market Size in 2026 | $892.5 Million |
| Market Size in 2035 | $1,482.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rotary Seal Rings, Gasket Seal Rings, Mechanical Seal Rings, O-Rings Industry Vertical: Aerospace, Oil & Gas, Automotive, Industrial Machinery Material Type: Carbon Fiber, Graphite, PTFE, Silicone Application: Hydraulic Systems, Fluid Transfer, Engine Components, Pump Sealing |
| Companies Covered | Trelleborg, Parker Hannifin, John Crane, Freudenberg Group, A.W. Chesterton Company, EagleBurgmann, SKF, James Walker & Co., Garlock, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbon Seal Rings Market Strategic Shifts
Active reshaping in carbon seal rings centers on specification tier consolidation, regulatory compliance automation, and procurement model compression toward direct OEM relationships.
Carbon fiber-reinforced PTFE composite formulations are supplanting traditional graphite in hydraulic system applications where chemical compatibility requirements have tightened beyond legacy material limits. Aerospace propulsion OEMs are specifying these formulations for extended service intervals, compressing competitive position for suppliers lacking polymer compounding depth. The structural consequence is tiered market access where API-standard and aerospace-grade specifications redraw competitive boundaries.
EPA emissions enforcement in the United States is elevating material traceability requirements for carbon seal rings sold into turbine engine and industrial machinery applications. Manufacturers must now document substrate origin and impregnation chemistry through entire supply chains to maintain market access. Aerospace-grade specification tiers face the steepest compliance burden, with FAA airworthiness directives layering additional certification requirements atop environmental rules.
After-sales service unbundling is fragmenting traditional distribution relationships in oil and gas field operations. Specialized technical support networks are displacing generalist distributors for high-temperature rotary seal applications, particularly in North American shale basins where equipment uptime premiums justify premium pricing. This channel shift concentrates margin capture with formulation-integrated suppliers capable of field-level engineering support.
Carbon Seal Rings Market Segmentation
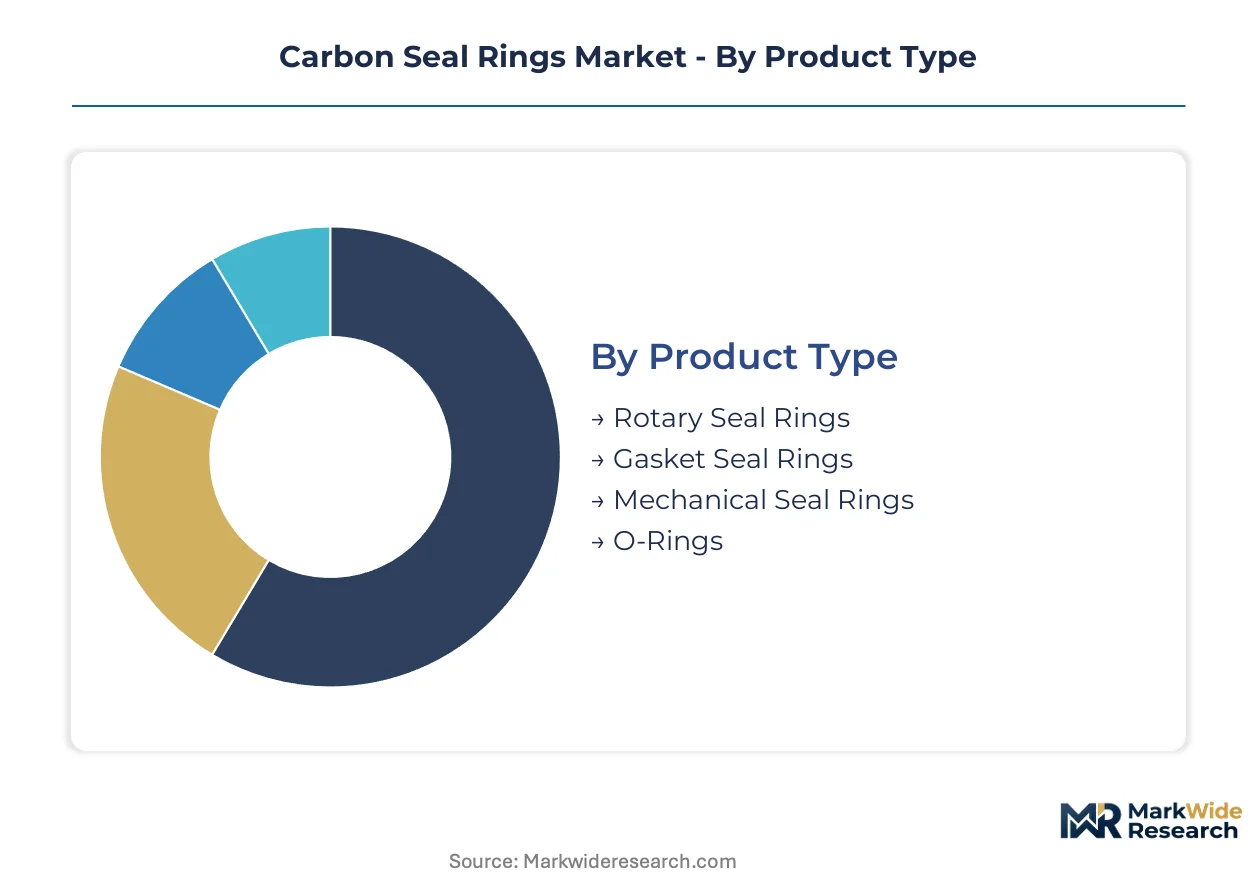
Carbon seal ring procurement splits across specification tiers that determine material certification burden and margin capture. Aerospace-grade and API-standard tiers enforce divergent traceability requirements that reshape supplier economics across each segment category.
Product Type:
EPA emissions enforcement and FAA airworthiness directives impose distinct material documentation requirements on each product configuration, compressing qualification timelines for rotary and mechanical variants sold into U.S. markets.
- Rotary Seal Rings:PTFE-composite formulations engineered for extended service intervals in turbine engines face the steepest FAA certification burden. Aerospace OEMs in the United States are pulling procurement toward these specifications as propulsion system maintenance cycles lengthen.
- Mechanical Seal Rings:Graphite and carbon fiber composites dominate continuous-process industries where replacement frequency generates recurring revenue. Germany's precision engineering clusters enforce the tightest material traceability standards for these components.
- Gasket Seal Rings:Static sealing applications in industrial machinery tolerate broader material specifications with reduced compliance overhead.
- O-Rings:Standardized geometries face commoditization pressure except where REACH substance restrictions on impregnation chemistries force formulation upgrades.
Mechanical seal rings handle the majority of throughput; rotary seal rings are the fastest mover on share.
Industry Vertical:
Customer procurement models range from direct OEM relationships in aerospace to service-network-dependent purchasing in oil and gas field operations.
- Aerospace:Turbine engine manufacturers mandate material certification upgrades that compress supplier qualification timelines. FAA directives layer atop EPA emissions rules to create the steepest compliance burden of any vertical.
- Oil & Gas:North American shale basins generate demand for high-temperature rotary seals supported by localized technical service networks. Field-level engineering support commands premium pricing in this vertical.
- Automotive:Emissions system sealing faces tightening material compatibility requirements as hydraulic fluid chemistries evolve.
- Industrial Machinery:Continuous-process chemical plants drive replacement-cycle revenue for specification-compliant mechanical seal suppliers.
Oil and gas concentrates procurement spend; aerospace is expanding most quickly on specification intensity.
Material Type:
REACH substance restrictions and EPA emissions enforcement jointly redirect formulation investment away from legacy graphite impregnation chemistries toward certified alternatives.
- PTFE:Carbon fiber-reinforced fluoropolymer composites displace traditional graphite in hydraulic systems where chemical compatibility requirements have tightened beyond legacy limits. Aerospace propulsion OEMs specify these formulations for extended service intervals.
- Carbon Fiber:Certified prepregs with full supply chain documentation command premium positioning as ECHA constraints on graphite impregnation redirect European investment. German precision engineering clusters drive specification intensity for fully traceable carbon fiber substrates.
- Graphite:Specialty substrate production anchors competitive position for backward-integrated suppliers; mid-scale processors lacking captive supply face lockout.
- Silicone:Lower-specification applications in automotive and general industrial machinery tolerate reduced material traceability requirements.
Graphite retains volume leadership; carbon fiber is climbing the fastest on regulatory-driven substitution.
Application:
Pressure differential requirements and thermal cycling exposure determine material selection and certification tier across each use case.
- Hydraulic Systems:Chemical compatibility requirements in industrial machinery have tightened beyond legacy graphite limits. PTFE-composite formulations are capturing specification share as hydraulic fluid chemistries evolve.
- Engine Components:Turbine sealing applications face joint EPA-FAA material traceability mandates that extend qualification periods for new formulations. Aerospace OEMs in the United States concentrate demand for aerospace-grade specification tiers.
- Fluid Transfer:Pump and pipeline sealing in oil and gas operations requires localized technical support for high-temperature rotary applications.
- Pump Sealing:Continuous-process chemical processing plants generate recurring replacement demand for mechanical seal rings with documented substrate origin.
Pump sealing handles the majority of unit volume; engine components command the steepest expansion trajectory on specification tier migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in carbon seal rings tilt toward surplus positions in Germany and the United States, while Asian manufacturing bases absorb raw graphite substrate imports. Trade documentation burdens under divergent EPA and ECHA substance lists create arbitrage opportunities in cross-border distribution channels.
United States
Aerospace OEMs in Connecticut and Ohio drive specification intensity for turbine engine seal rings. FAA airworthiness directives layer atop EPA emissions enforcement to create the steepest compliance burden globally. Houston's oil and gas equipment cluster demands localized technical support for high-temperature rotary applications.
Germany
Precision engineering clusters in Stuttgart and Munich enforce material traceability standards that compress lead times for certified carbon fiber prepregs. REACH substance restrictions redirect formulation investment away from legacy graphite impregnation chemistries. The country's national industrial regulator maintains strict documentation requirements for mechanical seal rings in continuous-process industries.
China
Domestic aerospace propulsion programs in Xi'an and Chengdu pull procurement toward extended-service-interval formulations. The country's national standards administration enforces dual carbon goals that reshape material sourcing for industrial machinery seals. Yangtze River Delta manufacturing bases face EU Green Deal carbon border adjustment compliance layering on exports.
Japan
Automotive hydraulic system manufacturers in Aichi Prefecture specify PTFE-composite formulations as fluid chemistries evolve beyond legacy graphite limits. The country's ministry of economy and trade oversees certification alignment with international aerospace standards. Osaka-based industrial machinery clusters concentrate demand for mechanical seal ring replacements.
India
Chemical processing plants in Gujarat and Maharashtra generate recurring replacement demand for specification-compliant mechanical seal rings. The country's national standards body enforces phased compliance schedules for industrial emissions equipment. Bangalore's emerging aerospace component sector imports certified carbon fiber prepregs for turbine engine applications.
Carbon Seal Rings Market Competitive Environment
Listed leaders compete with private specialists across specification tier access, creating a bifurcated structure where scale advantages clash with formulation agility. The vendor base concentrates around three strategic archetypes: polymer compounding specialists with aerospace certification depth, backward-integrated graphite substrate producers, and field-service-integrated oil and gas operators. Dominant competitive moves include capacity expansion in certified carbon fiber prepreg production and strategic partnerships for localized technical support networks.
Among European-based specialists, Trelleborg and EagleBurgmann occupy positions within the polymer compounding and field-service archetypes respectively. John Crane anchors the backward-integrated tier through captive graphite substrate production. These three exemplify how competitive positioning in carbon seal rings depends on control over either formulation expertise, raw material supply, or channel proximity to demanding end-use applications.
| Leading Market Players |
|---|
| Trelleborg |
| Parker Hannifin |
| John Crane |
| Freudenberg Group |
| A.W. Chesterton Company |
| EagleBurgmann |
| SKF |
| James Walker & Co. |
| Garlock |
| Others |
Value Chain & Pricing Dynamics
FAA airworthiness directives and EPA emissions enforcement jointly gate both supply qualification and price differentiation in carbon seal rings, compressing margin capture for uncertified suppliers while amplifying premium positioning for formulation-integrated incumbents with full traceability documentation.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in carbon seal rings. Aerospace-grade certification tiers command substantial premiums over API-standard specifications due to FAA-mandated material documentation burdens. Cost compression in standard-grade mechanical seal rings is intensifying because REACH substance restrictions force formulation switching for European chemical processing buyers. Price-sensitive procurement concentrates in gasket seal rings and O-rings where traceability requirements remain minimal, while least price-sensitive demand clusters in aerospace propulsion systems where equipment uptime premiums justify specification premiums.
Supply Chain Analysis
Extended lead times for certified carbon fiber prepregs now stretch across German precision engineering clusters, compressing just-in-sequence delivery windows for mechanical seal ring manufacturers. Supply concentration centers on China for specialty graphite substrates, Germany for precision-machined components, and the United States for aerospace-grade formulation integration. Raw material dependencies draw from synthetic graphite feedstock, carbon fiber tow imports, and fluoropolymer resin supply. Single-source vulnerability in aerospace-certified prepreg supply creates structural risk for tier-two processors. Distribution runs through direct OEM relationships in aerospace and specialized technical service networks in oil and gas field operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among aerospace OEMs and precision engineering clusters in Germany, fragmenting procurement leverage for mid-scale seal ring processors and compressing margin capture for specification-noncompliant suppliers.
For Market Incumbents: Fortify backward integration into captive graphite substrate production to lock out mid-scale competitors lacking raw material control. Deepen polymer compounding expertise pools for high-temperature rotary applications where technical personnel scarcity constrains rival expansion. Aerospace OEM consolidation around extended service interval specifications threatens suppliers lacking formulation agility; certification investment in FAA-compliant traceability systems anchors premium tier access. For New Entrants and Emerging Players: EASA-FAA dual certification fast-tracks unlock aerospace-grade specification tiers where incumbent concentration remains incomplete. White-space targets include localized technical service networks in North American shale basins and certified carbon fiber prepreg supply for India's emerging aerospace component sector. The most penetrable segment is gasket seal rings in general industrial machinery where traceability burdens remain minimal; a field-engineering partnership model with oil and gas equipment distributors accelerates channel access. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across aerospace-grade specification tiers as FAA documentation requirements extend qualification timelines and elevate working capital needs. Long-term viability over the coming decade rests on control over either formulation expertise, captive raw material supply, or proximity to demanding end-use applications through technical service networks. Acquisition target archetype: polymer compounding specialists with aerospace certification depth and underutilized capacity in certified carbon fiber prepreg production. The signal to watch is divergence between EPA and ECHA substance list updates, which would strand inventory positions and create distressed asset opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Certified Carbon Fiber Prepreg | Captures specification tier migration as REACH redirects European formulation investment. |
| Backward Integration into Specialty Graphite Production | Anchors competitive position against mid-scale processors lacking captive substrate supply. |
| Localized Technical Service Network Buildout | Commands premium pricing in North American shale basins where equipment uptime justifies field support. |
| Dual FAA-EASA Certification Investment | Unlocks aerospace-grade specification tiers with steepest compliance barriers and margin capture. |
| Strategic Partnership with Oil and Gas Field Operators | Displaces generalist distributors through after-sales service unbundling in high-temperature rotary applications. |
Study Parameters
Initial hypotheses were tested against primary input from aerospace procurement directors, chemical processing plant engineers, oil and gas field maintenance supervisors, and precision seal ring manufacturing executives, then refined through secondary validation. Primary fieldwork combined structured interviews with OEM specification teams and aftermarket service heads. Secondary sources included FAA airworthiness directive filings, ECHA REACH substance restriction updates, customs trade data for carbon fiber and graphite substrates, and SEC filings from listed industrial seal manufacturers. Bottom-up unit demand modeling triangulated against top-down industry spend estimates across the projection horizon.
Variance decomposition across product type, material formulation, industry vertical, and regional regulatory cluster shaped the analytical framework. Segmentation dimensions modeled include specification tier, end-use application, procurement channel structure, and certification compliance burden. CAGRs were derived through iterative reconciliation of replacement cycle frequencies, specification migration trajectories, and regulatory enforcement intensity. Industry-specific forecast inputs incorporated turbine engine maintenance interval extensions and carbon border adjustment implementation timelines.
Decision-makers should treat outputs as directional under assumptions of sustained EPA-FAA regulatory alignment and continued aerospace OEM consolidation; material deviation in certification timelines or trade policy would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Global Industrial Thermostatic Control Valves Market
Valves
Pneumatic Needle Valves Market
Valves
Explosion Vents Market
Valves
Chemical Injection Metering Pumps and Valves Market
Valves
Sand Control System Market
Valves
Global Automotive Valves Market
Valves
Pipeline Pigging Equipment Market
Valves
Pipeline Strainers Market
Valves
Portable Valve Actuator Market
Valves
Wind Energy Fasteners Market
Valves
Manual Control Valve Market
Valves
Europe Electro Hydraulic Servo Valve Market
Valves
Vacuum Insulated Pipe Market
Valves
Air Heated Vaporizer Market
Valves
Global Valves in Oil and Gas Industry Market
Valves
Hydraulic Valves Market