
 Global Valves in Chemical Market | 2026-2036
Global Valves in Chemical Market Size, Share, and Industry Trends Forecast 2026-2036
Global Valves in Chemical Market Insights
Asset-light leasing models for critical valve inventories is narrowing the competitive field to firms with strong balance sheets and service networks. Flowserve Corporation leverages its aftermarket service infrastructure to capture recurring revenue from chemical plant operators. Emerson Electric Co. sustains technology leadership through digital valve positioning systems integrated with distributed control architectures. KSB anchors its position in European chemical corridors with localized foundry capacity and rapid spare-part fulfillment.
Valves in chemical applications are mechanical flow-control devices engineered to withstand aggressive media, extreme temperatures, and pressure cycling, typically constructed from corrosion-resistant alloys or engineered polymers with tight shut-off classifications. Ball valves dominate high-cycle switching operations in batch chemical processing due to their quarter-turn actuation and minimal pressure drop characteristics. Stainless steel material grades command premium positioning in pharmaceutical and fine chemical end uses where surface finish and traceability requirements exceed standard industrial specifications. Electric control types are gaining share in hazardous-area installations as intrinsically safe actuator designs reduce pneumatic infrastructure dependency.
EPA emissions standards and EU REACH compliance frameworks mandate fugitive emission monitoring and low-leakage packing technologies across chemical processing facilities. FDA cGMP guidelines for pharmaceutical manufacturing impose material certification and cleanability requirements on wetted valve components. OSHA process safety management rules in the United States enforce mechanical integrity programs that drive systematic valve inspection and replacement cycles. Stakeholders must evaluate how evolving per- and polyfluoroalkyl substance restrictions will reshape seal and lining material portfolios across existing installed bases.
Market Dynamics
Automated valve procurement for corrosive fluid handling is concentrating demand among specialty chemical manufacturers with advanced metallurgy capabilities, compressing margins for commodity-grade suppliers.
Growth Catalysts
- EU Chemicals Strategy for Sustainability:Tightening material compliance requirements for sealing technologies are accelerating replacement cycles in European process plants.
- India's petrochemical corridor:Integrated refinery complexes commissioning new process units along the Gujarat coast are generating concentrated demand for high-pressure isolation valves.
- Electric actuator designs:Intrinsically safe electric control types are displacing pneumatic infrastructure in hazardous-area installations, opening retrofit opportunities.
Market Restraints
- Nickel alloy supply concentration:Superalloy feedstock dependence on limited foundry capacity in Germany and Japan creates input cost volatility for corrosion-resistant valve bodies.
- Per- and polyfluoroalkyl substance restrictions:Evolving seal and lining material bans under REACH and state-level US legislation are forcing premature obsolescence of installed PTFE-based packing systems.
- Technical limitation in extreme cycling:Metal-seated ball valves face fatigue-life constraints above 500,000 cycles in catalyst transfer service, limiting addressable market in continuous reforming units.
Strategic Opportunities
- Asset-light leasing models:Critical valve inventory rental programs create recurring revenue streams for firms with dense service networks in the US Gulf Coast chemical cluster.
- Digital valve positioning systems:Integration with distributed control architectures enables predictive maintenance contracts in German pharmaceutical manufacturing.
- China's dual carbon goals:MEE emissions monitoring mandates for chemical parks are stimulating demand for low-leakage packing retrofits in legacy ethylene crackers.
Industry Challenges
- Certification timeline compression:FDA cGMP material traceability requirements for pharmaceutical valves extend qualification cycles by 8-14 months.
- Skill scarcity in advanced welding:Orbital welding certification for superduplex valve fabrication concentrates qualified labor pools in Rotterdam and Singapore.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Valves in Chemical Market |
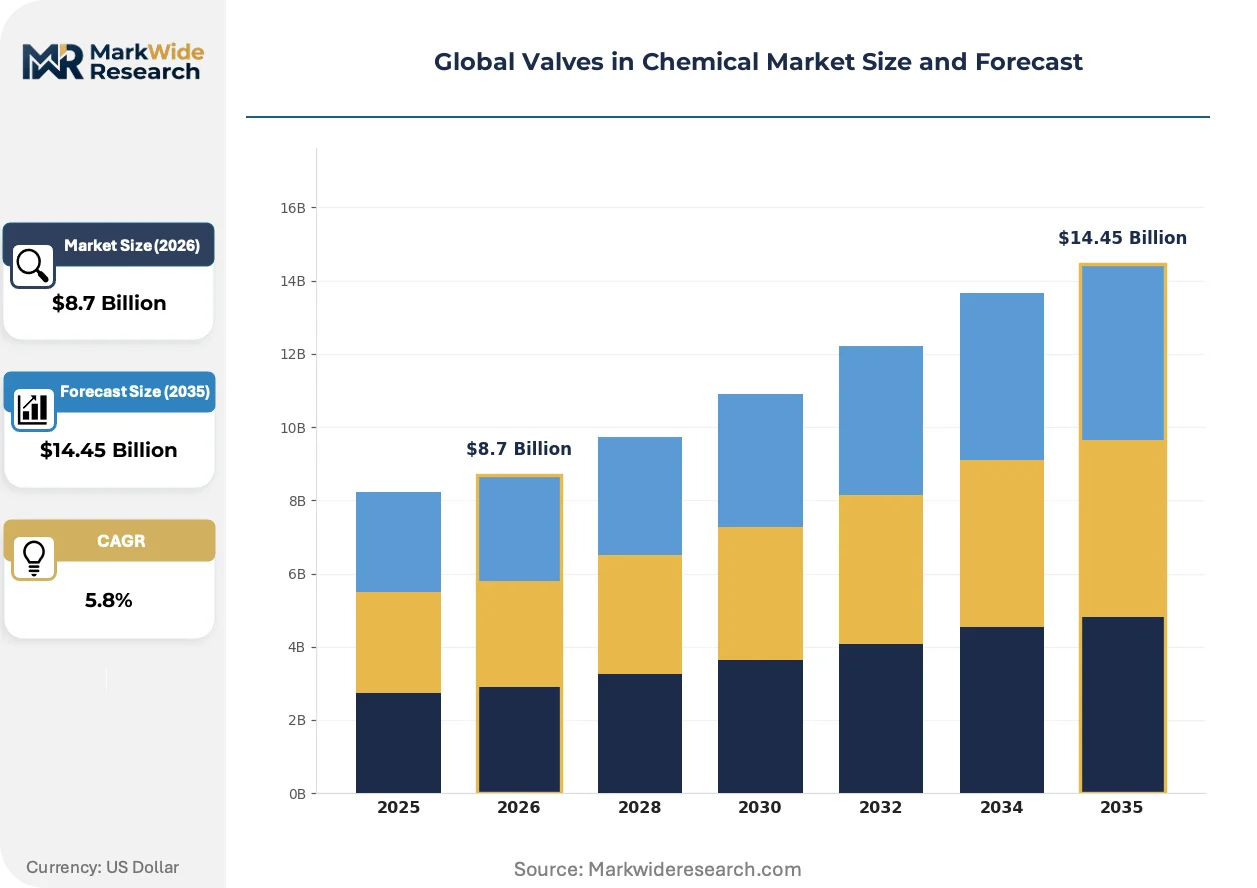
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ball Valves, Gate Valves, Globe Valves, Check Valves Material: Stainless Steel, Plastic, Brass, Carbon Steel End User: Petrochemical, Pharmaceutical, Wastewater, Food & Beverage Control Type: Manual, Pneumatic, Electric, Hydraulic |
| Companies Covered | Emerson Electric Co., Flowserve Corporation, SLB, IMI, Crane Company, Valmet, KITZ Corporation, Christian Bürkert GmbH & Co. KG, KSB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Valves in Chemical Market Trends and Innovations
Valve engineering is pivoting from mechanical reliability toward data-enabled performance assurance, with embedded sensing and predictive algorithms redefining competitive differentiation.
Metal additive manufacturing for valve body production is rendering obsolete conventional sand-casting for complex flow geometries below 50 kilograms. Specialty chemical producers in Switzerland and the Netherlands are qualifying laser-powder-bed-fusion Hastelloy components for chlorine service. This distributed production model is compressing spare-part lead times from 16 weeks to 72 hours for critical dimensions.
REACH restrictions on perfluorinated compounds are compelling seal material reformulation across European chemical processing. ECHA substance evaluation is disqualifying legacy PTFE compounds for new installations in fluorinated gas production. German valve packagers are accelerating graphite and thermoplastic elastomer validation programs to maintain market access.
Lifecycle service contracting is displacing transactional valve procurement in hazardous chemical service. Integrated operators on the US Gulf Coast are bundling inspection, repair, and predictive replacement into ten-year agreements with outcome-based availability guarantees. This model concentrates vendor selection on field service density rather than unit manufacturing cost.
Global Valves in Chemical Market Segmentation
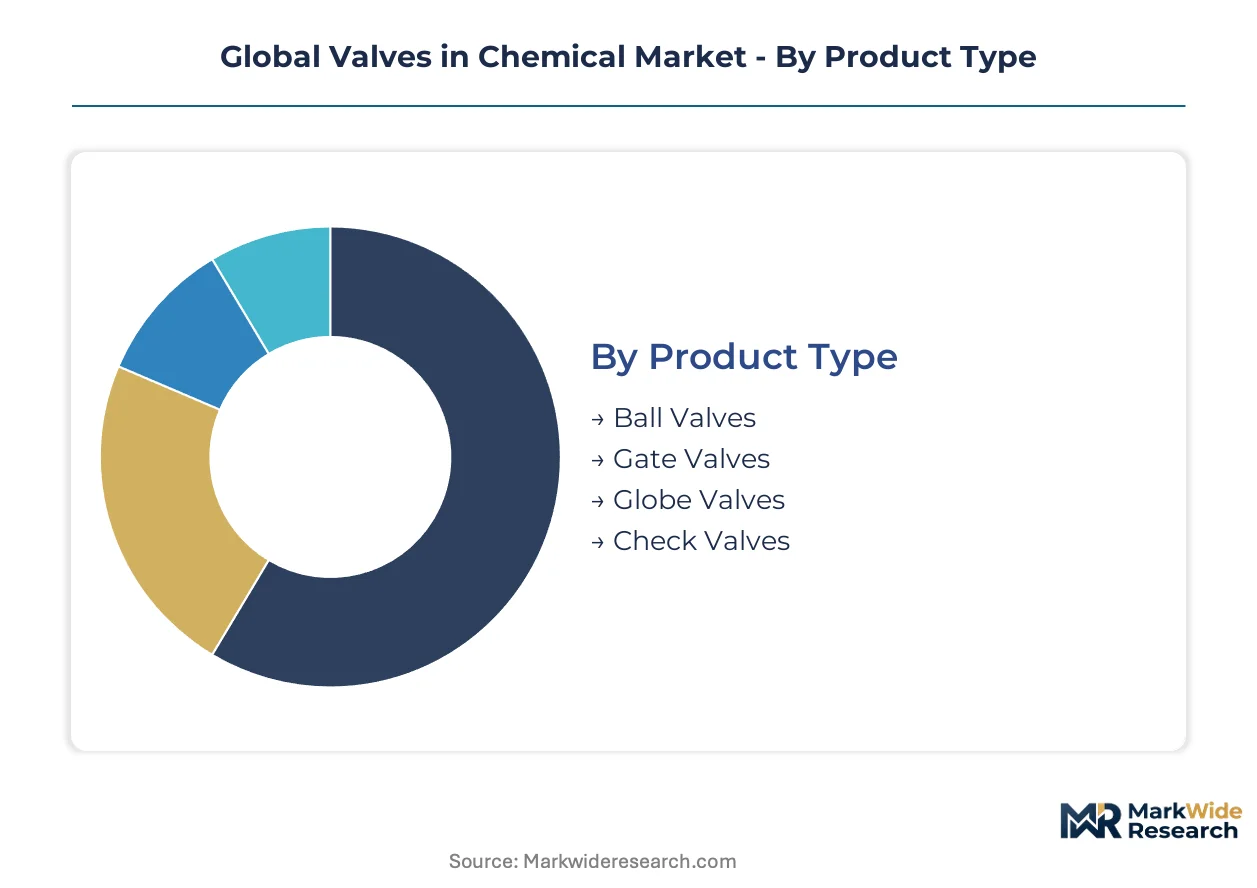
Valve procurement cycles vary dramatically across chemical applications, with some segments requiring annual replacement in corrosive service while others operate for decades in stable utility loops. Understanding these velocity differences enables suppliers to calibrate inventory, service density, and pricing architecture to specific segment economics.
Product Type:
Quarter-turn designs command shorter replacement cycles than linear-motion alternatives in high-cycling batch operations, while isolation valves in continuous service stretch toward 15-year lifespans.
- Ball Valves:Quarter-turn actuation delivers rapid switching with minimal pressure drop, making these the default choice for batch chemical processing where cycles exceed 100,000 annually. Demand concentrates in specialty chemical plants across Germany and China's coastal provinces as automated batch systems proliferate.
- Gate Valves:Linear-motion isolation with full-bore flow characteristics suits infrequently operated but critical shut-off points in ethylene crackers and reformer units. Gujarat's petrochemical corridor generates concentrated procurement for high-pressure forged designs as integrated refinery complexes expand.
- Globe Valves:Throttling precision in control loops drives specification for these multi-turn designs in pharmaceutical fine chemical synthesis.
- Check Valves:Passive flow prevention in pump discharge and compressor piping creates steady replacement demand across wastewater treatment and bulk chemical transfer applications.
Ball valves anchor the volume base while electric-actuated variants gain share at the steepest rate in hazardous-area retrofits.
Material:
Material selection directly determines corrosion allowance, welding complexity, and regulatory qualification burden across chemical service applications.
- Stainless Steel:Austenitic and duplex grades dominate pharmaceutical and food-grade applications where surface finish and traceability requirements exceed standard industrial specifications. FDA cGMP material certification programs in US and European facilities extend qualification timelines and sustain premium positioning.
- Plastic:PVDF and PTFE-lined designs deliver chemical inertness in chlorine and acid service at substantially lower installed weight than metallic alternatives. REACH restrictions on perfluorinated compounds are forcing rapid reformulation toward graphite and advanced elastomer alternatives in European chemical parks.
- Brass:Lead-free alloys retain position in low-pressure utility and instrumentation applications where cost sensitivity outweighs corrosion resistance requirements.
- Carbon Steel:Standard grades with corrosion allowances serve non-corrosive hydrocarbon and steam service in bulk petrochemical infrastructure.
Stainless steel anchors the value base while plastic-lined configurations climb the fastest as fluoropolymer restrictions reshape European material specifications.
End User:
End-use concentration determines service intensity, regulatory exposure, and vendor relationship durability across the installed base.
- Petrochemical:High-pressure isolation and control valves in ethylene crackers, aromatics complexes, and polyolefin plants operate under extreme thermal and mechanical stress. India's Gujarat corridor and US Gulf Coast chemical cluster generate the steepest procurement expansion as integrated complexes commission new process trains.
- Pharmaceutical:Surface finish, material traceability, and cleanability requirements under FDA and EMA guidelines sustain premium positioning for electropolished stainless steel and specialty alloy designs. Validation protocols extend vendor qualification cycles and concentrate procurement among established suppliers with documented compliance histories.
- Wastewater:Abrasion resistance and chemical compatibility in effluent treatment create steady demand for resilient-seated designs in municipal and industrial facilities.
- Food & Beverage:Hygienic design standards and clean-in-place compatibility drive specification for crevice-free construction and FDA-compliant elastomers.
Petrochemical applications anchor the volume base while pharmaceutical end uses command the steepest value expansion through regulatory-driven premium positioning.
Control Type:
Actuation architecture determines infrastructure requirements, hazardous-area compliance pathways, and integration complexity with plant control systems.
- Manual:Handwheel and lever operation persists in isolated utility applications and maintenance bypass configurations where automation economics fail to justify investment. Procurement concentrates in developing chemical corridors with lower labor costs and simpler process architectures.
- Pneumatic:Compressed air infrastructure dominates legacy installations across established chemical clusters, though EPC specifications are shifting toward electric alternatives in greenfield projects.
- Electric:Intrinsically safe actuator designs are displacing pneumatic infrastructure in hazardous-area installations, eliminating compressor maintenance and enabling precise digital positioning. German pharmaceutical manufacturers and US Gulf Coast operators are driving retrofit demand as distributed control integration becomes standard.
- Hydraulic:High-force actuation for large-bore isolation valves in pipeline and tankage applications serves niche requirements where pneumatic or electric torque proves insufficient.
Manual control anchors the installed base volume while electric actuation expands most quickly as intrinsically safe designs penetrate hazardous chemical service.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty chemical manufacturers in Germany and China dominate automated valve procurement, while India's petrochemical corridor generates concentrated demand for high-pressure isolation systems. Buyer archetypes cluster around integrated refinery operators, pharmaceutical multinationals, and specialty chemical producers with aggressive automation timelines.
Germany
Specialty chemical manufacturers in Ludwigshafen and Leverkusen expand automated valve procurement for corrosive fluid handling. ECHA substance evaluation under REACH disqualifies legacy PTFE compounds, accelerating seal material reformulation. The BASF cluster in Ludwigshafen drives demand for laser-powder-bed-fusion Hastelloy components as distributed production models compress spare-part lead times.
China
Coastal petrochemical provinces commission new ethylene crackers with electric-actuated isolation systems. MEE emissions monitoring mandates for chemical parks stimulate low-leakage packing retrofits in legacy infrastructure. The Yangtze River Delta chemical corridor concentrates procurement for intrinsically safe electric valves as dual carbon goals reshape plant automation specifications.
India
Integrated refinery complexes along the Gujarat coast commission new process trains requiring high-pressure forged gate valves. BIS certification requirements extend qualification timelines for imported corrosion-resistant alloys. The Dahej and Hazira industrial zones generate steep procurement expansion as Reliance and Nayara Energy expand aromatics and polyolefin capacity.
United States
Gulf Coast chemical cluster operators bundle inspection and predictive replacement into ten-year lifecycle service contracts. EPA emissions standards mandate fugitive emission monitoring and low-leakage packing technologies across Texas and Louisiana process plants. The Houston Ship Channel concentration favors vendors with dense field service networks over unit manufacturing cost competition.
Switzerland
Pharmaceutical fine chemical producers in Basel validate electropolished stainless steel valves for FDA cGMP compliance. Swissmedic guidelines and EMA traceability requirements sustain premium positioning for documented compliance histories. The Novartis and Roche supply ecosystem concentrates procurement among established suppliers with orbital welding certification for superduplex fabrication.
Global Valves in Chemical Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. Consolidation pressures favor firms with dense aftermarket service networks capable of capturing recurring revenue from lifecycle contracts. Strategic archetypes include integrated automation vendors, metallurgical specialists with captive foundry capacity, and regional fabricators with rapid spare-part fulfillment. Dominant competitive moves center on predictive maintenance service bundling and additive manufacturing qualification for complex alloy components.
Within the integrated automation tier, Emerson Electric Co. and Flowserve Corporation occupy positions defined by digital valve positioning systems and aftermarket infrastructure density. German engineering-focused KSB anchors the European chemical corridor archetype through localized production capabilities. Japanese precision manufacturers including KITZ Corporation exemplify the metallurgical specialist model with advanced alloy processing expertise.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Flowserve Corporation |
| SLB |
| IMI |
| Crane Company |
| Valmet |
| KITZ Corporation |
| Christian Bürkert GmbH & Co. KG |
| KSB |
| Others |
Pricing and Supply Chain Analysis
German and Japanese superalloy foundries concentrate feedstock supply for corrosion-resistant valve bodies, anchoring margin pools in downstream metallurgical certification tiers rather than commodity fabrication. Specialty chemical manufacturers in Ludwigshafen and Leverkusen absorb premium positioning through FDA-grade material traceability, while commodity-grade suppliers face compression from nickel alloy price volatility.
Pricing Analysis
Certification level creates the primary spread between pharmaceutical-grade and standard industrial valve procurement. Three-tier pricing structure across premium, standard, and economy levels reflects FDA cGMP material traceability, ISO 15848 fugitive emission compliance, and CE marking for European chemical parks. Cost compression in commodity stainless steel tiers is intensifying because Indian and Chinese fabricators expand forged-body capacity for non-corrosive hydrocarbon service. Pharmaceutical multinationals in Basel and Boston exhibit least price sensitivity due to validation protocol lock-in, while municipal wastewater operators in developing chemical corridors drive hardest bargaining on resilient-seated designs.
Supply Chain Analysis
Extended payment terms from EPC contractors on US Gulf Coast projects strain working capital for mid-tier valve packagers without supply-chain finance facilities. Manufacturing gravity centers on Germany, Japan, and China, with superduplex welding certification concentrating qualified labor pools in Rotterdam and Singapore. Raw material flows draw from Indonesian nickel laterite, South African chromium, and Chinese rare-earth alloying elements. Single-source vulnerability runs through limited Hastelloy laser-powder-bed-fusion capacity in Switzerland and the Netherlands. Distribution runs through authorized stocking distributors in Houston, Rotterdam, and Singapore who bundle inspection and predictive replacement services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital valve positioning systems are reconstituting this market around platform-economics logic, with predictive maintenance contracts creating winner-take-most dynamics for vendors achieving distributed control architecture interoperability.
For Market Incumbents: Harden aftermarket service density through orbital welding certification capture in Rotterdam and Singapore, insulating against additive manufacturing specialists qualifying laser-powder-bed-fusion Hastelloy components for chlorine service. Deepen captive foundry capacity in superalloy grades to offset nickel feedstock volatility from Indonesian and Japanese concentrate suppliers. Lock in ten-year lifecycle contracting with US Gulf Coast chemical cluster operators before emerging electric actuator vendors achieve hazardous-area certification parity. For New Entrants and Emerging Players: Pursue low-leakage packing retrofit opportunities in China's legacy ethylene crackers as MEE emissions monitoring mandates reshape seal material specifications away from REACH-restricted PTFE compounds. Target India's Dahej and Hazira industrial zones where BIS certification barriers filter out established European suppliers on corrosion-resistant alloy qualification timelines. Lead with asset-light leasing models for critical valve inventories, capturing recurring revenue without balance-sheet-intensive manufacturing investments. For Investors and Strategic Acquirers: Capital is best deployed toward metallurgical specialists with captive superalloy foundry capacity and documented FDA cGMP compliance histories, as regulatory qualification timelines extend vendor selection durability. Long-term viability hinges on additive manufacturing qualification for complex alloy components below 50 kilograms, compressing spare-part lead times from conventional sand-casting cycles. Watch for ECHA substance evaluation acceleration on perfluorinated compounds as inflection indicator for seal material reformulation winners.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Superalloy Foundry Capacity | KSB's localized German foundry capacity anchors rapid Hastelloy spare-part fulfillment for BASF Ludwigshafen cluster. |
| Digital Valve Positioning System Integration | Emerson Electric's distributed control architecture interoperability captures predictive maintenance contracts in pharmaceutical manufacturing. |
| Orbital Welding Certification Expansion | Flowserve's Singapore and Rotterdam qualified labor pools concentrate superduplex fabrication capability for Novartis Basel supply ecosystem. |
| Asset-Light Leasing Model Deployment | Critical valve inventory rental programs concentrate vendor selection on field service density in Houston Ship Channel chemical cluster. |
| Laser-Powder-Bed-Fusion Qualification | Swiss and Dutch specialty chemical producers validate additive manufacturing for chlorine service, compressing lead times from 16 weeks to 72 hours. |
Research Methodology
Cross-validation between primary interviews with plant managers, procurement leads at downstream petrochemical operators, distribution channel partners, and technical R&D directors anchors the qualitative findings in operational reality. Secondary validation draws from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and EPA emissions compliance disclosures. Bottom-up segmentation modeling triangulates against top-down macroeconomic drivers across the chemical processing capital expenditure cycle.
Calibration against historical replacement velocity patterns in corrosive versus non-corrosive service establishes baseline demand elasticity. Segmentation dimensions span valve type, material grade, end-use industry, control architecture, and regional regulatory cluster across the analysis window. CAGRs derive from installed base depreciation schedules, greenfield project pipelines, and retrofit timing assumptions tied to REACH and EPA emissions mandate compliance cycles. Nickel alloy price volatility and orbital welding labor scarcity feed as sensitivity inputs.
Sensitivities concentrate around ECHA substance evaluation acceleration on perfluorinated compounds, BIS certification timeline shifts in India, and MEE enforcement intensity in China's chemical parks. Forecasts embed assumptions on electric actuator penetration rates in hazardous areas and additive manufacturing qualification timelines for Hastelloy components. Macroeconomic deviation in chemical processing capital expenditure, regulatory restriction expansion on seal materials, or breakthrough fatigue-life improvements in metal-seated designs would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Europe Medium Voltage Switchgear Market
Valves
GCC and MENA Valves Market
Valves
Refrigeration Valves Market
Valves
APAC Valves Market
Valves
Pressure Control Equipment Market
Valves
Europe Vacuum Insulated Pipe Market
Valves
Cathodic Protection Market
Valves
North America High Voltage Switchgear Market
Valves
Deluge Valve Market
Valves
Hydraulic Diaphragm Valve Market
Valves
Global Globe Valve Market
Valves
Mobile Hydraulic Valves Market
Valves
Gas Equipment Market
Valves
Christmas Tree Valves Market
Valves
Sanitary Valves Market
Valves
North America Valves Market