
 Mooring Inspection Market | 2026-2036
Mooring Inspection Market Size, Share, and Industry Trends Forecast 2026-2036
Mooring Inspection Market Analysis
API RP 2SK certification cycles is bifurcating the competitive landscape between accredited specialists and generalist marine contractors. Acteon Group leverages its integrated subsea services platform to bundle inspection with intervention work across the North Sea and Gulf of Mexico. Oceaneering International sustains technology leadership through proprietary ROV-deployed measurement systems purpose-built for deepwater mooring line assessment. DOF Subsea anchors its position through vessel-based inspection campaigns that combine diver operations with robotic tooling for complete chain and connector evaluation.
Mooring inspection encompasses the systematic evaluation of anchoring systems, including studless chain, wire rope, synthetic fiber ropes, and their connection hardware, using non-destructive testing protocols to detect corrosion, wear, fatigue cracking, and deformation before structural failure occurs. The primary purpose is to assure continuous station-keeping capability of floating offshore structures exposed to cyclical wave, wind, and current loading over multi-decade design lives. Integrity assessment services command premium margins due to the specialized engineering analysis required to translate inspection data into remaining-life predictions and re-certification recommendations. ROV-based technology leads deployment for deepwater assets where diver access is impractical, while ultrasonic testing represents the fastest-growing modality as operators seek sub-surface defect detection without component removal. Visual inspection retains volume dominance in shallow-water harbors and port moorings where surface-accessible degradation patterns suffice for regulatory compliance.
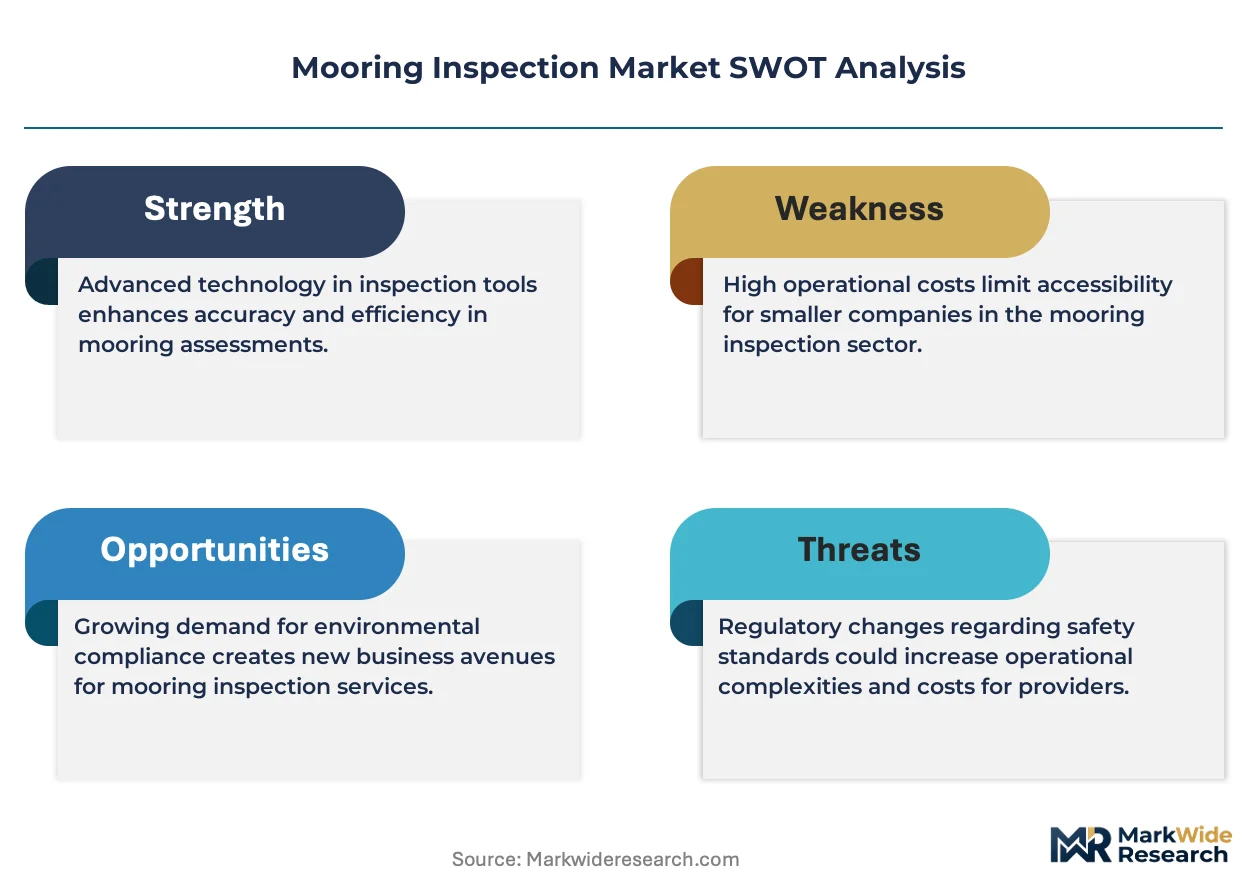
DNV standards, API guidelines, and IMO conventions collectively govern mooring system certification intervals, material acceptance criteria, and in-service inspection scope, creating compliance-driven demand that fluctuates with regulatory amendment cycles rather than purely commodity price signals. The US Coast Guard and Bureau of Safety and Environmental Enforcement enforce facility-specific inspection mandates for domestic offshore operations, while Norway's Petroleum Safety Authority imposes stricter documentation requirements for floating offshore installations in its territorial waters. Stakeholders must monitor the divergence between prescriptive classification rules and risk-based inspection approaches as classification societies compete to define the next generation of mooring integrity management standards.
Market Dynamics
Floating production system aging across the North Sea and Gulf of Mexico is forcing operators to compress inspection intervals from five-year cycles to continuous monitoring regimes, reshaping contractor relationships and technology procurement patterns.
Growth Catalysts
- API RP 2SK recertification mandates:Classification societies now require enhanced fatigue documentation for chain systems exceeding twenty years of service, compelling asset owners to expand inspection scope.
- Deepwater field development:Brazil's pre-salt discoveries and West African ultra-deepwater projects demand ROV-deployable inspection solutions for mooring lines beyond diver-accessible depths.
- Synthetic rope adoption:Polyester and high-modulus polyethylene mooring lines in floating offshore wind installations require specialized non-destructive testing protocols not applicable to traditional chain systems.
Market Restraints
- Specialized vessel scarcity:DP-2 and DP-3 class inspection vessels concentrate among North Sea and Gulf of Mexico operators, creating capacity bottlenecks during seasonal weather windows.
- Ultrasonic transducer supply concentration:High-frequency probe manufacturing for sub-surface chain defect detection depends on Japanese and German component suppliers with limited surge capacity.
- DNV-ST-C203 fatigue calculation complexity:The standard's probabilistic damage tolerance requirements demand PhD-level engineering interpretation, extending analysis timelines and inflating service costs.
Strategic Opportunities
- Floating offshore wind expansion:Scotland's ScotWind leasing rounds and Norway's Utsira Nord development will deploy hundreds of pre-laid mooring systems requiring inspection infrastructure.
- Continuous monitoring convergence:Integration of fiber-optic strain sensing with autonomous surface vehicles enables real-time tension monitoring without vessel mobilization.
- Risk-based inspection adoption:Norway's Petroleum Safety Authority permits extended statutory survey intervals for operators demonstrating predictive integrity management capabilities.
Industry Challenges
- Subsea robotics technician shortage:ROV pilot-technician training programs cannot match fleet expansion rates, particularly for advanced manipulator operations on connector hardware.
- Legacy chain database incompatibility:Decades of inspection records stored in proprietary formats resist migration to unified asset integrity platforms required by modern analytics.
- Multi-contractor coordination friction:Inspection campaigns involving separate diving, ROV, and laboratory analysis vendors create handoff delays and liability fragmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mooring Inspection Market |
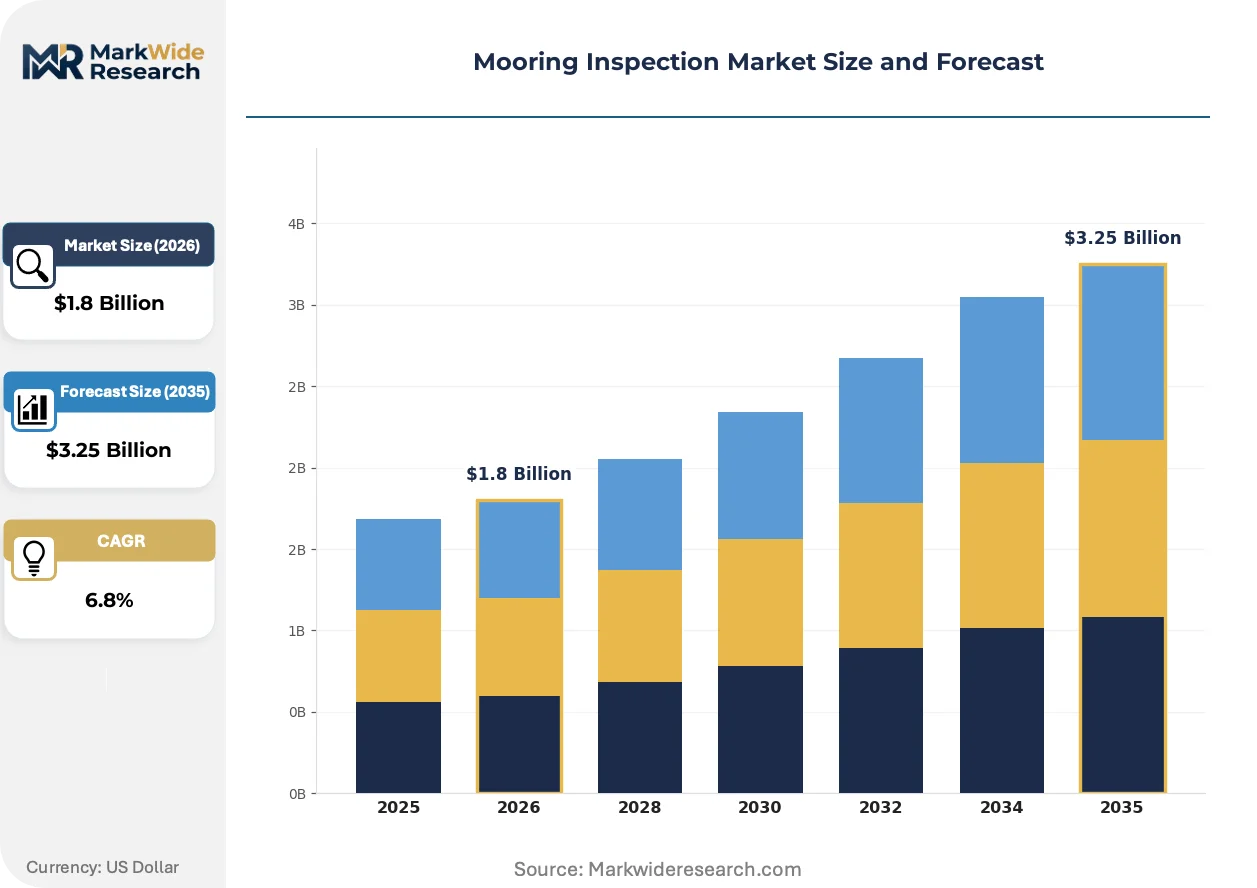
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Visual Inspection, Load Testing, Integrity Assessment, Maintenance Service Technology: Sonar Systems, ROV, Drones, Ultrasonic Testing End User: Oil & Gas Companies, Shipping Firms, Marine Contractors, Ports Application: Offshore Platforms, Harbors, Vessels, Floating Structures |
| Companies Covered | Acteon Group, DOF Subsea, Oceaneering International, Delmar, Moffatt & Nichol, DeepOcean, Deep Sea Mooring, Viking SeaTech, Welaptega, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mooring Inspection Market Emerging Trajectories
Inspection technology is compressing from vessel-dependent operations toward autonomous and permanently installed sensing architectures, reducing weather sensitivity while expanding data granularity for predictive maintenance models.
Subsea photogrammetry combined with machine-learning defect classification is miniaturizing. Norwegian operators now deploy battery-powered inspection crawlers on FPSO mooring chains during production downtime, eliminating the need for dedicated vessel standby. The technology is miniaturizing survey equipment from containerized ROV garages to briefcase-sized sensor pods that permanent technicians can deploy without specialized marine crews.
DNV's new offshore wind mooring standard imposes stricter documentation requirements for synthetic rope installations than existing oil and gas guidelines. Floating wind developers must submit manufacturing traceability records and accelerated aging test data before commercial operation. European project financiers now treat this certification as a loan covenant trigger, accelerating pre-construction inspection planning by twelve to eighteen months.
Asset owners are unbundling inspection services from integrated offshore contractors and contracting directly with specialized NDE firms. This disintermediation reflects dissatisfaction with bundled pricing opacity and enables direct ownership of inspection data intellectual property. The shift is most pronounced among UK North Sea operators with multiple field equity partners requiring transparent cost allocation across joint venture structures.
Mooring Inspection Market Segmentation
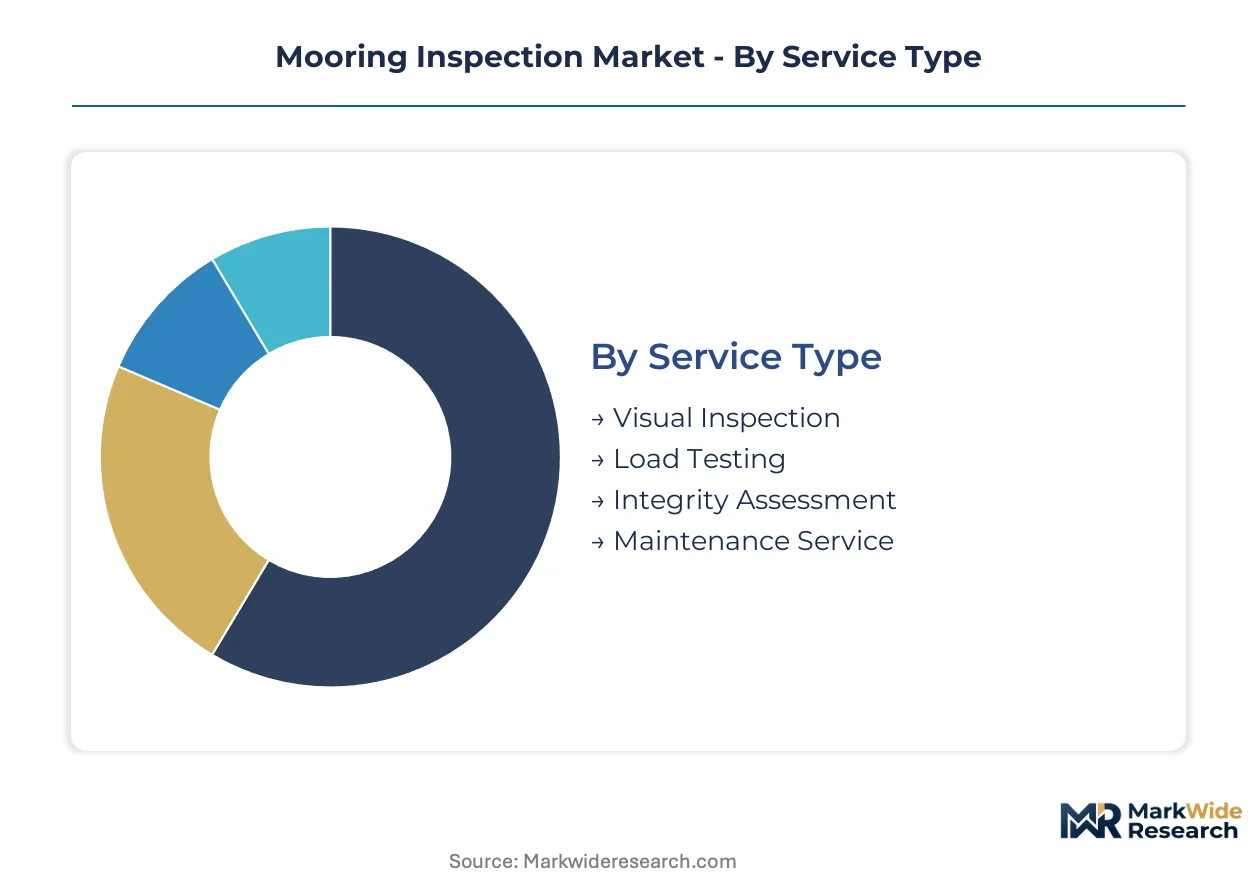
Mooring inspection demand fragments across service modalities, technology platforms, and asset classes. Each segment carries distinct procurement patterns, regulatory triggers, and margin structures that reshape contractor positioning.
Service Type:
Geographic concentration varies sharply: visual inspection and load testing dominate domestic port maintenance, while integrity assessment and maintenance services follow export-led offshore field development.
- Visual Inspection:Surface-level assessment of chain, wire rope, and connector hardware using optical magnification and photographic documentation. Norwegian North Sea operators deploy this modality for annual statutory surveys on aging FPSO mooring systems, driven by Petroleum Safety Authority documentation mandates.
- Integrity Assessment:Engineering analysis combining non-destructive testing data with fatigue-life modeling and remaining-strength calculations. Brazil's pre-salt operators commission specialized firms for this service to satisfy classification society recertification requirements for ultra-deepwater polyester moorings.
- Load Testing:Proof-load validation of mooring components under controlled tension to verify working load limits.
- Maintenance Service:Scheduled replacement of worn connectors, anodes, and tensioning hardware.
Visual inspection commands the established base. The steepest expansion runs through integrity assessment.
Technology:
Cost tiering separates vessel-dependent systems from portable deployables, with capital intensity determining contractor specialization and geographic reach.
- ROV:Tethered robotic vehicles equipped with manipulator arms and sensor payloads for deepwater chain and connector examination. Gulf of Mexico operators rely on ROV-deployed cathodic potential measurement for subsea mooring hardware beyond diver limits, compelled by Bureau of Safety and Environmental Enforcement facility inspection rules.
- Ultrasonic Testing:High-frequency acoustic pulse transmission for sub-surface defect detection in chain links and shackles. United Kingdom North Sea asset owners are adopting this modality fastest to satisfy DNV-ST-C203 probabilistic damage tolerance requirements without component removal.
- Sonar Systems:Acoustic imaging for seabed anchor position verification and scour monitoring.
- Drones:Aerial platforms for topside mooring fairlead and winch inspection.
ROV systems command the established base. The steepest expansion runs through ultrasonic testing.
End User:
Customer type dictates contract structure: oil and gas majors favor long-term framework agreements, while shipping firms and ports procure spot services.
- Oil & Gas Companies:Integrated operators and independents owning floating production, storage, and drilling assets. Norway's Equinor and Aker BP drive North Sea inspection procurement through joint venture cost-sharing structures, with API RP 2SK recertification cycles triggering bundled service awards.
- Marine Contractors:Subsea construction and installation firms requiring pre-lay and post-lay mooring verification. United Kingdom offshore wind developers contract these specialists for ScotWind floating foundation mooring acceptance testing.
- Shipping Firms:Tanker and bulk carrier operators with single-point mooring buoy maintenance needs.
- Ports:Harbor authorities managing vessel mooring dolphin and bollard integrity.
Oil and gas companies command the established base. The steepest expansion runs through marine contractors.
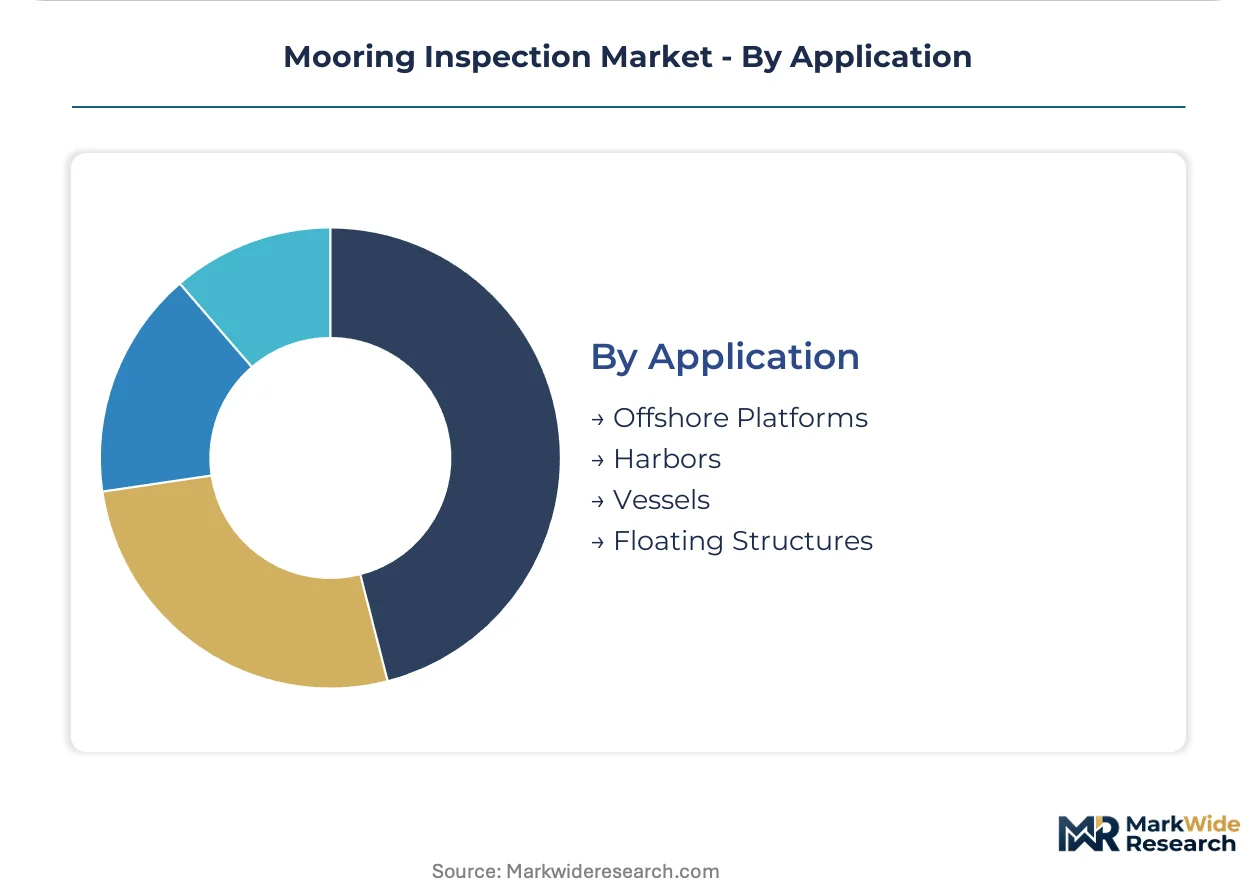
Application:
Volume concentration sits with shallow-water assets, while margin concentration follows deepwater complexity and regulatory stringency.
- Offshore Platforms:Floating production, drilling, and accommodation units in harsh-environment oil and gas provinces. United Kingdom and Norwegian North Sea fields host the densest concentration of moored platforms requiring continuous integrity management, with classification society rules compressing inspection intervals as systems age.
- Floating Structures:Offshore wind turbines, fish farms, and renewable energy platforms. Scotland's ScotWind and Norway's Utsira Nord developments are deploying pre-laid synthetic mooring systems that demand specialized non-destructive testing protocols distinct from traditional chain assessment.
- Harbors:Commercial port mooring infrastructure for cargo and passenger vessels.
- Vessels:Shipboard anchor and mooring winch systems.
Offshore platforms command the established base. The steepest expansion runs through floating structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North Sea pipeline network and its moored floating production infrastructure underwrites Norway's central role in offshore integrity services, with Statfjord and Gullfaks fields driving continuous inspection demand.
Norway
Equinor's Johan Sverdrup and Martin Linge developments compress inspection cycles for aging mooring systems. The Petroleum Safety Authority mandates documented fatigue-life assessments for floating installations exceeding design thresholds. Bergen and Stavanger host specialized contractor clusters executing ROV-based chain examinations for North Sea FPSO fleets.
United Kingdom
BP and Shell's decommissioning-delayed assets in the northern North Sea extend mooring service lives beyond original certification periods. The Health and Safety Executive enforces API RP 2SK compliance through offshore installation safety case reviews. Aberdeen maintains Europe's densest concentration of subsea inspection engineering consultancies and specialist vessel operators.
United States
Chevron and ExxonMobil operate legacy tension-leg platforms and FPSOs in the Gulf of Mexico requiring enhanced monitoring as hurricanes intensify. The Bureau of Safety and Environmental Enforcement mandates facility-specific inspection programs under 30 CFR 250 regulations. Houston anchors the contractor ecosystem serving deepwater mooring integrity campaigns across the Mississippi Canyon and Green Canyon production zones.
Brazil
Petrobras pre-salt developments at Búzios and Mero deploy polyester mooring systems in 2,000-meter water depths beyond diver access. The National Petroleum Agency requires classification society certification for all floating production mooring installations. Rio de Janeiro concentrates engineering capabilities for ROV-deployed inspection of ultra-deepwater synthetic line systems.
China
CNOOC expands floating LNG import terminal mooring networks along the eastern seaboard. The Maritime Safety Administration implements port state control inspection regimes for commercial vessel anchoring systems. Shanghai and Tianjin port authorities drive demand for visual inspection and load testing of harbor mooring dolphins serving container traffic.
Mooring Inspection Market Vendor Landscape
Listed leaders compete with private specialists across capital intensity and geographic reach. The market structures around three tiers: integrated subsea service conglomerates, vessel-dependent inspection contractors, and technology-focused non-destructive testing boutiques. Competitive positioning hardens through API RP 2SK accreditation acquisition and DP-class vessel fleet expansion. Consolidation pressure intensifies as operators seek single-source accountability for mooring integrity across multi-field portfolios.
Among integrated service providers, Acteon Group and Oceaneering International exemplify the conglomerate archetype bundling inspection with intervention capabilities. DOF Subsea occupies a position within the vessel-centric contractor tier, leveraging offshore support fleet access to capture campaign-based inspection awards. These three entities represent distinct strategic postures: technology-led integration, marine asset scale, and combined diver-robotic service delivery.
| Leading Market Players |
|---|
| Acteon Group |
| DOF Subsea |
| Oceaneering International |
| Delmar |
| Moffatt & Nichol |
| DeepOcean |
| Deep Sea Mooring |
| Viking SeaTech |
| Welaptega |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day mobilization lead times for DP-class inspection vessels concentrate pricing power among Norwegian and Gulf of Mexico operators, compressing margins for contractors without guaranteed fleet access while inflating premiums during North Sea seasonal windows.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates API RP 2SK-accredited specialists from generalist marine contractors and port-based visual inspection providers. Price differentiation hinges on certification grade and vessel specification tier, with DP-3 class spreads commanding substantial premiums over DP-1 alternatives. Pricing pressure stems from asset owners disintermediating bundled services and negotiating direct NDE contracts. Shipping firms and harbor authorities exhibit highest price sensitivity, while pre-salt operators accept premium positioning for ultra-deepwater synthetic rope assessment.
Supply Chain Analysis
Strait of Malacca transit chokepoints for high-frequency ultrasonic transducers from Japanese and German component manufacturers concentrate supply risk for sub-surface defect detection equipment. Manufacturing draws from Japan, Germany, and South Korea for precision probe assemblies, with raw material dependencies spanning rare-earth magnet supply and specialized piezoelectric ceramics. Single-source vulnerability runs through concentrated probe fabrication capacity. Distribution runs through OEM-direct vessel outfitting and regional service hub stocking for consumable replacement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-economics inflection is materializing as fiber-optic strain sensing interoperability standards enable third-party analytics layers atop proprietary inspection hardware, shifting value capture toward data-aggregation platforms.
For Market Incumbents: Fortify API RP 2SK accreditation moats through backward integration into ultrasonic probe calibration facilities, countering emerging NDE boutiques capturing direct owner contracts. Prioritize DP-2 vessel additions in Brazil to defend against regional specialists exploiting Petrobras pre-salt inspection demand. For New Entrants and Emerging Players: Anchor in floating offshore wind pre-lay verification services, the most penetrable segment as ScotWind and Utsira Nord developers seek synthetic rope specialists outside incumbent oil and gas channels. Pursue DNV-ST-C203 engineering certification as entry credential for integrity assessment contracts. For Investors and Strategic Acquirers: Carve-out targets emerge from integrated subsea conglomerates divesting non-core inspection units to streamline balance sheets. Long-term viability favors technology-led NDE boutiques with proprietary ROV-deployable measurement IP. Watch fiber-optic sensing standardization progress as inflection indicator for platform-economics value migration.| Strategic Initiative | Industry Significance |
|---|---|
| API RP 2SK Accreditation Investment | Classification society certification unlocks statutory survey contracts for aging North Sea FPSO fleets. |
| DP-Class Vessel Fleet Expansion | Dynamic positioning capability secures campaign awards during constrained North Atlantic weather windows. |
| Fiber-Optic Sensing Platform Integration | Real-time tension monitoring displaces vessel-dependent periodic inspection with continuous data streams. |
| Synthetic Rope NDE Protocol Development | Specialized polyester and HMPE assessment capabilities capture floating offshore wind pre-commissioning demand. |
| Asset Integrity Data Platform Acquisition | Unified analytics layers resolve legacy chain database incompatibility blocking predictive maintenance adoption. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of classification society certification records, offshore installation safety case filings, and vessel charter rate databases through structured interviews with FPSO asset integrity managers, ROV pilot-technician supervisors, subsea engineering consultants, and Petroleum Safety Authority regulatory leads. Bottom-up triangulation across service modality procurement volumes and top-down validation through integrated contractor revenue attribution ensure cross-verified market sizing.
Segmentation dimensions modeled span service type, technology platform, end-user category, and application asset class across the analysis window. CAGRs derive from inspection interval compression rates, floating production system age profiles, and regulatory amendment cycle timing. Forecast inputs incorporate synthetic rope adoption curves in floating offshore wind and continuous monitoring technology penetration assumptions.
Decision-makers should treat outputs as directional under base assumptions of sustained classification society enforcement stringency and DP-vessel fleet stability; material deviation in regulatory posture or marine asset availability would warrant model refresh. Practitioners should keep alternative scenarios live as floating offshore wind deployment pace and autonomous inspection technology maturation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Industrial Valves and Actuators Market
Valves
Sand Control System Market
Valves
Transmission Overload Protectors Market
Valves
Sliding Sleeves Market
Valves
Pipeline Pigging Equipment Market
Valves
Air Heated Vaporizer Market
Valves
Thermal Power Valve Market
Valves
Global Globe Valve Market
Valves
Pipeline and Process Services Market
Valves
Top Drive Systems Market
Valves
Global Plastic Valves Market
Valves
Valve Interlocks Market
Valves
Global Solenoid Valves Market
Valves
Pigging Valves Market
Valves
Pressure Gauge Market
Valves
Global Thermostatic Radiator Valve Market