
 Explosion Isolation Valves Market | 2026-2036
Explosion Isolation Valves Market Size, Share, and Industry Trends Forecast 2026-2036
Explosion Isolation Valves Market Insights
EU ATEX Directive compliance is hardening procurement standards for explosion protection equipment across European process industries. Emerson Electric Co. leverages its global automation platform to integrate isolation valves with distributed control systems, while Fike Corporation specializes in rapid-actuation flameless venting and isolation technologies for high-risk chemical environments. Danfoss A/S anchors its position through hydraulic and electromechanical actuator expertise that extends valve response speeds below critical flame propagation thresholds.
Explosion isolation valves are mechanical safety devices engineered to seal process ducts and pipelines within milliseconds of detecting pressure waves or thermal signatures from deflagration events, typically achieving closure times under 100 milliseconds to prevent flame front transmission between interconnected equipment. Ball valves dominate product type procurement due to their bidirectional sealing reliability and compatibility with pneumatic actuation in dust handling systems, while butterfly valves compete on cost and footprint in large-diameter duct applications. Oil and gas end users represent a mature, specification-driven segment where API and NFPA standards govern procurement, whereas power generation facilities are shifting toward integrated inspection and replacement service contracts to manage aging coal and biomass handling infrastructure.
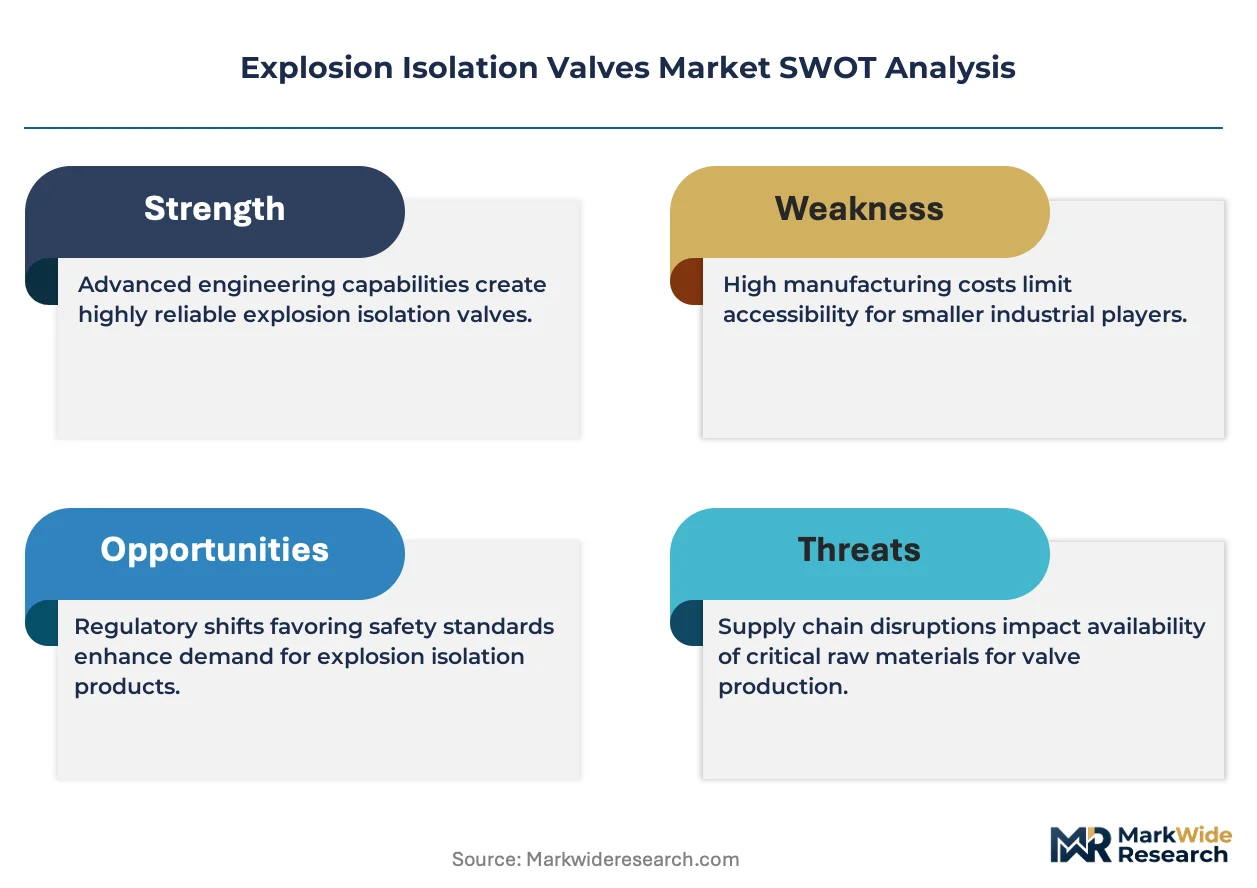
OSHA combustible dust National Emphasis Program enforcement and NFPA 69 standard revisions are mandating documented isolation capability in US manufacturing and chemical facilities, while EU ATEX Directive 2014/34/EU certification requirements block market access for non-compliant equipment across member states. EPA Risk Management Plan amendments for chemical process safety are further tightening documentation requirements for explosion protection system maintenance and testing intervals. Stakeholders must monitor divergence between US and European certification timelines, as asynchronous regulatory updates threaten to fragment product development roadmaps and complicate multinational facility standardization strategies.
Market Dynamics
OSHA combustible dust enforcement and EU ATEX Directive revisions are hardening certification requirements, forcing facility operators to replace passive protection with active isolation systems that demonstrate documented closure performance under 100 milliseconds.
Growth Catalysts
- NFPA 69 standard revisions:US chemical processors must now install certified isolation devices on all interconnected dust handling equipment, creating replacement demand across legacy installations.
- Shale-derived chemical investments:Gulf Coast petrochemical corridor expansions require explosion protection infrastructure sized for high-throughput polyethylene and polypropylene production lines.
- ATEX Directive 2014/34/EU compliance deadlines:German and Dutch process industries are retrofitting aging grain handling and pharmaceutical powder systems to maintain market access.
Market Restraints
- Specialized alloy supply concentration:Nickel-based superalloys for high-temperature valve seats concentrate among a limited supplier base in Scandinavia and Japan.
- Certification timeline friction:Asynchronous US-European approval cycles for new actuation technologies delay product launches by 18-24 months.
- Pneumatic actuator cost volatility:Compressed air system infrastructure requirements add 15-20% to total installed cost versus electric alternatives.
Strategic Opportunities
- Brazilian bioethanol dust handling:Sugar cane processing facility expansions lack indigenous explosion protection suppliers, creating import substitution potential.
- Integrated predictive maintenance:Convergence of pressure wave sensors with distributed control systems enables condition-based replacement contracts.
- India PLI scheme for chemicals:Domestic specialty chemical manufacturing incentives are attracting greenfield investments requiring ATEX-compliant isolation infrastructure.
Industry Challenges
- Control systems integration complexity:Legacy PLC architectures in US Midwest grain elevators resist seamless integration with modern isolation valve actuation protocols.
- Skilled commissioning technician shortage:Functional safety certification for explosion protection system validation remains concentrated among a limited pool of TÜV and exida-certified engineers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Explosion Isolation Valves Market |
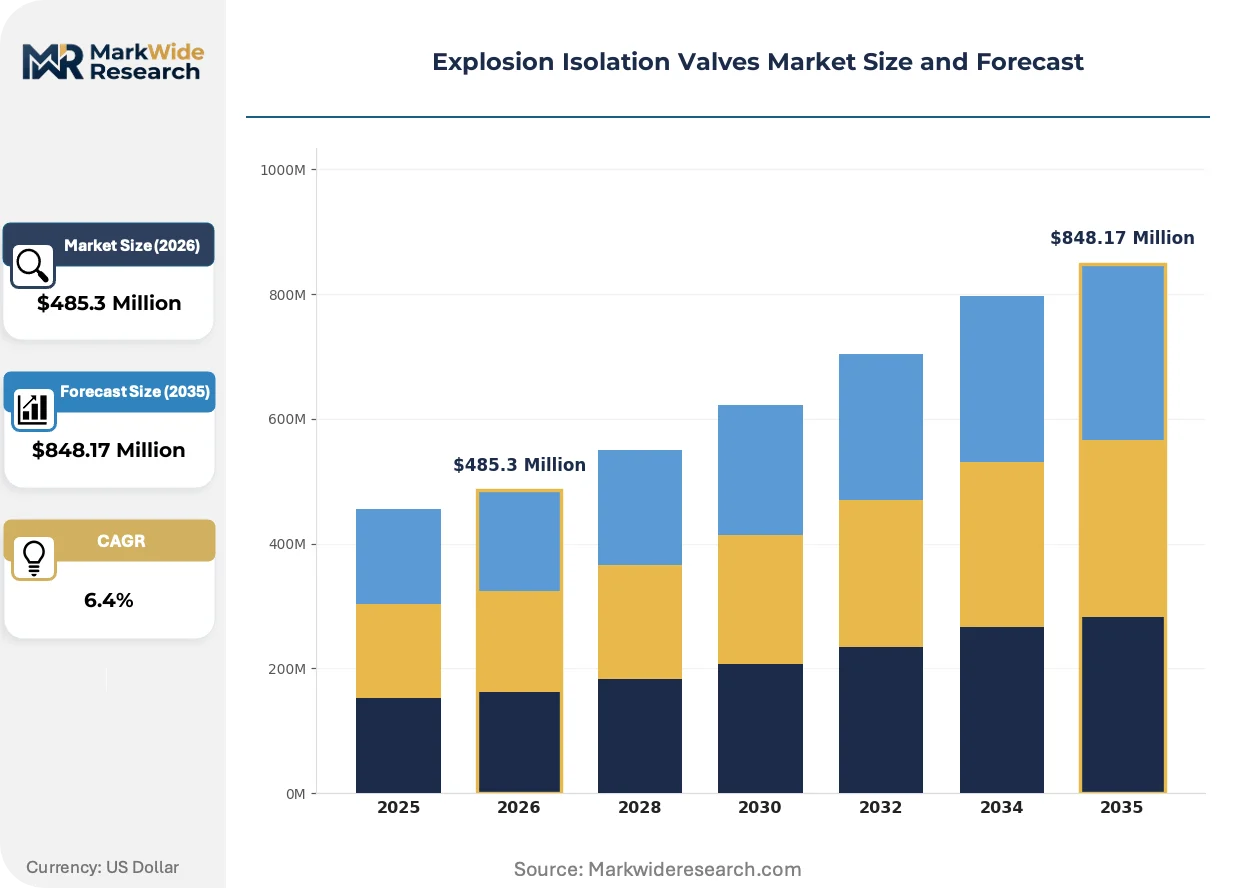
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $848.17 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ball Valves, Butterfly Valves, Gate Valves, Check Valves End User: Manufacturing Facilities, Chemical Plants, Oil & Gas Industries, Power Generation Installation Type: Indoor, Outdoor, High-Risk Areas, Standard Areas Service Type: Maintenance Services, Inspection Services, Replacement Services, Repair Services |
| Companies Covered | Emerson Electric Co., Parker Hannifin Corporation, Danfoss A/S, Fike Corporation, Bosch Rexroth AG, Curtiss-Wright Corporation, Rotork plc, CECO Environmental, CKD Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Explosion Isolation Valves Market Trends and Innovations
Electromechanical actuation and edge-computing sensor networks are compressing response latencies while regulatory documentation requirements force digitization of maintenance records across process industries.
Electro-hydraulic actuation is automating valve closure sequences in high-cycle dust collection applications. Food and beverage processors operating 24-hour spray drying lines are adopting these systems to eliminate pneumatic infrastructure maintenance. The technology is automating the shift from scheduled replacement to predictive intervention based on cycle-count telemetry.
REACH restrictions on per- and polyfluoroalkyl substances are forcing reformulation of valve seat materials in European pharmaceutical and food contact applications. Manufacturers must validate alternative elastomer compounds for thermal stability and chemical resistance. German chemical processors are accelerating qualification timelines to avoid supply disruption during the 2025 enforcement window.
Service unbundling is fragmenting traditional equipment-procurement relationships. US Gulf Coast petrochemical operators now contract inspection and recertification separately from initial valve supply, compressing vendor switching costs. This pattern is most visible among independent engineering-procurement-construction firms managing lump-sum turnkey projects.
Explosion Isolation Valves Market Segmentation
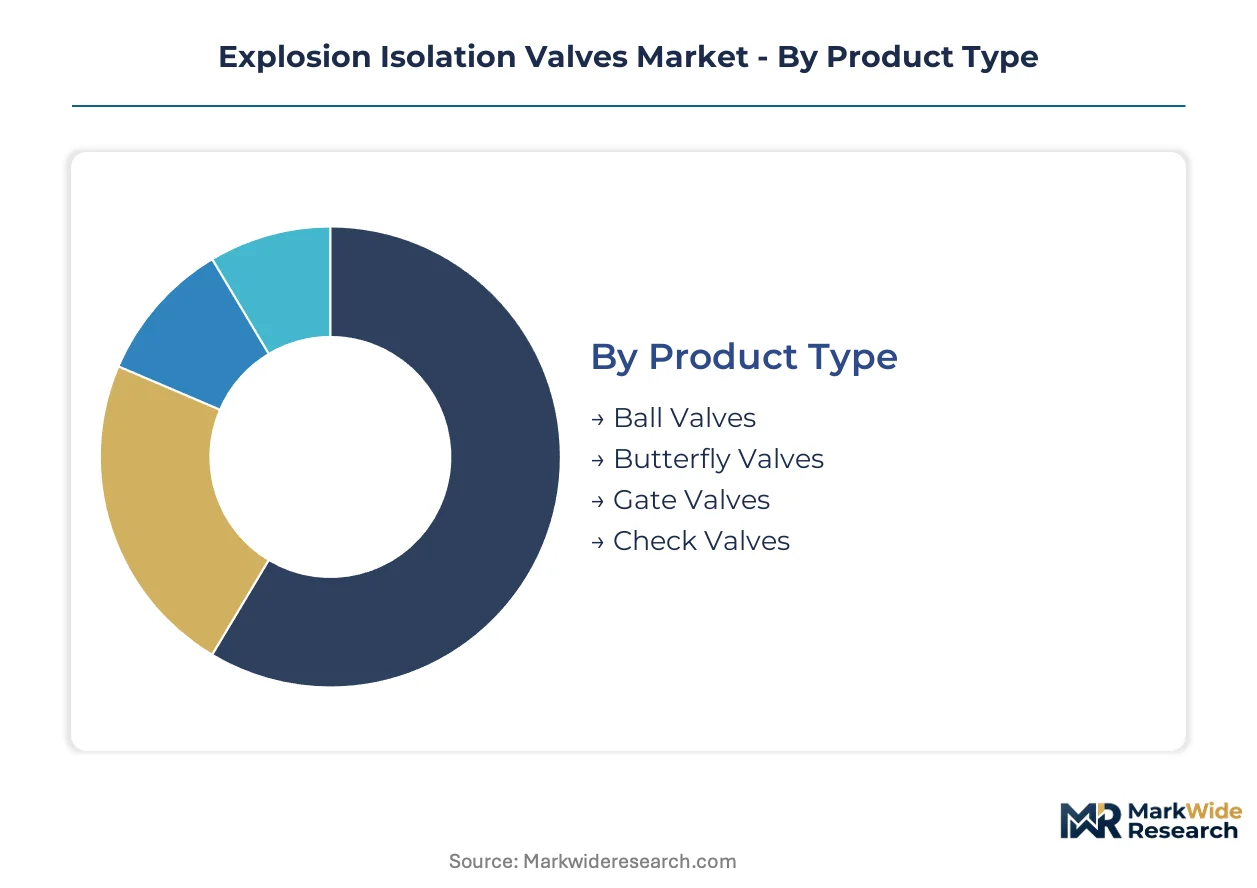
Explosion isolation valve procurement diverges sharply across operational contexts, with product architecture, environmental exposure, and service lifecycle each creating distinct buyer requirements. Facility operators segment their sourcing strategies based on flame propagation risk profiles, maintenance integration needs, and regulatory documentation burdens.
Product Type:
Buyers in this category differentiate primarily by sealing reliability requirements and actuation speed specifications under deflagration conditions.
- Ball Valves:Spherical closure elements achieve bidirectional sealing with pneumatic actuation compatibility, making them dominant in dust handling systems where zero-leakage isolation is mandatory. US Gulf Coast petrochemical processors specify these for polyethylene production lines requiring sub-100 millisecond closure.
- Butterfly Valves:Disc-based designs compete on installed cost and spatial footprint in large-diameter duct applications above 24 inches. German grain handling facilities favor these for retrofit installations where structural modifications are constrained.
- Gate Valves:Linear-motion closure mechanisms suit slurry-laden process streams in mining and minerals processing where particulate abrasion resistance outweighs speed requirements.
- Check Valves:Passive flow-direction devices provide economical backflow prevention in low-risk interconnecting piping where active isolation is not mandated by NFPA 69.
Ball valves lead volumes today; butterfly valves are gaining share fastest in cost-sensitive retrofit applications.
End User:
Procurement sophistication in this category tracks directly with regulatory enforcement intensity and insurance underwriting requirements.
- Chemical Plants:ATEX Directive 2014/34/EU and OSHA combustible dust enforcement mandate documented isolation capability on all interconnected equipment, driving replacement cycles. Dutch pharmaceutical powder processors are retrofitting legacy installations ahead of compliance deadlines.
- Oil & Gas Industries:API and NFPA standards govern specification-driven procurement where flame speed calculations determine valve sizing. US refinery expansions along the Texas-Louisiana corridor require isolation infrastructure sized for high-throughput shale-derived chemical feeds.
- Power Generation:Aging coal and biomass handling infrastructure is shifting toward integrated inspection and replacement service contracts to manage obsolescence risk.
- Manufacturing Facilities:Midwest US grain elevators and food processors face NFPA 69 compliance gaps in legacy PLC architectures resisting modern actuation protocol integration.
Oil and gas commands the largest contract values; chemical plants show the steepest expansion trajectory as enforcement hardens.
Installation Type:
Environmental exposure and hazard zone classification determine material specification and actuator protection requirements.
- High-Risk Areas:Zone 20/21 classified environments demand explosion-proof enclosures and nickel-based superalloy seats for thermal stability. Japanese chemical processors specify these for titanium dioxide handling lines.
- Outdoor:Weather-resistant actuation and corrosion-resistant coatings address coastal petrochemical exposure and freeze-thaw cycling. Brazilian bioethanol facilities import these configurations for sugar cane dust handling.
- Indoor:Controlled environment specifications prioritize compact pneumatic infrastructure and reduced noise signatures for occupied process buildings.
- Standard Areas:Non-classified locations permit economical electric actuation without explosion-proof enclosures, compressing total installed cost.
High-risk installations dominate specification complexity; outdoor configurations are climbing the fastest as greenfield investments shift to coastal and tropical geographies.
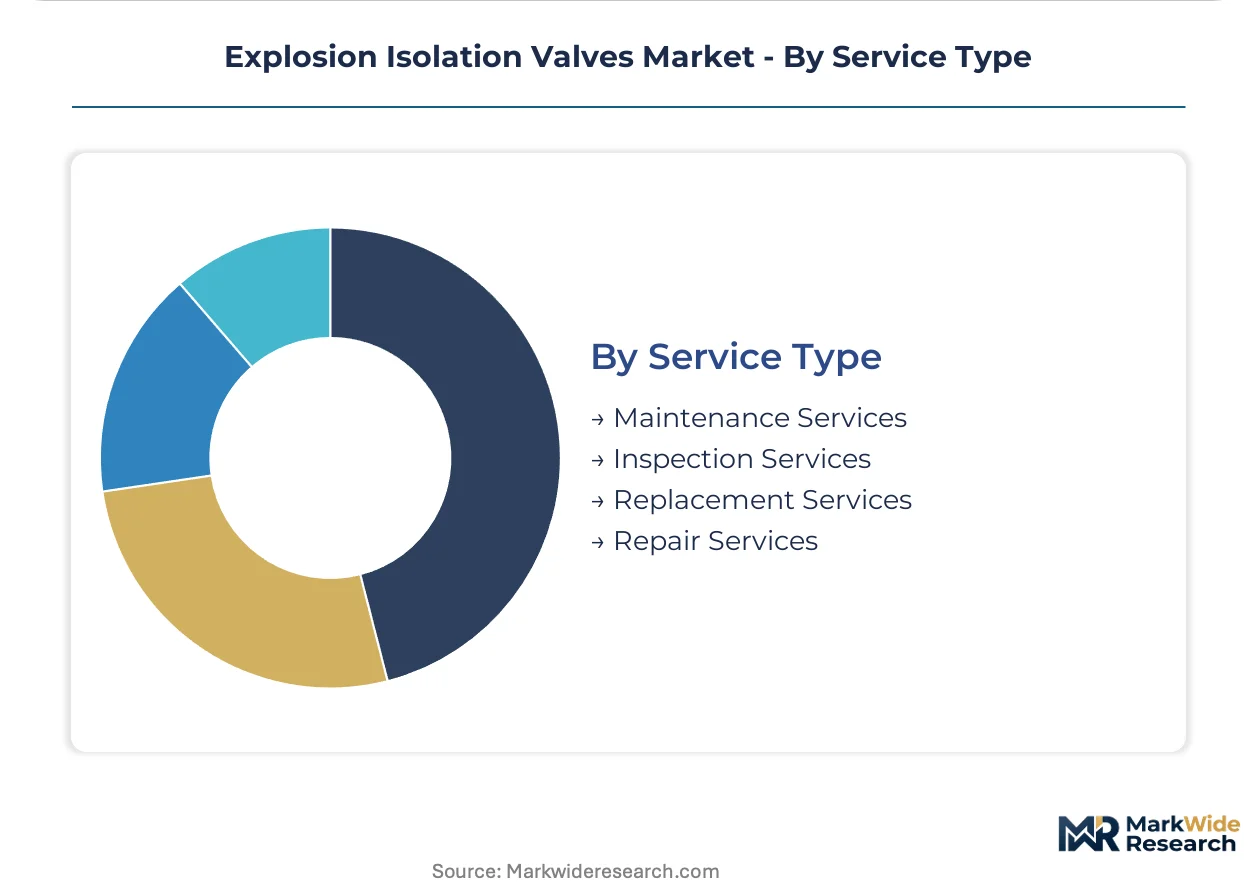
Service Type:
Contract structure preferences in this category reflect facility operator capabilities and regulatory documentation burdens.
- Inspection Services:Third-party validation of closure timing and seal integrity is unbundling from equipment supply, compressing vendor switching costs among US Gulf Coast EPC-managed projects.
- Maintenance Services:Predictive intervention contracts based on cycle-count telemetry are replacing scheduled replacement in 24-hour food and beverage spray drying operations.
- Replacement Services:Turnkey swap-out contracts address obsolescence in aging coal handling infrastructure where spare parts availability has degraded.
- Repair Services:Component-level refurbishment extends service life in budget-constrained grain elevator operations.
Inspection services lead contract proliferation today; predictive maintenance is expanding most quickly as sensor integration matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Explosion isolation valve manufacturing originated in German industrial centers during post-war chemical sector expansion, with Ruhr Valley process safety engineering establishing foundational ATEX certification protocols that now govern European procurement standards.
United States
Gulf Coast petrochemical corridor investments in polyethylene and polypropylene production lines are driving specification-grade isolation valve demand. OSHA combustible dust National Emphasis Program enforcement mandates documented sub-100 millisecond closure capability on all interconnected dust handling equipment. Texas-Louisiana refinery expansions require flame speed-calculated valve sizing for high-throughput shale-derived chemical feeds.
Germany
Ruhr Valley and Bavarian chemical processors are retrofitting legacy pharmaceutical powder and grain handling systems ahead of ATEX Directive 2014/34/EU compliance deadlines. REACH restrictions on per- and polyfluoroalkyl substances are forcing accelerated qualification of alternative valve seat elastomers before 2025 enforcement windows. Frankfurt-Rhine-Main pharmaceutical clusters are unbundling inspection contracts from equipment supply to compress vendor switching costs.
China
Yangtze River Delta specialty chemical manufacturing zones are attracting greenfield investments requiring explosion protection infrastructure under tightening MIIT process safety guidelines. Dual carbon policy implementation is accelerating coal handling infrastructure upgrades with integrated isolation systems. Shandong Peninsula petrochemical complexes are importing ATEX-certified designs for titanium dioxide and carbon black production lines.
Brazil
São Paulo state sugar cane processing and bioethanol dust handling facility expansions lack indigenous explosion protection suppliers, creating import substitution opportunities. ANVISA pharmaceutical manufacturing regulations are harmonizing with EU ATEX standards for active pharmaceutical ingredient production. Paulínia petrochemical hub investments require coastal-grade weather-resistant actuation systems for tropical exposure conditions.
India
Gujarat and Maharashtra specialty chemical manufacturing zones are expanding under PLI scheme incentives that mandate ATEX-compliant isolation infrastructure for export market access. CDSCO pharmaceutical regulations are converging with EU standards for active ingredient processing facilities. Dahej and Mundra petrochemical corridors require explosion protection systems sized for import-substituted polyethylene production.
Explosion Isolation Valves Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the explosion isolation valve market. Integrated automation conglomerates with captive foundry and actuator manufacturing capabilities command premium positioning in specification-driven oil and gas procurement. Specialized explosion protection engineering firms compete on rapid-actuation technology and flameless venting integration. The vendor base separates into three archetypes: full-stack automation platforms, dedicated explosion safety specialists, and component-focused actuator manufacturers. Dominant competitive moves include strategic partnerships with engineering-procurement-construction firms and geographic expansion through certification body relationships.
Within the integrated automation tier, Emerson Electric Co. and Danfoss A/S represent capital-intensive positioning with electromechanical and hydraulic actuator expertise. Fike Corporation exemplifies the specialized explosion protection archetype with rapid-actuation flameless venting capabilities. These three anchors demonstrate how vendor strategy diverges between distributed control system integration and standalone deflagration response specialization.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Parker Hannifin Corporation |
| Danfoss A/S |
| Fike Corporation |
| Bosch Rexroth AG |
| Curtiss-Wright Corporation |
| Rotork plc |
| CECO Environmental |
| CKD Corporation |
| Others |
Pricing and Supply Chain Analysis
ATEX-certified premium tier separation from economy-grade pneumatic alternatives manifests in both procurement budgets and supplier geography, with German and Japanese electromechanical actuator specialists commanding margin premiums while Chinese commodity pneumatic suppliers compete on total installed cost compression.
Pricing Analysis
Three-tier pricing structure across ATEX-certified premium, NFPA-compliant standard, and non-certified economy levels governs contract negotiations. Price differentiation rests on certification grade and after-sales service bundling, with inspection and recertification contracts unbundling from equipment supply. Cost compression in economy pneumatic tiers is intensifying because Brazilian and Indian buyers prioritize upfront capital expenditure minimization over lifecycle performance documentation. Midwest US grain elevators exhibit highest price sensitivity; Gulf Coast petrochemical operators show lowest sensitivity due to insurance underwriting mandates.
Supply Chain Analysis
Freight cost volatility for nickel-based superalloy valve seats from Scandinavia and Japan compresses margins on premium tier shipments to Brazil and India. Geographic supply concentration centers on Germany for ATEX-certified electromechanical actuators, China for pneumatic infrastructure components, and the United States for flame speed calculation engineering services. Raw material dependencies draw from Japanese specialty steel foundries, German precision machining centers, and Chinese aluminum die-casting operations. Single-source vulnerability in nickel alloy supply threatens delivery reliability. Distribution runs through engineering-procurement-construction firms managing lump-sum turnkey projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as enforcement hardening shifts procurement toward documented sub-100 millisecond closure performance and predictive maintenance integration.
For Market Incumbents: Deepen captive foundry control over nickel-based superalloy seat production to defend against Scandinavian supply concentration risk. Expand TÜV and exida-certified commissioning technician training programs to capture unbundled inspection service contracts. Reinforce distributed control system integration capabilities as legacy PLC architectures in US Midwest grain elevators resist modern actuation protocol adoption. For New Entrants and Emerging Players: The price-point gap between ATEX-certified German electromechanical systems and Chinese pneumatic alternatives creates entry space for mid-tier hybrid actuation. Target Brazilian bioethanol dust handling facilities lacking indigenous explosion protection suppliers. Pursue sugar cane processing import substitution through ANVISA-harmonized certification pathways and tropical-grade weather-resistant actuator configurations. For Investors and Strategic Acquirers: Consolidation pressure builds where functional safety certification scarcity concentrates among limited TÜV and exida-certified engineering pools. Long-term viability favors asset-light designers with rapid-actuation intellectual property over capital-heavy integrated automation platforms dependent on captive manufacturing scale. Watch for electro-hydraulic actuation adoption inflection in 24-hour food and beverage spray drying lines as predictive maintenance contract proliferation signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Superalloy Foundry Capacity | Secures nickel-based valve seat supply against Scandinavian concentration risk. |
| Electro-Hydraulic Actuation Platform Launch | Eliminates pneumatic infrastructure maintenance for 24-hour spray drying operations. |
| ATEX Certification Body Partnership Expansion | Accelerates market access across EU member states and harmonized jurisdictions. |
| Predictive Maintenance Service Contract Unbundling | Captures recurring revenue from pressure wave sensor and cycle-count telemetry integration. |
| Brazilian Bioethanol Sector Geographic Expansion | Addresses import substitution demand in sugar cane processing facility expansions. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads with secondary validation against SEC 10-K filings, customs and trade data, ACC and Cefic industry reports, and NFPA standard documentation. Bottom-up installation tracking and top-down petrochemical capital expenditure analysis provided cross-verification.
Comparable-period anchoring against historical ATEX Directive implementation cycles and OSHA National Emphasis Program enforcement waves structured the projection horizon. Segmentation dimensions modeled include product architecture, end-use industry, installation environment classification, and service contract structure. CAGRs derived from regression analysis of shale-derived chemical investment flows and regulatory compliance deadline clustering. Forecast inputs incorporated electromechanical actuation adoption curves and REACH restriction timeline impacts on valve seat material qualification.
The model assumes a particular technology adoption path; alternative pathways for edge-computing sensor networks would alter the outlook. Forecasts reflect assumptions about asynchronous US-European certification timeline convergence and nickel alloy supply concentration persistence. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Steel Cylinder Market
Valves
Servo Valves Market
Valves
Carbon Seal Rings Market
Valves
Compressor Valves Market
Valves
Liner Regulators Market
Valves
Motorized Valves Market
Valves
Static Seals Market
Valves
Air Heated Vaporizer Market
Valves
Electrohydraulic Servo Valves (Ehsvs) Market
Valves
Industrial Vacuum Valves Market
Valves
Global Marine Actuators and Valves Market
Valves
Curb Valves Market
Valves
Mechanical Shaft Seal Market
Valves
Diaphragm Valve Market
Valves
Explosion Vents Market
Valves
Thermal Power Valve Market