
 Industrial Vacuum Valves Market | 2026-2036
Industrial Vacuum Valves Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Vacuum Valves Market Outlook
Semiconductor fabs are bifurcating from general manufacturing as the dominant buyer archetype for precision vacuum valves. VAT Group AG leverages ceramic sealing technology to anchor the high-purity segment for chip fabrication. Pfeiffer Vacuum Technology AG sustains R&D intensity in integrated vacuum solutions. MKS Instruments Inc. competes through its dominance in pressure measurement and gas flow control adjacent to valve systems.
Industrial vacuum valves regulate gas flow in evacuated environments, typically achieving leak rates below 10⁻⁹ mbar·l/s through metal-to-metal or elastomer sealing architectures. Gate valves command the largest product category share due to their straight-through conductance and minimal particle generation in semiconductor process chambers. Stainless steel material grades dominate procurement specifications where outgassing constraints are strictest, while aluminum variants gain traction in weight-sensitive aerospace applications. Research laboratories represent a concentrated end-user segment for custom-configured ultra-high vacuum assemblies.
ISO 21360 defines vacuum pump and valve performance measurement protocols that manufacturers must certify against for cross-border equipment acceptance. EPA regulations in the United States restrict fluorinated greenhouse gas emissions from certain vacuum processes, redirecting demand toward dry pumping architectures with compatible valve trains. Semiconductor fabs in South Korea face MFDS pharmaceutical-adjacent contamination standards when producing biochip substrates. Stakeholders must monitor how evolving clean energy subsidies in China and the European Union redirect capital toward green hydrogen production, a vacuum-intensive application with distinct valve specification requirements.
Market Dynamics
EUV lithography deployment in semiconductor fabrication is compressing valve procurement cycles and elevating ceramic sealing specifications above legacy elastomer alternatives. This technology pull is restructuring supplier qualification protocols across East Asian manufacturing clusters.
Growth Catalysts
- EUV Lithography Expansion:Semiconductor fabs in South Korea and Taiwan are accelerating orders for all-metal gate valves capable of sustaining sub-10⁻¹⁰ mbar·l/s leak integrity during high-frequency cycling.
- China's Dual Carbon Goals:NMPA compliance mandates for hydrogen production equipment are redirecting procurement toward stainless steel valve trains compatible with dry pumping architectures.
- Green Hydrogen Infrastructure:European Union clean energy subsidies are stimulating vacuum-intensive electrolyzer builds requiring specialized high-conductance isolation valves.
Market Restraints
- Raw Material Concentration:Specialty stainless steel feedstock for ultra-high purity grades concentrates among a limited supplier base in Germany and Japan, creating input cost volatility.
- Technical Certification Barriers:ISO 21360 testing protocols for cross-border equipment acceptance impose extended validation timelines that delay new entrant market access.
- Substitution Pressure:Integrated vacuum modules combining valve, pump, and measurement functions are displacing standalone valve procurement in mid-tier research laboratory segments.
Strategic Opportunities
- India Manufacturing Buildout:PLI scheme incentives for semiconductor packaging are creating first-mover openings for valve suppliers establishing local service infrastructure.
- Regulatory Tailwind:EPA fluorinated greenhouse gas restrictions are mandating dry pump retrofits in legacy US fabs, generating replacement valve demand compatible with oil-free architectures.
- Technology Convergence:Integration of additive manufacturing with conventional CNC finishing is enabling rapid prototyping of custom ultra-high vacuum geometries for research applications.
Industry Challenges
- Specialized Welding Talent Scarcity:Electron beam welding certification for all-metal valve assemblies requires multi-year apprenticeship pipelines that lag current demand acceleration.
- Legacy System Integration Friction:Retrofitting modern valve positioners into 1990s-era semiconductor process chambers demands custom mechanical adapters that extend commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Vacuum Valves Market |
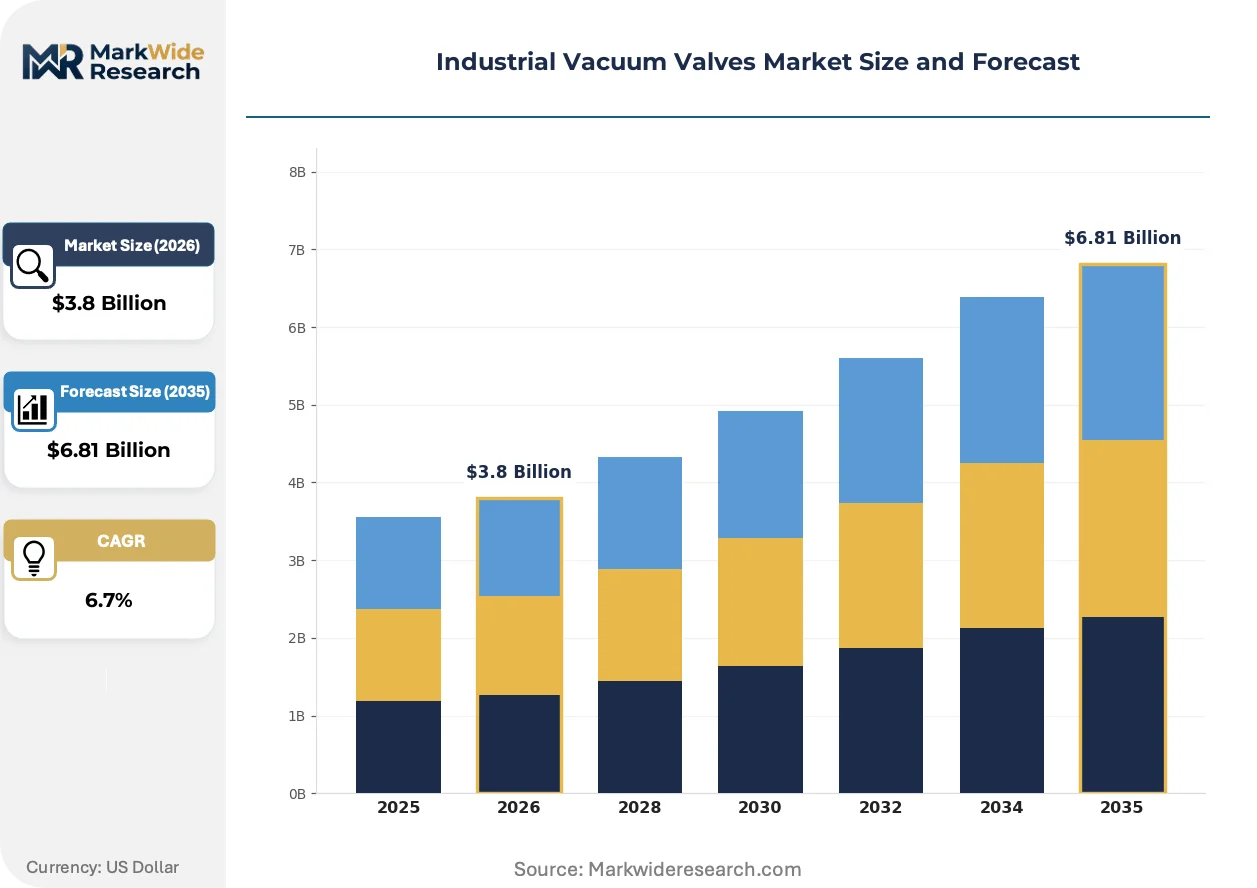
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gate Valves, Globe Valves, Check Valves, Ball Valves Material: Stainless Steel, Aluminum, Brass, PVC Application: Aerospace, Pharmaceutical, Food Processing, Semiconductor End User: Manufacturing, Research Laboratories, Automotive, Energy |
| Companies Covered | Parker Hannifin Corp., MDC Vacuum Products LLC, VAT Group AG, Atlas Copco AB, Agilent Technologies Inc., Pfeiffer Vacuum Technology AG, Kurt J Lesker Co., SMC Corp., MKS Instruments Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Vacuum Valves Market Strategic Shifts
Ceramic sealing architectures are displacing incumbent technologies across precision applications. Regulatory frameworks are rewriting material compliance boundaries. Procurement behavior is compressing toward integrated solution sourcing.
All-metal valve designs with aluminum oxide ceramic seals are displacing fluoroelastomer alternatives in EUV lithography process chambers. TSMC and Samsung Foundry have accelerated adoption timelines from qualification to volume procurement within eighteen-month windows. This displacement is compressing the addressable market for polymer-sealed valves in sub-10⁻⁹ mbar applications.
REACH restrictions on perfluorinated compounds are forcing reformulation of valve lubricants and seal materials across European semiconductor equipment supply chains. Manufacturers must now certify alternative chemistries through ECHA substance evaluation protocols before component integration. German valve suppliers are responding by accelerating in-house fluorine-free coating development programs.
Fab operators are consolidating valve procurement under integrated vacuum system contracts rather than discrete component sourcing. This behavioral shift concentrates purchasing authority with MKS Instruments and VAT Group AG at the expense of standalone valve distributors. The pattern is most pronounced in South Korea, where Samsung and SK Hynix have unbundled maintenance contracts from initial equipment purchases.
Industrial Vacuum Valves Market Segmentation
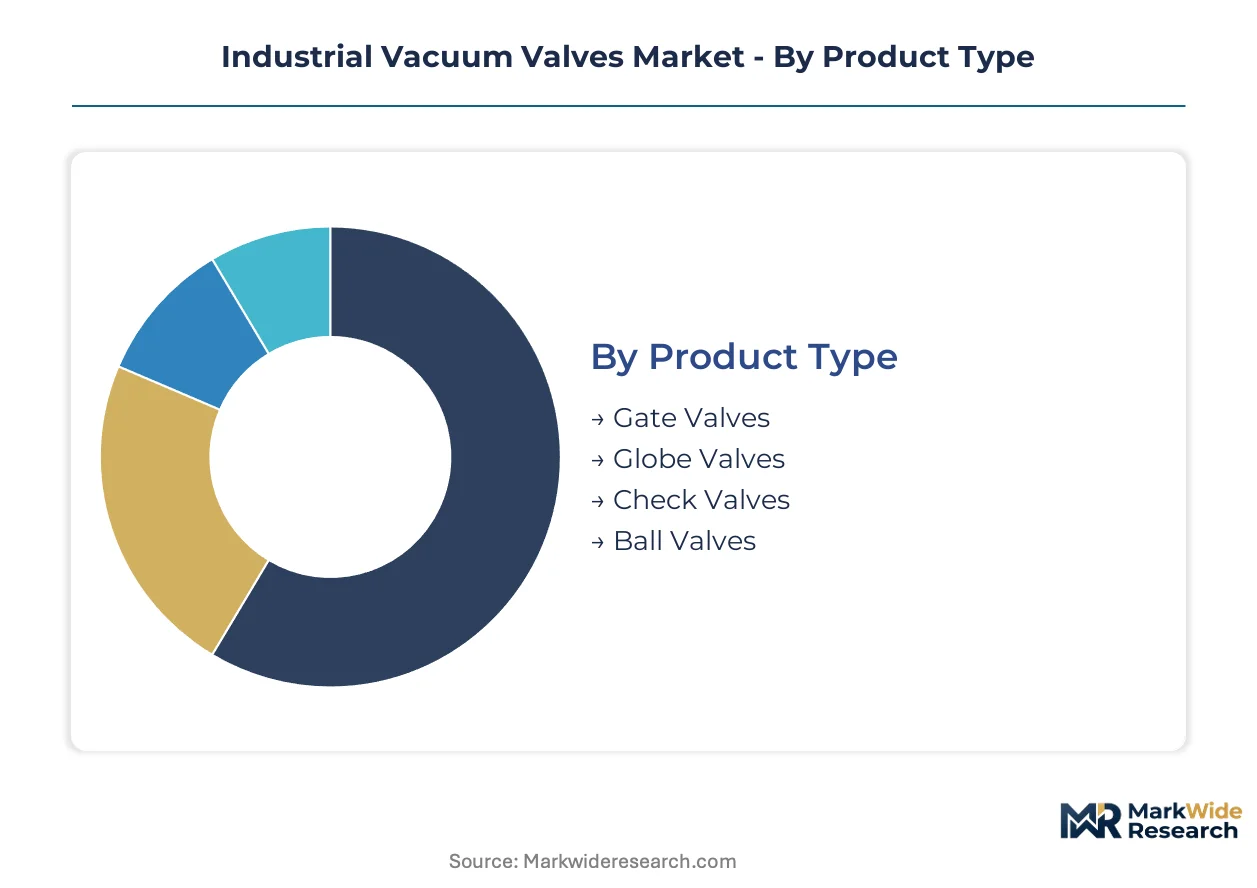
Segmentation in industrial vacuum valves reveals distinct margin architectures across sealing technologies and purity grades. Procurement patterns diverge sharply between semiconductor fabs demanding sub-10⁻¹⁰ mbar integrity and general manufacturing tolerating 10⁻⁶ mbar thresholds.
Product Type:
Margin pools concentrate in high-cycle gate valve architectures where ceramic sealing commands premium positioning over elastomer alternatives.
- Gate Valves:Metal-to-metal or ceramic-sealed designs achieve straight-through conductance with minimal particle generation. TSMC and Samsung Foundry procurement concentrates here for EUV lithography process chambers where leak integrity must sustain sub-10⁻¹⁰ mbar·l/s during high-frequency cycling.
- Globe Valves:Throttling precision suits roughing pump isolation and gas flow modulation. Demand clusters in pharmaceutical lyophilization equipment where MFDS contamination standards apply, though procurement volumes trail gate valve orders in semiconductor capital expenditure cycles.
- Check Valves:Unidirectional flow protection for backing pump trains.
- Ball Valves:Quarter-turn actuation suits rapid isolation in industrial vacuum coating systems.
Gate valves hold installed capacity across legacy fabs. Globe valves are rotating up the share rankings in biopharmaceutical vacuum applications.
Material:
Cost tier stratification separates ultra-high purity stainless steel specifications from weight-driven aluminum alternatives.
- Stainless Steel:316L and 316LN grades dominate where outgassing constraints are strictest, with electron beam welded assemblies achieving 10⁻¹² mbar·l/s helium leak rates. NMPA compliance mandates for hydrogen production equipment in China redirect procurement toward these grades compatible with dry pumping architectures.
- Aluminum:6061-T6 and A6063 variants gain traction in aerospace satellite propulsion systems where mass reduction outweighs outgassing penalties. NASA and ESA procurement specifications favor these for attitude control thruster isolation valves.
- Brass:Cost-effective for rough vacuum instrumentation and educational laboratory equipment.
- PVC:Limited to corrosive gas handling in chemical process industries below 10⁻³ mbar operating pressures.
Stainless steel maintains dominant share in semiconductor capital equipment. Aluminum is climbing fastest in space systems procurement.
Application:
Volume concentration tracks East Asian manufacturing cluster expansion, with technology pull from EUV lithography reshaping segment priorities.
- Semiconductor:EUV lithography deployment compresses valve procurement cycles and elevates all-metal ceramic-sealed specifications above legacy fluoroelastomer alternatives. South Korean and Taiwanese fabs now qualify suppliers within eighteen-month windows, restructuring supplier access protocols.
- Pharmaceutical:Lyophilization and freeze-drying equipment demands steam-sterilizable vacuum isolation. European REACH restrictions on perfluorinated compounds force reformulation of valve lubricants and seal materials through ECHA substance evaluation protocols.
- Aerospace:Satellite propulsion and space simulation chambers drive lightweight aluminum valve specifications.
- Food Processing:Vacuum packaging and freeze-drying applications prioritize sanitary surface finishes over extreme leak integrity.
Semiconductor applications anchor current revenue concentration. Pharmaceutical demand is expanding most quickly on biochip substrate production growth.
End User:
Customer type determines procurement behavior, with integrated vacuum system contracts displacing discrete component sourcing in consolidated buyer segments.
- Manufacturing:Semiconductor fabs and industrial coating operations drive volume procurement under multi-year framework agreements. Samsung and SK Hynix in South Korea have unbundled maintenance contracts from initial equipment purchases, concentrating purchasing authority with integrated vacuum solution providers.
- Research Laboratories:Custom-configured ultra-high vacuum assemblies for materials science and particle physics. CERN, DESY, and national laboratory procurement favors bespoke geometries with extended qualification timelines.
- Automotive:EV battery dry room vacuum systems and fuel cell test stands.
- Energy:Green hydrogen electrolyzer builds requiring high-conductance isolation valves under EU clean energy subsidies.
Manufacturing end users command dominant procurement volumes. Research laboratories represent the steepest expansion trajectory for additive-manufactured custom geometries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German stainless steel valve exports supply East Asian semiconductor fabs, while Chinese manufacturers redirect capacity toward domestic hydrogen infrastructure under NMPA compliance mandates. Trade corridors now prioritize material certification compatibility over pure cost arbitrage.
China
NMPA compliance mandates for hydrogen production equipment are redirecting procurement toward stainless steel valve trains compatible with dry pumping architectures. The dual carbon goals framework imposes stricter material traceability requirements on vacuum component suppliers. Yangtze River Delta manufacturing clusters are absorbing expanded domestic capacity for electrolyzer isolation valves.
South Korea
Samsung Foundry and SK Hynix are accelerating orders for all-metal gate valves sustaining sub-10⁻¹⁰ mbar·l/s leak integrity during high-frequency EUV lithography cycling. MFDS pharmaceutical-adjacent contamination standards apply to biochip substrate production facilities. Seoul Capital Area fabs now compress supplier qualification windows to eighteen months.
Taiwan
TSMC procurement concentrates on ceramic-sealed gate valves for EUV process chambers with minimal particle generation specifications. The island's semiconductor equipment supply chain maintains tight integration with Japanese specialty steel feedstock suppliers. Hsinchu Science Park anchors the densest concentration of ultra-high purity valve qualification activity worldwide.
United States
EPA fluorinated greenhouse gas restrictions are mandating dry pump retrofits in legacy fabs, generating replacement valve demand compatible with oil-free architectures. Clean energy subsidies under the IRA are stimulating vacuum-intensive electrolyzer builds in Texas and California. Greater Boston research laboratories represent concentrated demand for custom-configured ultra-high vacuum assemblies.
Germany
REACH restrictions on perfluorinated compounds are forcing reformulation of valve lubricants and seal materials through ECHA substance evaluation protocols. Bavaria-based fabricators concentrate electron beam welding certification capacity for all-metal valve assemblies. Stuttgart and Munich industrial clusters supply specialty 316LN stainless steel grades to global semiconductor equipment OEMs.
Industrial Vacuum Valves Market Competitive Environment
Listed leaders compete with private specialists across sealing technology and material purity tiers. The market exhibits moderate consolidation around integrated vacuum solution providers, with standalone valve distributors facing procurement authority erosion. Three archetypes dominate: ceramic-sealed precision specialists, stainless steel fabrication scale players, and diversified instrumentation conglomerates with valve-adjacent portfolios. Competitive moves concentrate on M&A for welding certification capacity and strategic partnerships for East Asian fab access.
Among Swiss- and German-based precision fabricators, VAT Group AG and Pfeiffer Vacuum Technology AG exemplify the ceramic-sealed specialist archetype, while MKS Instruments Inc. represents the diversified instrumentation tier with vacuum-adjacent positioning. These three entities anchor different competitive vectors without overlapping core specializations. Private specialists including MDC Vacuum Products LLC and Kurt J Lesker Co. occupy positions in custom research laboratory segments where qualification timelines extend and volume procurement contracts prove less decisive.
| Leading Market Players |
|---|
| Parker Hannifin Corp. |
| MDC Vacuum Products LLC |
| VAT Group AG |
| Atlas Copco AB |
| Agilent Technologies Inc. |
| Pfeiffer Vacuum Technology AG |
| Kurt J Lesker Co. |
| SMC Corp. |
| MKS Instruments Inc. |
| Others |
Value Chain & Pricing Dynamics
Eighteen-month supplier qualification windows in EUV lithography procurement compress inventory buffers and amplify pricing power for certified ceramic-sealed valve fabricators. This lead-time compression concentrates margin capture with electron beam welding specialists in Germany and Japan while forcing buyers into premium tier acceptance.
Pricing Analysis
The technology-generation pricing gap separates ceramic-sealed all-metal valves commanding premium positioning from fluoroelastomer alternatives facing rapid share erosion. Three-tier pricing structure across premium, standard, and economy levels stratifies by helium leak rate certification, with sub-10⁻¹⁰ mbar·l/s grades extracting maximum value from TSMC and Samsung Foundry procurement. Cost compression in polymer-sealed mid-tier products intensifies as integrated vacuum modules displace standalone valve demand. Research laboratories exhibit highest price sensitivity due to fragmented procurement volumes, while semiconductor fabs accept premium positioning to secure qualification continuity.
Supply Chain Analysis
Strategic stockpile preferences dominate among East Asian fabs maintaining six-month ceramic seal inventories against German and Japanese supply concentration. Specialty 316LN stainless steel feedstock draws from crucible melt capacity in Bavaria and Niigata Prefecture, with electron beam welding certification creating single-source vulnerability for all-metal assemblies. Tariff exposure on precision-machined valve bodies shipped from Stuttgart to Hsinchu Science Park compounds input cost volatility. Distribution runs through integrated vacuum system contracts with MKS Instruments and VAT Group AG, displacing standalone distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multi-year electron beam welding apprenticeship pipelines lag demand acceleration by forty percent, constraining capacity expansion for all-metal valve fabricators regardless of capital availability. This skill scarcity locks in incumbent positioning while delaying new entrant qualification timelines.
For Market Incumbents: Secure captive electron beam welding certification capacity through apprenticeship program expansion in Stuttgart and Munich industrial clusters. Deepen backward integration into specialty 316LN stainless steel feedstock through offtake agreements with German crucible melt suppliers, insulating against raw material concentration risk from Japanese competitors. For New Entrants and Emerging Players: Aftermarket service infrastructure gaps in India's PLI scheme semiconductor packaging corridors offer white-space entry with lower qualification barriers than EUV lithography procurement. Target hydrogen electrolyzer isolation valve demand under China's NMPA compliance mandates, where eighteen-month qualification windows have not yet compressed. Pursue additive manufacturing-enabled rapid prototyping for CERN and DESY research laboratory contracts. For Investors and Strategic Acquirers: Long-term, this sits as a welding-certification scarcity play because electron beam apprenticeship pipelines require decade-long maturation regardless of capital injection. Acquire mid-cap specialists with existing ISO 21360 certification infrastructure rather than greenfield qualification attempts. Watch EUV lithography deployment cadence at Samsung Foundry and TSMC as inflection signal for ceramic-sealed valve demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Electron Beam Welding Certification Expansion | Multi-year apprenticeship pipelines lock in supply-constrained pricing power for Bavarian fabricators. |
| Ceramic Seal Material Backward Integration | Captive aluminum oxide supply insulates VAT Group AG and Pfeiffer Vacuum from Japanese feedstock volatility. |
| India Service Infrastructure Localization | PLI scheme semiconductor packaging creates first-mover advantage for maintenance contract bundling. |
| Hydrogen Electrolyzer Valve Qualification | NMPA compliance mandates in China redirect procurement toward stainless steel dry-pumping architectures. |
| Additive Manufacturing Capability Acquisition | Rapid prototyping of custom ultra-high vacuum geometries captures CERN and national laboratory demand. |
Study Parameters
Operator-level perspectives from semiconductor fab procurement directors, electron beam welding technicians, vacuum system integration engineers, and hydrogen electrolyzer EPC contractors anchored the qualitative base. Primary interview findings triangulated against secondary validation from SEC 10-K filings of listed vacuum equipment manufacturers, ISO 21360 certification registries, and customs trade data for specialty stainless steel valve body exports. Bottom-up demand modeling across end-use segments converged with top-down macroeconomic indicators for industrial capital expenditure cycles.
Sensitivity analysis tested forecast robustness against EUV lithography deployment acceleration scenarios and Chinese dual carbon policy stringency variations. Segmentation dimensions modeled include sealing technology architecture, material purity grade, application vertical, end-user procurement behavior, and regional regulatory cluster. CAGRs derived from regression analysis of historical capital equipment procurement cycles projected across the analysis window. Industry-specific inputs incorporated semiconductor fab buildout pipelines and green hydrogen electrolyzer project development databases.
Underlying assumptions cover sustained EUV lithography adoption timelines and NMPA compliance enforcement continuity, with deviation risk concentrated in raw material supply disruptions from German and Japanese specialty steel producers. Forecasts reflect these documented assumptions with explicit scenario boundaries. Revision becomes warranted when electron beam welding certification capacity expansion crosses thresholds that eliminate current scarcity premiums.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Steel Cylinder Market
Valves
Sand Control System Market
Valves
Electro Pneumatic Positioner Market
Valves
Valve Grinder Market
Valves
Battery Safety Valve Market
Valves
Sanitary Valves Market
Valves
Total Containment Vessels Market
Valves
Fluid Power Cylinder Market
Valves
Pipeline Pigging Valves Market
Valves
Steam Safety Valve Market
Valves
Pipeline Pigging Equipment Market
Valves
Pressure Gauge Market
Valves
Off-Highway Hydraulic Valve Actuator Systems Market
Valves
Explosion Proof Solenoid Valves Market
Valves
Industrial Hydraulic Filters Market
Valves
Cryogenic Valve Market