
 Valve Sack Market | 2026-2036
Valve Sack Market Size, Share, and Industry Trends Forecast 2026-2036
Valve Sack Market Analytics
Multi-source procurement among construction material suppliers is realigning how valve sack volumes flow across regional converters. Mondi Group leverages its European paper-based sack capacity to anchor premium cement packaging contracts. Smurfit Kappa Group competes through integrated kraft paper supply chains that sustain margin control across multiple capacity tiers. Stora Enso Oyj differentiates via biobased barrier coatings that extend product shelf integrity for chemical and food-grade applications.
A valve sack is a pre-formed industrial bag incorporating a one-way filling valve that permits high-speed pneumatic loading of powdered or granular materials while preventing backflow; standard constructions employ multi-ply kraft paper or woven polypropylene with PE liners achieving burst strengths of 150–300 kN/m. Its primary purpose centers on dust-free, automated filling of cement, chemicals, and food commodities at rates exceeding 3,000 bags per hour. Polypropylene material types dominate volume due to moisture resistance and recyclability advantages in tropical climates, though paper constructions retain margin superiority in European food-grade segments. The 25 kg and 50 kg capacity tiers concentrate demand across construction and agriculture end users where manual handling norms persist.
EMA's evolving food contact material guidelines and REACH chemical restrictions are reshaping substrate selection and adhesive formulations for European valve sack converters. China's SAMR enforces GB standards for plastic food contact materials that limit recycled content ratios in woven polyethylene constructions destined for domestic food Industry buyers. India's BIS certification mandates for woven sacks used in fertilizer distribution are tightening tensile strength and UV stability benchmarks. Stakeholders must monitor how divergent regional compliance timelines reshape cross-border sourcing economics and localized production investments.
Market Dynamics
REACH compliance deadlines and China's evolving GB standards are forcing substrate substitutions across woven polypropylene supply chains, compressing converter margins while elevating certified producers.
Growth Catalysts
- Emerging economy food packaging:India's agriculture sector intensifies fertilizer procurement, driving 50 kg woven sack volumes through BIS-mandated distribution channels.
- REACH chemical restrictions:ECHA's evolving adhesive formulation limits accelerate biobased barrier coating adoption in European kraft paper constructions.
- Automated filling speeds:Pneumatic loading systems exceeding 3,000 bags per hour cement valve sack indispensability in cement and chemical processing.
Market Restraints
- Polypropylene feedstock volatility:Crude-linked resin pricing squeezes margin predictability for tropical-climate converters dependent on woven PE constructions.
- European supply concentration:Premium kraft paper capacity clusters in Nordic and Alpine regions, exposing buyers to logistics cost spikes during energy price shocks.
- Recycled content limits:SAMR's GB standards cap post-consumer ratios in Chinese food-contact woven sacks, constraining circular economy claims.
Strategic Opportunities
- India fertilizer distribution:BIS certification mandates for UV-stable woven sacks create certified-supplier premiums in government procurement channels.
- Biobased barrier convergence:Stora Enso's coating chemistry merges with Mondi's European paper capacity to capture chemical-grade shelf-life extensions.
- Sustainable packaging incentives:EU Green Deal procurement rules favor kraft-based valve sacks in public infrastructure cement contracts.
Industry Challenges
- Multi-standard compliance talent:Converters struggle to staff regulatory specialists fluent in REACH, GB standards, and BIS certification simultaneously.
- Legacy equipment retrofitting:Existing paper sack lines require capital-intensive modifications to handle biobased coating chemistries at commercial speeds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Valve Sack Market |
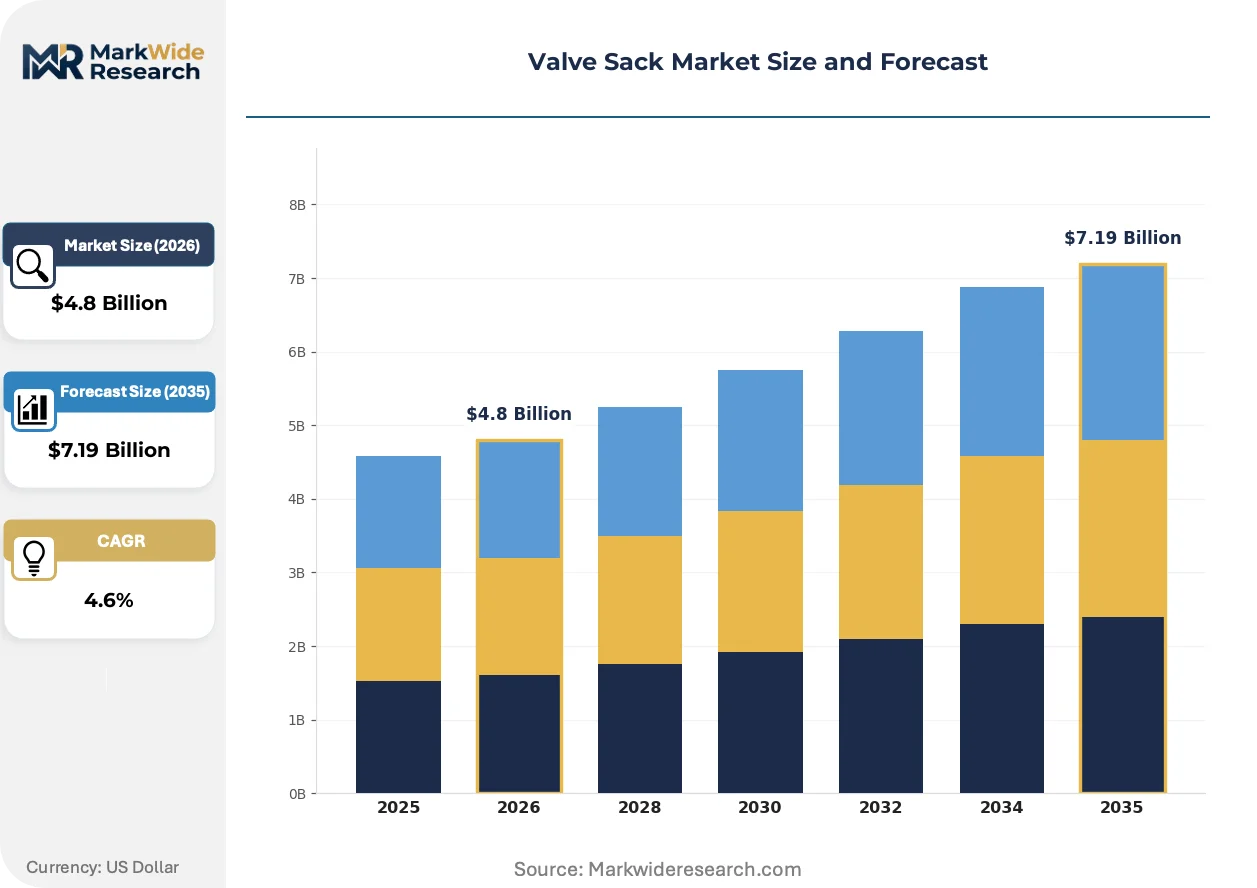
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polypropylene, Polyethylene, Woven Fabric, Paper End User: Food Industry, Construction, Chemicals, Agriculture Closure Type: Heat-Sealed, Sewn, Taped, Open-Top Capacity: 5 kg, 10 kg, 25 kg, 50 kg |
| Companies Covered | Mondi Group, BillerudKorsnäs AB, Smurfit Kappa Group, Sonoco Products Company, Hood Packaging Corporation, LC Packaging International BV, WestRock Company, Stora Enso Oyj, El Dorado Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Valve Sack Market Evolving Landscape
Material science advances and regulatory fragmentation are rewriting competitive rules for valve sack converters, privileging integrated substrate-coating capabilities over pure manufacturing scale.
Biobased barrier coatings derived from lignin and cellulose derivatives are unifying moisture protection with compostability claims. European chemical and food-grade buyers are adopting these constructions fastest, compressing the performance gap between traditional PE-lined kraft and next-generation biofilms. Smurfit Kappa's integrated pulp-to-sack supply chain positions it to capture margin from this substrate transition.
REACH Annex XVII restrictions on specific adhesive chemistries are forcing reformulation investments across European converters. The industrial consequence extends beyond compliance costs to substrate switching, as some legacy kraft-polyethylene laminates face technical obsolescence. Chemical packaging segments in Germany and France are responding fastest, accelerating supplier qualification audits.
Buyer consolidation among multinational cement producers is compressing contract renewal cycles and elevating total-cost-of-ownership analytics over unit pricing. Smaller regional converters lose share to integrated suppliers offering volume guarantees and technical service bundling. This pattern concentrates most visibly in Indian infrastructure procurement, where Adani and UltraTech Cement centralize packaging specifications.
Valve Sack Market Segmentation
Valve sack procurement patterns diverge sharply between high-volume commodity flows and premium-certified applications. Material selection and capacity specifications cascade through compliance requirements, filling speeds, and handling norms that vary by end-use sector.
Material Type:
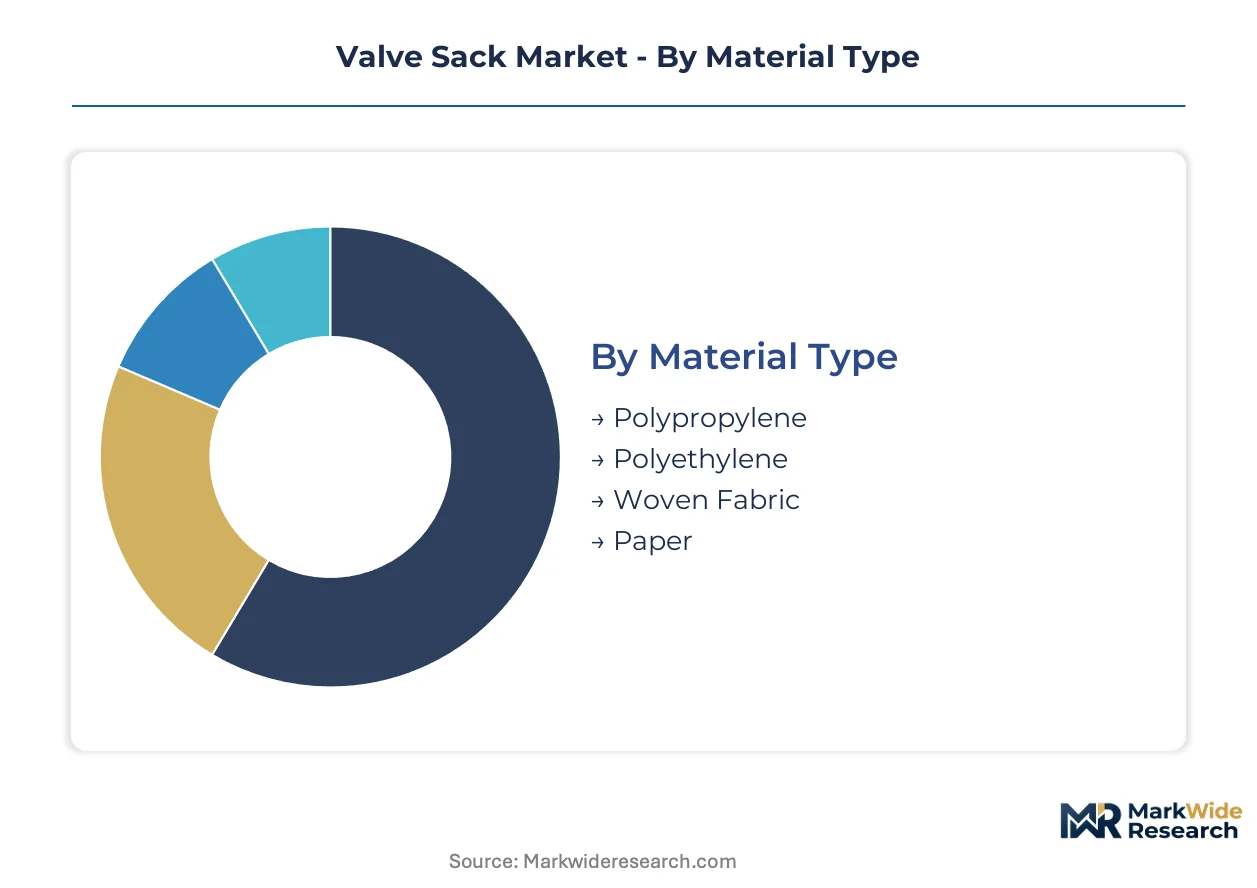
Polypropylene commands volume leadership while paper constructions capture margin premiums in regulated food-contact segments.
- Polypropylene:Woven polypropylene constructions incorporate PE liners achieving burst strengths of 150–300 kN/m. Demand concentrates in India's fertilizer distribution channels where BIS-mandated UV stability requirements favor certified woven PP suppliers over unregulated imports.
- Paper:Multi-ply kraft paper sacks with biobased barrier coatings are displacing PE-lined constructions in European chemical packaging. ECHA's REACH Annex XVII adhesive restrictions accelerate converter qualification audits across Germany and France.
- Polyethylene:Woven PE constructions serve tropical-climate cement packaging where moisture resistance trumps recyclability claims. SAMR's GB standards cap post-consumer recycled ratios in Chinese food-contact applications.
- Woven Fabric:Specialty woven fabric laminates target chemical-grade applications requiring enhanced puncture resistance. Deployment remains concentrated in European industrial chemical distribution.
Mature deployment sits with polypropylene. Newer deployment is concentrated in paper with biobased coatings.
End User:
Construction and agriculture anchor volume procurement while food and chemical segments drive specification complexity.
- Construction:Cement producers specify valve sacks for pneumatic filling systems exceeding 3,000 bags per hour. Adani and UltraTech Cement in India centralize packaging specifications, compressing contract renewal cycles toward integrated suppliers.
- Agriculture:Fertilizer distribution through government procurement channels in India mandates BIS-certified 50 kg woven sacks with specified tensile strength and UV degradation thresholds.
- Food Industry:Flour and sugar packaging in emerging economies demands dust-free automated filling with food-contact compliance. EMA guidelines and evolving GB standards reshape substrate selection.
- Chemicals:Chemical-grade applications require barrier coatings extending shelf integrity. Stora Enso's lignin-derived biofilms merge with European kraft capacity to capture this specification tier.
Volume procurement clusters in construction. Margin expansion concentrates in chemicals.
Closure Type:
Automation compatibility and seal integrity requirements split procurement between heat-sealed precision and sewn durability.
- Heat-Sealed:Precision heat-sealed closures enable high-speed automated lines with minimal backflow risk. Food Industry buyers in Europe specify these for powder filling operations.
- Sewn:Sewn closures dominate 50 kg agricultural sacks where manual handling and rough transport conditions prioritize seam strength over automation speed.
- Taped:Taped closures serve mid-tier chemical packaging where cost containment balances with moderate barrier requirements.
- Open-Top:Open-top constructions retain niche deployment for specialty filling equipment incompatible with valve mechanisms.
Automation adoption favors heat-sealed. Manual handling environments sustain sewn closure demand.
Capacity:
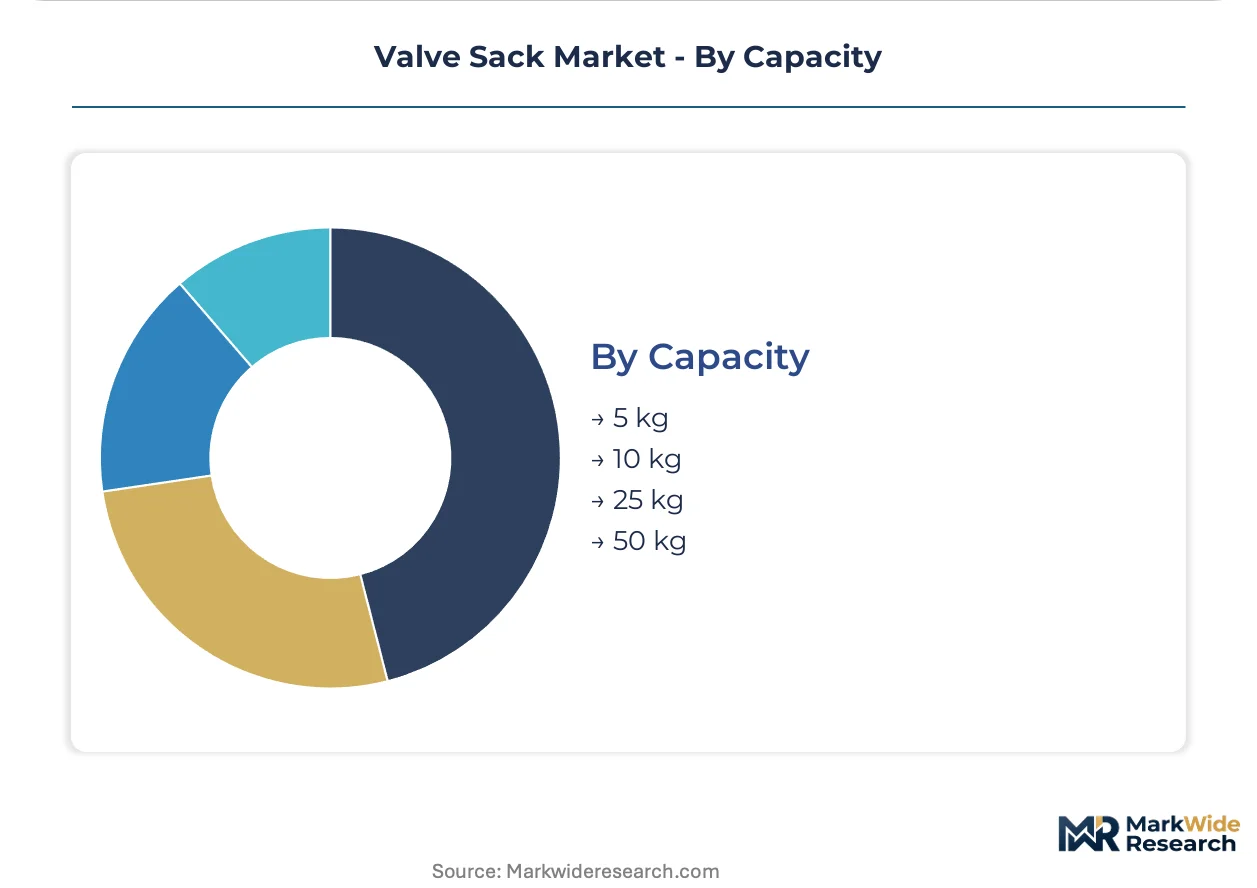
Handling norms and regulatory frameworks fixate procurement on 25 kg and 50 kg tiers despite automation enabling smaller formats.
- 50 kg:The 50 kg tier dominates Indian fertilizer distribution and tropical-climate cement packaging where manual handling norms persist. BIS certification mandates for woven sacks apply specifically to this capacity.
- 25 kg:The 25 kg tier concentrates in European food-grade segments where retail-facing packaging and ergonomic handling regulations constrain maximum weights.
- 10 kg:The 10 kg tier serves specialty chemical and food ingredients where batch control and retail shelf presentation override unit economics.
- 5 kg:The 5 kg tier remains limited to premium chemical samples and high-value food ingredients with limited volume penetration.
Regulatory handling limits anchor 25 kg in Europe. Labor-intensive distribution sustains 50 kg in emerging economies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kraft pulp availability in Nordic forests anchors European valve sack capacity, while polypropylene feedstock corridors in the Middle East and shale-rich North American regions shape substrate economics elsewhere.
Germany
Cement producers in the Rhine-Ruhr industrial belt specify high-speed pneumatic filling systems for construction chemicals. ECHA's REACH Annex XVII adhesive restrictions force reformulation investments across converters in Bavaria and Baden-Württemberg. The Hamburg-Bremen port cluster handles imported kraft paper flows for chemical-grade barrier coatings.
India
Fertilizer distribution through government procurement channels drives 50 kg woven polypropylene volumes. BIS certification mandates for UV-stable sacks tighten tensile strength benchmarks for suppliers in Gujarat and Maharashtra. The Mumbai-Pune industrial corridor concentrates certified converter capacity serving Adani and UltraTech Cement centralized specifications.
China
Food Industry buyers in the Yangtze River Delta expand valve sack procurement for flour and sugar packaging. SAMR's GB standards for plastic food contact materials cap recycled content ratios in woven polyethylene constructions. The Shandong Peninsula hosts woven PP clusters supplying domestic cement and chemical processors.
United States
Construction material suppliers multi-source valve sacks across regional converters to manage logistics cost volatility. EPA industrial emissions frameworks influence coating chemistry selection in Gulf Coast chemical packaging. The Southeast paper mill corridor supplies kraft substrate for domestic food-grade applications.
Brazil
Agricultural commodity exporters in São Paulo state specify moisture-resistant woven constructions for tropical-climate grain handling. ANVISA food contact regulations shape substrate selection for sugar and coffee packaging. The Santos port complex anchors export-oriented sack conversion capacity.
Valve Sack Market Competitive Landscape
Capacity expansion dominates the current landscape as converters respond to divergent regional compliance timelines. The vendor base separates into three tiers: integrated pulp-to-sack operators controlling substrate supply, specialized coating technology licensors, and regional fabricators serving single-country procurement channels. Strategic archetypes include Nordic forest-product conglomerates leveraging biobased R&D pipelines, and emerging-market specialists capturing government-mandated certification premiums. M&A activity and geographic licensing partnerships represent the dominant competitive moves.
Within the integrated forest-products tier, Mondi Group and Stora Enso Oyj exemplify substrate-coating convergence strategies. Smurfit Kappa Group occupies a position among kraft paper supply chain integrators. These three entities anchor different archetype positions: Mondi represents European premium cement packaging capacity, Stora Enso exemplifies biobased barrier coating development, and Smurfit Kappa sits within margin-controlled multi-tier production systems.
| Leading Market Players |
|---|
| Mondi Group |
| BillerudKorsnäs AB |
| Smurfit Kappa Group |
| Sonoco Products Company |
| Hood Packaging Corporation |
| LC Packaging International BV |
| WestRock Company |
| Stora Enso Oyj |
| El Dorado Packaging |
| Others |
Value Network & Pricing Analysis
Skilled adhesive formulation chemists concentrated in Bavaria and Baden-Württemberg command wage premiums that cascade through European kraft paper sack pricing, widening spreads between REACH-certified premium tiers and uncertified economy imports from Asian converters.
Pricing Analysis
Warranty-backed technical service bundling separates integrated suppliers from commodity converters competing on unit price alone. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments from multinational cement producers. Pricing pressure stems from polypropylene feedstock volatility linked to crude resin markets, compressing margin predictability for tropical-climate woven PE specialists. Government procurement channels in India exhibit highest price sensitivity due to mandated BIS certification costs, while European chemical-grade buyers prioritize shelf-life performance over unit economics.
Supply Chain Analysis
Workforce availability for biobased coating chemistry expertise constrains expansion in Nordic and Alpine kraft paper corridors. Supply concentrates in Germany, India, and China, with raw material dependencies spanning Nordic kraft pulp, Middle Eastern polypropylene resin, and lignin derivatives from Finnish forest products. Single-source vulnerability sits with premium kraft paper capacity clustering in energy-exposed Nordic regions. Distribution runs through government-mandated procurement channels in Indian agriculture and centralized specifications from Adani and UltraTech Cement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The valve sack market operates as a cost-of-compliance story where ECHA's REACH Annex XVII adhesive restrictions erect barrier-to-entry moats that favor certified European converters over uncertified import competition.
For Market Incumbents: Hedge against substrate obsolescence by accelerating biobased barrier coating R&D partnerships with Nordic forest-product conglomerates. Secure backward integration into kraft pulp supply through long-term offtake agreements with Alpine and Nordic mills, insulating margin from energy price volatility that threatens premium paper capacity. For New Entrants and Emerging Players: Begin with BIS-certified woven polypropylene production for Indian fertilizer distribution channels, where government procurement mandates create certified-supplier premiums. Capture white-space in UV-stable 50 kg agricultural sacks through technical service bundling that incumbent commodity converters cannot match. For Investors and Strategic Acquirers: Re-rating potential sits with integrated pulp-to-sack operators possessing captive biobased coating chemistry pipelines given EU Green Deal procurement rules favoring kraft-based valve sacks. Watch for inflection when REACH compliance deadlines force substrate switching accelerations across German and French chemical packaging segments.| Strategic Initiative | Industry Significance |
|---|---|
| Biobased Coating Chemistry Investment | Stora Enso's lignin-derived biofilms merge with European kraft capacity to capture chemical-grade shelf-life extensions. |
| Backward Integration into Kraft Pulp | Smurfit Kappa's integrated pulp-to-sack supply chain positions it to capture margin from substrate transition. |
| BIS Certification Capacity Addition | Certified converter capacity in Gujarat and Maharashtra captures government-mandated premiums in Indian fertilizer procurement. |
| REACH Compliance Reformulation | ECHA's adhesive restrictions force technical obsolescence of legacy kraft-polyethylene laminates in German chemical packaging. |
| Technical Service Bundling | Integrated suppliers offering volume guarantees displace smaller regional converters in compressed contract renewal cycles. |
Research Methodology
Independent corroboration across converter plant managers, procurement leads at cement and chemical OEMs, distribution channel partners, and technical R&D directors underwrites the qualitative findings. Secondary validation draws from customs and trade data, BIS certification registries, ECHA REACH filings, and SEC 10-K disclosures from integrated forest-product conglomerates. Bottom-up volume modeling triangulates against top-down macroeconomic demand projections.
Rate-of-change decomposition across material type, end-use industry, closure mechanism, and regional regulatory cluster shapes the analytical framework. CAGRs derive from segment-level volume trajectories and value-per-unit assumptions across the projection horizon. Forecast inputs incorporate BIS certification timeline accelerations, ECHA adhesive restriction phase-ins, and polypropylene feedstock price elasticity coefficients.
Underlying measurement precision varies by segment; REACH-compliant European chemical-grade applications carry tighter precision than emerging economy commodity cement procurement. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and feedstock price regime stability. Material deviation in ECHA compliance deadlines or Middle Eastern resin supply disruptions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Pressure Control Equipment Market
Valves
Hydraulic Valves Market
Valves
Gate Impellers Market
Valves
Degassing Valves Market
Valves
Industrial Vacuum Valves Market
Valves
Float Traps Market
Valves
Orifice Reducers Market
Valves
Global Globe Valve Market
Valves
Pneumatic Positioner Market
Valves
APAC Valves Market
Valves
Naval Actuators and Valves Market
Valves
Steam Safety Valve Market
Valves
Hybrid Valve Market
Valves
Europe Butterfly Valve Market
Valves
Choke and Kill Manifold Market
Valves
Leak Detection Market