
 Compressed Air Energy Storage (CAES) Market | 2026-2036
Compressed Air Energy Storage (CAES) Market Size, Share, and Industry Trends Forecast 2026-2036
Compressed Air Energy Storage (CAES) Market Outlook
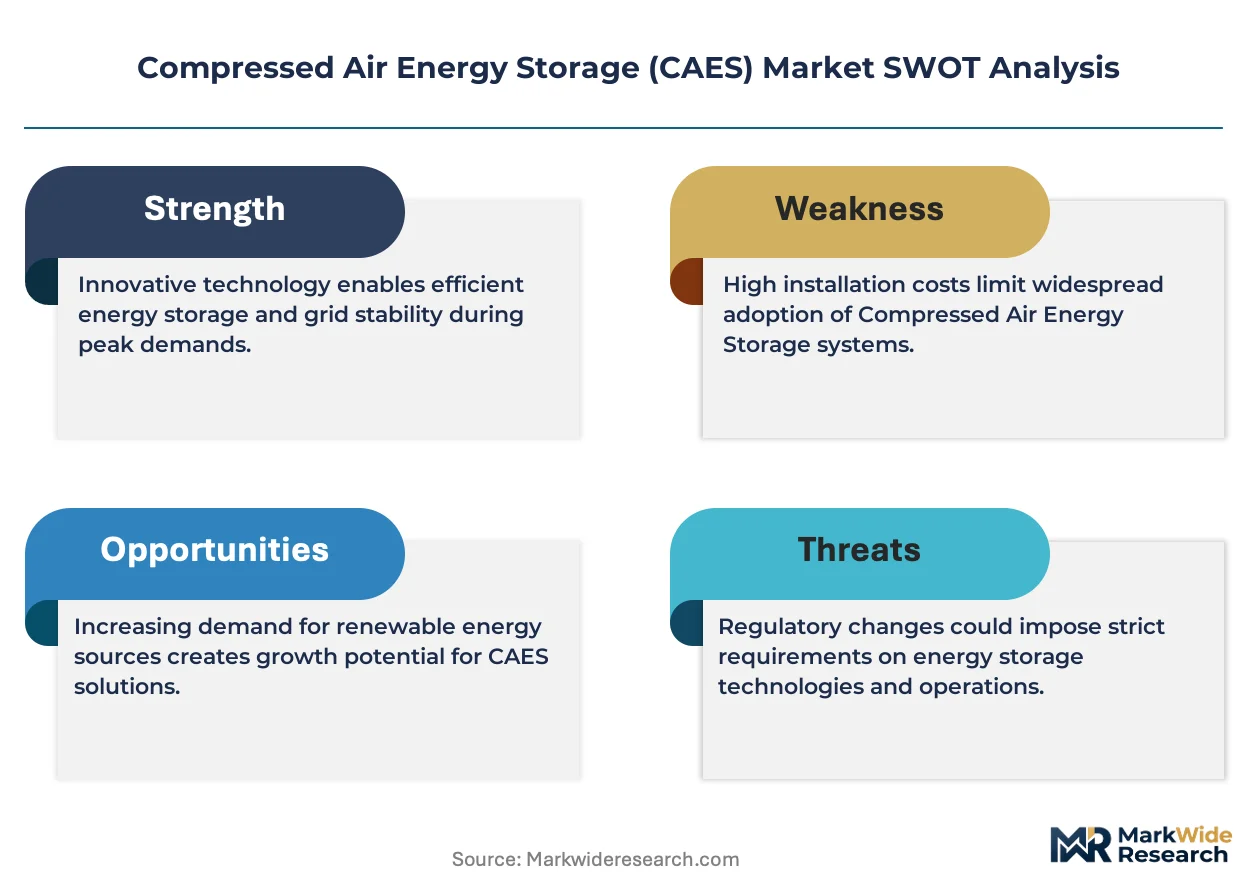
Advanced turbomachinery and thermal management integration is fragmenting traditional CAES engineering into discrete specialist layers. Hydrostor anchors offshore-adjacent compressed air storage through its proprietary A-CAES architecture. Siemens Energy leverages century-long turbomachinery expertise to dominate equipment supply for large-scale diabatic installations. Storelectric LTD differentiates through its zero-emission adiabatic designs targeting salt cavern deployments.
Compressed Air Energy Storage systems compress ambient air into sealed reservoirs—underground salt caverns, depleted aquifers, or above-ground vessels—then release it through turbines to generate electricity, with advanced configurations capturing compression heat to boost round-trip efficiency above 70%. Adiabatic technology leads in R&D intensity as developers chase near-isothermal performance without fuel combustion, while isothermal approaches occupy emerging niches in modular above-ground systems where siting flexibility outweighs scale economies. Utility-scale application dominates current deployment value, though renewable integration represents the fastest-growing demand channel as grid operators seek multi-hour discharge duration beyond lithium-ion economics.
The US EPA and FERC shape project economics through emissions permitting and wholesale market participation rules, while the EU F-Gas Regulation and CE marking constrain compressor refrigerant choices and equipment certification pathways. China's MIIT and National Energy Administration set domestic efficiency benchmarks and grid-connection standards that determine project viability. Stakeholders must monitor evolving capacity market remuneration mechanisms and underground storage leasing frameworks across these jurisdictions to secure long-term offtake structures.
Market Dynamics
Adiabatic CAES architectures are compressing the competitive window for conventional diabatic systems as developers chase round-trip efficiencies above 70% without fuel combustion. This thermal-capture imperative is forcing equipment suppliers to restructure R&D roadmaps and partnership strategies.
Growth Catalysts
- US IRA production tax credits:The Inflation Reduction Act's clean energy incentives accelerate project approvals for utility-scale installations in Texas and California.
- Renewable integration mandates:Grid operators in Germany and China require multi-hour storage duration beyond lithium-ion economics.
- Underground salt formation availability:Geological concentration along the US Gulf Coast and northern Germany reduces reservoir development costs.
Market Restraints
- High upfront capital intensity:Salt cavern drilling and turbomachinery procurement require decade-long payback periods that deter merchant developers.
- Geographic supply concentration:Specialist compressor manufacturers cluster in Germany and Japan, creating equipment delivery bottlenecks.
- Round-trip efficiency gap:Diabatic systems lose 50% of input energy to heat dissipation versus 85% for pumped hydro.
Strategic Opportunities
- Western China renewable corridors:MIIT grid-connection standards and abundant salt deposits create untapped deployment potential.
- Offshore-adjacent coastal storage:Subsea reservoir engineering enables gigawatt-scale projects without land-use conflicts.
- Isothermal modular systems:Above-ground vessel configurations serve industrial microgrids where siting flexibility outweighs scale economies.
Industry Challenges
- Subsurface engineering talent scarcity:Salt cavern geomechanics expertise concentrates at legacy oilfield services firms.
- FERC interconnection queue delays:Wholesale market participation rules create 3-5 year approval timelines.
- Thermal storage material certification:CE marking pathways for high-temperature containment systems remain undefined.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compressed Air Energy Storage (CAES) Market |
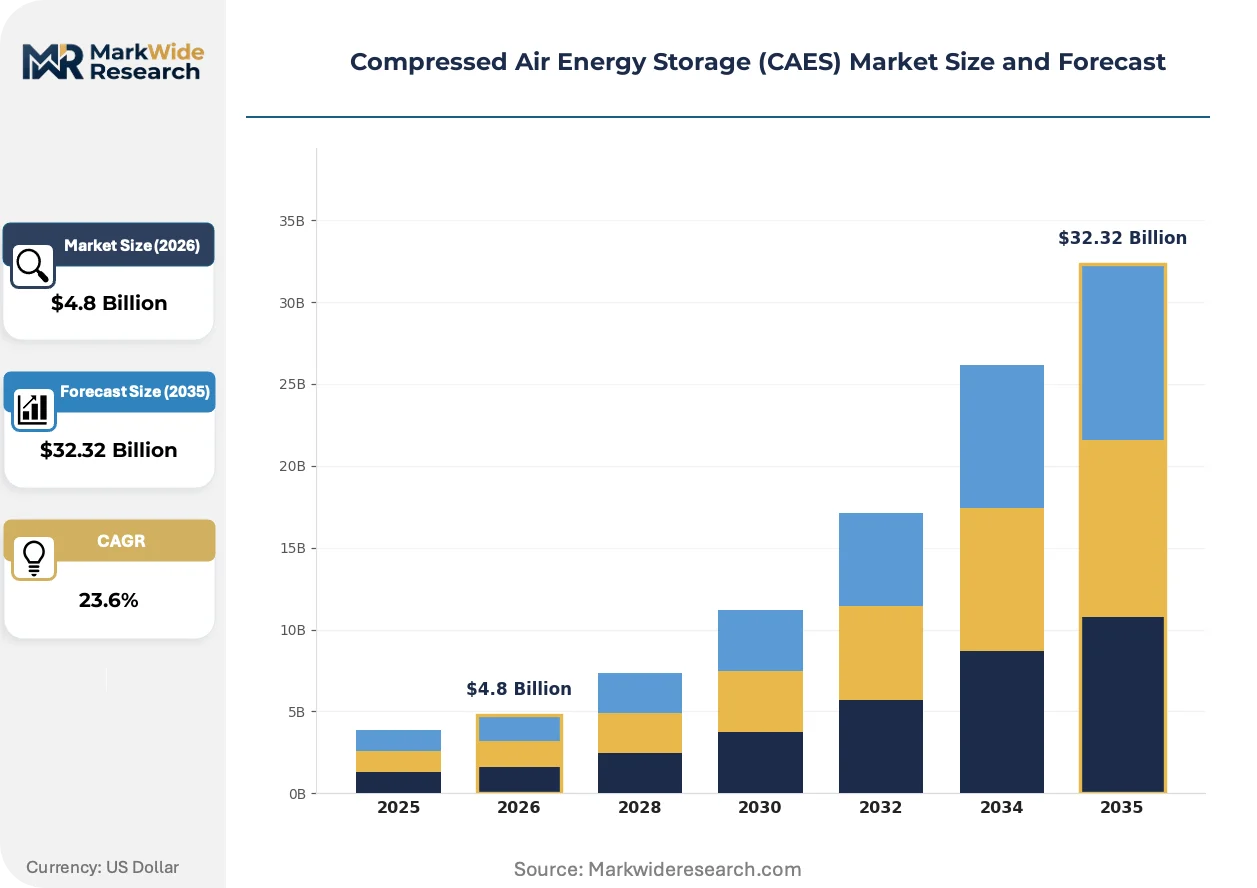
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $32.32 Billion |
| CAGR (2026 – 2036) | 23.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Diabatic, Aadiabatic, Isothermal, Multi-stage Application: Utility Scale, Renewable Integration, Peak Shaving, Grid Stabilization End User: Electric Utilities, Industrial Manufacturers, Renewable Energy Producers, Energy Storage Providers Installation Type: Onshore, Underground, Above Ground, Modular |
| Companies Covered | Baromar, Augwind, Hydrostor, Siemens Energy, TerraStor Energy Corporation, Storelectric LTD, APEX CAES, Mitsubishi Power Americas, Corre Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compressed Air Energy Storage (CAES) Market Strategic Shifts
Turbomachinery integration and thermal management architectures are fragmenting CAES engineering into discrete specialist layers. Equipment suppliers, reservoir developers, and grid integrators now compete for margin capture across redefined value chain positions.
Advanced adiabatic designs with packed-bed thermal storage are migrating from pilot demonstrations to commercial procurement. European utilities now specify these systems in RFPs for 100+ MWh installations. The technology is compressing the addressable market for fuel-fired diabatic retrofits.
EU F-Gas Regulation amendments restrict compressor refrigerant choices for new CAES builds. Equipment suppliers must redesign cooling loops around natural working fluids. German and French project developers face 12-18 month certification delays while awaiting CE marking pathway clarity.
Utility procurement teams now unbundle long-term reservoir leases from equipment supply and O&M contracts. Texas and California grid operators negotiate 20-30 year offtake structures with independent storage developers. This financing model rotation demands new risk allocation frameworks between cavern owners, technology providers, and power marketers.
Compressed Air Energy Storage (CAES) Market Segmentation
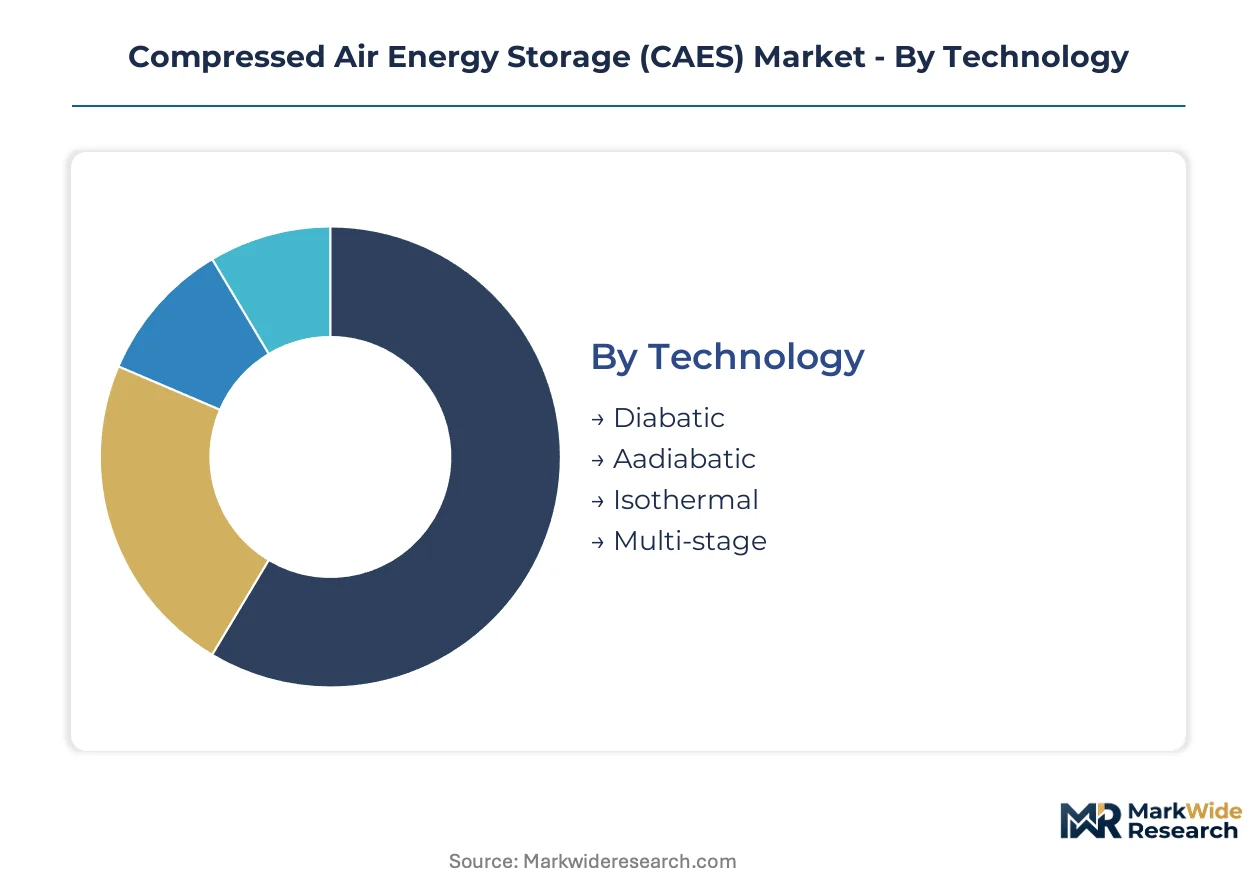
CAES market segmentation reveals divergent capital cycles across technology tiers, with modular above-ground systems deploying in 18-24 months while underground salt cavern projects stretch across 5-7 year development timelines. Understanding these velocity differentials shapes procurement strategies and partnership structures for developers and utilities alike.
Technology:
Cycle times compress from decade-long reservoir engineering for adiabatic salt cavern systems to sub-two-year deployment windows for modular isothermal units, creating distinct financing and risk profiles across the technology spectrum.
- Diabatic:Conventional fuel-assisted designs burn natural gas during expansion to offset thermal losses, achieving 40-50% round-trip efficiency. Texas and California utilities favor these systems for their proven operational track record and lower upfront capital requirements, though EPA emissions permitting adds 12-18 months to project timelines.
- Adiabatic:Heat-capture architectures store compression thermal energy in packed-bed or liquid media, eliminating fuel combustion while targeting 70%+ efficiency. Northern German utilities now specify these systems in 100+ MWh RFPs as EU F-Gas Regulation amendments constrain refrigerant choices for conventional compressor designs.
- Isothermal:Near-constant temperature compression using liquid pistons or spray cooling enables containerized above-ground deployment. Industrial microgrids in Japan and South Korea adopt these systems where subsurface engineering constraints prevent cavern development.
- Multi-stage:Cascaded compression with intercooling optimizes thermodynamic efficiency for large-scale installations. Chinese MIIT efficiency benchmarks increasingly favor these configurations for western China renewable corridor projects.
Diabatic systems anchor the volume base while adiabatic configurations gain share at the steepest rate as European and North American utilities prioritize zero-emission performance.
Application:
Margin structures vary sharply across use cases, with grid stabilization commanding premium pricing for sub-second response while renewable integration spreads capital costs across longer discharge durations.
- Utility Scale:Bulk energy arbitrage and capacity market participation drive gigawatt-hour class installations. Gulf Coast utilities leverage abundant salt dome geology to minimize reservoir development costs for these deployments.
- Renewable Integration:Multi-hour storage for solar and wind curtailment mitigation represents the expansion frontier. German grid operators now mandate 4-8 hour discharge capability beyond lithium-ion economics for new renewable interconnects.
- Peak Shaving:Demand charge reduction for commercial and industrial loads favors modular above-ground configurations. California industrial parks deploy these systems to manage time-of-use rate volatility.
- Grid Stabilization:Frequency regulation and voltage support services require rapid response turbomachinery. ERCOT market structures in Texas reward these capabilities through ancillary service premiums.
Utility scale applications dominate installed capacity while renewable integration climbs the fastest as clean energy mandates harden across major economies.
End User:
Procurement sophistication diverges between regulated utilities with long-term planning horizons and merchant developers seeking merchant market exposure.
- Electric Utilities:Vertically integrated operators in Texas, California, and Germany pursue ownership models with 20-30 year asset lives. FERC interconnection queue management and rate-base treatment drive their technology selection criteria.
- Industrial Manufacturers:Cement, steel, and chemical producers deploy behind-the-meter storage for power quality and cost hedging. German KBA industrial energy audits increasingly recommend CAES for emissions reduction compliance.
- Renewable Energy Producers:Wind and solar developers add storage to qualify for production tax credit bonuses and grid connection priority. US IRA incentives accelerate these hybrid project structures.
- Energy Storage Providers:Independent power developers unbundle reservoir leases from equipment supply to optimize capital stacks. Texas and California market structures favor these merchant models with energy-only revenue exposure.
Electric utilities anchor deployment volumes while energy storage providers expand most quickly as project finance structures mature.
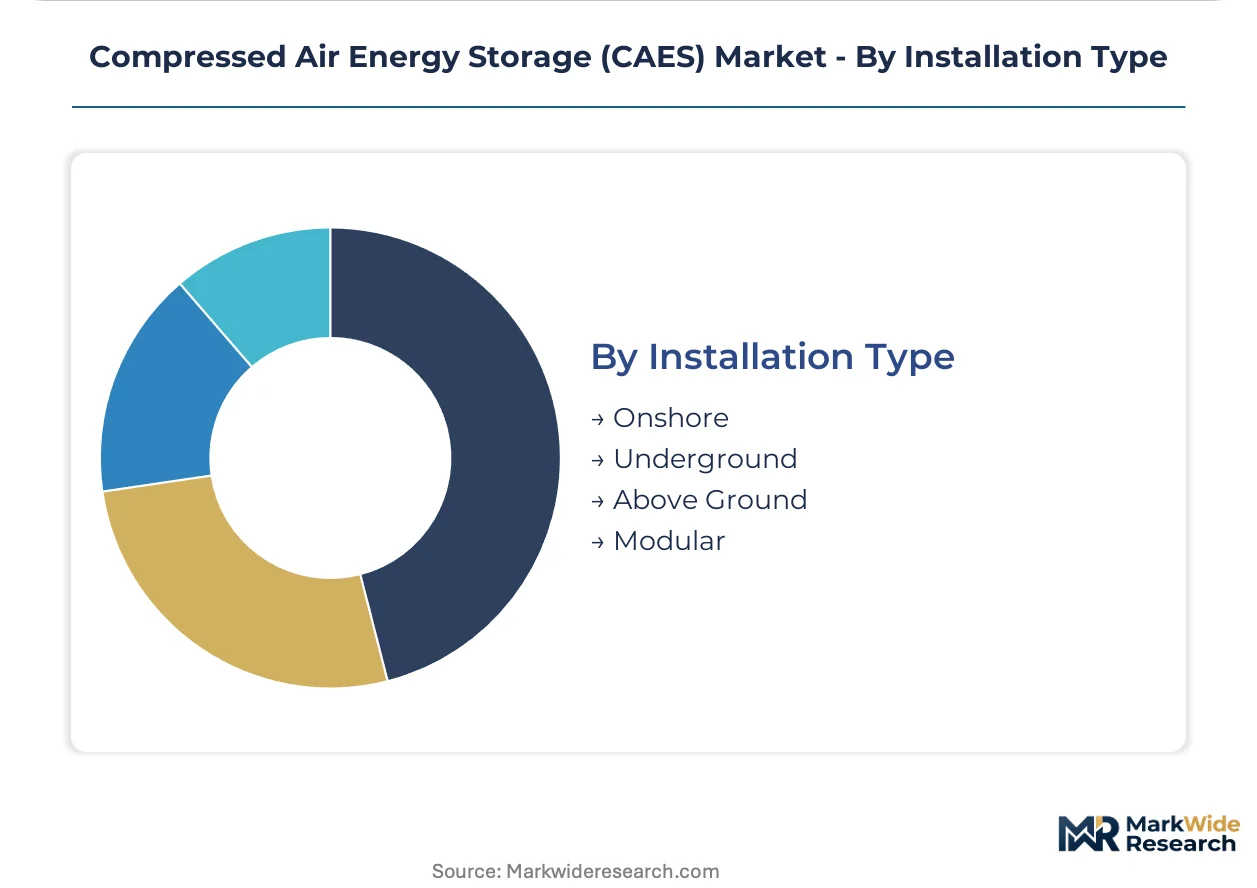
Installation Type:
Geological availability and land-use constraints segment addressable markets, with coastal subsea engineering opening new deployment frontiers.
- Onshore:Surface turbomachinery with underground or above-ground air storage dominates current deployment. Northern Germany's Zechstein salt basin supports the densest concentration of these installations.
- Underground:Salt cavern, depleted gas field, and aquifer reservoirs provide gigawatt-scale storage potential. US Gulf Coast geology offers the most favorable development conditions outside Europe.
- Above Ground:Welded steel pressure vessels and pipeline arrays enable rapid deployment without subsurface engineering. Japanese industrial clusters favor these configurations for seismic risk mitigation.
- Modular:Containerized isothermal units scale through replication rather than unit size. South Korean manufacturing hubs deploy these for incremental capacity expansion with minimal site preparation.
Underground installations anchor the megawatt-hour base while modular systems expand at the steepest trajectory as siting flexibility gains priority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German equipment manufacturers export compression systems to Texas and California utilities expanding renewable storage capacity, while Chinese project developers import thermal management expertise from European engineering firms for western corridor installations.
United States
Texas ERCOT grid operators and California ISO utilities drive demand for multi-hour discharge systems managing solar and wind intermittency. FERC interconnection rules and IRA production tax credits shape project economics across Gulf Coast salt dome regions. Houston-area developers leverage abundant underground geology to minimize cavern construction costs for utility-scale deployments.
Germany
Northern utilities mandate adiabatic configurations in 100+ MWh procurement tenders as renewable integration requirements harden. EU F-Gas Regulation amendments constrain compressor refrigerant selections, forcing equipment redesigns around natural working fluids. The Zechstein salt basin in Lower Saxony hosts the densest concentration of European CAES engineering activity.
China
Western renewable corridors in Xinjiang and Gansu provinces generate demand for bulk energy storage beyond lithium-ion duration limits. MIIT efficiency benchmarks and National Energy Administration grid-connection standards determine project viability. Sichuan-Chongqing engineering clusters develop domestic turbomachinery supply chains to reduce import dependence.
Japan
Industrial microgrids in Kanto and Kansai regions adopt modular above-ground systems where seismic risks prevent subsurface engineering. METI clean energy incentives support behind-the-meter deployments for manufacturing power quality. Osaka-based industrial parks integrate containerized units for demand charge management.
Canada
Hydrostor anchors offshore-adjacent development through subsea reservoir engineering along coastal British Columbia and Atlantic provinces. Federal clean energy investment tax credits accelerate project finance structures for utility partnerships. Toronto-area engineering firms specialize in geomechanical assessments for salt formation suitability.
Compressed Air Energy Storage (CAES) Market Competitive Environment
On the supply side, the industry is consolidating around three strategic layers: reservoir developers controlling subsurface access, turbomachinery specialists supplying compression equipment, and system integrators managing grid interconnection. Equipment suppliers and cavern operators now compete for margin capture across redefined value chain positions. Dominant competitive moves include strategic partnerships between technology providers and independent storage developers, plus capacity expansion into modular above-ground configurations.
Within the integrated system developer tier, Hydrostor and Storelectric LTD exemplify contrasting approaches to reservoir engineering and thermal architecture. Siemens Energy anchors the equipment supply segment through century-long turbomachinery expertise. Mitsubishi Power Americas occupies a position bridging Japanese industrial conglomerate scale with North American utility market access.
| Leading Market Players |
|---|
| Baromar |
| Augwind |
| Hydrostor |
| Siemens Energy |
| TerraStor Energy Corporation |
| Storelectric LTD |
| APEX CAES |
| Mitsubishi Power Americas |
| Corre Energy |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in German compressor manufacturing is tightening equipment lead times and emboldening suppliers to enforce stricter payment terms. This utilization squeeze cascades into project cost structures as developers absorb premium pricing for turbomachinery or accept extended delivery schedules.
Pricing Analysis
The pricing gap between adiabatic next-generation systems and conventional diabatic installations spans 40-60% on a per-megawatt basis. Project-based long-term offtake contracts dominate, with price differentiation driven by CE certification tier and reservoir lease bundling. Cost compression in standard diabatic configurations is intensifying because Chinese MIIT efficiency benchmarks are accelerating domestic equipment substitution. Merchant developers exhibit highest price sensitivity due to energy-only revenue exposure, while regulated utilities accept premium pricing for rate-base treatment certainty.
Supply Chain Analysis
Siemens Energy and Mitsubishi Heavy Industries anchor contract manufacturing capacity for large-scale turbomachinery, with specialist fabrication concentrated in Germany, Japan, and emerging Sichuan-Chongqing clusters. Supply draws from nickel-based superalloys, precision bearings, and high-pressure containment vessels. Single-source vulnerability in subsea reservoir engineering creates bottlenecks for offshore-adjacent projects. Distribution runs through EPC-led turnkey contracts unbundling into separate equipment, reservoir, and O&M procurement streams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The CAES market rewards control over salt cavern geomechanics expertise, a capability pool concentrated at legacy oilfield services firms with limited transfer to pure-play developers. This scarcity dynamic shapes competitive durability across technology tiers.
For Market Incumbents: Insulate margin capture by deepening backward integration into thermal storage media production and securing exclusive reservoir leaseholds along the US Gulf Coast. Siemens Energy should expand captive forging capacity for high-pressure casings to offset German equipment bottlenecks. Hydrostor must defend its subsea engineering lead against emerging coastal developers through patent thickets on A-CAES architecture. For New Entrants and Emerging Players: Build out modular isothermal offerings for Japanese industrial microgrids where seismic constraints block cavern development. Western China renewable corridors offer penetrable white space for adiabatic specialists partnering with domestic EPCs on MIIT-compliant designs. A licensing-heavy go-to-market model reduces capital requirements while accelerating grid-connection certification. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across above-ground modular configurations as containerized manufacturing achieves scale economies. Long-term viability favors developers with unbundled asset ownership separating reservoir leases from technology supply. Acquisition targets should display bundled cavern-turbomachinery integration capabilities. The signal to watch is FERC interconnection queue clearance velocity as a proxy for project finance availability.| Strategic Initiative | Industry Significance |
|---|---|
| Salt Cavern Lease Consolidation | Control over Zechstein and Gulf Coast geology locks in decade-long competitive positioning against late entrants. |
| Thermal Storage Material Certification | CE marking pathway clarity for packed-bed systems accelerates European utility procurement timelines. |
| Subsea Reservoir Engineering Partnership | Hydrostor's coastal British Columbia deployments demonstrate gigawatt-scale potential without land-use conflicts. |
| Domestic Turbomachinery Supply Chain | Chinese MIIT efficiency benchmarks favor Sichuan-Chongqing manufacturing clusters reducing import dependence. |
| Modular Isothermal Platform Launch | Containerized units capture Japanese industrial microgrid demand where seismic risks prevent underground engineering. |
Study Parameters
Initial hypotheses were tested against primary input from utility planning officers, IPP project developers, EPC contractors, and grid operators and refined through secondary validation. EIA capacity data, IEA storage technology roadmaps, FERC interconnection filings, and project development databases anchored quantitative baselines. Bottom-up project pipelines were triangulated against top-down regulatory mandate trajectories to constrain forecast variance.
Demand-supply balance modeling segmented installations by technology generation, project scale tier, reservoir type, and regional grid structure across the projection horizon. CAGRs were derived from capacity addition run rates and capital cost learning curves. MIIT efficiency benchmark trajectories and IRA production tax credit utilization rates served as key forecast inputs.
Stress conditions across FERC queue clearance durations, salt cavern drilling cost inflation, and compressor refrigerant availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on policy continuity and geological screening success rates. Quarterly review of interconnection approval velocity and equipment order backlogs is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Storage
Europe Battery Energy Storage System Market
Energy Storage
Residential Solar Energy Storage Market
Energy Storage
Cryogenic Vaporizer Market
Energy Storage
Off-Grid Energy Storage Systems Market
Energy Storage
Vessel Energy Storage Systems Market
Energy Storage
Global Data Center Energy Storage Market
Energy Storage
Hydrogen-Bromine Flow Battery Market
Energy Storage
Power Bank Market
Energy Storage
Solar Storage Inverter Market
Energy Storage
Natural Gas Storage Market
Energy Storage
Australia Energy Storage Systems (ESS) Market
Energy Storage
Germany Energy Storage Systems Market
Energy Storage
Battery Energy Storage Market
Energy Storage
Superconducting Magnetic Energy Storage Market
Energy Storage
Solar Storage System Market
Energy Storage
North America NMC Battery Energy Storage System (BESS) Market