
 Wind Energy Fasteners Market | 2026-2036
Wind Energy Fasteners Market Size, Share, and Industry Trends Forecast 2026-2036
Wind Energy Fasteners Market Insights
Direct procurement between turbine OEMs and specialized fastener manufacturers is rewriting traditional tiered supply arrangements. Dokka Fasteners leverages its Nordic heritage to dominate North Sea offshore contracts with salt-spray-certified bolting systems. Stanley Black & Decker sustains broad geographic coverage through its industrial distribution network serving both onshore and maintenance segments. ITH Bolting Technology specializes in hydraulic tensioning equipment paired with high-strength fasteners for tower flange connections.
Wind energy fasteners are high-strength mechanical joining elements, typically rated at property class 10.9 or 12.9, manufactured through hot forging and thread rolling to withstand cyclic loading, vibration, and corrosive marine atmospheres in turbine assemblies. Their primary purpose is to maintain structural integrity across the 20-25 year design life of wind turbines under extreme fatigue and environmental stress. Bolts command the largest product share due to their irreplaceable role in tower section splicing and nacelle anchoring, while offshore installation types carry premium positioning as subsea bolting requires duplex stainless steel grades and cathodic protection compatibility. Composite material fasteners represent an emerging structural segment as blade manufacturers test fiber-reinforced polymer joining solutions to reduce mass at root attachments.
DNV standards for offshore wind structures, ISO 898-1 for carbon and alloy steel fastener mechanical properties, and REACH compliance for surface coating chemistries collectively shape product qualification pathways and market access conditions across European and Asian supply chains. China's GB standards and NMPA-adjacent industrial certification requirements for critical wind components create parallel compliance obligations for exporters serving domestic turbine builders. Stakeholders must monitor evolving blade length specifications and floating platform designs, as these will dictate next-generation fastener sizing, preload retention systems, and inspection protocol investments without reference to specific calendar milestones.
Market Dynamics
Direct procurement contracts between turbine OEMs and specialized fastener manufacturers are collapsing traditional multi-tier distribution structures, compressing margin capture toward forging specialists with DNV-certified offshore capabilities.
Growth Catalysts
- EU F-Gas Regulation:Tightened corrosion-resistance mandates for subsea bolting systems are accelerating specification upgrades across North Sea offshore developments.
- China's coastal wind corridors:State-backed capacity additions in Jiangsu and Guangdong provinces are concentrating procurement volumes for monopile foundation fasteners.
- Hot forging automation:Advanced thread-rolling precision is reducing dimensional variance in 12.9-class tower splice bolts below 50-micron tolerances.
Market Restraints
- Alloy steel price volatility:Nickel and molybdenum input cost swings are compressing margins on duplex stainless grades required for cathodic protection compatibility.
- Nordic supply concentration:Salt-spray-certified bolting capacity clusters disproportionately around North Sea port infrastructure, creating geographic vulnerability.
- REACH surface coating restrictions:Hexavalent chromium limitations are forcing costly conversion to zinc-nickel alternatives without performance equivalence guarantees.
Strategic Opportunities
- Floating platform foundations:Pre-tensioned bolted connections for semi-submersible structures represent unpenetrated specification territory outside fixed-bottom experience bases.
- Blade root composite joining:Fiber-reinforced polymer fasteners are emerging as mass-reduction alternatives at carbon fiber root attachments.
- IRA domestic content bonuses:US offshore wind tax credits are incentivizing localized fastener forging capacity along Atlantic coast manufacturing zones.
Industry Challenges
- Hydraulic tensioning technician scarcity:Specialized preload calibration skills for tower flange connections are concentrating among aging European workforces.
- DNV-ST-0126 certification timelines:Extended fatigue testing protocols for offshore bolts are stretching product qualification cycles beyond 18 months.
- Legacy inventory incompatibility:New ISO 898-1 mechanical property grades are forcing write-downs of pre-2023 stocked carbon steel fasteners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wind Energy Fasteners Market |
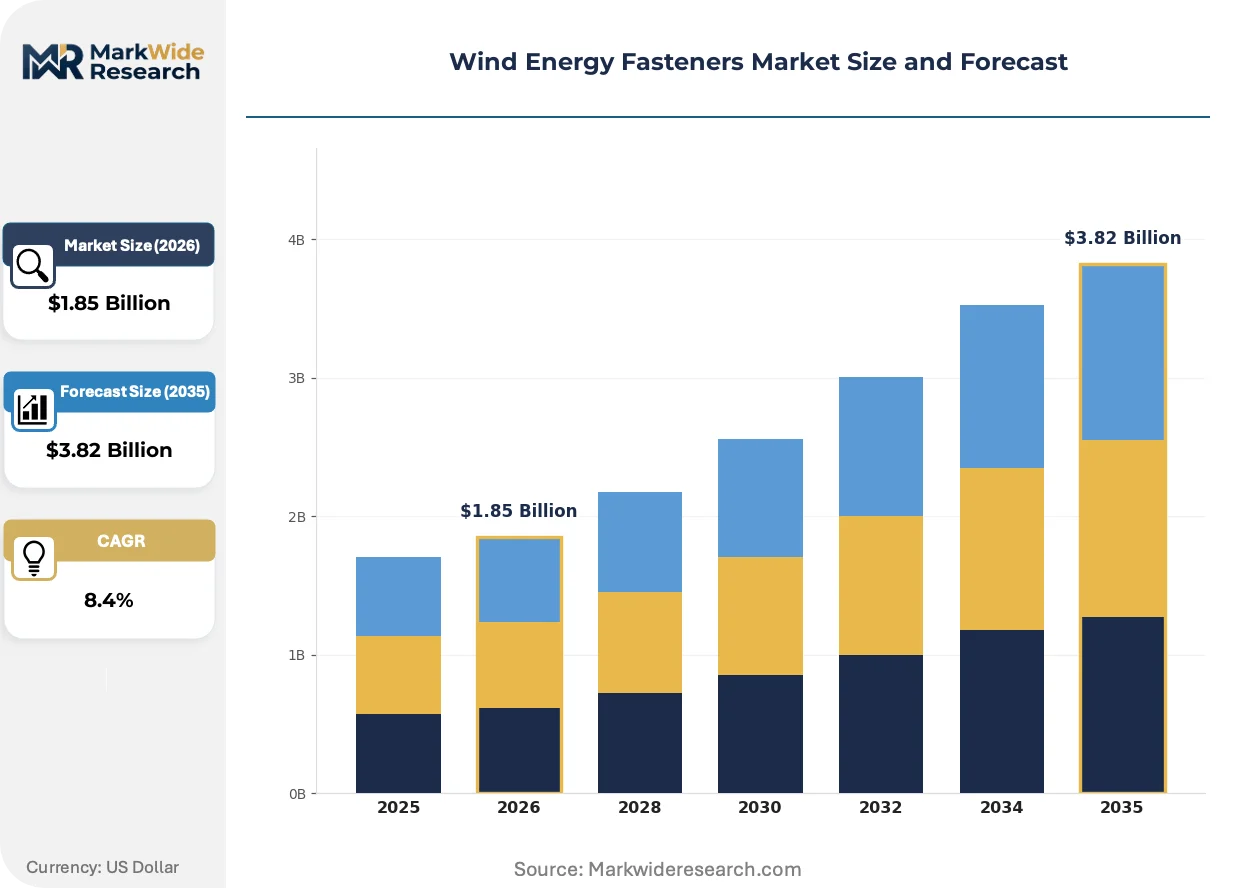
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.82 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bolts, Nuts, Washers, Rivets Application: Turbine Assembly, Blade Attachment, Tower Construction, Maintenance Material: Stainless Steel, Carbon Steel, Alloy, Composite Installation Type: Onshore, Offshore, Hybrid, Maintenance Services |
| Companies Covered | Dokka Fasteners, Dyson Corp., August Friedberg GmbH, Finework (Hu Nan) New Energy Technology Co., Ltd., Stanley Black & Decker, Graewe GmbH & Co. KG, ITH Bolting Technology, Oglaend System AS, Hilti Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wind Energy Fasteners Market Trends and Innovations
Material science advances and procurement model compression are redefining competitive differentiation in wind fastener supply, with specification authority migrating toward OEM engineering departments.
Smart bolting systems with embedded load sensors are hybridizing structural fasteners with condition-monitoring infrastructure. Vestas and Siemens Gamesa are piloting these systems on offshore tower flanges for real-time preload verification. The technology is hybridizing hardware supply with digital service revenue streams, forcing traditional forging houses to acquire sensor integration capabilities.
REACH authorization requirements for cadmium and hexavalent chromium surface treatments are eliminating legacy coating chemistries from European supply chains. ECHA's sunset date enforcement is accelerating zinc-nickel and organic coating adoption despite higher unit costs. Offshore foundation bolts face the steepest compliance burden, with German and Danish port authorities rejecting non-conforming shipments at customs.
Buyer consolidation around direct OEM-forger contracts is disintermediating industrial distributors from specification-grade procurement. Tier-one turbine builders are establishing multi-year offtake agreements with Nordic and Chinese forging specialists for monopile and tower segment bolting. This pattern is most pronounced in China's state-directed procurement, where CSSC and CRRC subsidiaries are capturing captive fastener supply through backward integration into heat-treatment and forging assets.
Wind Energy Fasteners Market Segmentation
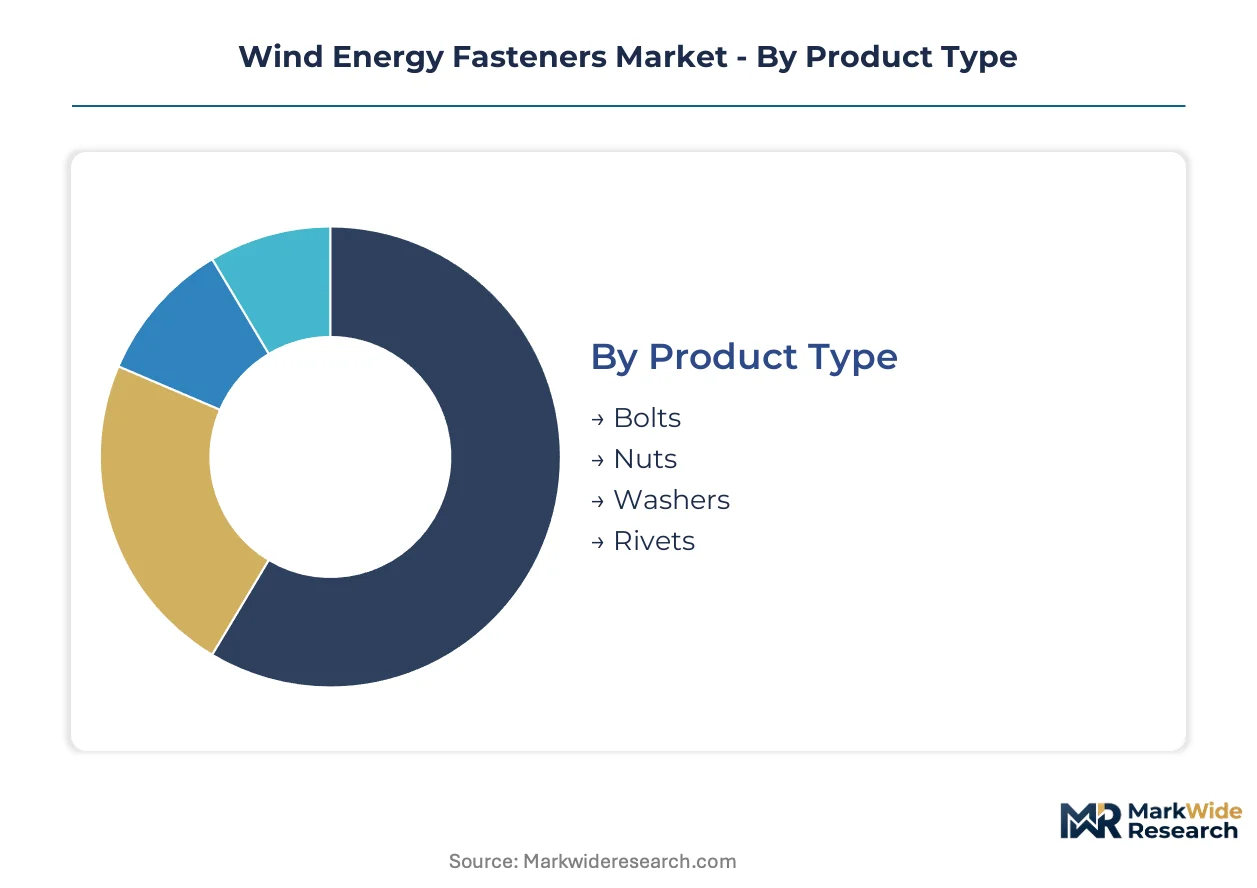
Segmentation in wind energy fasteners reveals how specification authority migrates across product hierarchies. Material grades and installation environments dictate procurement economics more than volume scale alone.
Product Type:
Mature forging categories dominate procurement volumes while emerging joining technologies test qualification pathways.
- Bolts:Hot-forged high-tensile fasteners rated 10.9 or 12.9 property class withstand cyclic loading across tower splices and nacelle anchors. Demand concentrates in monopile foundation contracts along China's Jiangsu and Guangdong coastal corridors, driven by state-backed offshore capacity additions requiring salt-spray-certified grades.
- Nuts:Precision-threaded mating components manufactured through cold or hot forming ensure preload retention under vibration fatigue. Procurement volumes track OEM direct contracting patterns, with Nordic forging specialists capturing North Sea offshore specifications through DNV-ST-0126 certification.
- Washers:Load-distribution elements prevent galling in flange connections subject to thermal cycling.
- Rivets:Permanent mechanical fasteners find limited application in specialized blade root assemblies and access platform construction.
Bolts handle the majority of throughput; composite-embedded alternatives are the fastest mover on share.
Application:
Cost tier separation between capital installation and recurring maintenance creates divergent specification requirements.
- Turbine Assembly:Nacelle component bolting demands precision preload calibration for gearbox and generator mounting frames. Vestas and Siemens Gamesa specify hydraulic tensioning protocols for main shaft bearing housings, concentrating procurement with ITH Bolting Technology and comparable equipment-integrated suppliers.
- Blade Attachment:Root segment joining faces mass-reduction pressures as rotor diameters expand beyond 15 meters. Fiber-reinforced polymer fastener trials at carbon fiber root attachments represent specification disruption for traditional metallic joining.
- Tower Construction:Sectional steel tube splicing relies on circumferential flange bolting with corrosion-resistant coatings.
- Maintenance:Replacement fastener demand follows installed base age profiles and inspection cycle findings.
Tower construction absorbs the largest capital allocation; blade attachment applications are climbing the fastest on specification innovation.
Material:
Supply concentration around duplex stainless capacity shapes geographic procurement patterns.
- Stainless Steel:Duplex and super-duplex grades provide cathodic protection compatibility for subsea bolting in North Sea and Atlantic offshore environments. REACH hexavalent chromium restrictions are forcing coating conversion to zinc-nickel alternatives without guaranteed performance equivalence, compressing margins on European-qualified material.
- Carbon Steel:Property class 8.8 and 10.9 fasteners serve onshore tower and foundation applications with lower corrosion exposure. Chinese GB standards and NMPA-adjacent certification requirements create parallel compliance tracks for domestic turbine builders versus export markets.
- Alloy:Nickel-molybdenum enhanced grades withstand extreme fatigue cycling in critical load paths.
- Composite:Fiber-reinforced polymer joining elements test qualification for mass-critical blade root applications.
Carbon steel moves the highest tonnage; composite formulations are expanding most quickly on R&D allocation.
Installation Type:
Geography-driven specification divergence separates fixed-bottom from floating foundation requirements.
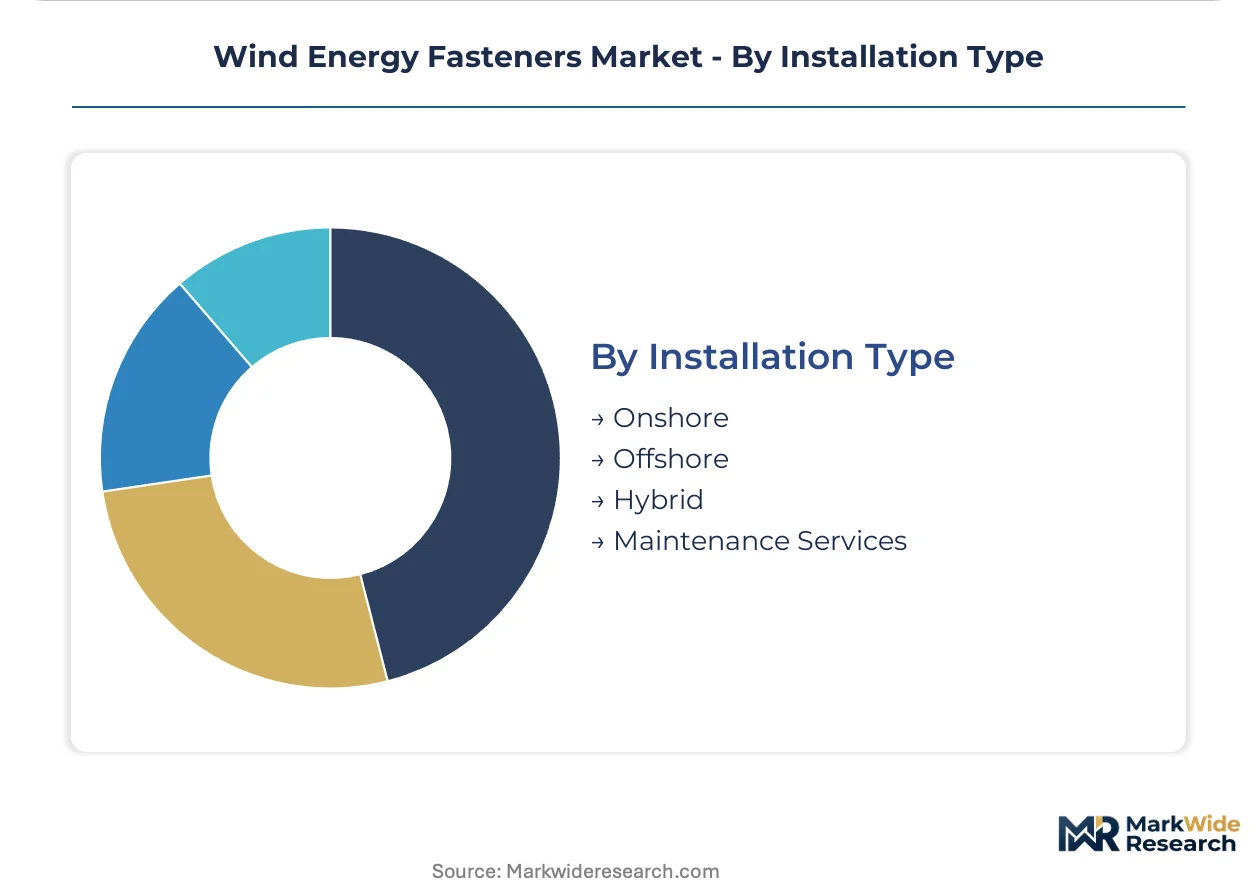
- Onshore:Ground-level foundation anchoring and tower erection use standard weathering-grade fasteners with conventional torque-controlled installation. Procurement flows through industrial distribution networks serving regional construction contractors with less stringent certification burdens than offshore equivalents.
- Offshore:Subsea bolting for monopile and jacket foundations demands duplex stainless grades, cathodic protection compatibility, and DNV fatigue certification. German and Danish port authorities enforce REACH coating compliance at customs, rejecting non-conforming shipments.
- Hybrid:Near-shore installations blend onshore installation methods with marine-grade material specifications.
- Maintenance Services:Offshore vessel-based replacement operations require pre-tensioned inventory and technician mobilization.
Onshore installations account for the greatest unit volume; floating platform foundations are gaining share fastest on unpenetrated specification territory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
IRA domestic content bonuses are reshaping procurement geography along the US Atlantic coast, while EU F-Gas Regulation enforcement tightens qualification requirements for North Sea offshore suppliers. China's state-backed coastal wind corridors concentrate forging capacity within domestic supply chains.
United States
Offshore lease auctions in Massachusetts and New York waters are driving monopile foundation demand. IRA tax credits incentivize localized forging capacity along Atlantic manufacturing zones. Port infrastructure investments in New Bedford and Portsmouth are clustering heat-treatment facilities for salt-spray-certified grades.
Germany
North Sea offshore expansion targets 70 GW capacity by 2045, requiring cathodic protection-compatible bolting systems. ECHA REACH enforcement eliminates hexavalent chromium coatings from customs clearance at Bremerhaven and Cuxhaven. Rostock and Wilhelmshaven port clusters host DNV-ST-0126-certified forging specialists for jacket foundation contracts.
China
Jiangsu and Guangdong provincial governments direct state-owned turbine builders toward captive fastener supply. GB standards and NMPA-adjacent certification requirements create parallel compliance tracks for domestic versus export markets. Yangtze River Delta forging clusters around Ningbo and Shanghai dominate monopile bolt procurement volumes.
United Kingdom
Dogger Bank and Hornsea development phases sustain demand for super-duplex subsea bolting. HSE offshore safety regulations align with DNV fatigue testing protocols for tower flange connections. Humber port infrastructure around Hull and Grimsby concentrates hydraulic tensioning service capabilities.
Denmark
Ørsted and Vestas headquarters proximity creates specification authority concentration for smart bolting pilot programs. Danish Maritime Authority enforcement of EU F-Gas corrosion mandates rejects non-conforming shipments at Esbjerg port. Esbjerg and Frederikshavn industrial zones anchor Nordic salt-spray-certified capacity.
Wind Energy Fasteners Market Competitive Landscape
On the supply side, the industry is consolidating around direct OEM-forger contracts that disintermediate traditional distribution tiers. Tier-one turbine builders establish multi-year offtake agreements with certified forging specialists, compressing margin capture toward DNV-qualified offshore capacity. Three strategic archetypes dominate: Nordic heritage suppliers with North Sea certification, Chinese state-linked fabricators with domestic captive demand, and diversified industrial conglomerates with broad geographic coverage. Competitive moves center on backward integration into heat-treatment assets and sensor-embedded smart bolting technology licensing.
Within the Nordic-certified tier, Dokka Fasteners and ITH Bolting Technology exemplify specification-grade positioning for offshore fatigue requirements. Stanley Black & Decker occupies a diversified industrial position spanning onshore distribution and maintenance segments through its network infrastructure. Among German precision fabricators, August Friedberg GmbH and Graewe GmbH & Co. KG represent mid-cap forging specialists with DNV-ST-0126 qualification pathways. Chinese state-directed procurement patterns favor Finework (Hu Nan) New Energy Technology Co., Ltd. as a domestic corridor supplier aligned with CSSC and CRRC capacity additions.
| Leading Market Players |
|---|
| Dokka Fasteners |
| Dyson Corp. |
| August Friedberg GmbH |
| Finework (Hu Nan) New Energy Technology Co., Ltd. |
| Stanley Black & Decker |
| Graewe GmbH & Co. KG |
| ITH Bolting Technology |
| Oglaend System AS |
| Hilti Corporation |
| Others |
Pricing and Supply Chain Analysis
Nickel and molybdenum alloy price volatility compresses margins on duplex stainless grades while simultaneously forcing buyers toward long-term offtake contracts that reshape forging capacity geography. This input cost instability widens spreads between DNV-certified offshore bolts and standard onshore grades while concentrating procurement power with turbine OEMs capable of volume guarantees.
Pricing Analysis
Certification level creates the primary spread across wind energy fastener pricing, with DNV-ST-0126 fatigue-certified offshore bolts commanding substantial premiums over ISO 898-1 standard grades. Three-tier pricing structure separates salt-spray-certified super-duplex systems from hot-forged carbon steel tower bolts and economy-grade maintenance replacements. Cost compression in carbon steel tiers is intensifying because Chinese state-backed procurement funnels volume through captive forging subsidiaries. Onshore construction contractors exhibit highest price sensitivity, while North Sea offshore developers prioritize cathodic protection compatibility over unit economics.
Supply Chain Analysis
Tariff exposure between China and Western offshore markets dominates supply chain risk calculus for turbine OEMs seeking dual-source forging capacity. Production gravity centers on Ningbo-Shanghai corridor, North Sea port clusters around Esbjerg and Bremerhaven, and emerging Atlantic coast heat-treatment facilities. Raw material flows draw from Indonesian nickel processing, European scrap alloy recovery, and domestic molybdenum concentrate. Single-source vulnerability concentrates in hydraulic tensioning equipment paired with specification-grade fasteners. Distribution runs through direct OEM-forger contracts that disintermediate industrial distributors from DNV-qualified procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct contracting between turbine OEMs and forging specialists fragments supply into certification-tier niches, creating entry points for specialists outside traditional distribution hierarchies. Floating platform foundation designs and composite blade root joining represent the most penetrable white-space segments.
For Market Incumbents: Build certification moats around DNV-ST-0126 fatigue testing capacity and smart bolting sensor integration. Secure multi-year offtake agreements with Vestas and Siemens Gamesa before Chinese state-linked fabricators achieve European qualification. Backward integration into heat-treatment assets in Esbjerg and Wilhelmshaven port zones defends geographic positioning against Atlantic coast IRA-incentivized competitors. For New Entrants and Emerging Players: Build out floating platform pre-tensioned connection expertise outside fixed-bottom experience bases. Target semi-submersible foundation contracts in US Atlantic lease areas where domestic content bonuses disadvantage established Nordic suppliers. Fiber-reinforced polymer fastener qualification for carbon fiber blade roots offers technology-licensing entry without forging capital intensity. For Investors and Strategic Acquirers: EU F-Gas Regulation enforcement reshapes the acquisition landscape by eliminating hexavalent chromium coating capacity from investable asset pools. Five-to-ten year viability favors mid-cap forging specialists with zinc-nickel conversion completed and DNV fatigue testing protocols operational. Acquisition target archetype: Nordic-certified specialists with salt-spray capacity and hydraulic tensioning service integration. Signal to watch: German and Danish customs rejection rates for non-REACH-compliant shipments as indicator of regulatory chokepoint severity.| Strategic Initiative | Industry Significance |
|---|---|
| DNV-ST-0126 Certification Investment | Qualification for North Sea monopile contracts requires 18-month fatigue testing protocols. |
| Smart Bolting Sensor Integration | Vestas and Siemens Gamesa pilot programs hybridize hardware with digital service revenue streams. |
| Zinc-Nickel Coating Conversion | ECHA REACH sunset dates eliminate cadmium and hexavalent chromium from European supply chains. |
| Atlantic Coast Heat-Treatment Capacity | IRA domestic content bonuses incentivize localized forging along Massachusetts and New York port zones. |
| Composite Fastener R&D Partnership | Blade manufacturers test fiber-reinforced polymer joining at carbon fiber root attachments. |
Research Methodology
The analysis maps hot-forged bolting systems, hydraulic tensioning equipment, surface coating technologies, and composite joining solutions, each validated through procurement directors at turbine OEMs, forging plant managers, port authority compliance officers, and offshore installation contractors. Primary fieldwork combined with secondary validation from DNV certification databases, ECHA REACH substance restriction filings, customs trade records, and state-owned enterprise procurement disclosures. Bottom-up volume estimates triangulate against top-down capacity assessments across Ningbo-Shanghai, North Sea, and Atlantic coast forging clusters.
Forecast assumptions hold fixed current EU F-Gas Regulation enforcement intensity, IRA domestic content bonus structures, and GB standards certification requirements for Chinese domestic market access while varying floating platform adoption rates and composite fastener qualification timelines. Segmentation dimensions modeled include product type, application, material grade, and installation environment across onshore, fixed-bottom offshore, and floating foundation categories. CAGRs derive from installed capacity projections, replacement cycle analysis, and specification upgrade intensity in corrosion-resistant grades.
Sensitivities concentrate around nickel-molybdenum alloy price swings, DNV certification timeline extensions, and REACH coating authorization enforcement shifts. Forecasts reflect documented assumptions regarding state-backed procurement concentration in China and direct OEM contracting migration in Western markets. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Global Plastic Valves Market
Valves
Safety Valve Market
Valves
Oil Drain Valves Market
Valves
Electro Pneumatic Positioner Market
Valves
Pulsation Dampeners Market
Valves
Emergency Shut Down Valves (ESDV) Market
Valves
Global Stainless Steel Control Valves Market
Valves
One-Way Valve Market
Valves
Christmas Tree Valves Market
Valves
Compressor Valves Market
Valves
Global Gate Valve Market
Valves
Motorized Valves Market
Valves
Naval Actuators and Valves Market
Valves
Global Valves Market
Valves
Steam Trap Valve Market
Valves
Global Control Valves Market