
 Middle East and Africa Machined Seals Market | 2026-2036
Middle East and Africa Machined Seals Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Machined Seals Market Foresight
PTFE compounds and advanced thermoplastics is rebalancing cost-performance trade-offs for high-temperature seal applications across the Middle East and Africa. EagleBurgmann Saudi Arabia leverages its localized manufacturing footprint to serve Aramco-affiliated maintenance schedules with reduced lead times. AESSEAL Saudi Arabia Co. Ltd. anchors its regional position through aftermarket service density in the Eastern Province industrial cluster. Arabian Seals Company Ltd. differentiates via composite material expertise tailored to sour gas service conditions.
Machined seals are precision-engineered components manufactured to tight tolerances, typically from metals, elastomers, or polymer composites, designed to prevent fluid or gas leakage between mating surfaces in rotating or static equipment. These components function through controlled compression and material resilience, maintaining seal integrity across pressure differentials ranging from vacuum to extreme process conditions in hydrocarbon processing and power generation systems. The O-Rings and Gaskets product categories dominate current procurement volumes due to their ubiquity in standard flange and groove applications across refinery turnaround cycles. Composite material formulations represent the fastest-expanding segment as operators seek chemical resistance without the weight penalties of all-metal constructions. Oil and Gas end users command the deepest margin pools given the technical certification requirements and penalty costs of unplanned downtime in upstream and midstream assets.
Saudi Arabia's Standards, Metrology and Quality Organization and the UAE's Emirates Authority for Standardization and Metrology enforce material traceability and pressure-equipment conformity protocols that directly determine supplier qualification status. The Gulf Standardization Organization's harmonized technical regulations for petroleum equipment create cross-border compliance obligations that favor seal manufacturers with multi-country certification holdings. Buyers must monitor how evolving national content requirements and local value-add mandates reshape sourcing decisions across the GCC industrial base.
Market Dynamics
The UAE's tightened fugitive emission standards under its national air quality framework is compressing procurement cycles and forcing operators toward higher-specification sealing solutions across downstream maintenance schedules.
Growth Catalysts
- Petrochemical capacity expansions:Saudi Arabia's industrial corridor around Jubail and Yanbu requires precision-engineered seal replacements at scale as downstream operators execute turnaround cycles.
- SFDA material traceability mandates:Saudi Arabia's Standards, Metrology and Quality Organization enforces pressure-equipment conformity protocols that directly expand qualified supplier volumes.
- Advanced thermoplastic formulations:PTFE compounds and polymer composites are rebalancing cost-performance trade-offs for high-temperature applications in sour gas service conditions.
Market Restraints
- Specialized alloy input volatility:Inconel and Hastelloy price swings compress margin pools for metal-to-metal seal manufacturers serving high-pressure hydrocarbon systems.
- Multi-country certification burdens:Gulf Standardization Organization harmonized technical regulations create cross-border compliance obligations that favor incumbent suppliers with established multi-jurisdiction holdings.
- Preformed seal substitution:Molded elastomeric seals in standard flange applications displace machined alternatives in low-pressure utility systems.
Strategic Opportunities
- East African industrial corridors:Ethiopia and Tanzania's emerging fertilizer and cement complexes present greenfield seal specification windows before incumbent supplier lock-in solidifies.
- UAE local value-add mandates:Emirates Authority for Standardization and Metrology procurement guidelines reward in-country assembly and testing capabilities for maintenance contractors.
- Digital twin integration:Convergence of predictive maintenance platforms with seal performance monitoring creates subscription-based service revenue streams for technical distributors.
Industry Challenges
- Precision machining talent scarcity:CNC programming and five-axis grinding expertise shortages in the Eastern Province industrial cluster constrain capacity expansion timelines.
- API 6A certification timelines:Wellhead equipment qualification protocols require 12-18 month validation cycles that delay new material introductions.
- Legacy system integration friction:Existing pump and compressor fleets with imperial groove specifications complicate metric-standard seal retrofit programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Machined Seals Market |
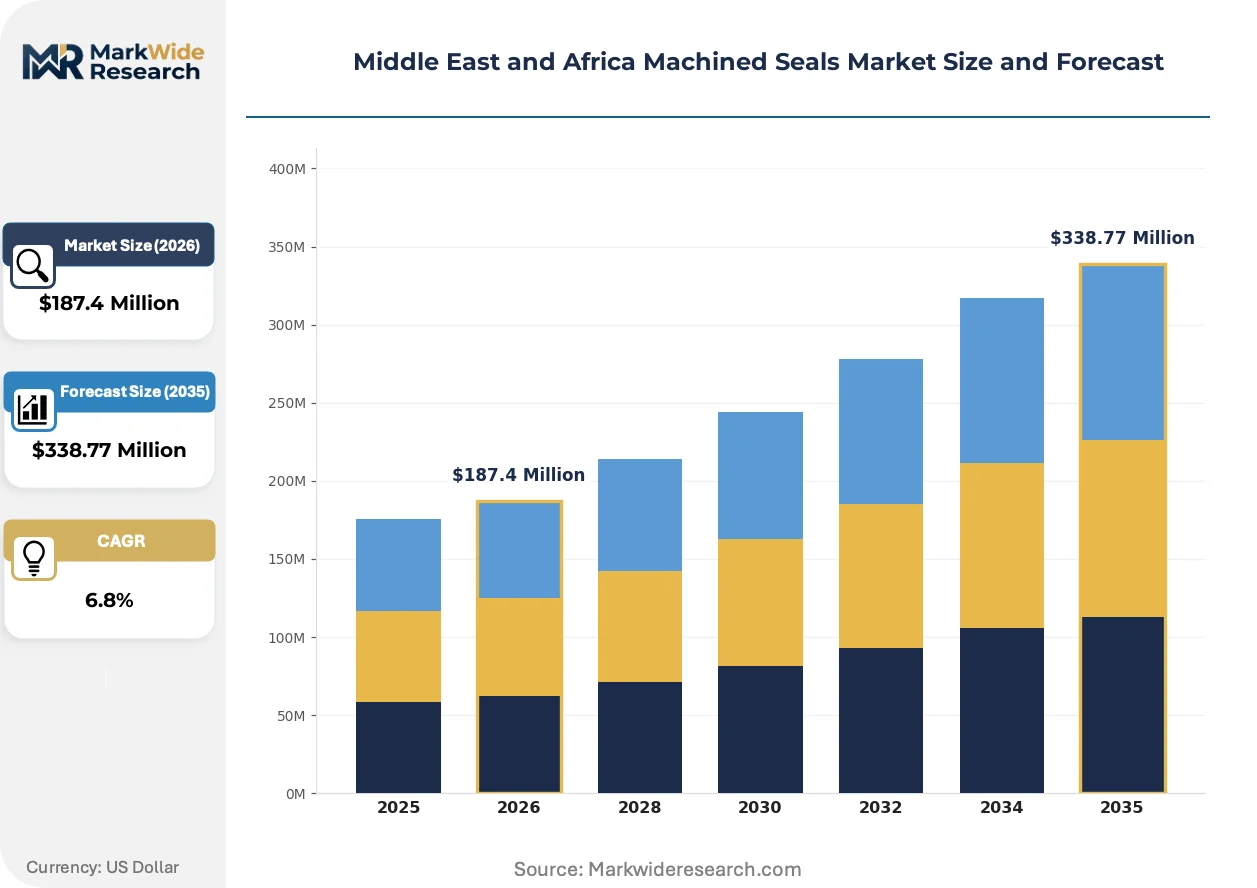
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: O-Rings, Gaskets, Bearings, Bushings Material: Metal, Rubber, Composite, Plastic End User: Aerospace, Automotive, Oil & Gas, Manufacturing Application: Hydraulic Systems, Pneumatic Systems, Valve Sealing, Pump Sealing |
| Companies Covered | EagleBurgmann Saudi Arabia, AESSEAL Saudi Arabia Co. Ltd., Arabian Seals Company Ltd. (ASC), Sealmatic Oman, Quantech Seal Manufacturing LLC, QMS Seals, Precision Polymer Engineering (PPE LLC), Hydrofit Engineering Sharjah, Bliss Anand KSA, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Machined Seals Market Shifts & Advancements
Material science advances and regulatory stringency are compressing traditional metal-elastomer trade-offs while reshaping how operators specify, procure, and maintain sealing systems across hydrocarbon processing assets.
Hybrid PTFE-graphite compounds with bronze or glass fiber fillers are consolidating market share in high-temperature rotary applications previously dominated by all-metal labyrinth designs. Aramco-affiliated refineries are adopting these formulations at accelerated rates for boiler feed pump and compressor seal upgrades. The shift is consolidating supplier margins around material science capabilities rather than pure machining scale.
MOHAP's alignment with ISO 15848 fugitive emission testing protocols is tightening qualification thresholds for valve and flange seals in UAE petrochemical facilities. The industrial consequence is disqualification of uncertified suppliers from national oil company procurement lists. Composite seal manufacturers with pre-existing ISO 15848-1 Class BH certification are capturing specification authority in Abu Dhabi National Oil Company maintenance contracts.
Buyer consolidation around integrated maintenance contractors is compressing direct OEM seal procurement in favor of bundled aftermarket service agreements. Technical distributors with localized inventory and field machining capabilities are displacing traditional manufacturer-direct channels. This pattern is most visible in Saudi Arabia's Eastern Province, where SABIC-affiliated complexes have centralized seal procurement through three approved maintenance integrators.
Middle East and Africa Machined Seals Market Segmentation
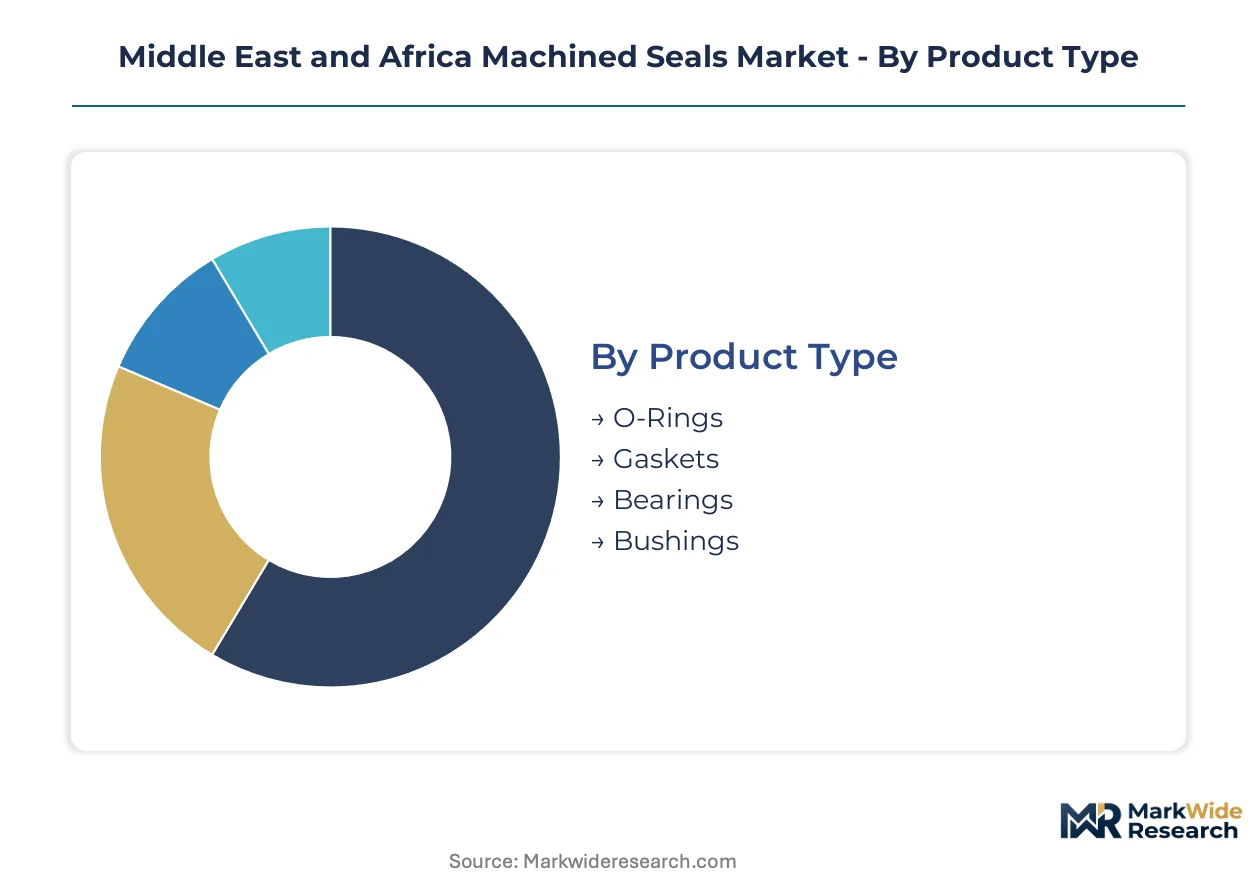
Segmentation in the Middle East and Africa machined seals market reveals how procurement authority concentrates around specific material certifications and end-use compliance requirements. Understanding these divisions exposes where margin pools deepen and where supplier qualification barriers create defensive moats.
Product Type:
Supply concentration in the Eastern Province industrial cluster favors manufacturers with localized CNC machining capacity for high-volume rotary seal categories.
- O-Rings:Circular elastomeric or thermoplastic rings seated in grooves, compressed between mating surfaces to block fluid escape. Procurement volumes concentrate in Saudi Arabia's Jubail petrochemical corridor where flange maintenance cycles drive recurring replacement schedules.
- Gaskets:Static seals manufactured from sheet materials or precision-cut composites, engineered to fill irregularities between flange faces. UAE refinery turnaround contractors specify these for heat exchanger and pressure vessel applications under tightened fugitive emission standards.
- Bearings:Load-supporting rotary elements with integrated sealing lips for contamination exclusion.
- Bushings:Cylindrical sleeves reducing friction and wear in oscillating or reciprocating assemblies.
Today's leader: O-Rings. Tomorrow's challenger: Gaskets.
Material:
Cost-performance trade-offs in high-temperature hydrocarbon service are compressing traditional metal-elastomer hierarchies across GCC processing assets.
- Metal:Inconel, Hastelloy, and stainless steel alloys machined to sub-micron tolerances for extreme pressure differentials. Sour gas wellhead equipment in Saudi Arabia requires these formulations where elastomer degradation risks unplanned shutdown penalties.
- Composite:PTFE-graphite compounds with bronze or glass fiber fillers consolidating share in boiler feed pump and compressor seal upgrades previously using all-metal labyrinth designs.
- Rubber:Nitrile, fluorocarbon, and perfluoroelastomer formulations for standard temperature ranges.
- Plastic:Engineering thermoplastics including PEEK and UHMW-PE for chemical resistance without metallic weight penalties.
Metal commands specification authority today. Composite formulations are climbing the fastest as Aramco-affiliated refineries accelerate material trials.
End User:
Margin depth varies sharply by certification burden and downtime penalty exposure across industrial sectors in the Middle East and Africa.
- Oil & Gas:Upstream, midstream, and downstream operators commanding the deepest margin pools given API 6A certification requirements and penalty costs of unplanned downtime in hydrocarbon assets. Procurement centralization through SABIC-affiliated maintenance integrators in the Eastern Province is reshaping supplier access.
- Automotive:Assembly plants and tier suppliers specifying precision seals for transmission and engine systems. South African manufacturing corridors generate steady demand for high-volume elastomeric replacements.
- Aerospace:MRO facilities and OEM tier suppliers requiring material traceability and AS9100 quality system compliance.
- Manufacturing:General industrial machinery maintenance spanning cement, fertilizer, and steel processing facilities.
Oil & Gas anchors revenue concentration. Manufacturing offers volume scale with thinner margins.
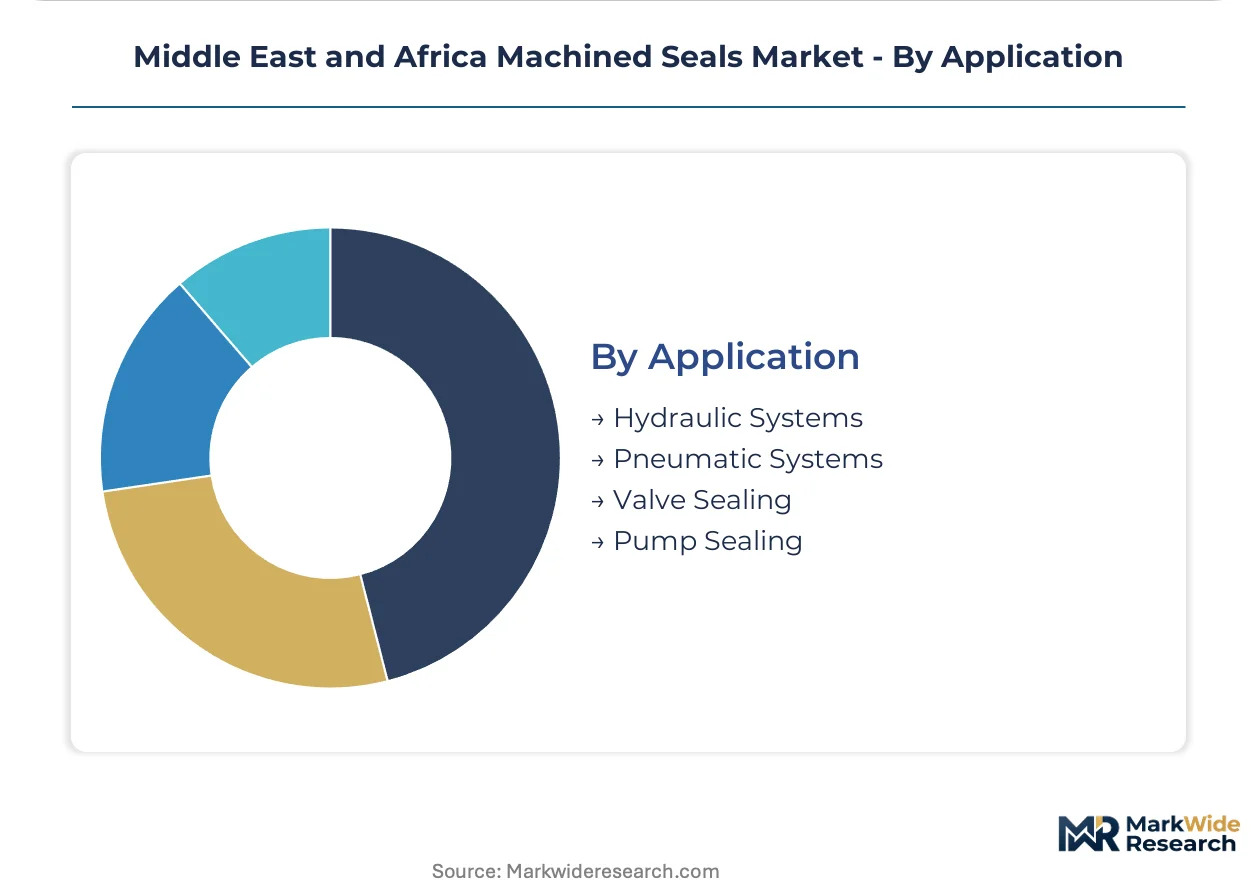
Application:
Functional specifications in rotating versus static equipment create divergent supplier qualification pathways across the region.
- Hydraulic Systems:Dynamic seals containing pressurized fluid in cylinders and actuators, subject to reciprocating wear and extrusion failure modes. Mobile equipment fleets in UAE construction and logistics sectors drive aftermarket replacement cycles.
- Pump Sealing:Mechanical and packed seal configurations for centrifugal and positive displacement pumps. API 682 compliance requirements in Saudi Arabian refinery boiler feed water systems restrict qualified supplier pools.
- Pneumatic Systems:Low-friction seals for compressed air circuits in automation and process control.
- Valve Sealing:Stem, seat, and flange gaskets isolating process fluids in isolation and control valve assemblies.
Hydraulic systems dominate current procurement volumes. Pump sealing represents the steepest expansion trajectory as predictive maintenance platforms extend seal life monitoring contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's Eastern Province industrial cluster anchors machined seal procurement volumes across the Middle East and Africa, with Jubail and Yanbu petrochemical complexes driving replacement cycles for precision-engineered components.
Saudi Arabia
Aramco-affiliated refineries and SABIC complexes in Jubail execute continuous turnaround schedules requiring API-certified seal replacements. SFDA enforces material traceability protocols that expand qualified supplier pools for pressure-equipment conformity. The Eastern Province concentration around Dammam hosts localized CNC machining capacity serving maintenance integrators.
United Arab Emirates
ADNOC maintenance contracts and downstream refinery upgrades in Ruwais generate specification-grade demand for fugitive emission-compliant sealing solutions. MOHAP's alignment with ISO 15848 testing protocols tightens qualification thresholds for valve and flange seals. Dubai-based technical distributors with field machining capabilities capture procurement authority from manufacturer-direct channels.
South Africa
Sasol's Secunda coal-to-liquids complex and emerging renewable hydrogen pilot projects require specialized seals for syngas and high-pressure process conditions. The country's national standards regulator enforces pressure-equipment safety codes that determine supplier access. KwaZulu-Natal industrial corridors around Durban sustain aftermarket replacement cycles for chemical processing and pulp mill assets.
Egypt
Suez Canal petrochemical zones and Mediterranean LNG export terminals drive procurement for cryogenic and high-temperature seal applications. The Egyptian Organization for Standardization and Quality administers conformity assessment protocols for imported industrial components. Alexandria's manufacturing base hosts regional distribution hubs serving North African maintenance contractors.
Oman
Duqm refinery and petrochemical complex construction creates greenfield specification windows for machined seal suppliers before incumbent lock-in solidifies. The country's national standards body implements petroleum equipment technical regulations aligned with Gulf Standardization Organization harmonized frameworks. Sohar industrial port concentration attracts seal fabricators establishing localized assembly and testing capabilities.
Middle East and Africa Machined Seals Market Competitive Landscape
Global majors compete with regional champions across certification density and aftermarket service reach. The vendor base stratifies between integrated sealing system providers and specialized machining houses, with qualification barriers favoring incumbents holding multi-jurisdiction API and ISO certifications. Three archetypes dominate: European-origin majors with localized Saudi manufacturing, Gulf-based technical distributors with field service density, and Indian-subcontinent fabricators competing on cost-position for standard elastomeric replacements. Competitive moves concentrate on capacity expansion in the Eastern Province industrial cluster and strategic partnerships with maintenance integrators consolidating procurement authority.
Among Saudi-based operations, EagleBurgmann Saudi Arabia and AESSEAL Saudi Arabia Co. Ltd. exemplify the localized manufacturing archetype, while Arabian Seals Company Ltd. occupies a position within the specialized composite materials tier. These entities represent how regional licensing arrangements and in-country value-add capabilities determine competitive access to national oil company procurement lists.
| Leading Market Players |
|---|
| EagleBurgmann Saudi Arabia |
| AESSEAL Saudi Arabia Co. Ltd. |
| Arabian Seals Company Ltd. (ASC) |
| Sealmatic Oman |
| Quantech Seal Manufacturing LLC |
| QMS Seals |
| Precision Polymer Engineering (PPE LLC) |
| Hydrofit Engineering Sharjah |
| Bliss Anand KSA |
| Others |
Supply & Pricing Matrix
Hybrid PTFE-graphite compound adoption in Aramco-affiliated refineries is simultaneously compressing all-metal seal margins and concentrating procurement authority around material-science-capable suppliers in Saudi Arabia's Eastern Province. This technology transition rewards localized CNC machining capacity while penalizing distant fabricators unable to meet API 682 compliance timelines for boiler feed pump upgrades.
Pricing Analysis
Specialized alloy input volatility in Inconel and Hastelloy markets passes through directly to metal-to-metal seal quotations for sour gas wellhead applications. Three-tier pricing structure across API-certified premium, ISO-standard mid-tier, and uncertified economy levels separates Aramco-approved suppliers from maintenance integrator channels. Cost compression in the economy tier intensifies as Indian-subcontinent fabricators compete for standard elastomeric replacements. Downstream operators in SABIC-affiliated complexes exhibit lowest price sensitivity given unplanned downtime penalties, while cement and fertilizer procurement teams in East Africa drive hardest bargain terms.
Supply Chain Analysis
SFDA local value-add mandates and Emirates Authority for Standardization and Metrology procurement guidelines are reshaping sourcing toward in-country assembly and testing capabilities across the GCC. Supply concentration centers on Saudi Arabia, the UAE, and Oman, with raw material dependencies spanning PTFE resin feedstocks, bronze powder fillers, and high-performance elastomer compounds. Single-source vulnerability runs through specialized alloy suppliers serving high-pressure hydrocarbon systems. Distribution runs through technical distributors with field machining capabilities displacing manufacturer-direct channels in the Eastern Province industrial cluster.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa machined seals market functions as a regulatory compounder where SFDA material traceability mandates and MOHAP's ISO 15848 alignment continuously expand qualified supplier pools while compressing procurement cycles for non-compliant competitors.
For Market Incumbents: Anticipate displacement by maintenance integrators consolidating procurement authority through bundled aftermarket service agreements. Defensive positioning requires deepening API 6A certification holdings across multiple Gulf Standardization Organization jurisdictions while expanding localized CNC capacity in Dammam to match EagleBurgmann Saudi Arabia's lead-time advantages. Channel control through exclusive technical distributor partnerships offers the strongest defensive lever against direct procurement erosion.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in composite seal formulations opens specification windows in Duqm's greenfield petrochemical construction before incumbent lock-in solidifies. White-space targets concentrate in East African industrial corridors around Ethiopian fertilizer complexes and Tanzanian cement plants where certification burdens remain lighter. A field-machining-plus-local-inventory go-to-market angle bypasses the 12-18 month API 6A validation cycles blocking direct refinery access.
For Investors and Strategic Acquirers: Valuations sit cheapest among Indian-subcontinent fabricators lacking GCC certification density but possessing cost-position for standard elastomeric volume. Long-term viability across the analysis window favors acquisition targets with pre-existing ISO 15848-1 Class BH certification and established maintenance integrator relationships. The signal to watch is ADNOC procurement list revisions following MOHAP regulatory updates.
| Strategic Initiative | Industry Significance |
|---|---|
| API 6A Certification Expansion | Multi-jurisdiction qualification holdings unlock Aramco and ADNOC maintenance contract access. |
| Localized CNC Capacity Buildout | Eastern Province machining presence matches EagleBurgmann Saudi Arabia's turnaround response capabilities. |
| Composite Material R&D Partnership | PTFE-graphite formulation expertise captures specification authority in high-temperature rotary applications. |
| Maintenance Integrator Alliance | Exclusive service agreements with SABIC-affiliated contractors displace direct OEM procurement channels. |
| East African Distribution Establishment | Pre-incumbency positioning in Ethiopian and Tanzanian industrial corridors secures greenfield specification windows. |
Research Methodology
Bottom-up oil and gas operator modeling reconciled against top-down seal manufacturer capacity tracking forms the analytical core of this study. Primary interviews with maintenance directors at SABIC-affiliated complexes, procurement leads at Aramco downstream assets, technical distributors in the Eastern Province, and aftermarket service heads at AESSEAL Saudi Arabia anchored demand-side intelligence. Secondary validation drew from Gulf Standardization Organization technical regulations, SFDA conformity assessment protocols, SEC 10-K filings of listed seal manufacturers, and customs records of PTFE resin and alloy imports into Saudi Arabia and the UAE.
Historical trendline analysis of petrochemical turnaround cycles and refinery maintenance schedules established baseline replacement demand patterns across the projection horizon. The forecast framework models segmentation dimensions spanning product type, material formulation, end-use sector, and application function, with particular weighting on API certification tier and geographic regulatory cluster. CAGRs derive from regression analysis of procurement volume trends against capacity expansion announcements in Jubail, Yanbu, and Ruwais industrial zones, incorporating predictive maintenance platform adoption as a seal life extension variable.
Caveats apply where API 6A certification timeline delays, Inconel price volatility spikes, or sudden shifts in national content requirements could materially shift the outlook. Forecasts reflect assumptions around continued petrochemical capacity execution in Saudi Arabia and sustained regulatory stringency in UAE fugitive emission enforcement. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Asia-Pacific Industrial Valves Market
Valves
Dense Phase Vessels Market
Valves
Asia-Pacific Medium Voltage Switchgear Market
Valves
Fluid Transfer Solutions Market
Valves
3-Way Pilot Operated Directional Control Valves Market
Valves
Electronic Expansion Valves Market
Valves
Sandblast Valves Market
Valves
Gas Equipment Market
Valves
Pipeline and Process Services Market
Valves
Pipeline Pigging System Market
Valves
Degassing Valves Market
Valves
Water Draw Off Valves Market
Valves
Transmission Overload Protectors Market
Valves
Global Globe Valve Market
Valves
Industrial Valves Market
Valves
GCC and MENA Valves Market