
 Hydrogen Liquefaction Unit Market | 2026-2036
Hydrogen Liquefaction Unit Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen Liquefaction Unit Market Insights
Modular packaging of hydrogen liquefaction systems is broadening buyer choice across mid-scale hydrogen hubs and distributed export terminals. Linde leverages its cryogenic engineering heritage to sustain technology leadership in large-scale plant design. Chart Industries anchors North American supply through specialized heat exchanger manufacturing for liquefaction trains.
A hydrogen liquefaction unit is an industrial cryogenic system that cools gaseous hydrogen to approximately minus 253 degrees Celsius, converting it to liquid form for dense storage and efficient transport. The process typically employs multi-stage Claude-Brayton or helium refrigeration cycles with ortho-para hydrogen conversion catalysts to prevent vaporization losses. Multi-stage plant configurations dominate current deployment for export-scale terminals, while modular units represent the fastest-growing segment as developers seek standardized, redeployable assets with shorter commissioning timelines. Cryogenic technology leads the technology dimension, though pulse tube alternatives are gaining traction in research facility deployments where maintenance access is constrained.
The EU Green Deal and F-Gas Regulation are mandating lower-carbon liquefaction processes and restricting high-global-warming-potential refrigerants in new equipment. Japan's METI has established hydrogen supply chain certification rules that directly shape liquefaction unit specifications for export-bound projects. Stakeholders must monitor how evolving refrigerant phase-down schedules and cross-border hydrogen certification standards reshape equipment procurement criteria and supplier qualification thresholds.
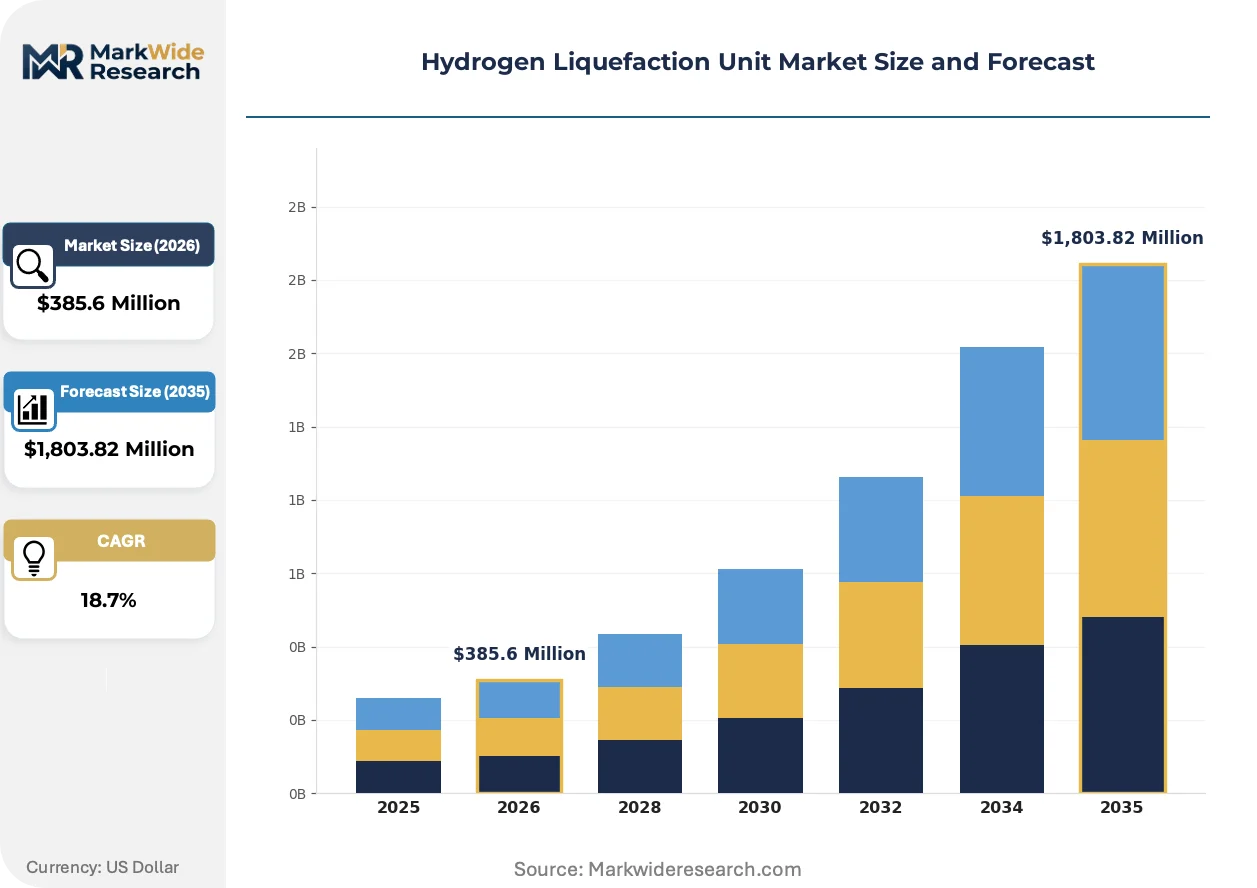
Market Dynamics
Multi-stage Claude-Brayton refrigeration cycles face intensifying pressure from modular pulse tube alternatives as developers prioritize redeployable assets with compressed commissioning timelines over permanent infrastructure commitments.
Growth Catalysts
- EU F-Gas Regulation:Equipment efficiency mandates are accelerating replacement cycles for high-global-warming-potential refrigerant systems across European liquefaction terminals.
- Maritime hydrogen supply chains:Export terminal developers in Germany, Japan, and South Korea are procuring liquefaction trains at unprecedented scale to serve ammonia-to-hydrogen conversion hubs.
- Ortho-para conversion catalysts:Advanced catalyst formulations are reducing vaporization losses in storage, improving round-trip efficiency for long-haul hydrogen transport.
Market Restraints
- Helium supply concentration:Rare gas procurement depends on Qatar, Russia, and Algeria, exposing refrigeration cycle operators to geopolitical supply interruptions.
- Cryogenic steel input costs:Nickel-alloy pressure vessel fabrication requires specialized 9% nickel steel subject to volatile commodity pricing.
- Grid interconnection standards:Japan's METI certification rules create non-tariff barriers for European and North American equipment suppliers.
Strategic Opportunities
- Research facility deployments:Pulse tube refrigeration is penetrating university and national laboratory markets where maintenance access constraints favor solid-state alternatives.
- India's green hydrogen mission:National production targets are catalyzing liquefaction infrastructure investments at ports along the western coastline.
- Heat exchanger standardization:Modular brazed aluminum heat exchanger platforms are enabling supplier-agnostic system integration.
Industry Challenges
- Cryogenic welder certification:Qualified technicians for 9% nickel steel fabrication remain scarce across all major manufacturing regions.
- Legacy hydrogen purity standards:Existing ISO 14687 specifications create friction for novel liquefaction process validation.
- Commissioning timeline compression:Developer pressure for 18-month deployment cycles strains quality assurance protocols for safety-critical systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogen Liquefaction Unit Market |
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $1,803.82 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Stage Plant, Multi-Stage Plant, Systems, Modular Units Technology: Cryogenic, Lo-Cost, Pulse Tube, Helium Refrigeration Application: Transportation, Storage, Power Generation, Industrial Use End User: Energy Sector, Gas Suppliers, Industrial Manufacturers, Research Facilities |
| Companies Covered | Linde, Air Liquide, Air Products and Chemicals, Inc., Chart Industries, Kawasaki Heavy Industries, Iwatani Corporation, Siemens Energy, Honeywell International Inc., Baker Hughes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen Liquefaction Unit Market Trends and Innovations
Equipment manufacturers are converging on standardized module architectures that sacrifice peak efficiency for operational flexibility and redeployment optionality across evolving hydrogen hub locations.
Pulse tube cryocoolers are rewriting deployment economics for distributed liquefaction. Research institutions and remote demonstration projects are adopting these maintenance-free systems despite higher capital costs. The technology is compressing the viable scale floor for liquefaction investments, enabling pilot-scale validation before export-terminal commitments.
Japan's METI hydrogen supply chain certification is mandating full lifecycle carbon accounting for liquefaction equipment. Terminal developers must document electricity sourcing and refrigerant leakage rates to qualify for subsidy support. European suppliers are restructuring procurement documentation to satisfy these traceability requirements.
Buyers are unbundling engineering-procurement-construction contracts into separate equipment supply and commissioning service agreements. Mid-scale hub developers prefer this structure to retain operational control while accessing specialized cryogenic expertise. South Korean port authorities pioneered this bifurcation, with German and Australian developers now replicating the model.
Hydrogen Liquefaction Unit Market Segmentation
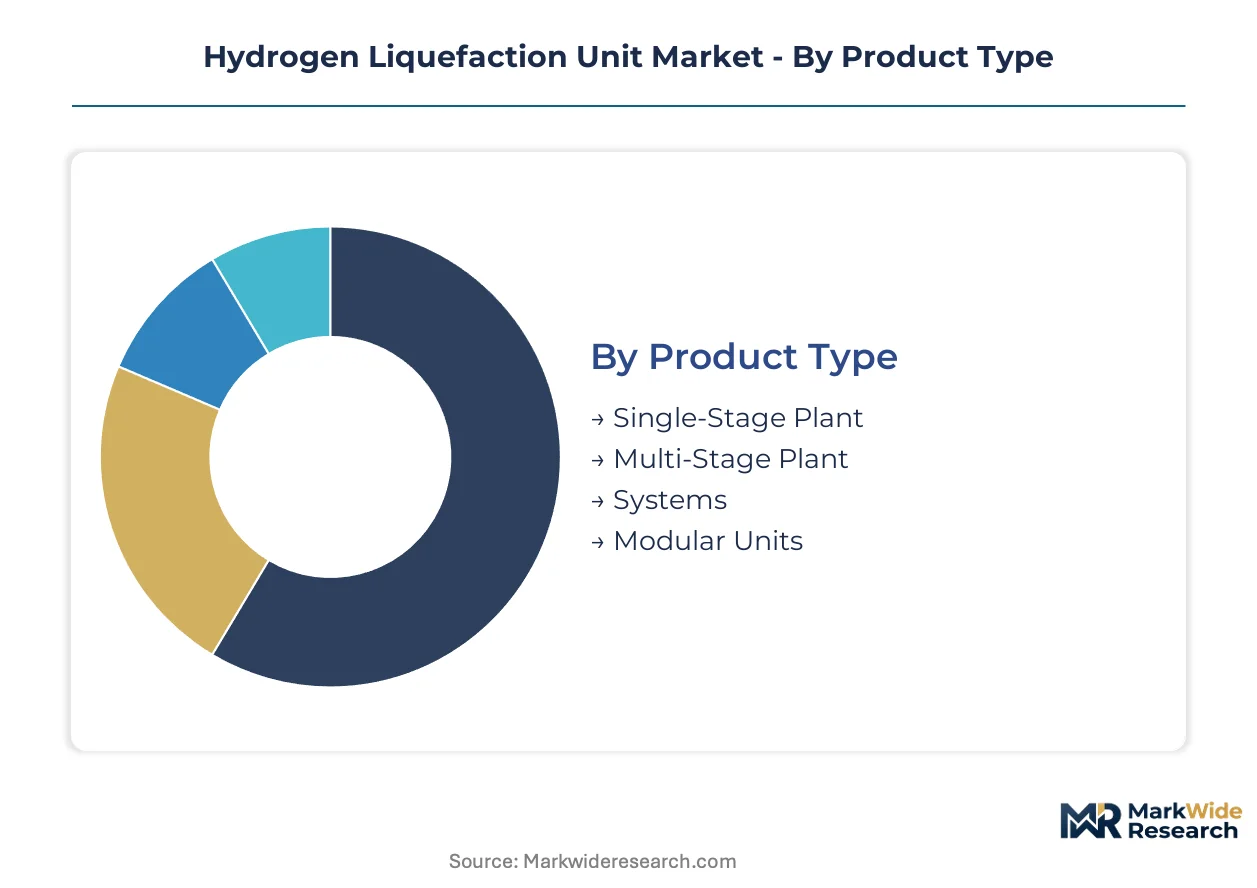
Segmentation in hydrogen liquefaction reveals how equipment specifications diverge across certification regimes, from Japan's METI lifecycle carbon accounting to the EU F-Gas Regulation's refrigerant phase-down schedules. Buyers face distinct compliance burdens depending on which segment combination they procure.
Product Type:
Certification burdens vary sharply by plant scale, with multi-stage configurations triggering Japan's most stringent METI documentation requirements while modular units navigate lighter approval pathways in European ports.
- Multi-Stage Plant:These configurations employ cascaded Claude-Brayton refrigeration cycles with ortho-para conversion stages to achieve the minus 253 degrees Celsius target. German and Japanese export terminal developers concentrate procurement here, driven by maritime hydrogen supply chain mandates requiring maximum throughput density.
- Modular Units:Standardized, redeployable skids compress commissioning timelines to 18 months versus 36-plus for permanent infrastructure. South Korean port authorities pioneered their adoption, with Australian developers now replicating the bifurcated procurement model to retain operational control.
- Single-Stage Plant:Simpler configurations serve pilot-scale validation and research facility deployments where throughput requirements remain modest.
- Systems:Integrated packages combine compression, purification, and liquefaction subsystems for turnkey deployment scenarios.
Multi-stage plant configurations sit at the top of the volume ranking, with modular units climbing the fastest as developers prioritize redeployment optionality.
Technology:
Cost tiers separate these alternatives, with cryogenic systems commanding premium positioning while pulse tube alternatives penetrate price-sensitive research markets despite higher capital outlays.
- Cryogenic:Conventional Claude-Brayton and helium refrigeration cycles dominate export-scale terminals through proven efficiency at megawatt-scale cooling loads. Linde and Chart Industries anchor supply for this technology tier.
- Pulse Tube:Solid-state refrigeration eliminates moving parts at the cold end, enabling maintenance-free operation in remote demonstration projects and university laboratories where technician access is constrained. Research institutions accept 20-30% efficiency penalties for operational simplicity.
- Helium Refrigeration:Dependent on concentrated supply from Qatar, Russia, and Algeria, exposing operators to geopolitical interruption risks that factor into total cost of ownership calculations.
- Lo-Cost:Emerging alternatives target distributed hydrogen hub economics through simplified cycle architectures and reduced nickel-alloy steel requirements.
Cryogenic technology captures the dominant revenue share, though pulse tube alternatives are gaining share fastest in constrained-access deployment scenarios.
Application:
End-use applications map to distinct customer maturity levels, with transportation applications facing the steepest certification requirements while industrial use segments navigate more established approval pathways.
- Transportation:Maritime hydrogen supply chains and heavy-duty fuel cell vehicles demand liquid hydrogen density for viable range economics. German, Japanese, and South Korean port authorities are scaling liquefaction trains specifically for ammonia-to-hydrogen conversion hubs serving shipping corridors.
- Storage:Long-duration energy storage applications prioritize boil-off minimization through advanced ortho-para conversion catalysts, improving round-trip efficiency for seasonal hydrogen reserves.
- Power Generation:Utility-scale hydrogen peaking plants require rapid-dispatch liquid hydrogen supply chains with guaranteed purity specifications.
- Industrial Use:Refinery hydrogen management and ammonia synthesis feedstock applications represent established demand with standardized equipment specifications.
Transportation applications lead absolute volume, with storage applications expanding most quickly as grid-scale seasonal storage projects advance.
End User:
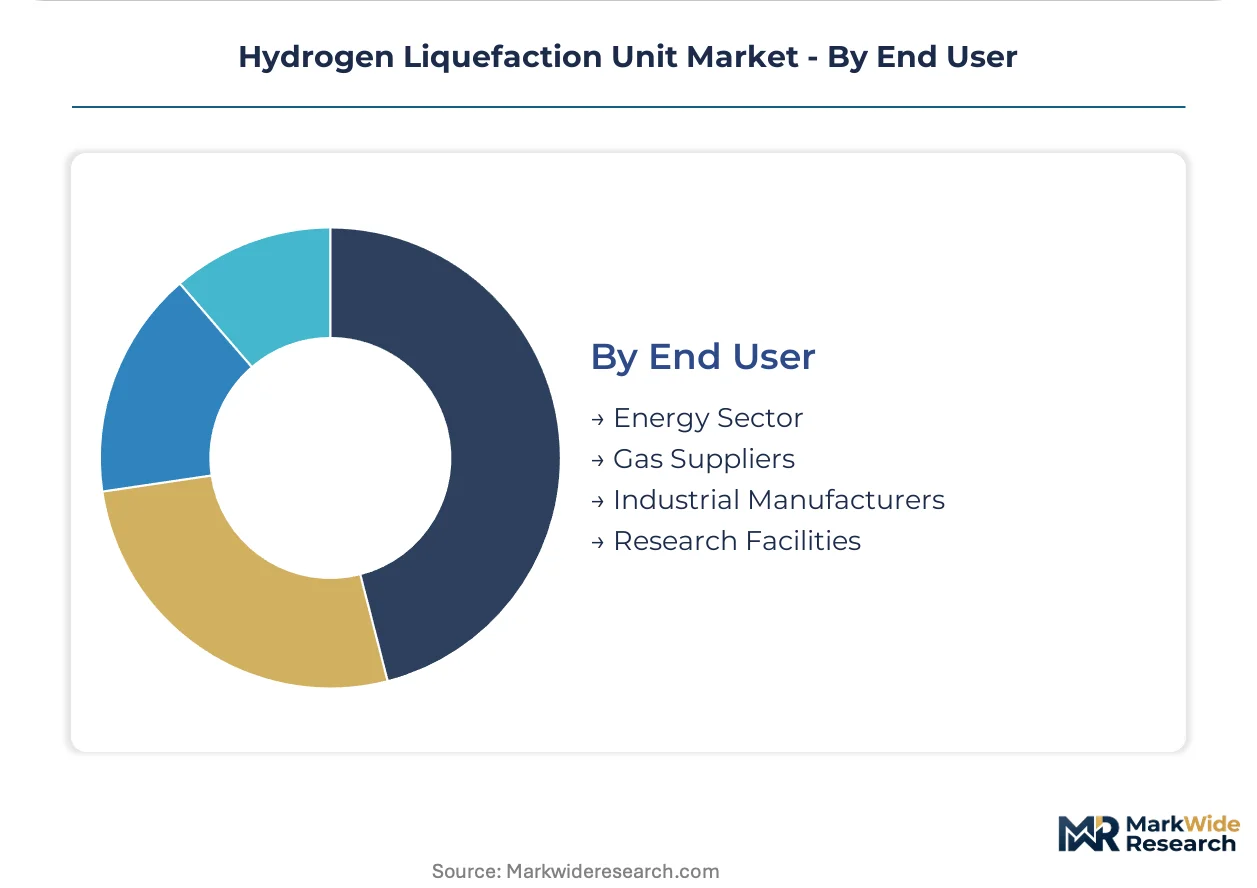
Customer type determines procurement sophistication, with energy sector buyers deploying integrated engineering-procurement-construction capabilities while research facilities prioritize maintenance simplicity over capital efficiency.
- Energy Sector:Integrated oil majors and dedicated hydrogen developers command procurement scale for multi-train export terminals. These buyers unbundle EPC contracts to retain operational control while accessing specialized cryogenic commissioning expertise.
- Research Facilities:National laboratories and university programs favor pulse tube systems despite higher capital costs, accepting efficiency tradeoffs for maintenance-free operation in shielded or remote environments.
- Gas Suppliers:Industrial gas incumbents leverage existing cryogenic infrastructure and customer relationships to anchor liquefaction investments at established production sites.
- Industrial Manufacturers:Steel, chemical, and refining operations procure liquefaction capacity for captive hydrogen management and process integration.
Energy sector buyers dominate procurement volume, with research facilities showing the steepest expansion trajectory as national hydrogen research programs proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hydrogen liquefaction technology first achieved commercial scale in Germany during the 1980s through Linde's development of multi-stage Claude-Brayton systems for industrial gas applications. Today, deployment geography tracks maritime export terminal construction and national hydrogen hub programs across four continents.
Germany
Port authorities at Hamburg and Wilhelmshaven are procuring liquefaction trains for ammonia-to-hydrogen conversion hubs serving North Sea shipping corridors. The EU F-Gas Regulation mandates refrigerant phase-down schedules that reshape equipment specifications for all new terminal builds. Industrial clusters along the Rhine-Ruhr corridor anchor demand for refinery hydrogen management applications.
Japan
METI's hydrogen supply chain certification rules require full lifecycle carbon accounting for liquefaction equipment procured at Kobe and Yokohama terminals. The Kansai region concentrates manufacturing partnerships between heavy industrial conglomerates and cryogenic engineering specialists. Osaka Bay port infrastructure is scaling specifically for liquid hydrogen export to Southeast Asian markets.
South Korea
Ulsan and Busan port authorities pioneered bifurcated procurement models that separate equipment supply from commissioning services. The country's national hydrogen roadmap targets liquefaction capacity expansion for maritime bunkering corridors connecting East Asian manufacturing centers. Daegu-Gyeongbuk industrial complexes supply specialized nickel-alloy pressure vessel components.
United States
Gulf Coast hydrogen hub awards under the Department of Energy's Regional Clean Hydrogen Hubs program are catalyzing liquefaction infrastructure investments at Port of Houston and Corpus Christi. Texas and Louisiana industrial corridors leverage existing cryogenic expertise from LNG operations to accelerate deployment timelines. California's Port of Long Beach is evaluating modular systems for heavy-duty fuel cell vehicle supply chains.
Australia
Western Australia's Pilbara region is developing liquefaction capacity for green hydrogen export to Japanese and South Korean terminals. The country's hydrogen export strategy prioritizes Port of Newcastle and Gladstone as liquefaction hubs serving Asia-Pacific demand. Queensland's renewable energy zones are co-locating electrolysis and liquefaction assets to minimize transport losses.
Hydrogen Liquefaction Unit Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology complexity and project scale dimensions. The vendor base concentrates around cryogenic engineering heritage and specialized heat exchanger manufacturing capabilities. Three archetypes dominate: integrated industrial gas conglomerates with century-long cryogenic expertise, diversified heavy engineering groups with aerospace-derived thermal management capabilities, and specialized equipment fabricators focused on modular system architectures. Competitive moves center on unbundling engineering-procurement-construction contracts and accelerating commissioning timeline compression through standardized module platforms.
Within the integrated industrial gas tier, Linde and Air Liquide exemplify premium-positioned players leveraging proprietary Claude-Brayton cycle expertise accumulated across decades of large-scale plant deployment. Chart Industries occupies a distinct position among North American specialized fabricators, anchoring supply for heat exchanger subsystems that constitute critical path components in liquefaction train assembly. Siemens Energy represents the diversified engineering conglomerate archetype, translating power generation and process industry capabilities into hydrogen infrastructure project execution.
| Leading Market Players |
|---|
| Linde |
| Air Liquide |
| Air Products and Chemicals, Inc. |
| Chart Industries |
| Kawasaki Heavy Industries |
| Iwatani Corporation |
| Siemens Energy |
| Honeywell International Inc. |
| Baker Hughes |
| Others |
Pricing and Supply Chain Analysis
Nickel-alloy steel price indices cascade directly through liquefaction unit cost structures, compressing margins at the modular unit tier while reinforcing premium positioning for multi-stage plant configurations serving METI-certified Japanese terminals. Buyers face stark trade-offs between standardized module economics and permanent infrastructure efficiency as commodity volatility reshapes procurement timelines.
Pricing Analysis
Project-based long-term offtake contracting dominates large-scale terminal procurement, separating METI-certified Japanese builds from EU F-Gas-compliant European configurations and economy-tier modular deployments. Price differentiation hinges on certification grade—Japan's lifecycle carbon accounting commands substantial premiums—and volume scale, with multi-train export terminals securing favorable terms. Cost compression in the modular segment intensifies as South Korean port authorities standardize bifurcated procurement models. Research facilities show least price sensitivity, accepting 20-30% efficiency penalties for pulse tube simplicity.
Supply Chain Analysis
Japan's METI qualification gates restrict European and North American equipment suppliers from subsidy-eligible terminal projects, creating structural supply segmentation. Manufacturing concentrates in Germany, Japan, and South Korea, with Daegu-Gyeongbuk industrial complexes feeding specialized nickel-alloy pressure vessel components. Raw material dependencies center on 9% nickel steel, helium refrigeration cycles, and ortho-para conversion catalysts. Single-source vulnerability runs through concentrated helium supply from Qatar, Russia, and Algeria. Distribution runs through unbundled equipment supply and commissioning service agreements pioneered by South Korean port authorities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in hydrogen liquefaction rests on modular standardization reducing commissioning timelines from 36 months to 18 months, while METI certification premiums sustain pricing power at the top tier.
For Market Incumbents: Deploy backward integration into nickel-alloy pressure vessel fabrication to hedge cryogenic steel input volatility. Incumbents must secure cryogenic welder certification pipelines ahead of competitor capacity builds, while reinforcing technology leadership through proprietary Claude-Brayton cycle optimization against pulse tube substitution threats. For New Entrants and Emerging Players: Pulse tube solid-state refrigeration offers a technology-first wedge into research facility and remote demonstration project markets where maintenance access constraints override efficiency penalties. New entrants should target Australia's western coastline green hydrogen ports, penetrating through simplified cycle architectures that reduce nickel-alloy steel requirements and accelerate deployment timelines. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized heat exchanger fabricators possessing modular brazed aluminum platforms enabling supplier-agnostic system integration. Long-term viability favors acquisition targets with captive cryogenic engineering expertise and established METI documentation capabilities. Watch for inflection in Japan's hydrogen supply chain certification rule expansions to Southeast Asian import terminals.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Unit Standardization | Compresses commissioning timelines to 18 months for redeployable export terminal assets. |
| METI Certification Investment | Unlocks Japanese subsidy-eligible procurement and lifecycle carbon accounting premiums. |
| Helium Supply Diversification | Mitigates geopolitical interruption risks from concentrated Qatar-Russia-Algeria sourcing. |
| Cryogenic Welder Pipeline Development | Addresses scarcity constraining 9% nickel steel fabrication capacity expansion. |
| Pulse Tube Technology Licensing | Penetrates maintenance-constrained research and remote demonstration markets. |
Research Methodology
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core, combining primary interviews with EPC contractors, port authority procurement officers, cryogenic engineering specialists, and industrial gas project developers with secondary validation from EIA hydrogen hub disclosures, IEA clean hydrogen tracking reports, METI certification documentation, and EU F-Gas Regulation implementation schedules. Triangulation across stakeholder inputs and regulatory filings ensures segment-level accuracy.
Historical trendline analysis of liquefaction train deployment timelines, capacity utilization patterns, and certification cost structures informs projection modeling across the analysis window. Segmentation dimensions include plant scale tier, refrigeration cycle technology, application end-use, and regional regulatory framework. CAGRs derive from equipment procurement pipeline tracking, electrolysis capacity buildout correlations, and maritime hydrogen supply chain milestone achievements.
The model holds under sustained EU F-Gas refrigerant phase-down schedules and Japan METI certification continuity; deviation in helium supply disruption severity or cryogenic steel price volatility spikes would shift equipment cost assumptions. Forecasts reflect documented procurement patterns and regulatory implementation timelines. A model refresh is warranted upon material change in Japan-South Korea hydrogen supply chain certification reciprocity agreements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydrogen Energy
Green Hydrogen Market
Hydrogen Energy
Green Hydrogen Dispensing Equipment Market
Hydrogen Energy
Hydrogen Purification Technologies Market
Hydrogen Energy
Asia-Pacific Clean Hydrogen Market
Hydrogen Energy
Hydrogen Generator Market
Hydrogen Energy
Electrolyzer Market
Hydrogen Energy
Hydrogen Gas Generator Market
Hydrogen Energy
Hydrogen Powered Engine Market
Hydrogen Energy
Hydrogen Purification Market
Hydrogen Energy
Hydrogen for Mobility Market
Hydrogen Energy
United States Hydrogen Generation Market
Hydrogen Energy
Photovoltaic Hydrogen Production Market
Hydrogen Energy
Hydrogen Composite Tanks Market
Hydrogen Energy
Merchant Hydrogen Market
Hydrogen Energy
India Hydrogen Market
Hydrogen Energy
Europe Hydrogen Generation Market