
 Lined Valves Market | 2026-2036
Lined Valves Market Size, Share, and Industry Trends Forecast 2026-2036
Lined Valves Market Insights
ASME Class 600 and higher pressure-temperature rating upgrades is redrawing procurement priorities across process industries. Flowserve Corporation leverages captive fluoropolymer lining capacity to anchor premium positioning in acid transport applications. Crane Co. competes through specialized diaphragm valve designs for slurry transfer, while KITZ Corporation dominates Asian water treatment infrastructure with standardized ball valve platforms.
Lined valves incorporate corrosion-resistant internal barriers—typically PTFE, PFA, or ceramic coatings bonded to cast steel or ductile iron bodies—enabling reliable isolation and throttling of aggressive chemicals, acids, and abrasive slurries in continuous process environments. Fluoropolymer lining materials command the widest specification range due to chemical inertness across pH extremes and thermal cycling. Ball valves lead product type demand in chemical processing for quarter-turn shutoff reliability, while diaphragm valves sustain higher margin pools in pharmaceutical and fine chemical applications requiring zero stem leakage.
EPA mandates under the Clean Air Act and Resource Conservation and Recovery Act enforce fugitive emission limits that elevate lined valve specifications in US refineries and chemical plants. REACH registration requirements and the EU F-Gas Regulation restrict certain lining chemistries, redirecting European procurement toward certified PTFE and advanced ceramic alternatives. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions across multiple jurisdictions, as material phase-outs could force redesign cycles faster than typical plant turnaround schedules allow.
Market Dynamics
Fluoropolymer lining capacity concentration among integrated manufacturers is redrawing procurement economics, forcing process industries to lock in multi-year supply agreements or absorb pass-through resin costs.
Growth Catalysts
- EPA corrosion mandates:Fugitive emission rules under the Clean Air Act compel US refineries to specify PTFE-lined ball valves for acid transfer lines.
- Hydrogen economy buildout:Electrolyzer projects in Germany's industrial corridor are specifying PFA-lined isolation valves for high-purity alkaline circuits.
- Semiconductor fab expansion:Ultra-high purity fluoropolymer diaphragm valves are capturing specification share in wet chemical processing tools.
Market Restraints
- Resin supply concentration:PTFE and PFA polymer production clusters in China and Japan expose buyers to freight volatility and tariff exposure.
- REACH chemical restrictions:ECHA scrutiny of per- and polyfluoroalkyl substances forces premature redesign cycles before standard plant turnarounds.
- Ceramic lining cost barrier:Alumina and silicon carbide coatings command 3-4x fluoropolymer pricing, limiting adoption outside extreme temperature applications.
Strategic Opportunities
- India chemical corridor:Dahej and Mundra petrochemical complexes are greenfield opportunities for fluoropolymer-lined valve specifications.
- Carbon capture infrastructure:Amine-based CO2 absorption systems require corrosion-resistant throttling valves in post-combustion capture trains.
- Digital twin integration:Valve condition monitoring via IIoT sensors is creating attach-rate opportunities for smart-lined valve packages.
Industry Challenges
- Fluoropolymer welding certification:Qualified technicians for PFA liner fusion are scarce, extending field service lead times.
- Legacy system interoperability:Retrofitting lined valves into existing DCS architectures requires custom actuator mapping and extended commissioning windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lined Valves Market |
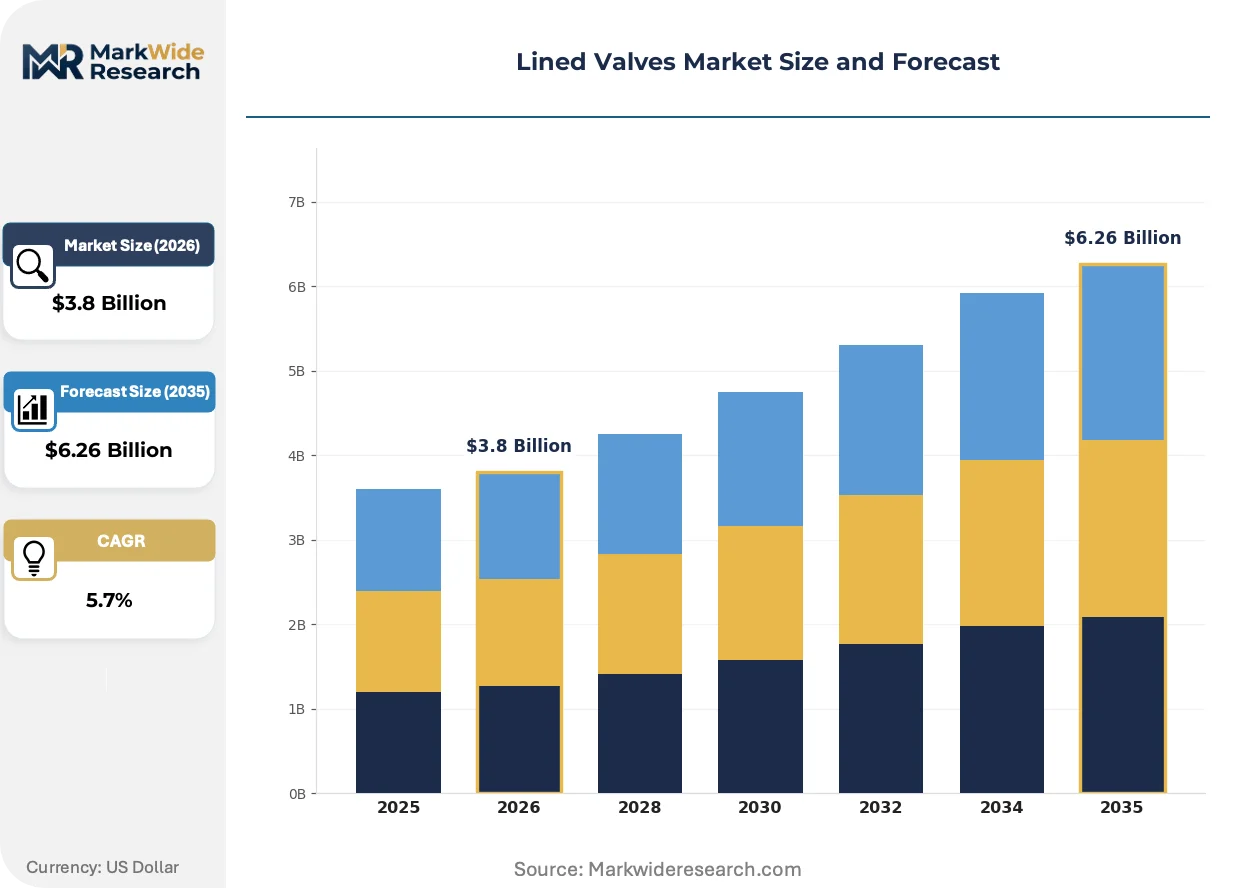
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ball Valves, Butterfly Valves, Globe Valves, Diaphragm Valves, Check Valves Lining Material: PTFE, Rubber, Polyethylene, Ceramic, Fluoropolymer End User Industry: Chemical Processing, Pulp & Paper, Water Treatment, Power Generation, Mining Application: Corrosive Fluid Handling, Slurry Transfer, Acid Transport, High Temperature Processes, Abrasive Media Control |
| Companies Covered | Emerson Electric Co., Flowserve Corporation, Crane Co., KITZ Corporation, Neles, ITT Inc, ARI Armaturen, Samson Controls Inc, ChemValve-Schmid AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lined Valves Market Trends and Innovations
Material science advances and regulatory chemistry restrictions are forcing simultaneous evolution in lining formulations and valve architectures across process industries.
Advanced ceramic spray deposition is decomposing the traditional fluoropolymer monopoly in high-temperature acid service. Hydrometallurgy operators in copper and nickel refining are piloting alumina-titania coatings for autoclave discharge lines. This ceramic shift is compressing specification windows where PTFE thermal limits previously dictated valve selection.
EU F-Gas Regulation phase-down schedules are accelerating refrigerant chemistry changes that cascade into valve material specifications. Cold chain infrastructure projects must now certify compatibility with HFO and natural refrigerant alternatives. Food processing and pharmaceutical cold storage builds in the Netherlands and Denmark are driving demand for revised elastomer and lining compound approvals.
Asset-as-a-service contracting is penetrating the valve procurement landscape. Chemical processors in the US Gulf Coast are unbundling valve supply from installation and predictive maintenance obligations. This service model compression transfers lifecycle risk to OEMs while compressing upfront capital outlays for plant operators.
Lined Valves Market Segmentation
Lined valve procurement splits across four dimensions that rarely align. Engineers optimizing for fluoropolymer chemical resistance may sacrifice the quick shutoff geometry of ball valves, while procurement teams chasing ceramic durability absorb 3-4x unit cost premiums that reshape project economics.
Product Type:
EPA corrosion mandates and REACH chemical restrictions are fragmenting specification authority between process engineers and compliance officers.
- Ball Valves:Quarter-turn shutoff geometry with fluoropolymer-lined ball and seat assemblies dominates acid transport lines in US Gulf Coast refineries. ASME Class 600 rating upgrades are concentrating procurement around forged steel bodies with PFA liner fusion certification.
- Diaphragm Valves:Zero stem leakage architecture sustains premium positioning in pharmaceutical sterile processing and fine chemical synthesis where EMA GMP guidelines enforce containment integrity. Weir-type bodies with PTFE diaphragms capture specification share in European biologics manufacturing.
- Butterfly Valves:Compact face-to-face dimensions suit slurry handling in mining tailings and pulp mill liquor lines.
- Globe Valves:Throttling precision serves amine-based carbon capture absorption trains requiring precise flow modulation.
- Check Valves:Swing and lift configurations protect pumps in abrasive media recirculation systems.
Ball valves handle the majority of throughput; diaphragm valves are the fastest mover on share.
Lining Material:
Cost tiers separate specification windows by temperature envelope and chemical aggression level.
- Fluoropolymer:PFA and PTFE formulations command the widest pH range from strong oxidizers to caustic media, with thermal cycling tolerance to 260°C enabling specification across continuous process environments from Germany's industrial corridor to Dahej petrochemical complexes.
- Ceramic:Alumina-titania and silicon carbide coatings penetrate autoclave discharge lines in copper hydrometallurgy where fluoropolymer thermal limits fail, though 3-4x pricing restricts adoption to extreme temperature acid service.
- Rubber:EPDM and nitrile linings serve water treatment and mild chemical duty at economy tier positioning.
- Polyethylene:HDPE barriers protect against abrasive slurries in mining and aggregate processing.
- PTFE:Virgin and filled PTFE formulations anchor chemical processing specifications with proven fusion welding protocols.
Fluoropolymer captures the highest specification volume; ceramic coatings are expanding most quickly in high-temperature niches.
End User Industry:
Application severity and regulatory exposure concentrate margin in specific verticals.
- Chemical Processing:Chlor-alkali, sulfuric acid, and specialty chemical producers specify fluoropolymer-lined systems for fugitive emission compliance under EPA Clean Air Act and REACH registration requirements, with procurement concentrated around Leverkusen, Ludwigshafen, and US Gulf Coast clusters.
- Water Treatment:Municipal and industrial desalination infrastructure in Asia-Pacific drives standardized ball valve platforms with rubber or polyethylene linings for cost-sensitive large-volume deployment.
- Pulp & Paper:Digester liquor and bleach plant chemical handling requires corrosion-resistant throttling in high-chloride environments.
- Power Generation:FGD scrubber systems and cooling water chemistry control specify lined isolation valves for coal and combined-cycle plants.
- Mining:Hydrometallurgical leaching and tailings management expose valves to abrasive slurry and acidic process liquors.
Chemical processing commands the dominant specification authority; water treatment is climbing the fastest on infrastructure buildout.
Application:
Fluid characteristics dictate liner material selection and valve geometry tradeoffs.
- Corrosive Fluid Handling:Strong acids, caustics, and oxidizing media in continuous chemical process streams require fluoropolymer-lined ball or diaphragm valves with fusion-welded liner integrity verified to ASME and ISO pressure-temperature ratings.
- Slurry Transfer:Mining tailings, pulp mill liquor, and chemical precipitates demand full-port ball valves or resilient-seated butterfly valves with abrasion-resistant polyethylene or rubber linings.
- Acid Transport:Sulfuric, hydrochloric, and nitric acid pipeline systems specify PFA-lined ball valves for quarter-turn reliability in refinery and chemical plant acid service.
- High Temperature Processes:Autoclave discharge and thermal oxidizer service exceeding 260°C forces ceramic-lined globe or plug valve architectures.
- Abrasive Media Control:Sand, catalyst fines, and mineral slurries accelerate wear on standard linings, directing specification toward hardened ceramic coatings or thick-section rubber formulations.
Corrosive fluid handling anchors the specification base; high temperature processes are gaining share fastest on ceramic material advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PTFE and PFA resin production clusters in China and Japan expose valve manufacturers to freight volatility and tariff exposure, forcing process industries to diversify sourcing across multiple geographies. Germany's industrial corridor around Leverkusen and Ludwigshafen anchors European specification authority for fluoropolymer-lined systems.
United States
EPA fugitive emission rules under the Clean Air Act compel Gulf Coast refineries to specify PTFE-lined ball valves for acid transfer lines. The Resource Conservation and Recovery Act enforces corrosion-resistant equipment mandates in chemical processing facilities. Houston and Beaumont petrochemical clusters are absorbing premium-grade valve specifications as ASME Class 600 rating upgrades concentrate procurement.
Germany
Electrolyzer projects in the industrial corridor are specifying PFA-lined isolation valves for high-purity alkaline circuits in hydrogen economy buildout. EU F-Gas Regulation phase-down schedules redirect procurement toward certified PTFE alternatives. Leverkusen and Ludwigshafen chemical complexes are tightening material specifications under REACH chemical safety rules.
China
Domestic fluoropolymer polymer production serves chlor-alkali and sulfuric acid producers with captive resin supply advantages. The country's national environmental regulator enforces fugitive emission standards that elevate lined valve specifications in coastal refineries. Shanghai and Ningbo petrochemical zones are integrating local lining capacity with valve fabrication.
India
Dahej and Mundra petrochemical complexes present greenfield opportunities for fluoropolymer-lined valve specifications in expanding chemical processing infrastructure. The Bureau of Indian Standards certifies pressure-temperature ratings for process equipment imports. Gujarat's industrial corridor is attracting valve OEMs establishing local assembly operations.
Japan
Ultra-high purity fluoropolymer diaphragm valve demand from semiconductor fab expansion drives specification share in wet chemical processing tools. METI industrial policy supports domestic materials science leadership in advanced lining formulations. Kyushu and Hiroshima electronics manufacturing clusters are qualifying next-generation PFA liner fusion protocols.
Lined Valves Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated manufacturers commanding premium positioning through captive fluoropolymer lining capacity while standardized fabricators compete on volume in water treatment infrastructure. The vendor base splits between multinational valve specialists with in-house resin processing and regional fabricators sourcing third-party liners. Two dominant archetypes emerge: integrated technology leaders with backward control over fluoropolymer supply, and scale-driven specialists in standardized ball valve platforms. Competitive moves concentrate on multi-year supply agreement lock-ins and IIoT-enabled smart valve package development.
Among the named participants, Flowserve Corporation exemplifies the integrated archetype with captive fluoropolymer lining capacity anchoring premium positioning in acid transport applications. Crane Co. occupies a position within specialized diaphragm valve design for slurry transfer segments. KITZ Corporation represents the scale-driven standardized platform approach dominating Asian water treatment infrastructure procurement.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Flowserve Corporation |
| Crane Co. |
| KITZ Corporation |
| Neles |
| ITT Inc |
| ARI Armaturen |
| Samson Controls Inc |
| ChemValve-Schmid AG |
| Others |
Pricing and Supply Chain Analysis
Multi-year supply agreements lock in fluoropolymer resin access for chemical processors while anchoring price visibility against freight volatility and tariff exposure. These contracts concentrate procurement leverage among integrated manufacturers with captive lining capacity, forcing process industries to absorb pass-through costs or accept extended lead times from third-party fabricators.
Pricing Analysis
EPA corrosion mandates dictate the pricing tier structure across the lined valve market. Three-tier pricing structure across premium, standard, and economy levels separates ASME Class 600 certified PFA-lined systems from uncertified PTFE alternatives and rubber-lined economy valves. Price differentiation hinges on fusion-welding certification and REACH registration compliance. Cost compression in standard-tier fluoropolymer valves is intensifying because resin supply concentration in China and Japan exposes buyers to freight volatility. Municipal water treatment infrastructure represents the most price-sensitive segment, while semiconductor fabs demonstrate least sensitivity due to ultra-high purity requirements.
Supply Chain Analysis
PTFE and PFA polymer production clusters in China and Japan constitute the critical chokepoint anchoring global lined valve economics. Raw material dependencies center on fluoropolymer resin, cast steel forgings, and ceramic coating precursors. Supply chain risk manifests as tariff exposure on Chinese resin imports disrupting procurement economics for European and North American fabricators. Distribution runs through direct OEM channels for premium chemical processing specifications and distributor networks for standardized water treatment platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
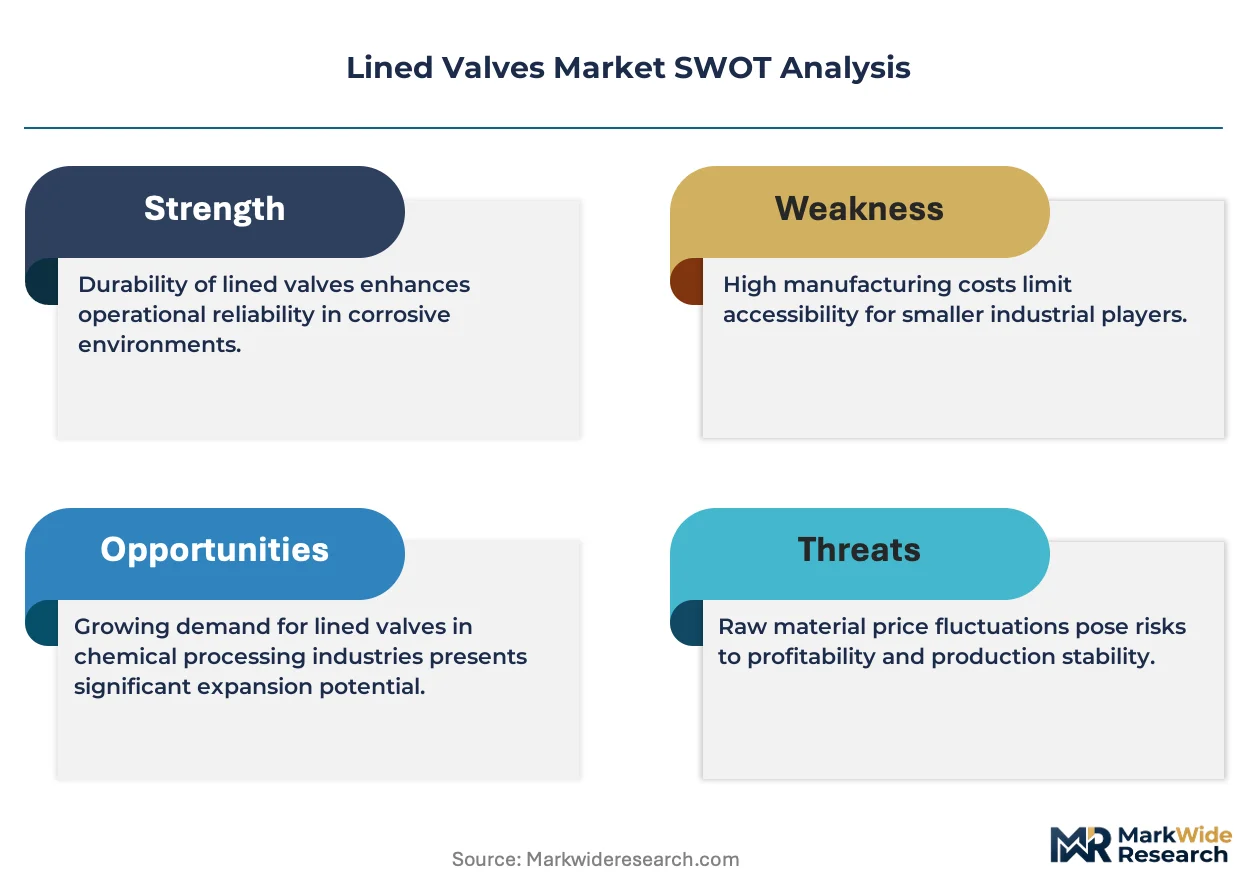
Regulatory fragmentation across EPA, REACH, and emerging PFAS restrictions creates niche specification windows that reward specialized positioning over scale dominance. Demand-side shifts toward hydrogen economy infrastructure and carbon capture systems fragment procurement authority between process engineers and compliance officers.
For Market Incumbents: Shield premium positioning by deepening backward integration into fluoropolymer resin processing and securing multi-year offtake agreements with chlor-alkali producers. Ceramic coating certification investments defend against high-temperature specification erosion. Capacity addition in Germany's industrial corridor anchors European hydrogen economy capture.
For New Entrants and Emerging Players: Predictive maintenance service bundling represents the service-layer gap where integrated OEMs under-serve cost-conscious municipal water treatment operators. India's Dahej and Mundra petrochemical complexes offer the most penetrable geography for greenfield specification wins. Digital twin integration capabilities provide the go-to-market angle for smart-lined valve packages in carbon capture infrastructure.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap specialists with qualified PFA liner fusion technicians and established REACH registration portfolios. Long-term viability rests on material science adaptability as PFAS phase-outs accelerate redesign cycles. Watch ECHA per- and polyfluoroalkyl substance restriction timelines as the inflection signal for ceramic coating demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluoropolymer Resin | Captive PTFE and PFA supply secures margin control against Chinese resin volatility. |
| Long-term Supply Agreement Lock-ins | Multi-year contracts with Leverkusen and Ludwigshafen chemical complexes anchor revenue visibility. |
| Digital Twin Integration Development | IIoT sensor packages for valve condition monitoring capture attach-rate premiums in carbon capture. |
| Ceramic Coating Certification Investment | Alumina-titania spray deposition protocols penetrate autoclave discharge specifications above 260°C. |
| Regional Assembly Operations in India | Gujarat industrial corridor presence captures Dahej and Mundra greenfield petrochemical specifications. |
Research Methodology
The analysis maps fluoropolymer-lined, ceramic-lined, and rubber-lined valve sub-sectors, each validated through procurement directors at chemical processing facilities, maintenance engineers at water treatment plants, and technical R&D leads at valve OEMs. Primary interviews with plant managers at US Gulf Coast refineries and distribution channel partners in European industrial corridors combined with secondary validation from customs trade data, SEC 10-K filings, and chemical industry association reports. Bottom-up unit shipment estimates and top-down value triangulation cross-verified segment outputs.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled product type, lining material grade, end-use industry vertical, and regional production hub dimensions. CAGRs derived from regression analysis of historical specification trends and forward-projected infrastructure buildout pipelines. Hydrogen economy electrolyzer deployment schedules and semiconductor fab expansion timelines served as industry-specific forecast inputs.
Material uncertainties — ECHA PFAS restriction acceleration, ceramic coating cost breakthroughs, and India import tariff shifts — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory stability and resin supply continuity. Practitioners should keep alternative scenarios live as REACH chemical safety rule evolution and EPA fugitive emission enforcement intensity develop.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Pneumatic Slide Gates Market
Valves
Orifice Reducers Market
Valves
Global Pipeline Safety Market
Valves
Pipeline Integrity Management (PIM) Market
Valves
Flanges Market
Valves
Fin Tube Market
Valves
Ball Valves Market
Valves
Oil Drain Valves Market
Valves
Transmission Overload Protectors Market
Valves
Pneumatic Needle Valves Market
Valves
Motorized Valves Market
Valves
Directional Control Valves Market
Valves
Pipeline Pigging Valves Market
Valves
Global Plug Valve Market
Valves
Europe Vacuum Insulated Pipe Market
Valves
Industrial Valves Market