
 Global Plastic Valves Market | 2026-2036
Global Plastic Valves Market Size, Share, and Industry Trends Forecast 2026-2036
Global Plastic Valves Market Foresight
The EU F-Gas Regulation is repositioning demand toward fluoropolymer alternatives in HVAC and refrigeration infrastructure. Georg Fischer Ltd. leverages its Swiss manufacturing base to supply high-purity piping systems for semiconductor fabs. Hayward Industries, Inc. dominates North American pool and aquaculture valve segments through captive distribution networks. Plast-O-Matic Valves, Inc. specializes in corrosion-resistant thermoplastic designs for aggressive chemical environments.
Plastic valves are flow-control devices molded from thermoplastic polymers such as PVC, CPVC, PP, and PTFE, typically rated for pressures up to 150 psi and temperatures ranging from sub-zero to 200°F depending on material grade, serving industries where metallic corrosion or electrolytic degradation would compromise system integrity. Ball valves lead product type demand due to their quarter-turn simplicity and sealing reliability in water treatment systems, while diaphragm valves capture premium margins in pharmaceutical and chemical processing applications where zero dead-leg design prevents contamination. Polyvinyl chloride anchors material volume through cost efficiency in municipal water infrastructure, though polytetrafluoroethylene commands price premiums in semiconductor and aggressive chemical service.
The EPA Safe Drinking Water Act and NSF/ANSI 61 certification requirements in the United States, alongside REACH chemical compliance and CE marking under the EU Pressure Equipment Directive, collectively elevate barrier-to-entry standards for market participants. India's BIS quality mandates and China's GB standards for plastic piping components further fragment regulatory compliance obligations across manufacturing footprints. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions in Europe and North America, as these threaten incumbent PTFE valve architectures while creating openings for advanced polypropylene and PVDF formulations.
Market Dynamics
Corrosion-driven material substitution is restructuring procurement patterns across water infrastructure, chemical processing, and semiconductor fabrication end-uses, as asset owners prioritize lifecycle cost over initial capital outlay.
Growth Catalysts
- EU Drinking Water Directive compliance:German municipal utilities are expanding thermoplastic valve procurement to meet revised lead-free mandates, displacing legacy bronze installations.
- India's Jal Jeevan Mission:Rural water supply buildout is concentrating polypropylene diaphragm valve demand in state-level procurement tenders.
- Fluoropolymer thermal stability:PTFE-lined valve architectures are capturing HVAC retrofit work as the EU F-Gas Regulation phases down high-GWP refrigerants.
Market Restraints
- Specialty resin supply concentration:Virgin PVDF pellet production clusters in Western European and Japanese chemical complexes, exposing buyers to freight-driven cost volatility.
- Pressure-temperature envelope limitations:Thermoplastic valves face technical exclusion from high-pressure steam applications above 150 psi, ceding share to metal-seated alternatives.
- Per- and polyfluoroalkyl substance restrictions:ECHA proposals to limit PTFE precursor chemicals are creating regulatory friction for incumbent fluoropolymer valve architectures.
Strategic Opportunities
- Semiconductor fabrication expansion:Taiwan, South Korea, and Arizona fab buildouts are generating demand for ultra-high-purity PFA valve systems in wet chemical distribution.
- Desalination membrane integration:Reverse osmosis train OEMs are specifying thermoplastic valve skids to reduce seawater corrosion in Saudi and Australian coastal projects.
- Digital twin convergence:IoT-enabled valve positioners combined with predictive maintenance platforms are opening premium service revenue streams for system integrators.
Industry Challenges
- Welding technician scarcity:Socket fusion and butt fusion certification programs for thermoplastic piping systems face enrollment gaps in North American and European labor markets.
- NSF/ANSI 61 certification timelines:Third-party testing protocols for potable water contact materials extend product launch cycles by 12-18 months.
- Legacy DCS integration complexity:Retrofitting smart positioners onto installed plastic valve bases requires protocol bridging for Modbus and Foundation Fieldbus networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Plastic Valves Market |
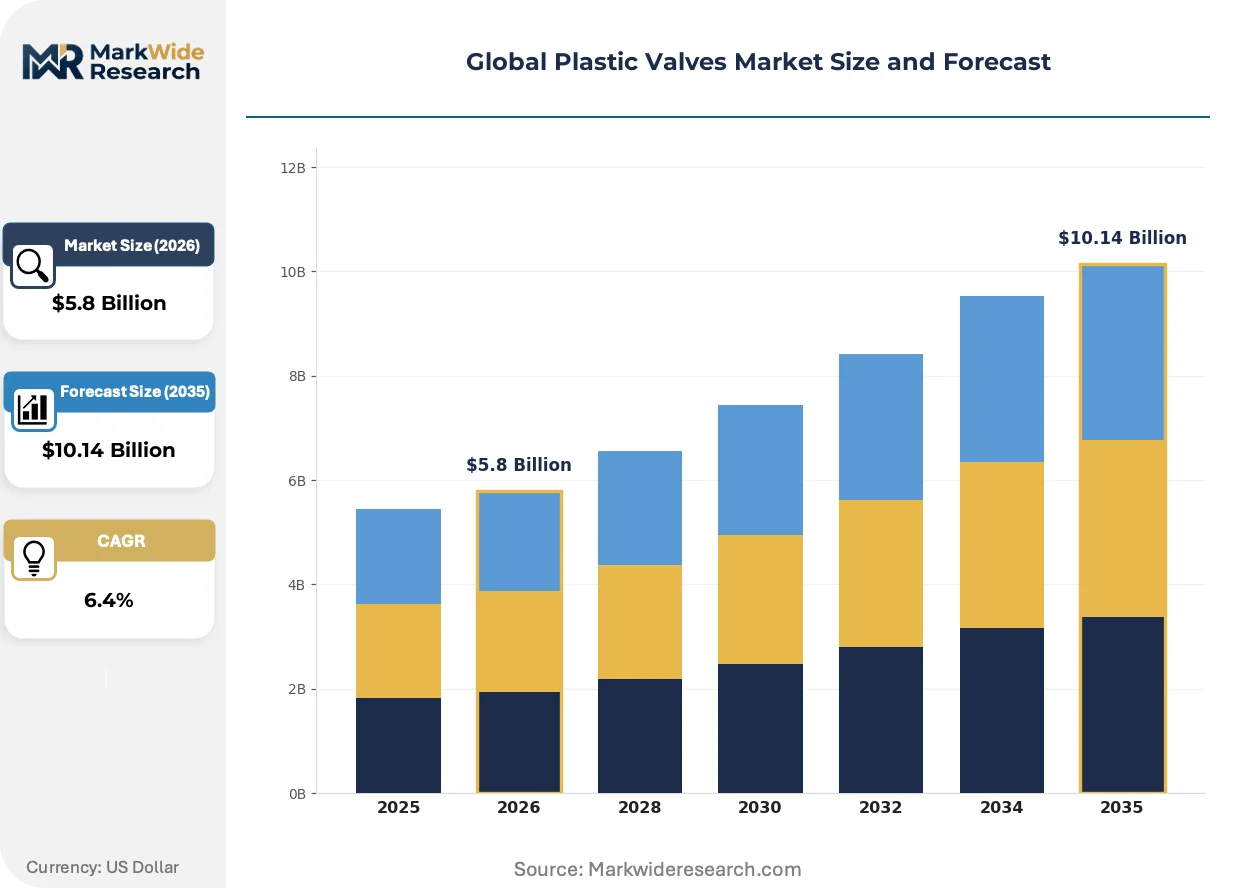
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ball Valves, Butterfly Valves, Globe Valves, Check Valves, Diaphragm Valves Material: Polyvinyl Chloride, Polypropylene, Polytetrafluoroethylene, Chlorinated Polyvinyl Chloride, Acrylonitrile Butadiene Styrene Application: Water Treatment Systems, Chemical Processing, Food & Beverage, Marine Equipment, Agriculture Irrigation End User: Municipal Facilities, Process Plants, Food Manufacturers, Shipbuilders, Farms |
| Companies Covered | Plast-O-Matic Valves, Inc., Hayward Industries, Inc., Georg Fischer Ltd., Simtech Process Systems, Valtorc International, Asahi/America, Inc., NIBCO INC., Flowserve Corporation, Spears Manufacturing Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Plastic Valves Market Shifts & Advancements
Material science advances and regulatory chemistry restrictions are converging to reshape valve specification criteria, with end-users prioritizing traceability and circularity credentials alongside mechanical performance.
Advanced polypropylene compounds with glass-fiber reinforcement are unifying pressure ratings and chemical resistance in a single material platform. Chemical processors in the US Gulf Coast and Rotterdam Antwerp port complexes are specifying these grades for sulfuric acid and caustic soda service. The technology is unifying what previously required separate PVC and PVDF inventory positions, compressing supplier SKUs and simplifying maintenance procurement.
The EU F-Gas Regulation's phasedown schedule for hydrofluorocarbon refrigerants is redirecting HVAC specification toward PTFE and PFA valve architectures compatible with low-GWP alternatives like R-1234yf and R-513A. Equipment OEMs in Germany and Italy are redesigning expansion valve blocks to accommodate these chemistries. The semiconductor sub-fab segment faces the most acute compliance pressure, driving qualification of fluoropolymer alternatives ahead of the 2030 phase-down milestones.
Asset owners are consolidating valve procurement through framework agreements with tier-one distributors, displacing spot purchasing through local mechanical contractors. Water treatment utilities in California, Texas, and Florida are centralizing specification authority at the corporate engineering level. The shift is most visible in municipal infrastructure verticals where lifecycle cost modeling now dominates capital committee decisions.
Global Plastic Valves Market Segmentation
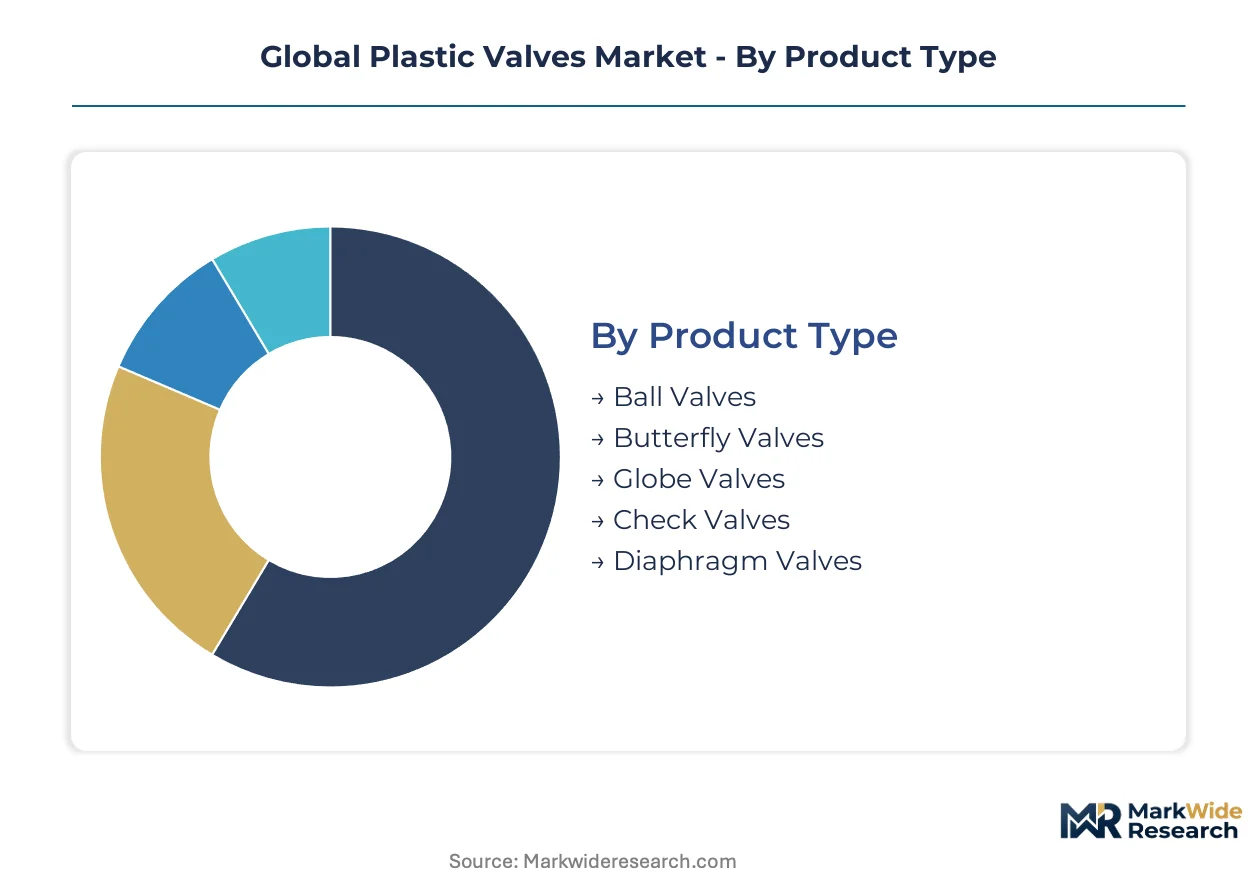
Plastic valve procurement patterns diverge sharply across product architectures, resin chemistries, and end-use environments. Specification criteria in semiconductor fabs bear little resemblance to municipal water infrastructure decisions. Understanding these fault lines reveals where margin concentrates and where volume scales.
Product Type:
Capital deployment for manufacturing capacity varies dramatically by valve architecture, with precision-machined fluoropolymer designs demanding the highest upfront tooling investment.
- Ball Valves:Quarter-turn sealing mechanisms molded from PVC and CPVC dominate volume production for water distribution networks. German utilities under EU Drinking Water Directive mandates are displacing legacy bronze installations with thermoplastic ball valve assemblies rated for 150 psi service.
- Diaphragm Valves:Zero dead-leg designs in PTFE and PFA configurations command premium positioning in pharmaceutical bioreactors and semiconductor wet chemical distribution. India's Jal Jeevan Mission is concentrating polypropylene diaphragm valve demand in state-level rural water supply tenders.
- Butterfly Valves:Wafer-style thermoplastic configurations serve large-bore flow control in desalination pre-treatment trains.
- Globe Valves:Throttling applications in chemical processing favor glass-reinforced polypropylene for sulfuric acid service.
- Check Valves:Swing and spring-loaded thermoplastic designs prevent backflow in irrigation lift stations.
Most installed capacity flows through Ball Valves. Expansion is steepest in Diaphragm Valves.
Material:
Resin selection maps directly to chemical resistance requirements and temperature envelopes, with fluoropolymer grades requiring specialized extrusion equipment that limits supplier pools.
- Polyvinyl Chloride:Cost-optimized formulations anchor municipal water infrastructure volume through NSF/ANSI 61 certified compounds. California and Texas utilities specify PVC valves for distribution network retrofits where lead-free compliance drives material substitution.
- Polytetrafluoroethylene:Virgin and filled PTFE grades deliver chemical inertness in semiconductor sub-fab chemical delivery systems. ECHA proposals restricting PTFE precursor chemicals are forcing qualification of alternative fluoropolymer architectures ahead of regulatory deadlines.
- Polypropylene:Homopolymer and copolymer grades balance chemical resistance with weldability in pharmaceutical process piping.
- Chlorinated Polyvinyl Chloride:Elevated temperature ratings to 200°F expand hot water and industrial heat transfer applications.
- Acrylonitrile Butadiene Styrene:Lower-cost engineering resin serves light-duty pneumatic and vacuum systems.
PVC commands the broadest installed base. PTFE is climbing the fastest on semiconductor fabrication expansion.
Application:
End-use environments dictate specification rigor, with ultra-high-purity requirements in electronics manufacturing creating the steepest qualification barriers.
- Water Treatment Systems:Corrosion-resistant thermoplastic valves in reverse osmosis and ultraviolet disinfection skids reduce lifecycle cost versus metallic alternatives. Saudi and Australian coastal desalination projects are specifying thermoplastic valve trains for seawater service.
- Chemical Processing:Aggressive acid and caustic service demands glass-reinforced polypropylene and PVDF architectures. Rotterdam and Houston petrochemical clusters specify these grades for sulfuric acid and sodium hydroxide handling.
- Food & Beverage:FDA-compliant materials and sanitary surface finishes serve dairy and brewing process equipment.
- Marine Equipment:Seawater corrosion resistance drives thermoplastic specification in ballast and cooling systems.
- Agriculture Irrigation:Cost-driven PVC and ABS valve deployment in drip and pivot irrigation networks.
Water Treatment Systems absorb the greatest valve volume. Chemical Processing is gaining share fastest on material substitution trends.
End User:
Procurement authority centralization varies by customer type, with municipal utilities consolidating engineering specification at corporate levels while process plants retain site-level autonomy.
- Municipal Facilities:Drinking water and wastewater treatment plants specify NSF/ANSI 61 certified thermoplastic valves through framework agreements with tier-one distributors. Florida and California utilities have shifted from spot purchasing through mechanical contractors to centralized corporate procurement.
- Process Plants:Chemical and pharmaceutical manufacturers prioritize lifecycle cost modeling over initial capital outlay in valve selection. German chemical processors under REACH compliance obligations are specifying traceable resin grades with full material certification.
- Food Manufacturers:Sanitary process requirements drive specification of FDA-compliant thermoplastic valve architectures.
- Shipbuilders:Marine classification society approvals govern thermoplastic valve selection for seawater systems.
- Farms:Price-sensitive procurement of PVC and ABS valves for irrigation infrastructure.
Municipal Facilities represent the deepest installed base. Process Plants are expanding procurement most quickly on corrosion-driven substitution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Plastic valve manufacturing first scaled in Germany and Switzerland during the 1950s as thermoplastic polymer chemistry advanced. Early adoption centered on chemical processing corridors where metallic corrosion failures drove material substitution. Today's demand geography reflects that industrial heritage while incorporating new fabrication clusters in Asia and North America.
United States
EPA Safe Drinking Water Act enforcement is accelerating lead-free infrastructure replacement across municipal water systems. California and Texas utilities specify NSF/ANSI 61 certified thermoplastic valves through centralized corporate procurement frameworks. The Houston petrochemical corridor demands glass-reinforced polypropylene valves for sulfuric acid handling in refinery service.
Germany
EU Drinking Water Directive compliance deadlines are displacing legacy bronze installations with corrosion-resistant thermoplastic assemblies. REACH chemical obligations push German processors toward traceable resin grades with full material certification. The BASF-Ludwigshafen chemical cluster anchors fluoropolymer valve specification for aggressive process environments.
India
Jal Jeevan Mission rural water supply buildout concentrates polypropylene diaphragm valve demand in state-level procurement tenders. BIS quality mandates for plastic piping components fragment compliance obligations across manufacturing footprints. Gujarat's chemical processing belt qualifies advanced polypropylene compounds for caustic soda service.
China
GB standards for plastic piping components govern domestic valve specification while dual carbon goals reshape resin sourcing priorities. Semiconductor fabrication expansion in Shanghai and Beijing generates demand for ultra-high-purity fluoropolymer systems. The Yangtze River Delta hosts wet chemical distribution infrastructure requiring PTFE-lined valve architectures.
Japan
METI industrial policy supports advanced materials qualification for semiconductor sub-fab chemical delivery. JIS standards compatibility enables Japanese valve fabricators to supply Taiwan and South Korean fab buildouts. The Osaka-Kobe industrial corridor specializes in precision-machined fluoropolymer designs for pharmaceutical bioreactors.
Global Plastic Valves Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material purity and certification tiers, with fluoropolymer specialists commanding price multiples over PVC commodity fabricators. The vendor base organizes into three strategic archetypes: Swiss and German precision manufacturers serving semiconductor and pharmaceutical verticals, North American full-line distributors capturing municipal infrastructure volume, and Asian-scale producers supplying cost-optimized irrigation and construction segments. Consolidation pressure concentrates among mid-tier regional fabricators lacking either purity certification or distribution scale. Dominant competitive moves include backward integration into virgin resin compounding and geographic expansion through distributor acquisition.
Within the precision-manufacturing tier, Georg Fischer Ltd. exemplifies Swiss-origin engineering focus on high-purity systems, while Hayward Industries, Inc. occupies a position as a North American distributor-integrated operator. Plast-O-Matic Valves, Inc. represents the corrosion-resistant specialization archetype for aggressive chemical environments. These three anchors illustrate how competitive positioning fragments across material grade, geographic served-market, and end-use specification rigor rather than converging on uniform scale economies.
| Leading Market Players |
|---|
| Plast-O-Matic Valves, Inc. |
| Hayward Industries, Inc. |
| Georg Fischer Ltd. |
| Simtech Process Systems |
| Valtorc International |
| Asahi/America, Inc. |
| NIBCO INC. |
| Flowserve Corporation |
| Spears Manufacturing Company |
| Others |
Supply & Pricing Matrix
Backward integration into virgin resin compounding anchors competitive positioning for precision-grade manufacturers, while commodity fabricators remain exposed to pellet price volatility from Western European and Japanese chemical complexes. This structural divide concentrates pricing power among fluoropolymer specialists who control material purity from polymerization through finished valve assembly.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ultra-high-purity fluoropolymer systems from NSF/ANSI 61 certified municipal grades and irrigation-optimized PVC commodity valves. Price differentiation hinges on certification grade and geographic delivery cost, with semiconductor-grade PTFE assemblies commanding multiples over water infrastructure PVC. Pricing pressure stems from freight-driven cost volatility in specialty resin supply, compressing margins for mid-tier fabricators lacking captive compounding. Municipal utilities exhibit highest price sensitivity through centralized procurement frameworks, while semiconductor fabs prioritize traceability over unit cost.
Supply Chain Analysis
Domestic-content mandates under India's BIS quality standards and China's GB standards are reshaping sourcing patterns toward localized compounding and finishing operations. Virgin PVDF pellet production clusters in Germany, Japan, and the United States, drawing from specialized fluorochemical feedstocks and precision extrusion equipment. Supply chain risk centers on single-source vulnerability for semiconductor-grade PFA resins, where qualification timelines lock buyers into incumbent suppliers. Distribution runs through tier-one industrial distributors for municipal infrastructure, while semiconductor and pharmaceutical verticals rely on direct OEM specification and system integrator partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in fluoropolymer value tiers, where semiconductor fabrication buildouts sustain premium pricing power and lifecycle cost modeling displaces capital-committee price sensitivity.
For Market Incumbents: Anchor defensive positioning through captive supply of virgin PTFE and PFA resins, insulating against ECHA regulatory restrictions on precursor chemicals. Invest in NSF/ANSI 61 certification breadth to capture California and Texas utility centralization trends. Deepen backward integration into resin compounding to defend margin position against freight-driven input volatility. For New Entrants and Emerging Players: Mid-sized chemical processors in the US Gulf Coast and Rotterdam Antwerp corridors represent underserved buyer archetypes seeking glass-reinforced polypropylene alternatives to dual PVC-PVDF inventory positions. Target desalination membrane integration projects in Saudi Arabia and Australia where thermoplastic valve skid specification is accelerating. Pursue qualification partnerships with reverse osmosis train OEMs to bypass entrenched distributor relationships. For Investors and Strategic Acquirers: Roll-up economics work for precision-machined fluoropolymer specialists because semiconductor and pharmaceutical qualification barriers prevent rapid new entrant scaling. Target mid-tier regional fabricators lacking either purity certification or distribution scale, with integration value hinging on certification transferability. Watch ECHA regulatory timelines as inflection indicators for PTFE alternative demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive supply of virgin PVDF insulates German and Japanese manufacturers from freight-driven pellet volatility. |
| NSF/ANSI 61 Certification Expansion | Accelerated approval timelines capture California and Texas municipal utility centralization mandates. |
| Semiconductor Fab Qualification Partnerships | Direct OEM relationships with Taiwan and Arizona buildouts bypass tier-one distributor control. |
| Desalination System Integration | Reverse osmosis train specification in Saudi coastal projects anchors seawater corrosion-resistant demand. |
| IoT-Enabled Valve Positioner Development | Predictive maintenance platforms open premium service revenue streams for system integrators. |
Research Methodology
Direct dialogue with plant engineers, municipal procurement directors, semiconductor sub-fab managers, chemical processing maintenance heads, and tier-one distributor technical sales teams grounded qualitative assessment of specification criteria and procurement authority shifts. Secondary validation drew from EPA Safe Drinking Water Act enforcement records, ECHA regulatory proposal documents, SEC 10-K filings of listed valve manufacturers, BIS quality mandate circulars, and customs trade data for thermoplastic resin imports. Bottom-up demand modeling across end-use installations triangulated against top-down resin consumption estimates from chemical industry associations.
Segmented outputs across product architecture, material grade, application environment, and end-user procurement type structured the analytical framework throughout the forecast period. CAGRs derived from installation base expansion rates, replacement cycle assumptions, and material substitution elasticity in corrosion-sensitive applications. Semiconductor fabrication capital expenditure pipelines, Jal Jeevan Mission tender volumes, and EU F-Gas Regulation compliance timelines informed sector-specific trajectory inputs.
Underlying measurement precision varies by segment; semiconductor and pharmaceutical qualification data carry tighter precision than municipal infrastructure spot purchasing estimates. Forecasts reflect documented assumptions regarding regulatory enforcement timing, resin supply concentration stability, and welding technician certification program expansion. Raw material price volatility, ECHA restriction implementation scope, and central bank rate impacts on municipal capital budgets represent specific revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Global Stainless Steel Control Valves Market
Valves
Global Globe Valve Market
Valves
Global Marine Actuators and Valves Market
Valves
Choke Valves Market
Valves
Construction Valve Seat Insert Market
Valves
India Industrial Valves Market
Valves
Harmonic Dampers Market
Valves
Gate Impellers Market
Valves
Blow - Off Valves Market
Valves
Transmission Overload Protectors Market
Valves
Electrohydraulic Servo Valves (Ehsvs) Market
Valves
North America Residential Ball Valves Market
Valves
Europe Industrial Valves Market
Valves
One-Way Valve Market
Valves
Off-Highway Hydraulic Valve Actuator Systems Market
Valves
Valve Sack Market