
 LNG Satellite Station Market | 2026-2036
LNG Satellite Station Market Size, Share, and Industry Trends Forecast 2026-2036
LNG Satellite Station Market Insights
Composite membrane materials is broadening design flexibility for small-scale containment systems, reducing unit weight and foundation costs versus traditional concrete and steel configurations. Chart Industries leverages vertical manufacturing scale across cryogenic equipment lines to sustain cost leadership in modular tank fabrication. Linde Plc anchors its position through captive production of insulation substrates and cold-box assemblies. Mitsubishi Kakoki Kaisha specializes in high-pressure vaporization skids that differentiate its integrated station packages for Asian industrial clients.
An LNG satellite station is a decentralized, small-scale facility that receives, stores, and regasifies liquefied natural gas for localized distribution, typically incorporating cryogenic storage vessels rated for minus 162 degrees Celsius alongside vaporization and pressure regulation skids. These installations bridge pipeline gaps by delivering natural gas to industrial zones, marine terminals, and remote communities without grid connectivity. Full containment systems dominate capital deployment due to regulatory mandates for secondary spill protection, while membrane technology captures the fastest expansion owing to reduced footprint requirements and faster site assembly. Onshore deployment absorbs the majority of current investment, though remote location installations are deepening as mining and extraction operators seek fuel switching away from diesel generators.
FERC in the United States governs siting and safety standards for LNG facilities, while the EU Green Deal and F-Gas Regulation constrain methane leakage thresholds and refrigerant selections across European installations. India's Petroleum and Natural Gas Regulatory Board enforces city gas distribution licensing that directly shapes satellite station placement and throughput obligations. Stakeholders must monitor evolving methane intensity benchmarks and carbon border adjustment mechanisms that will determine project finance eligibility and offtake contract pricing in key demand corridors.
Market Dynamics
Membrane containment systems are compressing construction timelines and eroding the cost advantage of conventional concrete tanks, forcing incumbent fabricators to retool fabrication lines or cede coastal industrial projects to modular specialists.
Growth Catalysts
- FERC Safety Mandates:Full containment system requirements for secondary spill protection in the United States accelerate capital deployment toward compliant storage vessels and vaporization skids.
- Industrial Heating Demand:Energy-intensive manufacturing clusters across Gujarat and Jiangsu adopt LNG satellite stations to replace coal-fired process heat and meet tightening emission standards.
- Marine Bunkering Infrastructure:Port-proximate facilities in Texas and Singapore expand storage and regasification capacity to service dual-fuel vessel fleets under IMO sulfur caps.
Market Restraints
- Nickel-Alloy Input Volatility:Cryogenic storage vessel fabrication depends on nickel and austenitic stainless steel prices, which swing with Indonesian ore export policies and LME inventory cycles.
- European Regulatory Friction:The EU F-Gas Regulation constrains refrigerant selections for liquefaction and regasification cycles, limiting equipment sourcing and extending procurement timelines.
- Diesel Generator Substitution Threat:Remote mining operators retain diesel backup capacity where LNG supply chain reliability remains unproven, slowing fuel-switching commitments.
Strategic Opportunities
- Indian City Gas Distribution:PNGRB licensing mandates for compressed natural gas and piped natural gas networks create anchor demand for satellite stations in unserved tier-2 and tier-3 cities.
- Membrane-Concrete Hybrid Designs:Convergence of composite membrane materials with conventional concrete secondary containment opens retrofit opportunities at aging import terminals.
- Carbon Border Adjustment Mechanisms:Emerging EU carbon tariffs on embodied emissions in manufactured goods incentivize Chinese and Indian industrial exporters to source lower-carbon process fuels.
Industry Challenges
- Cryogenic Welding Certification:Qualified technicians for 9% nickel steel and aluminum alloy fabrication remain scarce, extending commissioning schedules for membrane tank assembly crews.
- Legacy Control System Integration:Distributed control system protocols at brownfield industrial sites require custom middleware development to interface with modern vaporization skid PLCs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LNG Satellite Station Market |
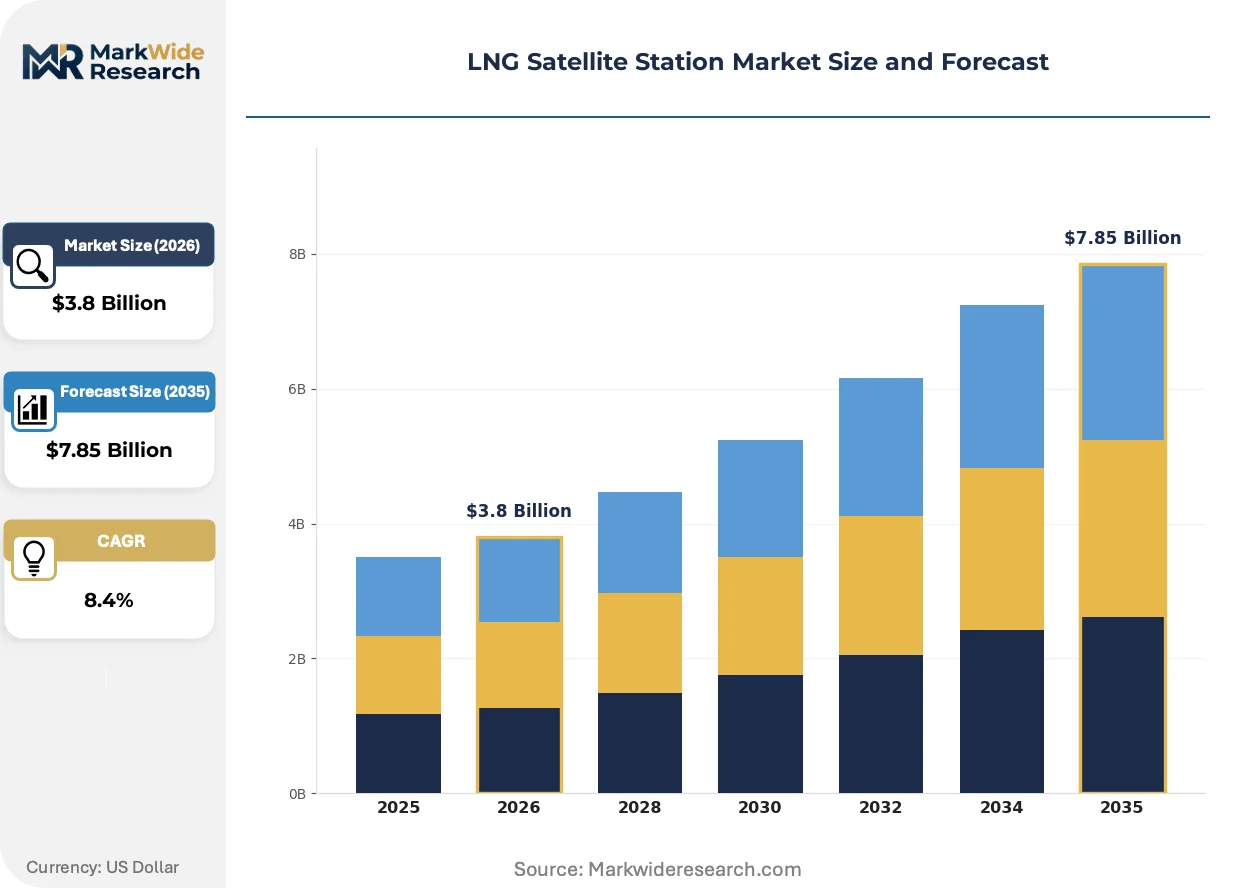
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Membrane Technology, Full Containment, Spherical Tanks, Horizontal Tanks Application: Power Generation, Marine Fuel, Industrial Heating, Residential Heating End User: Utilities, Transportation, Construction, Oil & Gas Deployment: Onshore, Offshore, Remote Locations, Urban Areas |
| Companies Covered | Honeywell International Inc., Mitsubishi Kakoki Kaisha, Shell Plc, Cryolor, JFE Engineering, Chart Industries, Wartsila Oyj ABP, Axègaz, Linde Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LNG Satellite Station Market Trends and Innovations
Equipment miniaturization and regulatory tightening around methane intensity are converging to redefine competitive advantage around speed of deployment rather than unit scale.
Composite membrane containment is modularizing small-scale LNG storage by replacing concrete primary barriers with prefabricated stainless steel and polyurethane laminate panels. Industrial developers in India and China now specify membrane systems for 5,000-20,000 cubic meter installations that ship in standard containers and assemble on-site within weeks. This compression of construction duration is modularizing project finance structures, enabling developers to sequence offtake contracts after rather than before capital commitment.
The EU Green Deal methane leakage thresholds are forcing equipment vendors to redesign vaporization skids with enhanced sealing systems and continuous emissions monitoring. Installations across Rotterdam and Hamburg now incorporate infrared detection and closed-loop flare recovery to stay below tightening ppm limits. Asian fabricators supplying European projects must certify equipment under updated EN standards, creating compliance lag for non-EU manufacturers.
Industrial buyers are consolidating procurement authority from plant-level engineers to centralized energy desks that negotiate multi-site fuel supply agreements. This concentration of purchasing power compresses vendor margins and privileges suppliers offering throughput guarantees and integrated maintenance contracts. The shift is most visible across Texas petrochemical complexes and Jiangsu steel mill clusters where fuel costs dominate operating expenditure.
LNG Satellite Station Market Segmentation
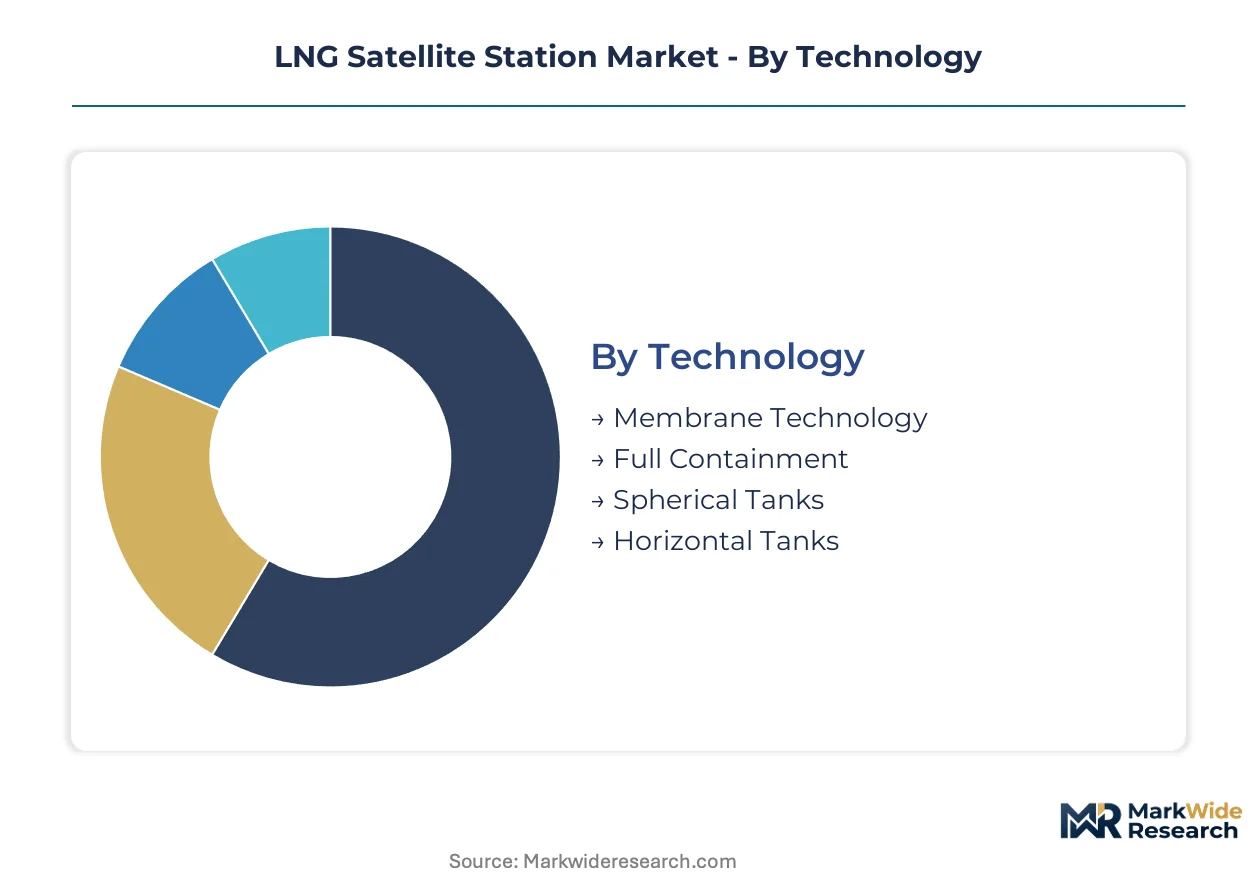
Segmentation in the LNG satellite station market reveals how certification burdens, deployment constraints, and end-use requirements reshape procurement patterns across technology categories. Understanding these divisions exposes where capital concentrates and where modular solutions displace legacy infrastructure.
Technology:
Membrane technology carries lighter foundation and seismic certification requirements than concrete alternatives, while full containment systems demand FERC-mandated secondary spill protection documentation that extends permitting timelines.
- Membrane Technology:Prefabricated stainless steel and polyurethane laminate panels assemble on-site within weeks, cutting foundation costs by 60% versus concrete. Demand concentrates in Gujarat and Jiangsu manufacturing clusters where speed-to-operation outweighs 40-year asset life assumptions.
- Full Containment:Double-walled concrete and steel configurations with secondary spill barriers dominate US coastal installations under FERC safety mandates. Texas port-proximate facilities absorb the majority of capital deployment despite 18-24 month construction timelines.
- Spherical Tanks:High-pressure rated aluminum alloy vessels serve marine bunkering applications in Singapore where space constraints favor vertical footprint optimization.
- Horizontal Tanks:Cylindrical configurations suit remote mining camps in Western Australia with modular transport requirements and lower throughput needs.
Full containment sits at the top of the volume ranking, with membrane technology climbing the fastest.
Application:
Application segmentation tracks how emission regulations and fuel switching economics concentrate investment across industrial, marine, and power generation corridors.
- Industrial Heating:Process heat substitution in energy-intensive manufacturing drives the steepest expansion trajectory. Jiangsu steel mills and Gujarat chemical complexes deploy satellite stations to displace coal-fired boilers under tightening MEE and Central Pollution Control Board mandates.
- Marine Fuel:IMO sulfur caps and EU Green Deal methane thresholds force Rotterdam and Hamburg terminals to install vaporization skids with infrared leak detection. Dual-fuel vessel fleets now require bunkering infrastructure at 15+ ports.
- Power Generation:Grid-isolated industrial parks in Texas and Louisiana specify satellite stations for combined-cycle peaking units where pipeline interconnections remain uneconomical.
- Residential Heating:Polish and Czech district heating networks pilot small-scale regasification for seasonal peak shaving, constrained by EU F-Gas Regulation refrigerant restrictions.
Industrial heating commands the largest installed base, while marine fuel gains share fastest on IMO regulatory momentum.
End User:
End user segmentation exposes divergent procurement authority structures, from centralized utility fuel desks to fragmented construction site managers.
- Utilities:City gas distribution licensees under India's PNGRB anchor demand through 25-year throughput contracts. Consolidated procurement compresses vendor margins and privileges integrated maintenance agreements.
- Transportation:Marine terminal operators and trucking fleet owners seek portable vaporization skids for flexible bunkering logistics across Rotterdam, Singapore, and Houston.
- Construction:Remote infrastructure projects in Western Canada specify temporary satellite stations for equipment fueling, with diesel backup retention where supply chain reliability remains unproven.
- Oil & Gas:Upstream operators in the Permian Basin deploy stations for drilling power and flare gas replacement, subject to EPA methane performance standards.
Utilities dominate contract value, with transportation expanding most quickly on marine bunkering infrastructure buildout.
Deployment:
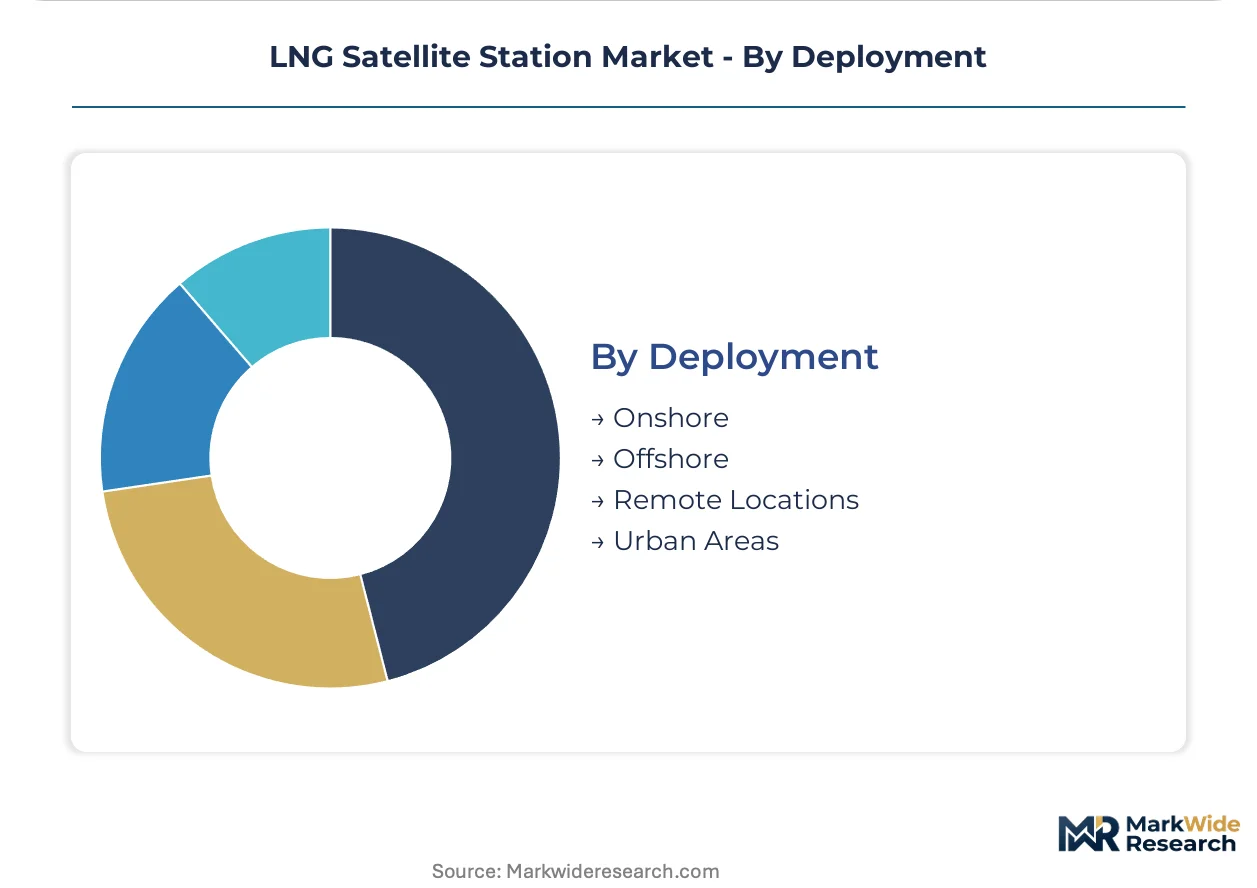
Deployment mode determines foundation engineering, logistics burden, and regulatory jurisdiction with sharp cost tier differentiation.
- Onshore:Coastal industrial zones in Texas, Gujarat, and Jiangsu absorb majority capital deployment. FERC, PNGRB, and MEE permitting pathways create 6-18 month variance in commissioning schedules.
- Remote Locations:Mining and extraction operators in Western Australia and Northern Canada pursue fuel switching from diesel generators. Supply chain reliability gaps slow commitment velocity despite carbon reduction targets.
- Offshore:Platform-integrated mini-LNG facilities serve North Sea decommissioning and West African field development, constrained by DNV certification requirements for marine environment exposure.
- Urban Areas:Dense European and Japanese cities specify below-ground membrane tanks with 5,000 cubic meter limits, navigating seismic codes and land scarcity simultaneously.
Onshore deployment leads absolute investment, with remote locations showing the steepest expansion trajectory on mining sector decarbonization pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gujarat's chemical manufacturing corridor anchors near-term deployment velocity for membrane containment systems serving industrial heating retrofits. FERC safety mandates in the United States and EU Green Deal methane thresholds are reshaping capital allocation toward compliant full containment infrastructure. India's PNGRB licensing framework and China's MEE emission standards are compressing procurement timelines across Asian industrial clusters.
United States
Texas port-proximate facilities absorb the majority of North American capital deployment for marine bunkering infrastructure serving dual-fuel vessel fleets. FERC governs siting and safety standards for secondary spill protection requirements that extend permitting timelines to 18-24 months. Houston-Galveston industrial zones specify full containment systems for combined-cycle peaking units where pipeline interconnections remain uneconomical.
China
Jiangsu steel mills and manufacturing clusters deploy membrane technology to displace coal-fired process heat under tightening MEE emission mandates. The country's dual carbon goals accelerate fuel-switching timelines for energy-intensive industrial zones along the Yangtze River Delta. Nantong and Zhangjiagang port facilities integrate satellite stations with marine bunkering operations for coastal shipping corridors.
India
Gujarat chemical complexes and ceramic manufacturing belts adopt LNG satellite stations to meet Central Pollution Control Board particulate emission caps. PNGRB city gas distribution licensing creates anchor demand through 25-year throughput contracts for compressed natural gas networks. Hazira and Mundra industrial zones concentrate membrane system deployment where speed-to-operation outweighs 40-year asset life assumptions.
Germany
Rotterdam and Hamburg terminals install vaporization skids with infrared leak detection to stay below EU Green Deal methane leakage thresholds. The EU F-Gas Regulation constrains refrigerant selections for regasification cycles, limiting equipment sourcing options for Asian fabricators. Ruhr industrial heritage zones pilot membrane-concrete hybrid retrofits at aging import terminals.
Singapore
Marine bunkering infrastructure expansion supports dual-fuel vessel fleets under IMO sulfur caps across Southeast Asian shipping lanes. Space constraints at Jurong Port favor spherical tank configurations with vertical footprint optimization for high-pressure vaporization skids. The Maritime and Port Authority's licensing framework shapes storage capacity placement and throughput obligations for terminal operators.
LNG Satellite Station Market Competitive Landscape
Capacity expansion dominates the current landscape as fabricators retool lines to capture membrane technology share from conventional concrete specialists. The vendor base stratifies across three tiers: integrated cryogenic equipment conglomerates with captive insulation substrate production, regional tank fabricators serving licensed city gas distribution networks, and modular skid specialists compressing on-site assembly timelines. Consolidation pressure is intensifying as procurement authority shifts from plant engineers to centralized energy desks demanding throughput guarantees.
Among integrated cryogenic equipment conglomerates, Chart Industries and Linde Plc occupy positions defined by backward integration into cold-box assemblies and insulation substrates. Mitsubishi Kakoki Kaisha sits within the high-pressure vaporization skid specialist tier, anchoring integrated station packages for Asian industrial clients. These three companies exemplify how vertical manufacturing scale and captive component production separate premium-tier vendors from regional competitors bidding on standardized storage vessel contracts.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Mitsubishi Kakoki Kaisha |
| Shell Plc |
| Cryolor |
| JFE Engineering |
| Chart Industries |
| Wartsila Oyj ABP |
| Axègaz |
| Linde Plc |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal methane leakage thresholds gate both qualified supply and premium-tier pricing access, as Asian fabricators must certify equipment under updated EN standards to serve Rotterdam and Hamburg terminals. This regulatory filter concentrates sourcing authority among vendors with captive cold-box production and backward integration into insulation substrates, while compressing margins for standardized storage vessel contractors.
Pricing Analysis
Input-cost pass-through from nickel-alloy volatility shapes contract structures across cryogenic vessel fabrication. Pricing stratifies across FERC-certified full containment, membrane modular systems, and economy-grade horizontal tanks for remote deployment. Price differentiation rests on certification grade and after-sales service bundling. Cost compression in membrane tiers is intensifying because prefabricated panel assembly cuts foundation requirements by sixty percent. City gas distribution licensees under India's PNGRB show least price sensitivity due to twenty-five-year throughput guarantees, while remote mining operators retain diesel backup where LNG supply reliability remains unproven.
Supply Chain Analysis
Regional distribution centers in South Korea, Japan, and Germany anchor hub-and-spoke patterns for cryogenic equipment components. Fabrication draws from Indonesian nickel ore, Chinese stainless steel rolling capacity, and German polyurethane laminate substrate production. Single-source vulnerability concentrates in 9% nickel steel plate supply from limited qualified mills. Distribution runs through EPC contractor networks and licensed city gas distribution integrators rather than direct OEM channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Industrial buyers consolidating procurement authority toward centralized energy desks now specify throughput guarantees and integrated maintenance contracts that favor vendors with captive component production.
For Market Incumbents: Hedge membrane technology share erosion by retooling concrete fabrication lines for hybrid membrane-concrete retrofits at aging import terminals. Anchor position through backward integration into cold-box assemblies and insulation substrates. Defend against modular skid specialists compressing on-site assembly timelines by certifying equipment under updated EN standards for EU Green Deal compliance. For New Entrants and Emerging Players: Marine terminal operators in Southeast Asia represent the most penetrable channel partner type for portable vaporization skids serving flexible bunkering logistics. Target unserved tier-2 and tier-3 Indian cities under PNGRB licensing mandates where speed-to-operation outweighs forty-year asset life assumptions. Enter through membrane system deployment partnerships with Gujarat and Jiangsu manufacturing clusters seeking coal displacement. For Investors and Strategic Acquirers: Roll-up economics work for regional tank fabricators serving licensed city gas distribution networks because procurement authority concentration privileges integrated maintenance agreements over pure equipment sales. Five-to-ten year viability hinges on carbon border adjustment mechanism adoption by Chinese and Indian industrial exporters seeking lower-carbon process fuels. Watch EU methane intensity benchmarks tightening toward ppm-level thresholds as the inflection signal for compliance-premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Technology Certification | EN standard compliance unlocks Rotterdam and Hamburg terminal procurement under EU Green Deal thresholds. |
| Backward Integration into Insulation Substrates | Captive cold-box production separates premium-tier vendors from standardized storage vessel competitors. |
| City Gas Distribution Licensing Partnership | PNGRB mandates in India create twenty-five-year anchor demand through compressed natural gas network buildout. |
| Marine Bunkering Infrastructure Expansion | IMO sulfur caps force dual-fuel vessel fleet servicing capacity at fifteen-plus global ports. |
| Hybrid Membrane-Concrete Retrofit Development | Aging import terminals in Ruhr zones and coastal US facilities present brownfield upgrade opportunities. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with EPC contractors, city gas distribution licensing officers, cryogenic equipment procurement leads, and marine terminal operators alongside secondary validation. Sources include FERC filings, EU ETS and F-Gas Regulation documentation, PNGRB licensing records, MEE emission standard publications, and customs trade data for nickel-alloy inputs. Bottom-up project pipeline assessment triangulates against top-down industrial fuel substitution modeling.
Granularity-level framing models technology categories at the containment system variant level, application segments at the end-use process heat substitution level, and deployment modes at the regulatory jurisdiction level across the projection horizon. CAGRs derive from weighted average of segment-specific deployment velocities and input cost trajectory assumptions. Forecast inputs incorporate nickel price volatility cycles, FERC permitting timeline distributions, and PNGRB licensing cadence.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to carbon border adjustment mechanism implementation timing and EU methane intensity benchmark tightening. Forecasts reflect documented assumptions around industrial coal displacement economics and marine bunkering infrastructure buildout rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Africa Oil and Gas Downstream Market
Offshore Oil and Gas
Norway Offshore Oil and Gas Decommissioning Market
Offshore Oil and Gas
North Sea Oil and Gas Market
Offshore Oil and Gas
East Africa Natural Oil and Gas Midstream Market
Offshore Oil and Gas
Deep Water Drilling Market
Offshore Oil and Gas
Iran Oil and Gas Downstream Market
Offshore Oil and Gas
North America FLNG Market
Offshore Oil and Gas
Equatorial Guinea Oil and Gas Midstream Market
Offshore Oil and Gas
Norway Oil and Gas Downstream Market
Offshore Oil and Gas
China Oil and Gas Upstream Market
Offshore Oil and Gas
Abyssinian Oil Market
Offshore Oil and Gas
Offshore Drilling Market
Offshore Oil and Gas
Europe Floating Offshore Wind Power Market
Offshore Oil and Gas
Oil and Gas Downstream Market
Offshore Oil and Gas
South Sudan Oil and Gas Upstream Market
Offshore Oil and Gas
Norway Oil and Gas EPC Market