
 Utility Locator Market | 2026-2036
Utility Locator Market Size, Share, and Industry Trends Forecast 2026-2036
Utility Locator Market Intelligence
The 'Dig Once' policy framework in the United States is decoupling project timelines from the availability of utility maps, increasing the upfront requirement for accurate location services. Radiodetection Ltd. leverages its strong brand recognition in electromagnetic locators. Leica Geosystems competes with integrated hardware and software solutions for complex surveying tasks. Geophysical Survey Systems, Inc. specializes in ground penetrating radar (GPR) technology for challenging subsurface environments.
A utility locator is an electronic instrument used to detect and trace buried public utility mains. These devices operate by detecting electromagnetic fields or using ground penetrating radar with frequencies often between 100 and 900 MHz, preventing damage during excavation. While electromagnetic locators constitute the largest product segment, ground penetrating radar systems are gaining share. This growth is driven by demand from telecom operators and municipal authorities for locating non-conductive assets.
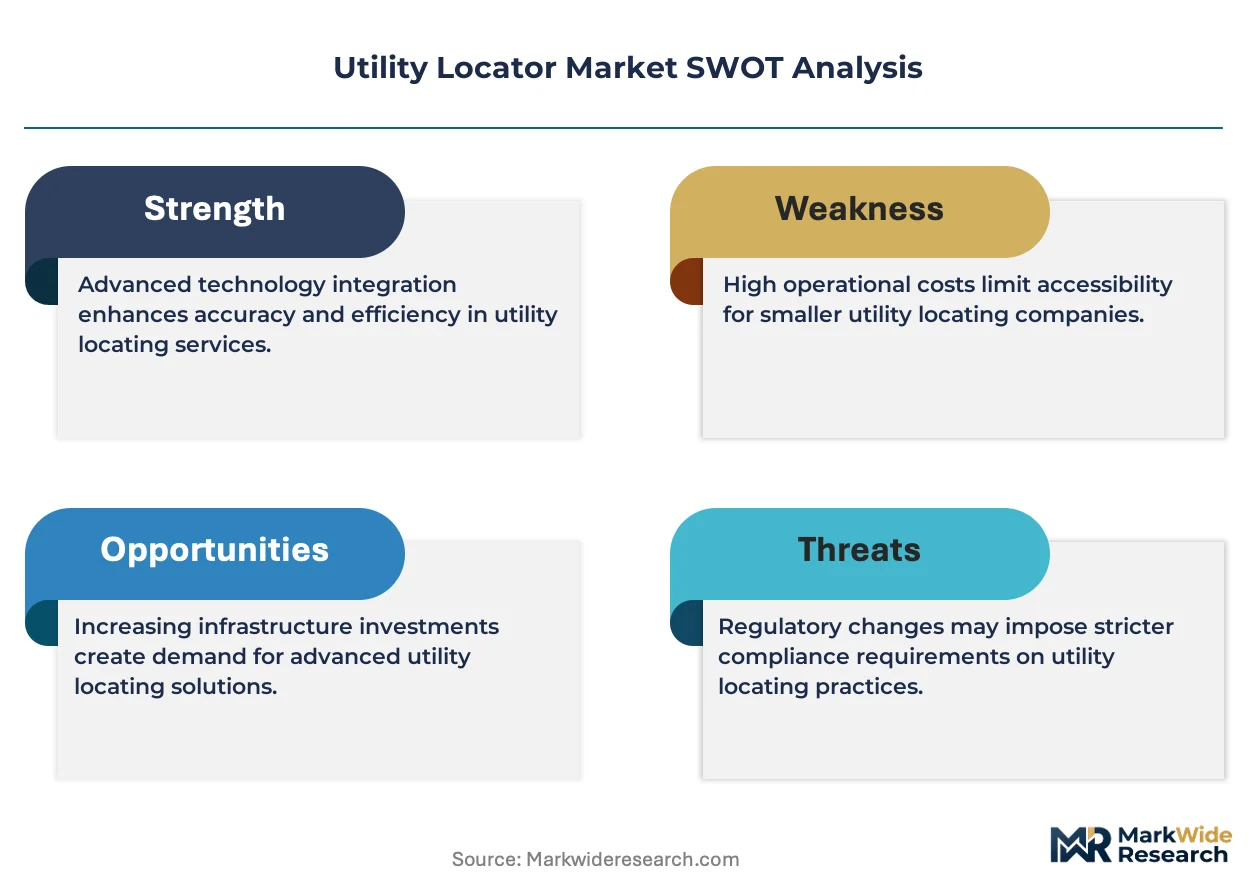
Damage prevention regulations enforced by bodies like the U.S. Occupational Safety and Health Administration (OSHA) create a baseline for safe excavation. Formal standards such as the UK’s PAS 128 and Australia’s AS 5488 are elevating the requirements for locator accuracy and data quality. This regulatory pressure shapes technology adoption among construction contractors and municipal authorities. Decisions for market participants now center on balancing the capital cost of advanced locating technologies against the rising liability of utility strikes.
Market Dynamics
The utility locator market is defined by a structural shift from basic damage avoidance to precision mapping for infrastructure projects. This transition is driven by new data quality standards and the high cost of utility strikes during urban densification.
Growth Catalysts
- Dig Once Policies:Frameworks like the 'Dig Once' policy in the United States increase upfront demand for comprehensive locating to coordinate multiple utility installations.
- Telecommunication Infrastructure:The global expansion of fiber optic networks by telecom operators requires precise locating services to plan routes and prevent damage to existing assets.
- SUE Standards:Adoption of Subsurface Utility Engineering (SUE) standards provides a formal framework that elevates the requirement for accurate locating in construction and civil engineering.
Market Restraints
- High Capital Cost:The significant initial investment required for advanced ground penetrating radar and multi-frequency electromagnetic systems presents a barrier for smaller contractors.
- GPR Performance Limitations:Ground penetrating radar technology can be less effective in certain subsurface conditions, such as high-conductivity clay soils or saturated ground.
- Inaccurate Legacy Records:Poor quality or nonexistent historical utility maps in older urban areas complicate locating efforts and increase the risk of undetected utilities.
Strategic Opportunities
- BIM and GIS Integration:Integrating locator data into Building Information Modeling (BIM) and Geographic Information System (GIS) platforms creates opportunities for offering 3D utility mapping services.
- Non-Conductive Asset Locating:Growth in locating non-metallic assets, such as plastic water pipes and fiber optic cables, creates demand for GPR systems among municipal authorities.
- Infrastructure Renewal Projects:Large-scale public works and infrastructure modernization programs in countries like India and the United States create sustained demand for locating services.
Industry Challenges
- Technician Skill Gap:A shortage of skilled technicians capable of operating advanced locators and accurately interpreting complex GPR or electromagnetic field data remains a key operational constraint.
- Data Standardization:The lack of universal standards for collecting, formatting, and sharing subsurface utility data hinders interoperability between different systems and stakeholders on a project.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Utility Locator Market |
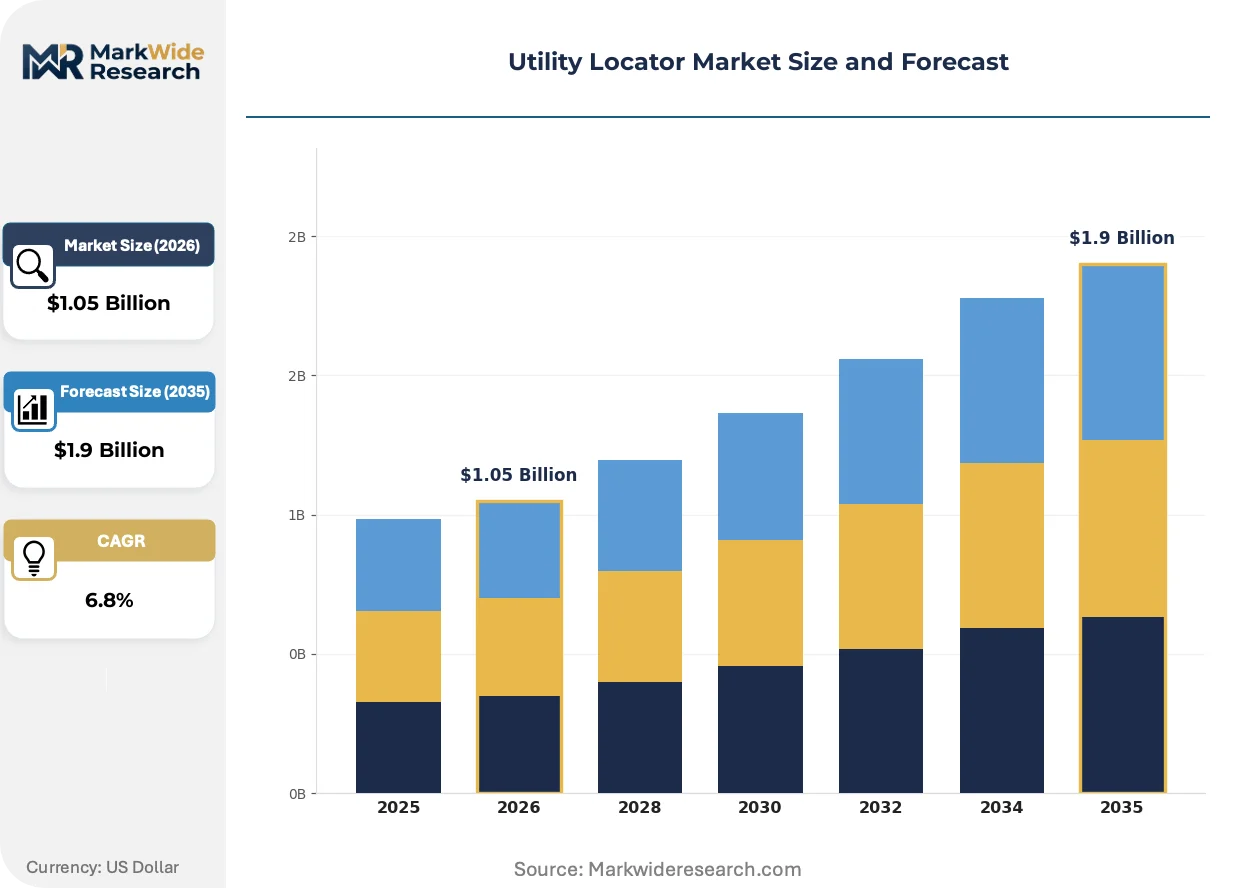
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $1.9 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electromagnetic Locators, Ground Penetrating Radar, Acoustic Locators, RFID Locators, Ultrasonic Locators End Use Sector: Construction Contractors, Municipal Authorities, Telecom Operators, Pipeline Operators, Electrical Utility Firms Technology: Radio Frequency Identification, Magnetic Field Detection, Sonar Technology, Infrared Scanning, Laser Detection Deployment Mode: Handheld Devices, Vehicle-Mounted Systems, Portable Kits, Drone-Based Solutions, Fixed Installations |
| Companies Covered | Geophysical Survey Systems, Inc., Leica Geosystems, Vivax-Metrotech, The Charles Machine Works, Inc., 3M Company, Radiodetection Ltd., Guideline Geo, RIDGID, Emerson Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Utility Locator Market Strategic Shifts & Innovations
Technology and service models are evolving toward the creation of digital subsurface assets, not just physical markings. This move transforms one-off locating tasks into a continuous data management process for asset owners like municipalities and telecom operators.
Multi-frequency electromagnetic locators and modular ground penetrating radar (GPR) systems provide enhanced detection capabilities. Construction contractors and specialized locating firms are adopting these systems to improve accuracy in congested underground environments. This technology is modularizing the field toolkit, allowing technicians to adapt a single platform for diverse soil types and target materials.
Australia’s AS 5488 standard for classifying subsurface utility information is creating new data quality requirements. The standard compels engineering firms to specify and verify the quality level of located data, moving beyond simple detection. Construction contractors working on public infrastructure projects are most affected, now needing to invest in compliant technology and workflows.
A shift toward equipment leasing and rental models is gaining traction among small and mid-sized contractors. This trend disrupts the traditional direct-purchase channel, especially for high-end GPR systems with significant capital outlay. The pattern is most pronounced in the United States and European markets, where equipment costs and project-based work cycles favor operational expenditure.
Utility Locator Market Segmentation
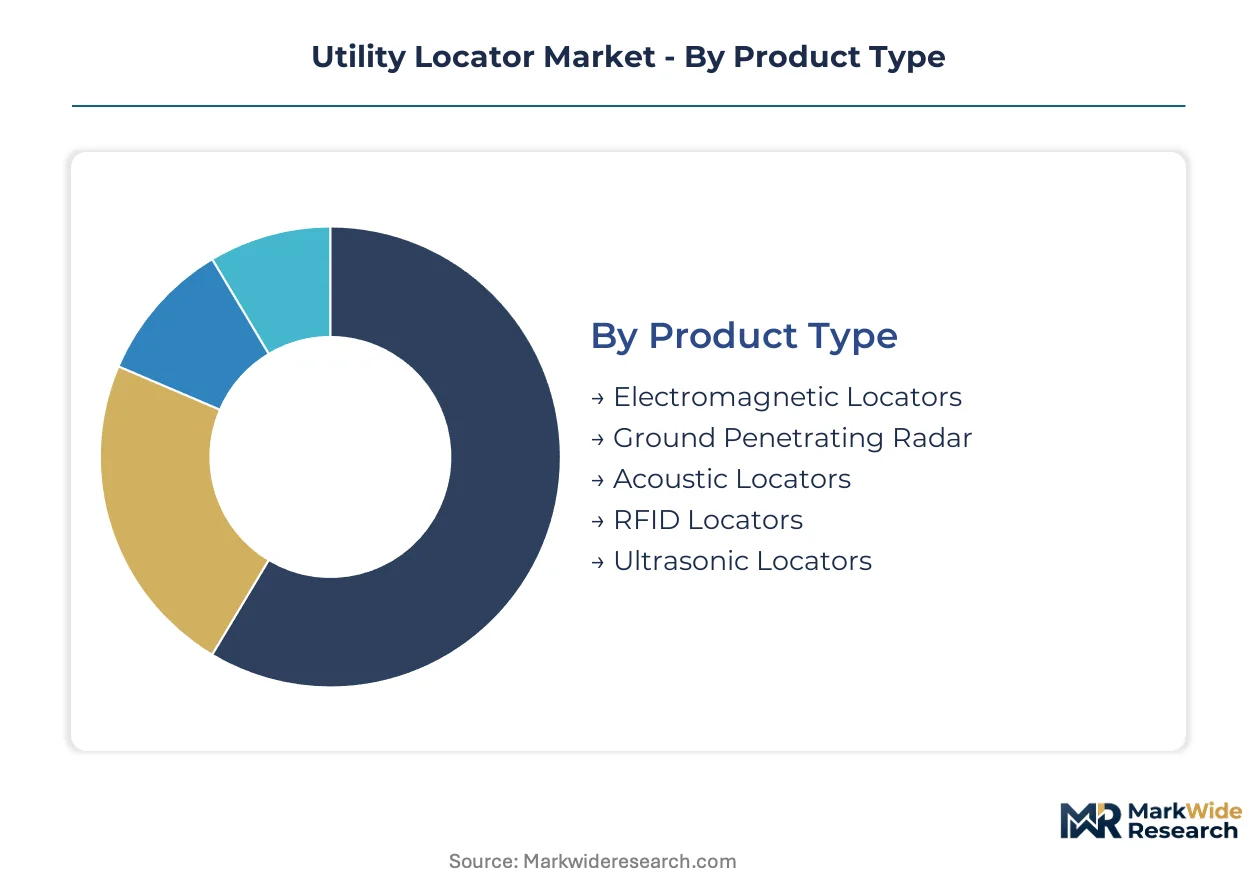
The utility locator market exhibits distinct segments driven by varying technological capabilities, end-user requirements, and deployment preferences. Understanding these segmentations provides clarity on market demand patterns and strategic investment areas for participants.
Product Type:
Supply of utility locator products concentrates around specific detection methodologies, each suited for distinct subsurface environments.
- Electromagnetic Locators:These instruments detect conductive utilities by sensing electromagnetic fields generated by current flow or induced signals. Demand concentrates among telecom operators expanding fiber networks, requiring precise mapping of existing metallic infrastructure.
- Ground Penetrating Radar:GPR systems use high-frequency radio waves, often between 100 and 900 MHz, to detect subsurface anomalies and non-conductive utilities. Demand focuses on municipal authorities locating non-conductive assets like plastic water pipes and fiber optic conduits.
- Acoustic Locators:These devices detect leaks or voids using sound waves; water utility firms use them for pipe integrity checks.
- RFID Locators:They locate utilities marked with passive RFID tags; employed for precise asset identification in new installations.
- Ultrasonic Locators:These utilize sound waves to map internal pipe conditions; primarily used for sewer and drain inspections.
Electromagnetic Locators absorb the bulk of installed capacity; Ground Penetrating Radar is expanding most quickly.
End Use Sector:
The application of utility locator technology varies significantly across different end-use sectors, reflecting diverse operational needs and regulatory compliance requirements.
- Construction Contractors:These firms require accurate locating services to prevent utility strikes during excavation activities on project sites. Demand is driven by damage prevention regulations enforced by bodies like the U.S. Occupational Safety and Health Administration (OSHA).
- Telecom Operators:These entities need precise mapping for the global expansion of fiber optic networks and new cable installations. Their focus is on preventing damage to existing infrastructure during new deployments and maintenance.
- Municipal Authorities:They use locators for managing public infrastructure assets; focus on locating non-conductive assets like plastic water pipes.
- Pipeline Operators:These companies employ advanced systems for maintaining gas and oil pipelines; they prioritize safety and integrity of buried assets.
- Electrical Utility Firms:They utilize locators for identifying buried power cables; essential for preventing outages and ensuring worker safety.
Demand from Construction Contractors remains consistently high, while Telecom Operators show significant growth potential.
Technology:
The maturity curve of utility locating technologies ranges from established detection methods to emerging digital mapping solutions.
- Magnetic Field Detection:This technology employs electromagnetic principles to sense conductive materials, forming the core of widely used electromagnetic locators. It is essential for identifying metal pipes and electrical cables.
- Radio Frequency Identification:This technology utilizes embedded RFID tags for exact point identification and data retrieval from marked utilities. Demand is growing for precise mapping of newly installed non-metallic utilities.
- Sonar Technology:This uses acoustic waves to detect subsurface features; applied in specialized contexts like underwater or pipeline inspections.
- Infrared Scanning:This detects temperature differentials for identifying leaks or buried objects; useful for specific anomalies.
- Laser Detection:Primarily used for precise positioning and mapping above ground; integrates with survey equipment for accurate utility data capture.
The adoption rate for Magnetic Field Detection is mature, whereas Radio Frequency Identification is gaining traction.
Deployment Mode:
Different customer types drive the preference for specific deployment modes, balancing mobility with data collection scope.
- Handheld Devices:These offer portability and ease of use for field technicians, enabling quick and efficient on-site locating. They represent the most common deployment mode for daily locating tasks by contractors.
- Vehicle-Mounted Systems:These integrate GPR or other sensors onto vehicles for rapid surveying of large areas and corridors. They are preferred by municipal authorities and large infrastructure projects for efficiency in data collection.
- Portable Kits:These provide modular components for varied site conditions; offering flexibility for specialized locating firms.
- Drone-Based Solutions:These utilize aerial platforms for remote sensing and mapping; an emerging mode for large-scale preliminary surveys.
- Fixed Installations:These are permanently installed sensors for continuous monitoring; used in critical infrastructure areas for real-time utility integrity checks.
Most operational activity relies on Handheld Devices, with Vehicle-Mounted Systems seeing increased investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The 'Dig Once' policy framework in the United States drives significant demand concentration for utility locating services. This policy increases upfront requirements for accurate subsurface mapping to coordinate multiple utility installations. Diverse infrastructure development programs across other key global regions further shape demand patterns.
United States
Public infrastructure renewal projects and expanding telecom fiber networks generate substantial demand for utility locating. The U.S. Occupational Safety and Health Administration (OSHA) enforces damage prevention regulations, creating a baseline for safe excavation practices. California's dense urban areas, including Los Angeles and San Francisco, see intensive locating for ongoing utility upgrades and smart city initiatives.
India
Large-scale public works and rapid urban densification necessitate precise subsurface utility mapping. Government infrastructure modernization programs, particularly in transportation and digital connectivity, drive increased demand for advanced locators. Mumbai's extensive metro expansion projects require comprehensive underground utility detection to prevent costly strikes and project delays.
United Kingdom
The adoption of Subsurface Utility Engineering (SUE) standards, such as PAS 128, elevates requirements for locating accuracy in construction and civil engineering. Urban infrastructure upgrades and utility network maintenance contribute to consistent demand. London's complex and extensive underground networks necessitate advanced locating services for new developments and existing asset management.
Australia
Compliance with the AS 5488 standard for classifying subsurface utility information creates new data quality requirements for engineering firms. New infrastructure developments, including major road and rail projects, require detailed utility mapping. Sydney's ongoing public transport projects, like the Metro system, require precise subsurface utility information for safe and efficient construction.
Utility Locator Market Key Industry Players
North American producers anchor one tier, emphasizing robust equipment and software integration; European specialists hold another, focusing on precision and adherence to advanced SUE standards. The market exhibits a tiered structure, with global technology leaders and specialized GPR providers. Key strategic archetypes include integrated hardware/software providers, GPR technology specialists, and traditional electromagnetic locator manufacturers. Competitive moves involve technology integration and strategic partnerships to offer comprehensive solutions.
Among global technology providers, Leica Geosystems exemplifies integrated hardware and software solutions for complex surveying tasks. Geophysical Survey Systems, Inc. represents specialized expertise in ground penetrating radar technology for challenging environments. Radiodetection Ltd. anchors the electromagnetic locator segment with strong brand recognition. These entities collectively drive innovation in detection capabilities and data quality across diverse project requirements.
| Leading Market Players |
|---|
| Geophysical Survey Systems, Inc. |
| Leica Geosystems |
| Vivax-Metrotech |
| The Charles Machine Works, Inc. |
| 3M Company |
| Radiodetection Ltd. |
| Guideline Geo |
| RIDGID |
| Emerson Electric |
| Others |
Cost & Logistics Intelligence
A scarcity of skilled technicians in specialized GPR operation directly links to higher service pricing tiers, influencing both equipment and advanced solution costs.
Pricing Analysis
Lead-time-driven pricing structures reward early project planning with better rates, while urgent requirements for advanced locating services incur premium charges. Project-based pricing models dominate, reflecting the bespoke nature of subsurface utility mapping tasks. Price differentiation stems from the accuracy level of the data delivered and the specific technology deployed. Pricing softness reflects the increasing availability of entry-level electromagnetic locators. Construction contractors remain highly price-sensitive for routine tasks, while municipal authorities prioritize accuracy over cost for critical infrastructure projects.
Supply Chain Analysis
Reverse-logistics pathways for specialized GPR and electromagnetic locators facilitate equipment refurbishment and rental models, extending product lifecycle. Supply concentration for advanced components, such as high-frequency radar emitters and signal processing units, centers in countries like the United States, Germany, and Japan. The industry draws from specialized electronics and sensor manufacturing. Single-source vulnerability for proprietary sensor technology represents a structural risk. Distribution runs through a network of specialized equipment dealers and direct sales channels to large infrastructure firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The utility locator market is navigating a technology-transition phase, with advanced GPR and integrated digital mapping solutions displacing traditional manual detection methods.
For Market Incumbents: Deepen integration efforts between hardware and software platforms to offer comprehensive 3D utility mapping solutions. Consolidate market share by acquiring smaller specialized firms focused on niche GPR applications, addressing the threat from fragmented service providers. Invest in advanced sensor R&D to maintain a technological edge. Focus on developing standardized data output formats for seamless integration with BIM and GIS platforms.
For New Entrants and Emerging Players: A price-point gap exists between high-end GPR systems and basic electromagnetic locators, presenting an opportunity for modular, mid-range solutions. Target smaller construction contractors and local municipalities in developing regions. Offer equipment leasing and rental models to overcome high capital cost barriers for these segments. Focus on user-friendly interfaces and robust training programs as a go-to-market angle.
For Investors and Strategic Acquirers: Re-rating potential sits with integrated solution providers given the increasing regulatory push for data quality and precision mapping. The long-term viability of the market is strong, driven by global infrastructure renewal and digitization trends. Identify acquisition targets with strong intellectual property in GPR technology or established software platforms for utility data management. Monitor the adoption rate of SUE standards as a key inflection indicator for market acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Integrated Hardware/Software Platforms | Leica Geosystems enhances user workflows and data fidelity for complex survey tasks. |
| Expand Equipment Leasing & Rental Programs | Vivax-Metrotech addresses capital cost barriers for smaller construction contractors. |
| Invest in Advanced GPR Sensor R&D | Geophysical Survey Systems, Inc. improves detection capabilities in challenging subsurface environments. |
| Form Strategic Partnerships with Engineering Firms | Radiodetection Ltd. ensures data quality compliance with evolving SUE standards. |
| Standardize Data Output for BIM/GIS Integration | The Charles Machine Works, Inc. facilitates seamless incorporation into large infrastructure projects. |
Research Approach
Document review covered industry reports, regulatory filings from OSHA and PAS 128, and technical specifications from leading manufacturers, complemented by interviews with project managers, utility engineers, and field technicians. This approach combined primary insights with secondary validation across diverse data sources. Bottom-up and top-down triangulation ensured data consistency and accuracy.
The quantitative model produced market size and growth forecasts across the modeling period, segmented by product type, end-use sector, technology, and deployment mode. Compound Annual Growth Rates were derived from historical data analysis and projected demand drivers. Key forecast inputs included infrastructure spending trends and telecom network expansion plans.
Inputs from public infrastructure spending reports and manufacturer product roadmaps were available through the study window; gaps in comprehensive historical pricing data introduce uncertainty bands. Forecasts reflect assumptions regarding regulatory enforcement and technological adoption rates. Practitioners should monitor global infrastructure investment cycles and SUE standard evolution for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Philippines Construction Equipment Market
Construction Equipment
Shotcrete Sprayer Market
Construction Equipment
Boring Bar Market
Construction Equipment
Concrete Testers Market
Construction Equipment
Rotomolding Market
Construction Equipment
Small Bulldozers Market
Construction Equipment
Arc Welding Equipment Market
Construction Equipment
Asia-Pacific Road Marking Machine Market
Construction Equipment
Crane Aftermarket Market
Construction Equipment
Self-Pierce Riveting (SPR) Equipment Market
Construction Equipment
Heavy Construction Equipment Rental Market
Construction Equipment
Assembly Machine Market
Construction Equipment
Global Cone Crusher Market
Construction Equipment
Compact Power Equipment Rental Market
Construction Equipment
Europe Construction Equipment Rental Market
Construction Equipment
Tower Crane Market