
 Europe Construction Equipment Rental Market | 2026-2036
Europe Construction Equipment Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Construction Equipment Rental Market Insights
CE marking under the Machinery Directive 2006/42/EC is reorganizing competitive access across the Europe construction equipment rental landscape, filtering out operators lacking certified maintenance protocols and documented safety traceability. Loxam Group leverages its pan-European depot network to sustain same-day availability guarantees in dense urban corridors. Boels Rental anchors its position through specialized high-reach aerial platforms for wind turbine maintenance across the North Sea basin. Zeppelin Rental differentiates via integrated telematics fleets that compete on utilization transparency rather than headline rates.
Europe construction equipment rental denotes the commercial provision of heavy machinery and access equipment on temporary contractual terms, encompassing earthmoving units with operating weights from 1.5 to 80 tonnes and aerial work platforms extending to 58 metres working height, primarily serving project-based contractors seeking capital flexibility and obsolescence protection. Excavators and bulldozers command the largest installed rental fleets, reflecting sustained civil engineering volumes and road renewal backlogs. Aerial work platforms represent the fastest-expanding equipment category, driven by stringent fall-protection enforcement and multi-storey retrofit mandates. Fleet management as a deployment model is capturing disproportionate margin pools as operators bundle telematics, predictive maintenance, and operator certification into multi-year service contracts.
The EU Green Deal and national transpositions of the Energy Performance of Buildings Directive are reshaping equipment specifications, with France's DGCCRF and Germany's KBA both intensifying emissions verification for diesel-powered rental fleets. REACH compliance for hydraulic fluids and lubricants adds material cost layers that favor larger rental houses with centralized procurement scale. Stakeholders must monitor the trajectory of Stage V emission retrofit deadlines and assess whether battery-electric equipment portfolios warrant accelerated capital commitment ahead of anticipated city-center access restrictions.
Market Dynamics
The EU Green Deal's embodied carbon tracking mandates are forcing contractors to abandon equipment ownership in favor of rental models that maximize asset utilization and minimize idle emissions across project portfolios.
Growth Catalysts
- Stage V Emission Standards:Germany's KBA enforcement of diesel retrofit deadlines accelerates fleet turnover toward cleaner rental equipment that contractors prefer over capital-intensive compliance investments.
- Urban Densification:Multi-storey retrofit mandates across Paris, Berlin, and Amsterdam drive aerial work platform demand as fall-protection regulations tighten on confined construction sites.
- Telematics Integration:IoT-enabled utilization tracking allows rental operators to bundle predictive maintenance and operator certification into multi-year service contracts capturing premium margins.
Market Restraints
- REACH Compliance Costs:Centralized procurement of hydraulic fluids and lubricants with full material traceability favors only the largest rental houses, squeezing mid-tier operators.
- Supply Concentration in Germany:Earthmoving equipment manufacturing clusters around Munich and Stuttgart create geographic dependency risks for rental fleets seeking rapid replacement availability.
- Stage V Retrofit Technical Limits:Battery-electric alternatives lack sufficient energy density for heavy earthmoving applications above 40 tonnes operating weight, constraining zero-emission transitions.
Strategic Opportunities
- Poland Infrastructure Pipeline:EU cohesion fund allocations for road and rail renewal create underpenetrated demand for excavator and compactor rental fleets outside established Western European markets.
- Wind Turbine Maintenance:North Sea offshore wind expansion requires specialized high-reach aerial platforms that command day-rate premiums unavailable in standard construction applications.
- Fleet Management Bundling:The Energy Performance of Buildings Directive's retrofit mandates enable rental operators to package equipment, telematics, and carbon reporting into integrated service contracts.
Industry Challenges
- Certified Technician Scarcity:CE marking under Machinery Directive 2006/42/EC requires documented maintenance protocols that outstrip available trained technician supply in Southern Europe.
- Telematics-Legacy System Integration:Rental operators with heterogeneous equipment vintages face data standardization friction when deploying unified fleet management platforms across acquired depot networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Construction Equipment Rental Market |
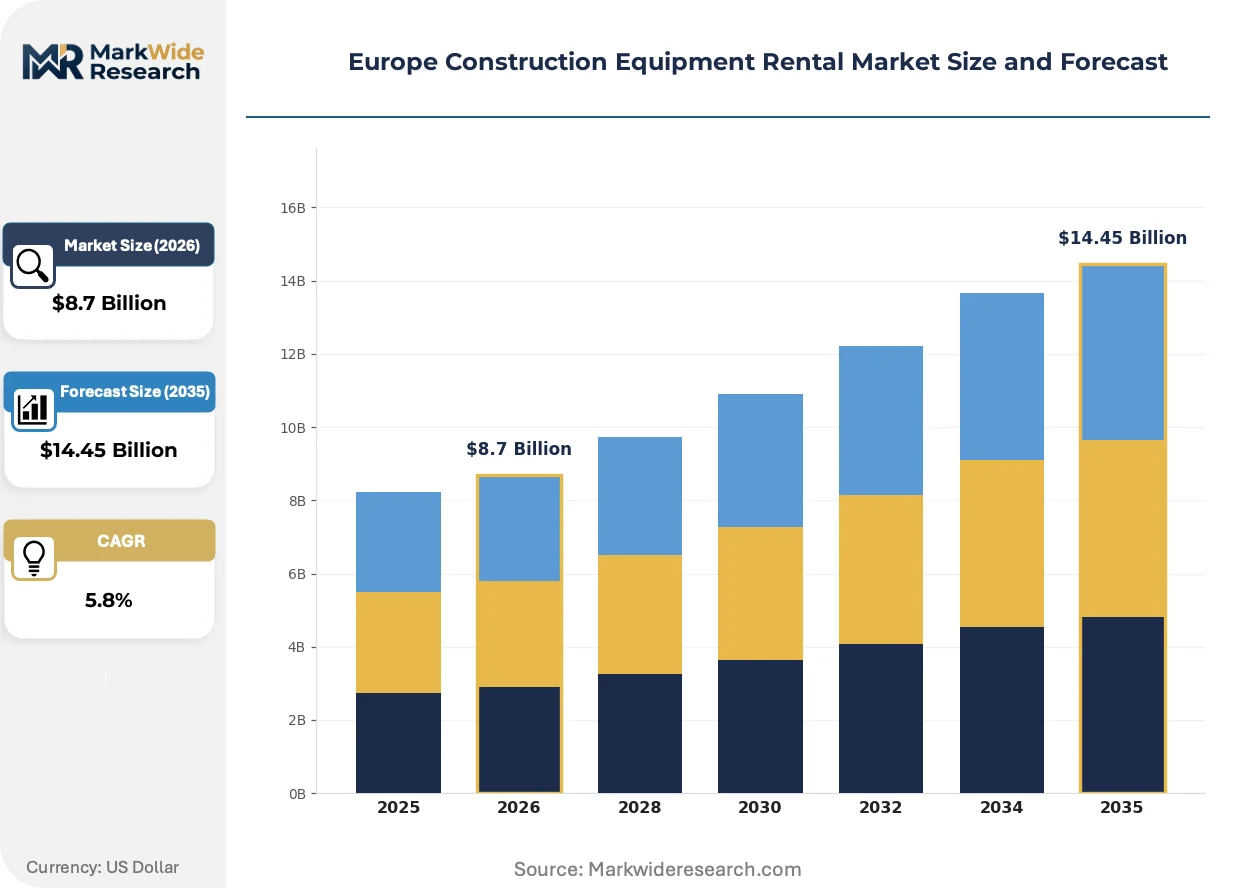
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Excavators, Bulldozers, Aerial Work Platforms, Forklifts End User: Construction Companies, Civil Engineers, Contractors, Private Developers Application: Residential Projects, Commercial Projects, Infrastructure Development, Industrial Projects Deployment Model: On-site Rental, Long-term Leasing, Short-term Rental, Fleet Management |
| Companies Covered | Ashtead Group (Sunbelt Rentals), Cramo (Renta Group), Loxam Group, Liebherr Group, Caterpillar Inc., Boels Rental, Zeppelin Rental, Mateco, Kiloutou Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Construction Equipment Rental Market Trends and Innovations
Electrification and digitalization are converging to transform how rental fleets are deployed, monitored, and priced across European construction markets.
Battery-electric compact excavators and wheel loaders are displacing diesel equivalents in urban cores where city-center access restrictions loom. Municipal contractors in Amsterdam, Copenhagen, and Oslo are specifying zero-emission equipment in tender documents two years ahead of anticipated regulatory mandates. This shift compresses residual value risk for diesel-heavy owned fleets while concentrating premium rental demand around operators with diversified powertrain portfolios.
France's DGCCRF has intensified emissions verification protocols for diesel-powered rental equipment operating within low-emission zones. The enforcement mechanism requires real-time telematics documentation that smaller rental operators cannot provision without third-party platform subscriptions. German and Dutch contractors are now pre-qualifying rental suppliers based on verified emissions traceability, filtering competitive access toward capitalized fleet operators.
Outcome-based contracting is replacing traditional day-rate structures for multi-year infrastructure projects. Contractors in the Nordics and Benelux are negotiating availability guarantees and utilization penalties rather than equipment rental rates alone. This behavioral shift concentrates margin pools with rental houses possessing dense depot networks and predictive maintenance capabilities, compressing returns for asset-heavy, service-light competitors.
Europe Construction Equipment Rental Market Segmentation
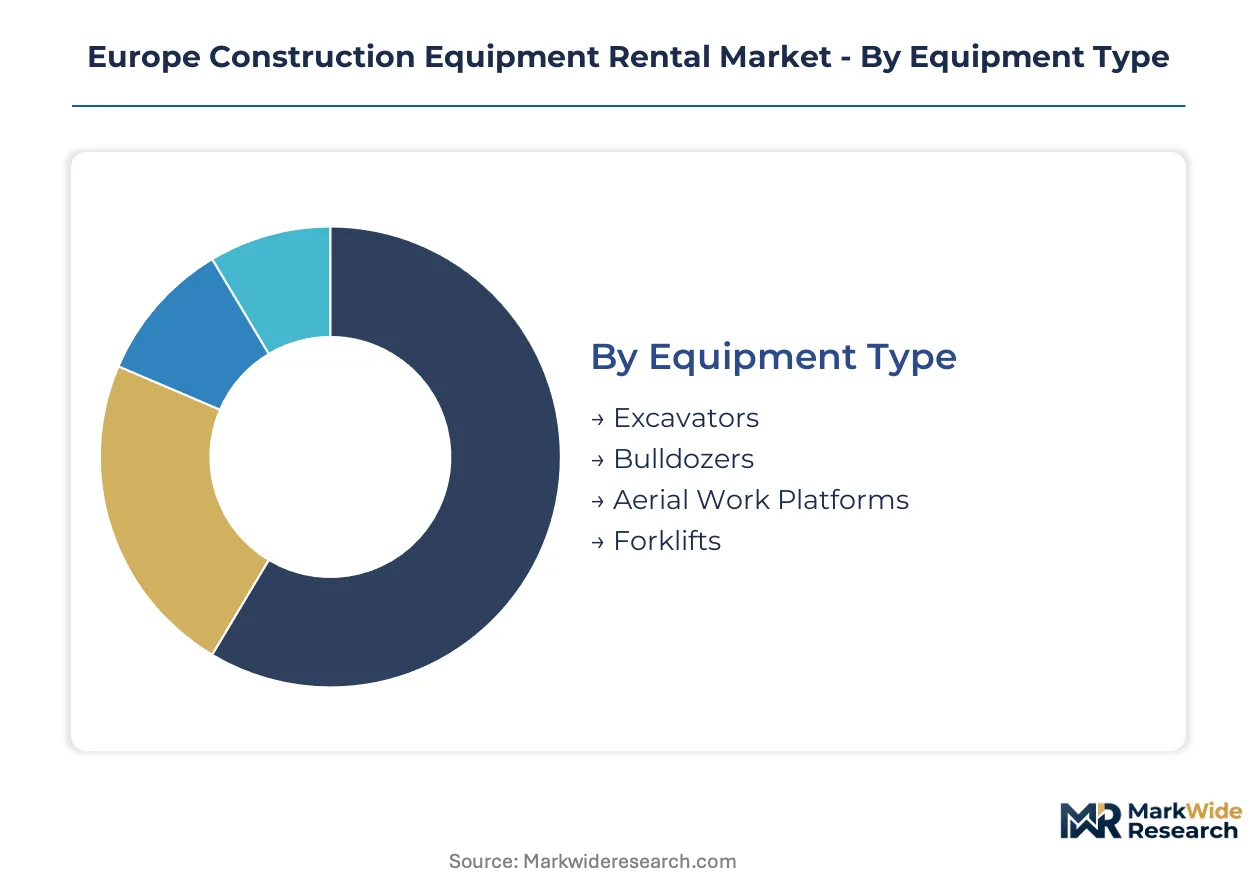
Equipment rental flows through distinct channel configurations depending on contract duration, asset complexity, and customer capital constraints. Segment boundaries are blurring as fleet management bundles reshape traditional rental economics across European construction markets.
Equipment Type:
Channel mix varies sharply by equipment category: earthmoving units move through depot networks with high asset turnover, while aerial platforms concentrate in specialized distributors serving maintenance contractors.
- Excavators:Operating weights from 1.5 to 80 tonnes dominate fleet composition across European rental houses. German infrastructure renewal programs and road maintenance backlogs in France and Italy absorb the highest rental volumes, with Stage V compliance accelerating turnover toward newer diesel and hybrid units.
- Aerial Work Platforms:Working heights extending to 58 metres command premium day-rates in wind turbine maintenance and multi-storey retrofit applications. Urban densification mandates across Paris, Berlin, and Amsterdam are compressing demand toward zero-emission electric models ahead of city-center access restrictions.
- Bulldozers:Heavy earthmoving applications above 40 tonnes face technical limits for battery-electric alternatives, constraining fleet transitions. Rental demand concentrates in civil engineering projects with extended duration contracts.
- Forklifts:Material handling equipment serves industrial and logistics end-uses with shorter rental cycles. Warehouse construction expansion across Poland and the Czech Republic is absorbing counterbalance and reach truck deployments.
By volume, excavators lead. By growth pace, aerial work platforms are climbing the fastest.
End User:
Customer type determines contract structure, with large civil engineers negotiating multi-year fleet management agreements while smaller contractors rely on spot rentals.
- Construction Companies:Full-service general contractors bundle equipment needs across project portfolios, favoring rental partners with pan-European depot density and telematics integration.
- Civil Engineers:Infrastructure specialists in Germany, the Netherlands, and Scandinavia drive demand for heavy earthmoving fleets with documented maintenance traceability under CE marking requirements.
- Contractors:Subcontractor segments exhibit fragmented procurement patterns, often sourcing through regional rental depots without long-term contractual commitments.
- Private Developers:Residential and commercial project sponsors prioritize capital flexibility, accelerating adoption of short-term rental models over equipment ownership.
By contract value, civil engineers dominate. By account expansion velocity, private developers are gaining share fastest.
Application:
Project type shapes equipment specification, with infrastructure mandates demanding heavy earthmoving fleets and urban retrofits concentrating aerial platform deployments.
- Infrastructure Development:Road, rail, and utility projects consume the largest equipment tonnages. EU cohesion fund allocations for Eastern European rail renewal are redirecting fleet capacity toward Poland and Romania.
- Commercial Projects:Office and retail construction drives demand for mid-range excavators and material handling equipment, with sustainability certifications influencing electric equipment specifications.
- Residential Projects:Housing construction exhibits cyclical demand patterns, with compact equipment favored for confined urban sites.
- Industrial Projects:Manufacturing facility construction and maintenance require specialized heavy-lift and precision placement equipment with certified operator provisions.
By fleet deployment, infrastructure development leads. By margin per machine-hour, commercial projects are expanding most quickly.
Deployment Model:
Service intensity separates deployment tiers, with pure rental competing against integrated fleet management for multi-year contract capture.
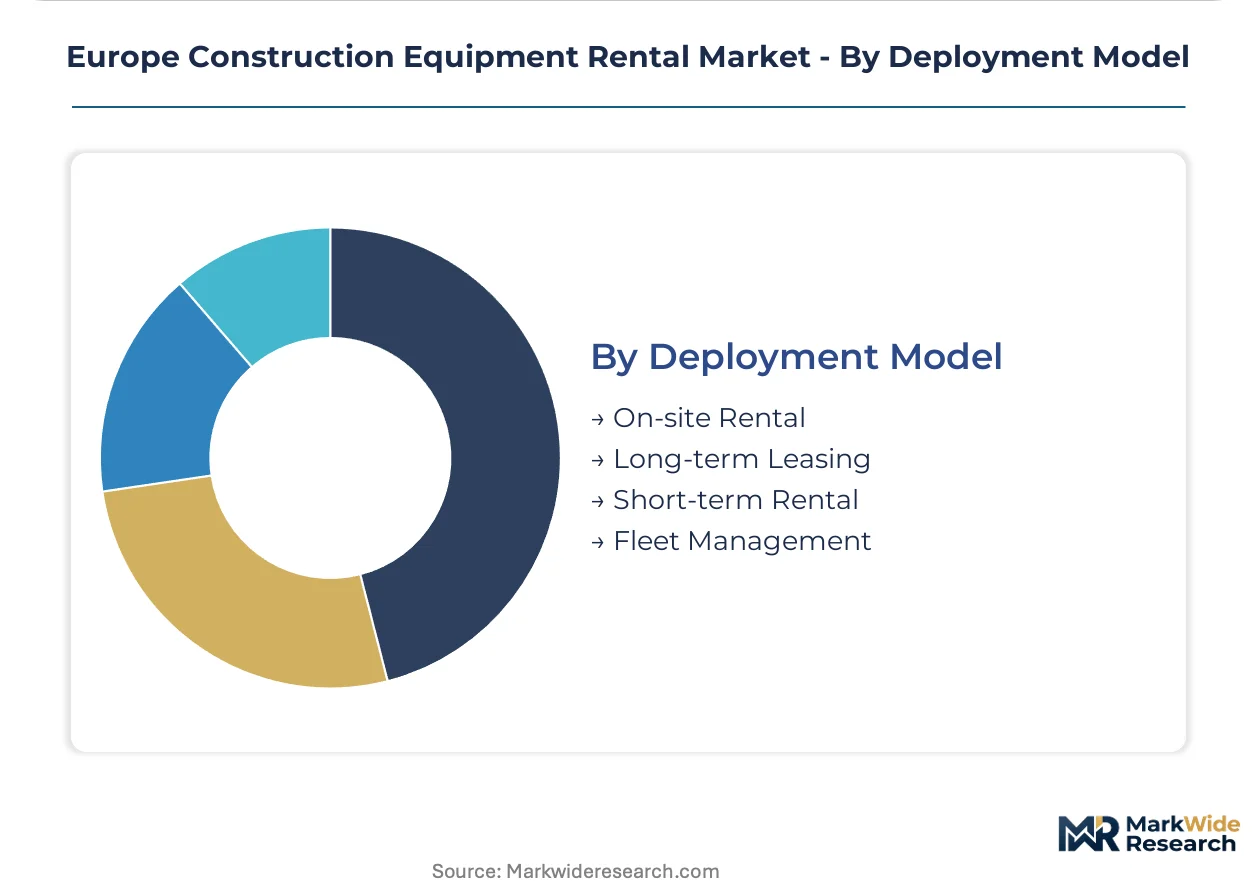
- Fleet Management:Bundled telematics, predictive maintenance, and operator certification command premium pricing in multi-year infrastructure contracts. Nordic and Benelux contractors are negotiating availability guarantees rather than day-rates alone.
- Long-term Leasing:Extended duration contracts with maintenance inclusion appeal to civil engineers with predictable project pipelines, transferring residual value risk to rental operators.
- Short-term Rental:Spot market demand serves project peaks and emergency replacements, with pricing transparency compressing margins for undifferentiated depot operators.
- On-site Rental:Dedicated equipment pools at large construction sites reduce logistics costs for extended-duration projects, common in German and French infrastructure megaprojects.
By revenue concentration, fleet management leads. By contract growth rate, long-term leasing is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Civil engineers in Germany, the Netherlands, and Scandinavia command the largest equipment rental commitments, while urban densification mandates across Paris, Berlin, and Amsterdam accelerate aerial platform demand.
Germany
The KBA enforces Stage V diesel retrofit deadlines that accelerate fleet turnover toward cleaner rental equipment. Infrastructure renewal programs and road maintenance backlogs absorb record volumes of earthmoving machinery. Munich and Stuttgart host manufacturing clusters where rental operators source rapid replacement availability for excavators above 40 tonnes.
France
The DGCCRF intensifies emissions verification protocols for diesel-powered equipment within low-emission zones. Multi-storey retrofit mandates across Paris drive demand for zero-emission aerial work platforms. Civil engineering contractors in the Île-de-France region negotiate availability guarantees rather than traditional day-rate structures.
United Kingdom
Fall-protection enforcement tightens on confined construction sites, compressing demand toward electric aerial platforms. The Health and Safety Executive mandates documented maintenance traceability under CE marking requirements. London's urban densification projects consume premium rental volumes for compact excavators and high-reach equipment.
Netherlands
Municipal contractors in Amsterdam specify zero-emission equipment in tender documents ahead of anticipated city-center access restrictions. Outcome-based contracting replaces traditional day-rate structures for multi-year infrastructure projects. Rotterdam's port expansion and flood defense megaprojects anchor heavy earthmoving rental demand.
Poland
EU cohesion fund allocations for road and rail renewal create underpenetrated demand for excavator and compactor rental fleets. Warehouse construction expansion across Warsaw and Łódź absorbs counterbalance and reach truck deployments. Eastern European contractors lack the capital intensity for equipment ownership, accelerating rental model adoption.
Europe Construction Equipment Rental Market Competitive Landscape
Player mix skews toward pan-European depot networks with telematics integration capabilities. Consolidation pressures squeeze mid-tier operators lacking centralized procurement scale for REACH-compliant hydraulic fluids. Three archetypes dominate: capitalized fleet operators with diversified powertrain portfolios, specialized high-reach aerial platform providers, and integrated fleet management bundlers. Competitive moves concentrate on depot network densification and predictive maintenance capability acquisition.
Within the pan-European network tier, Loxam Group and Boels Rental exemplify operators leveraging geographic scale for same-day availability guarantees. Zeppelin Rental occupies a position emphasizing integrated telematics fleets that compete on utilization transparency. These three entities represent distinct strategic postures—depot density, specialized aerial access, and digital fleet management—without which rental operators face margin compression from undifferentiated spot-market competition.
| Leading Market Players |
|---|
| Ashtead Group (Sunbelt Rentals) |
| Cramo (Renta Group) |
| Loxam Group |
| Liebherr Group |
| Caterpillar Inc. |
| Boels Rental |
| Zeppelin Rental |
| Mateco |
| Kiloutou Group |
| Others |
Pricing and Supply Chain Analysis
Asset utilization rates above 75% in German rental fleets create scale economies that compress per-unit maintenance costs and establish price floors mid-tier operators cannot match. This concentration of efficient capacity around Munich and Stuttgart manufacturing clusters simultaneously anchors supply availability and pricing power for earthmoving equipment across Northern Europe.
Pricing Analysis
Cost-plus contracts with steel and diesel indexation dominate multi-year infrastructure agreements, insulating rental operators from input volatility while transferring utilization risk to contractors. Price differentiation hinges on CE marking tier and telematics integration depth, with certified fleet operators commanding 15-20% premiums over undifferentiated depot competitors. Pricing pressure stems from spot-market transparency in short-term rentals, where digital platforms compress margins for asset-heavy, service-light operators. Civil engineers exhibit lowest price sensitivity due to availability guarantee requirements, while subcontractor segments drive aggressive rate competition.
Supply Chain Analysis
Germany and Italy anchor hydraulic system and diesel engine production for rental fleet manufacturers, with component sourcing concentrated around Munich, Stuttgart, and Bologna industrial corridors. Supply chains draw from forged steel structures, high-pressure hydraulics, and Tier IV/Stage V emission control modules. Single-source vulnerability concentrates in electronic control unit suppliers serving telematics-integrated fleets. Distribution runs through owned depot networks for pan-European operators, while regional players rely on third-party logistics for equipment repositioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment rental penetration in Eastern European construction markets sits at roughly half Western European levels, creating an early-cycle expansion opportunity as EU cohesion fund deployment accelerates infrastructure project pipelines.
For Market Incumbents: Consolidate depot networks in Poland and Romania ahead of cohesion fund disbursement, acquiring regional operators with established contractor relationships. CE marking compliance investments filter out mid-tier competitors lacking documented maintenance protocols. Backward integration into predictive maintenance software development protects margin pools as outcome-based contracting displaces day-rate structures.
For New Entrants and Emerging Players: Lead with battery-electric compact equipment portfolios targeting Amsterdam, Copenhagen, and Oslo municipal tenders two years ahead of anticipated zero-emission mandates. Poland's warehouse construction boom offers underpenetrated demand for material handling rentals outside established Western European markets. Partner with telematics platform providers rather than building proprietary systems to accelerate market entry.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fleet management bundlers with multi-year infrastructure contracts, positioning these operators for premium valuations versus asset-heavy spot-market competitors. Acquisition targets should display dense depot networks in Germany and the Netherlands plus diversified powertrain portfolios. Watch Stage V retrofit deadline enforcement intensity as the signal for accelerated fleet turnover and rental model adoption inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Depot Network Densification | Same-day availability guarantees in urban corridors capture premium pricing from civil engineers. |
| Battery-Electric Fleet Transition | Zero-emission equipment positions operators for Amsterdam and Oslo municipal tender requirements. |
| Predictive Maintenance Integration | Telematics-enabled utilization tracking supports outcome-based contracting with availability penalties. |
| CE Marking Compliance Investment | Documented safety traceability filters competitive access under Machinery Directive enforcement. |
| Eastern European Geographic Expansion | Poland infrastructure pipelines offer underpenetrated demand outside saturated Western markets. |
Research Methodology
The analysis maps earthmoving equipment, aerial work platforms, and fleet management services, each validated through rental operations directors, civil engineering procurement leads, and depot network managers. Primary interviews with maintenance certification officers and telematics platform engineers combined with secondary validation from EU customs data, KBA emission registration databases, and infrastructure project pipeline disclosures. Bottom-up equipment deployment estimates triangulate against top-down construction sector value-add figures.
Consistency checks against EU construction equipment import volumes and rental fleet utilization surveys validated projection outputs across the modeling period. Segmentation dimensions include equipment operating weight tier, powertrain architecture, contract duration structure, and regional regulatory cluster. CAGRs derive from equipment replacement cycle analysis and penetration rate trajectories, with Stage V compliance deadlines and urban densification mandates serving as key forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained EU cohesion fund allocation or accelerated battery-electric technology cost reduction would require recalibration. Forecasts reflect assumptions regarding emission regulation enforcement intensity and contractor capital constraint persistence. Recalibration cycles align with material shifts in Stage V retrofit deadlines and municipal zero-emission equipment mandates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Ultrasonic Welding Machine Market
Construction Equipment
Mill Pulverizer Market
Construction Equipment
Extrusion Equipment Market
Construction Equipment
Autonomous Cranes Market
Construction Equipment
Earthmoving Equipment Tyres Market
Construction Equipment
Laser Welding Equipment Market
Construction Equipment
Excavator Wheels Market
Construction Equipment
Heavy Duty IBC Market
Construction Equipment
Saudi Arabia Completion Equipment and Services Market
Construction Equipment
Hydraulic Packers Market
Construction Equipment
Vietnam Crane Market
Construction Equipment
Drone-Based Solutions in Construction Market
Construction Equipment
Road Roller Market
Construction Equipment
Roadheaders Market
Construction Equipment
Crane Aftermarket Market
Construction Equipment
Laser Beam Welding Equipment Market