
 Civil Engineering Market | 2026-2036
Civil Engineering Market Size, Share, and Industry Trends Forecast 2026-2036
Civil Engineering Market Intelligence
Modular project delivery is consolidating buyer preference across large-scale infrastructure programs. Fluor Corporation leverages integrated engineering-procurement-construction frameworks to capture complex energy and industrial contracts. AECOM sustains geographic dominance in transportation systems through its multi-continental design-build footprint. Bechtel Corporation anchors its competitive position with specialized capabilities in dam engineering and heavy civil structures.
Civil engineering encompasses the planning, design, construction, and maintenance of physical infrastructure including load-bearing structures with specified compressive strengths, drainage gradients, and seismic resilience ratings. Its primary purpose is to create durable public and private works that support economic activity, population mobility, and environmental protection. Bridge construction commands substantial capital allocation across government agency portfolios, while tunnel excavation exhibits accelerated growth in mountainous and densely urbanized terrains where surface expansion faces constraints. Building Information Modeling technology concentrates margin pools through reduced rework rates and accelerated project timelines.
FERC regulates hydroelectric dam safety and interstate waterway standards in the United States, directly shaping demand for specialized dam engineering services. EMA and national building codes across Europe enforce stricter material certification and lifecycle carbon thresholds, altering procurement criteria for construction firms and engineering consultants. Stakeholders must monitor how evolving climate adaptation mandates reshape project feasibility assessments and long-term infrastructure asset valuations.
Market Dynamics
Building Information Modeling technology is compressing project timelines and reducing rework rates across transportation and energy infrastructure programs. Government procurement offices now mandate digital twin deliverables for contracts above threshold values, forcing engineering firms to restructure technical workflows and staff competencies.
Growth Catalysts
- Seismic code upgrades:FERC and national building authorities in Japan enforce stricter dam and bridge resilience standards, expanding specialized engineering service contracts.
- India-China corridor investments:Cross-border freight initiatives accelerate tunnel excavation demand through Himalayan terrain where surface expansion faces physical constraints.
- Modular construction methods:Integrated design-build frameworks reduce capital risk for public agencies financing large-scale transportation systems.
Market Restraints
- Steel and cement price volatility:Raw material input costs swing with energy market fluctuations, compressing fixed-price contract margins for heavy civil contractors.
- Specialized equipment supply concentration:Tunnel boring machine manufacturing clusters in Germany and Japan create procurement bottlenecks for projects in South Asia.
- Lifecycle carbon thresholds:EU Green Deal compliance requirements extend project feasibility study durations and increase upfront certification costs.
Strategic Opportunities
- Resilient infrastructure mandates:Climate adaptation requirements in coastal US states and Southeast Asian megacities open design-build contracts for flood-resistant transportation systems.
- Digital twin convergence:Integration of IoT sensors with BIM platforms enables predictive maintenance service revenue streams for bridge and tunnel operators.
- Public-private partnership channels:Availability-based payment structures for toll roads and water treatment facilities shift risk allocation and attract institutional capital.
Industry Challenges
- Geotechnical specialist scarcity:Qualified tunnel engineers and dam safety experts command premium compensation, inflating project labor cost structures.
- Multi-stakeholder coordination complexity:Federal, state, and municipal permitting timelines for interstate waterway projects extend construction windows by 18-36 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Civil Engineering Market |
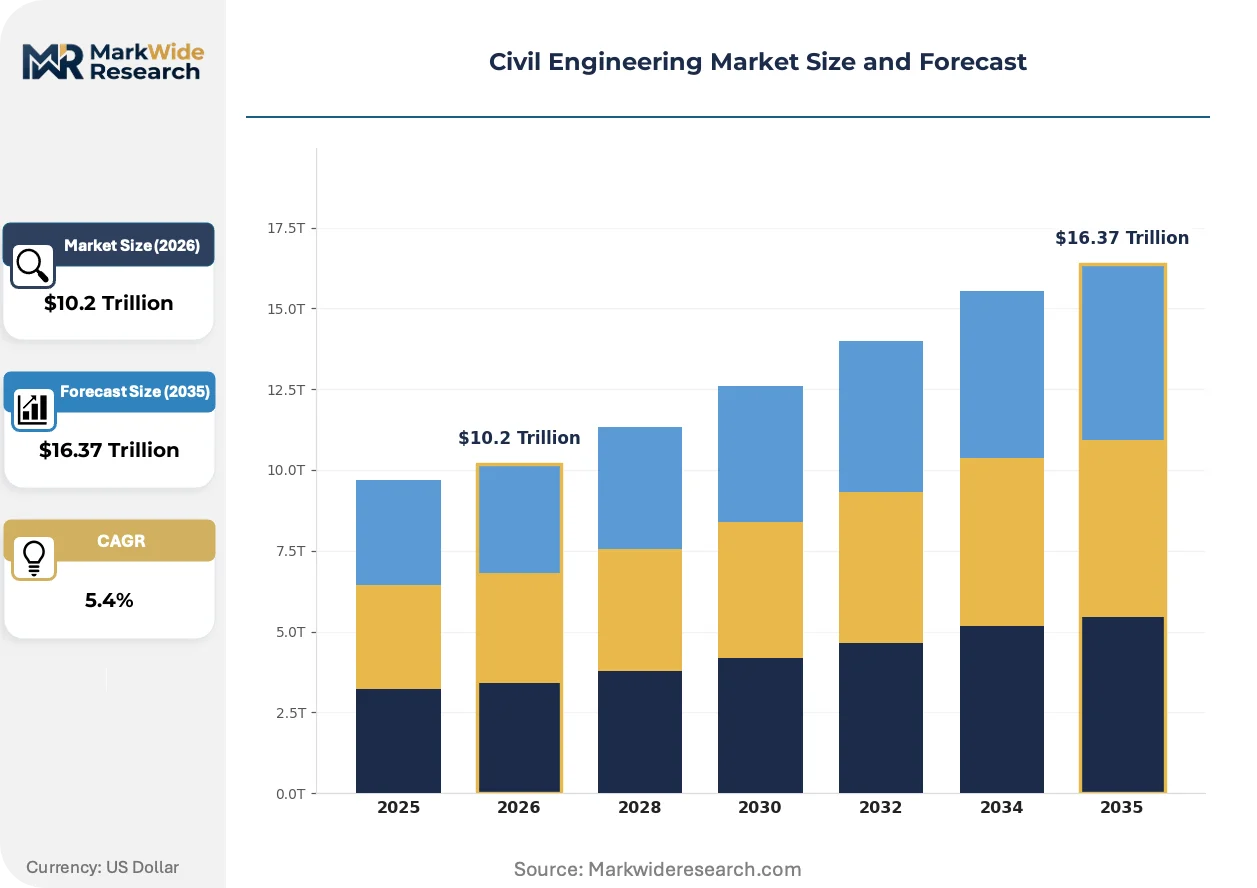
| Market Size in 2026 | $10.2 Trillion |
| Market Size in 2035 | $16.37 Trillion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Bridge Construction, Tunnel Excavation, Road Development, Dam Engineering, Airport Infrastructure Technology: Building Information Modeling, Geotechnical Software, Structural Analysis Tools, Earthquake Simulation, Hydraulic Modeling Application: Urban Planning, Environmental Management, Water Resources, Transportation Systems, Land Development Client Type: Government Agencies, Private Developers, Engineering Consultants, Construction Firms, Non-Governmental Organizations |
| Companies Covered | Turner Construction Company, Fluor Corporation, Quanta Services, Inc., Jacobs Engineering Group, AECOM, EMCOR Group, Inc., Kiewit Corporation, Clark Construction Group, Bechtel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Civil Engineering Market Strategic Shifts & Innovations
Digital fabrication and autonomous construction equipment are compressing field labor requirements while elevating precision standards for load-bearing structures. These shifts demand simultaneous investment in software platforms and workforce retraining.
Prefabricated bridge components with embedded fiber-optic monitoring systems are consolidating quality control processes for transportation agencies. State departments of transportation in California and Texas specify these elements for seismic corridor upgrades. The technology compresses on-site assembly time and reduces traffic disruption duration.
REACH substance restrictions and the EU Green Deal carbon border adjustments are altering material procurement criteria for European infrastructure projects. Contractors now source low-clinker cement and recycled steel aggregates to maintain eligibility for public tenders. German and Dutch port authorities enforce these standards for maritime civil works.
Performance-based maintenance contracts are displacing traditional lump-sum construction awards for bridge and tunnel assets. Australian state infrastructure agencies and Canadian provincial ministries now procure 25-30 year operational commitments from design-build consortia. This model transfers deterioration risk to contractors and aligns long-term asset condition with payment schedules.
Civil Engineering Market Segmentation
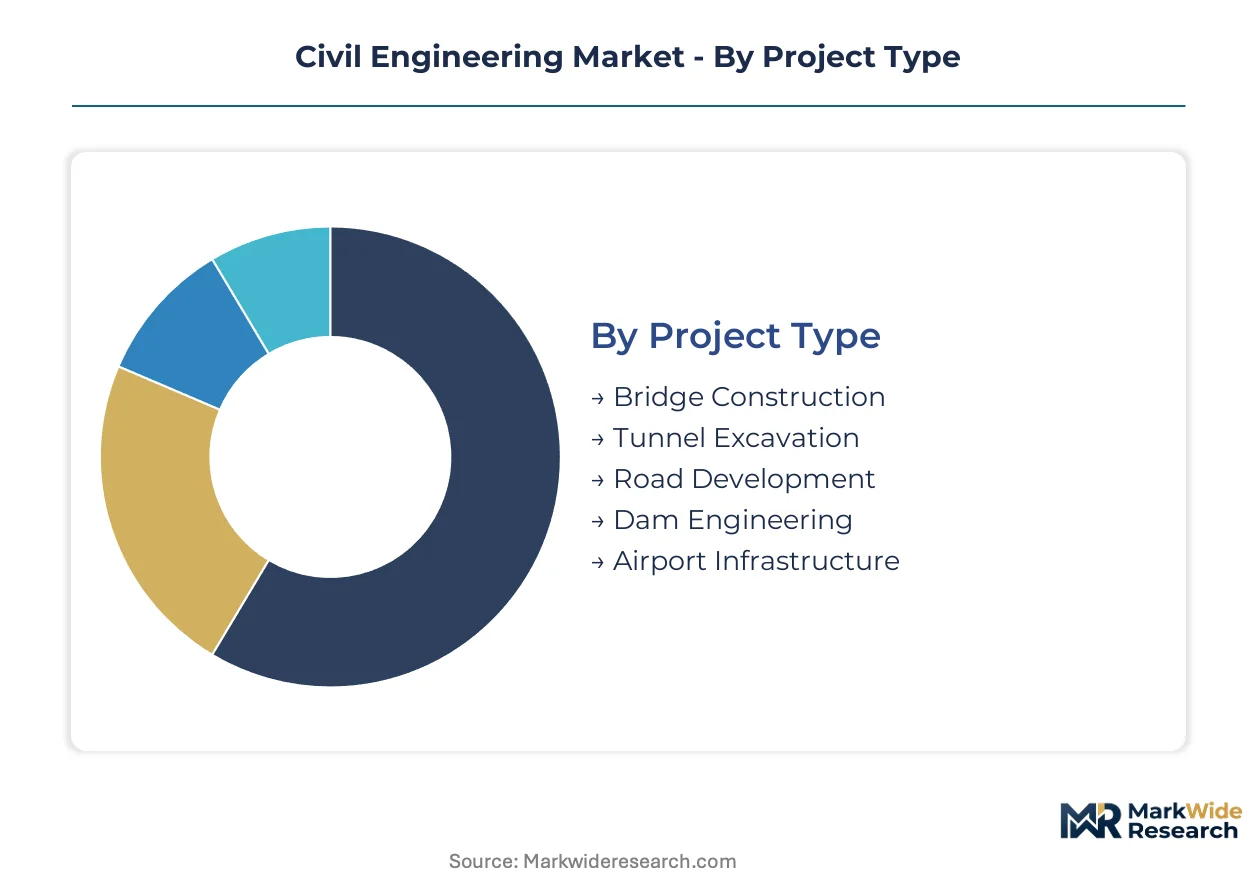
Civil engineering markets fragment across project scale, technical complexity, and regulatory exposure. Segment selection determines contractor qualification requirements, technology procurement budgets, and risk allocation structures for infrastructure owners.
Project Type:
FERC mandates specialized dam safety certifications for hydroelectric structures, while state DOTs enforce bridge inspection protocols that shape contractor eligibility tiers across project categories.
- Bridge Construction:Load-bearing structures with specified compressive strengths and seismic resilience ratings. Demand concentrates in California and Texas where state transportation departments specify prefabricated components with embedded fiber-optic monitoring for seismic corridor upgrades.
- Tunnel Excavation:Underground infrastructure through mountainous and densely urbanized terrains. Himalayan cross-border freight corridors in India and China accelerate procurement where surface expansion faces physical constraints and geotechnical complexity inflates specialist compensation.
- Road Development:Highway and arterial networks with drainage gradient specifications. Municipal agencies in rapidly urbanizing Southeast Asian megacities dominate procurement volumes.
- Dam Engineering:Hydroelectric and water retention structures requiring FERC safety compliance. Specialized design-build consortia capture contracts through technical prequalification barriers.
- Airport Infrastructure:Runway systems and terminal foundations with heavy load-bearing requirements. Federal aviation authorities in the United States and civil aviation regulators in India enforce pavement strength certification protocols.
Leading the category by volume: Road Development. Expanding most quickly: Tunnel Excavation.
Technology:
Software procurement decisions hinge on interoperability with government digital twin mandates and lifecycle carbon tracking requirements.
- Building Information Modeling:Integrated 3D modeling platforms compressing project timelines and reducing rework rates. Government procurement offices in Germany and the United States now mandate BIM deliverables for contracts above threshold values, forcing engineering firms to restructure technical workflows.
- Geotechnical Software:Subsurface analysis tools for foundation and tunnel design. Specialist scarcity in qualified tunnel engineers drives premium licensing demand across South Asian infrastructure programs.
- Structural Analysis Tools:Load simulation and material stress modeling systems. Bridge engineering consultants in Japan and California deploy these for seismic code compliance verification.
- Earthquake Simulation:Dynamic response modeling for seismic resilience rating. Japan's METI and California's state building codes enforce stricter analytical requirements for critical infrastructure.
- Hydraulic Modeling:Water flow and flood prediction systems for drainage and dam design. Dutch and German port authorities specify these for maritime civil works under EU Green Deal carbon thresholds.
Category revenue concentrates in BIM platforms. Steepest expansion trajectory: Earthquake Simulation.
Application:
End-use segmentation determines regulatory jurisdiction and funding mechanism availability across infrastructure asset classes.
- Urban Planning:Integrated land use and transportation system design. Megacity authorities in India and Southeast Asia allocate capital for resilient infrastructure amid climate adaptation mandates.
- Environmental Management:Erosion control and ecological restoration engineering. EU Green Deal compliance requirements extend project feasibility study durations and increase upfront certification costs for European contractors.
- Water Resources:Treatment facilities and distribution network construction. Australian state infrastructure agencies and Canadian provincial ministries procure 25-30 year operational commitments through performance-based maintenance contracts.
- Transportation Systems:Multimodal freight and passenger corridors. Public-private partnership availability-based payment structures for toll roads shift risk allocation and attract institutional capital.
- Land Development:Site preparation and foundation engineering for commercial and residential construction. Private developers in Texas and Florida drive demand amid population mobility patterns.
Transportation Systems dominates capital allocation. Fastest-gaining share: Water Resources.
Client Type:
Procurement sophistication varies sharply across buyer categories, with government agencies mandating digital deliverables while private developers prioritize speed-to-market.
- Government Agencies:Federal, state, and municipal infrastructure owners with multi-stakeholder coordination complexity. FERC and national building authorities enforce specialized engineering service contracts through prequalification standards.
- Private Developers:Commercial and residential project sponsors with compressed decision timelines. Risk tolerance for fixed-price contracts compresses when steel and cement price volatility escalates.
- Engineering Consultants:Technical advisory firms structuring integrated design-build frameworks. Fluor Corporation and AECOM capture complex contracts through multi-continental footprint advantages.
- Construction Firms:Heavy civil contractors executing field operations. Equipment supply concentration in Germany and Japan creates procurement bottlenecks for tunnel boring machine deployment.
- Non-Governmental Organizations:Development finance and humanitarian infrastructure sponsors. Climate adaptation requirements in coastal US states and Southeast Asian megacities open design-build contract access.
Government Agencies anchor procurement volume. Climbing the fastest: Engineering Consultants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes the largest share of cement and steel for infrastructure while Germany and Japan manufacture the specialized tunnel boring equipment that South Asian projects require. This production-consumption divide shapes procurement timelines and cost structures across major civil engineering programs.
United States
State transportation departments in California and Texas drive prefabricated bridge component procurement for seismic corridor upgrades. FERC enforces specialized dam safety certifications that filter contractor eligibility for hydroelectric structures. The Pacific Northwest and Gulf Coast concentrate water resource infrastructure investment under climate adaptation mandates.
China
Cross-border freight corridors through Himalayan terrain accelerate tunnel excavation demand where surface expansion faces physical constraints. National building authorities enforce stricter seismic resilience standards for critical infrastructure. The Yangtze River Delta and Pearl River Delta anchor high-speed rail and urban transit construction volumes.
India
Municipal agencies in rapidly urbanizing megacities dominate road development procurement with drainage gradient specifications. The Central Electricity Authority and Bureau of Indian Standards shape material certification requirements for public tenders. Maharashtra and Gujarat concentrate design-build consortia executing performance-based maintenance contracts.
Germany
Dutch and German port authorities specify low-clinker cement and recycled steel aggregates for maritime civil works under EU Green Deal carbon thresholds. ECHA REACH substance restrictions alter material procurement criteria for European infrastructure projects. The Ruhr industrial region and Bavarian engineering clusters supply tunnel boring machine manufacturing capacity.
Japan
METI enforces stricter analytical requirements for earthquake simulation in critical infrastructure design. Specialist scarcity in qualified tunnel engineers drives premium licensing demand for geotechnical software platforms. The Kanto region around Tokyo and Kansai region around Osaka concentrate seismic resilience engineering services.
Civil Engineering Market Key Industry Players
The competitive structure tilts toward integrated design-build consortia with multi-continental footprints. Engineering-procurement-construction frameworks dominate large-scale transportation and energy contracts. Three archetypes occupy distinct positions: full-service conglomerates with government agency relationships, specialized dam and tunnel engineering boutiques, and regional construction firms with equipment-heavy execution capabilities. Consolidation through strategic partnerships and technology licensing agreements defines current competitive moves.
Among North American-based integrated service providers, Fluor Corporation and AECOM exemplify the multi-continental footprint archetype that captures complex contracts through geographic coverage advantages. Bechtel Corporation occupies a position within the specialized heavy civil structures tier, anchoring competitive positioning through technical prequalification in dam engineering. These three entities represent how scale and specialization vectors segment opportunity capture across government procurement channels.
| Leading Market Players |
|---|
| Turner Construction Company |
| Fluor Corporation |
| Quanta Services, Inc. |
| Jacobs Engineering Group |
| AECOM |
| EMCOR Group, Inc. |
| Kiewit Corporation |
| Clark Construction Group |
| Bechtel Corporation |
| Others |
Cost & Logistics Intelligence
Qualified tunnel engineers concentrated in Germany and Japan command premium compensation that widens pricing-tier spreads between standard design-build contracts and specialized geotechnical services, with labor-cost differentials across Himalayan corridor projects in India and China forcing procurement officers to tier contractor eligibility by technical certification grade.
Pricing Analysis
Margin tightening in fixed-price heavy civil contracts reflects steel and cement price volatility tied to energy market fluctuations, compressing returns for contractors unable to pass input cost swings to government agency clients. Three-tier pricing structure across premium certified, standard prequalified, and economy tiered bid levels separates FERC-compliant dam engineering from state DOT bridge maintenance and municipal road development. Price differentiation traces to seismic code certification grade and BIM deliverable sophistication. Steel-reinforced concrete contractors face acute cost-down pressure as raw material indices swing. Government agencies exhibit lowest price sensitivity given availability-based payment structures, while private developers in Texas and Florida show highest sensitivity to fixed-price risk.
Supply Chain Analysis
Specialist manufacturing labor availability in Germany and Japan anchors tunnel boring machine production, constraining equipment deployment timelines for South Asian infrastructure programs. Supply concentrates in these two precision-engineering hubs, with China consuming dominant shares of cement and steel inputs. Raw material dependencies rest on clinker for low-carbon cement formulations, high-grade steel plate for bridge girders, and polymer composites for embedded fiber-optic monitoring systems. Single-source vulnerability clusters around German-Japanese TBM manufacturing duopoly. Distribution runs through design-build consortia integrating engineering-procurement-construction frameworks for government agency clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Building Information Modeling platforms are displacing legacy CAD workflows across transportation and water resource infrastructure programs, compressing project timelines and restructuring contractor technical competencies.
For Market Incumbents: Deepen vertical integration into prefabricated component manufacturing to capture margin pools from embedded sensor technologies specified by California and Texas state DOTs for seismic corridor upgrades. Anchor position through FERC dam safety certification maintenance as specialized engineering service contracts expand. Defend against modular construction entrants by controlling design-build consortium formation channels.
For New Entrants and Emerging Players: EU Green Deal carbon border adjustments in Europe open a window for low-clinker cement and recycled steel aggregate sourcing specialists to penetrate German and Dutch port authority procurement. Target water resources performance-based maintenance contracts in Australia and Canada where 25-30 year operational commitments transfer deterioration risk and attract institutional capital. Enter through BIM-IoT predictive maintenance service bundling for bridge and tunnel operators.
For Investors and Strategic Acquirers: Re-rating potential sits with geotechnical software platforms given earthquake simulation demand acceleration under Japan METI and California seismic code upgrades. Long-term viability favors specialized dam and tunnel engineering boutiques with FERC prequalification and Himalayan corridor project experience. Watch digital twin mandate adoption velocity across government procurement offices as inflection indicator for BIM platform valuation expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Prefabricated Components | Captures embedded fiber-optic monitoring margins specified by California DOT seismic upgrades. |
| BIM-IoT Platform Convergence | Enables predictive maintenance revenue streams for bridge operators under digital twin mandates. |
| Low-Carbon Material Certification Investment | Secures EU Green Deal eligibility for German and Dutch port authority maritime civil works. |
| Performance-Based Maintenance Contracting | Aligns 25-30 year asset condition with payment schedules for Australian state infrastructure agencies. |
| Geotechnical Specialist Workforce Development | Addresses qualified tunnel engineer scarcity inflating Himalayan corridor project labor costs. |
Research Approach
Multi-period observation of cement and steel input cost indices, government procurement contract awards, and seismic code adoption timelines anchored the trend analysis, supplemented by interviews with infrastructure program directors at state transportation departments, FERC compliance officers, design-build consortium project managers, geotechnical engineering consultants, and BIM platform implementation leads. Secondary validation drew from FERC dam safety filings, state DOT capital improvement programs, EU ECHA REACH substance restriction updates, and Bureau of Indian Standards material certification protocols. Bottom-up project pipeline assessment and top-down macro infrastructure spending analysis provided triangulation.
Segment-weighting across project type, technology platform, application end-use, and client procurement sophistication shaped the analytical framework across the projection horizon. Modeled dimensions included bridge construction, tunnel excavation, road development, dam engineering, and airport infrastructure categories crossed with BIM, geotechnical software, structural analysis, earthquake simulation, and hydraulic modeling technology tiers. CAGRs derived from elasticity-adjusted infrastructure investment flows and technology adoption S-curves. Industry-specific inputs incorporated FERC regulatory compliance cost structures and EU Green Deal carbon threshold implementation schedules.
The model assumes a particular BIM adoption path; alternative pathways for digital twin convergence with IoT sensor networks would alter the outlook for predictive maintenance service revenue projections. Forecasts reflect assumptions regarding seismic code upgrade enforcement consistency and raw material price stabilization. Material deviation in government digital mandate adoption velocity or tunnel boring machine manufacturing capacity expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Structural Engineering
Global Concrete Restoration Market
Structural Engineering
North America Facade Market
Structural Engineering
Geotechnical Engineering Market
Structural Engineering
Europe Facade Market
Structural Engineering
Metal Structural Insulation Panels Market
Structural Engineering
Concrete Wind Tower Market
Structural Engineering
Fluid Viscous Dampers Market
Structural Engineering
Bridge Expansion Joint Market
Structural Engineering
Prestressed High Strength Concrete Pipe Pile Market
Structural Engineering
Europe Bridge Bearings Market
Structural Engineering
UK Facade Market
Structural Engineering
Asia-Pacific Structural Health Monitoring Market
Structural Engineering
Southeast Asia Anchors and Grouts Market
Structural Engineering
Self-Levelling Concrete Market
Structural Engineering
Structural Lightweight Concrete Market
Structural Engineering
Self-Healing Concrete Market