
 Plastic Fencing Market | 2026-2036
Plastic Fencing Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Fencing Market Analysis
The EU Green Deal is realigning material sourcing requirements across European fencing supply chains, pushing converters toward recycled PVC and bio-based feedstocks. Pexco leverages its extrusion scale to serve utility and highway barrier contracts across North America. CertainTeed anchors its position through building-products distribution integration with major home improvement retailers.
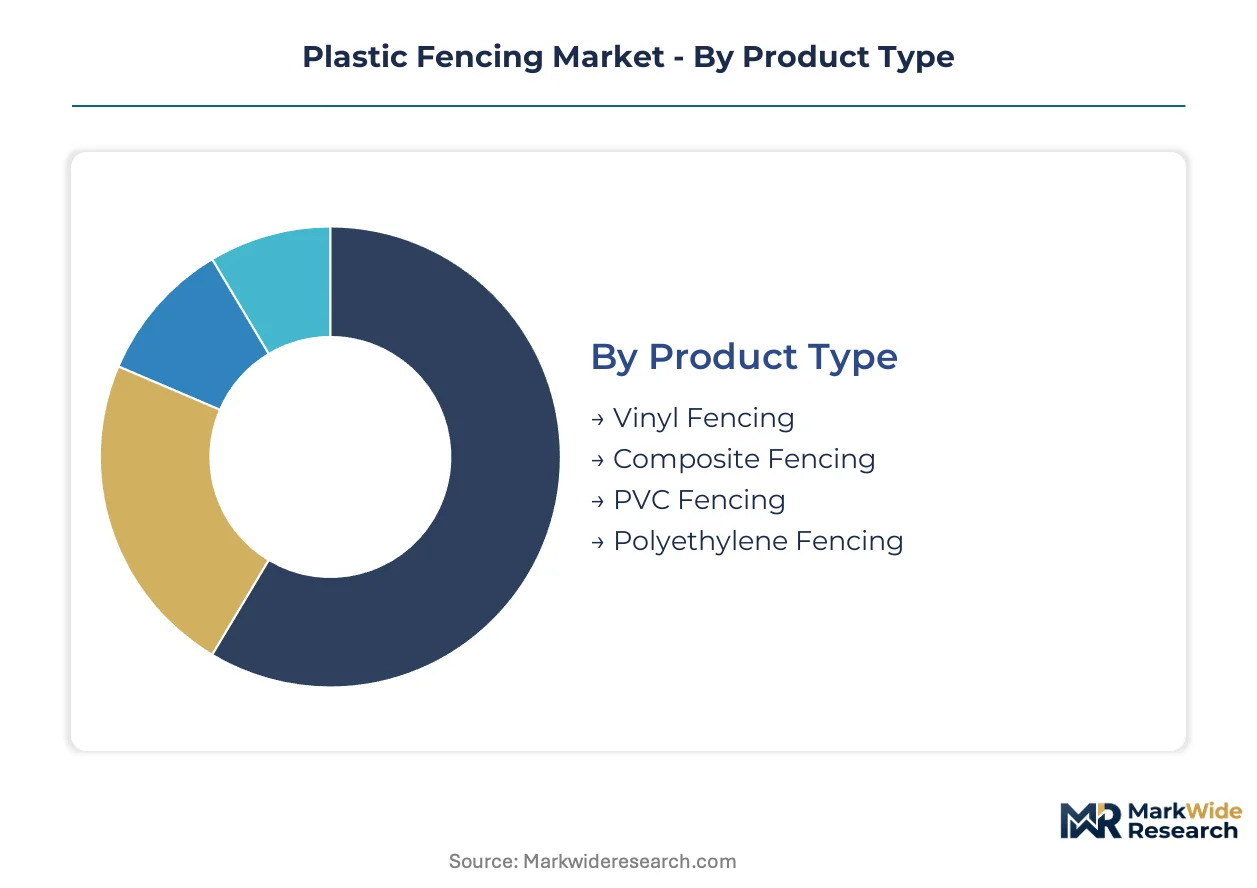
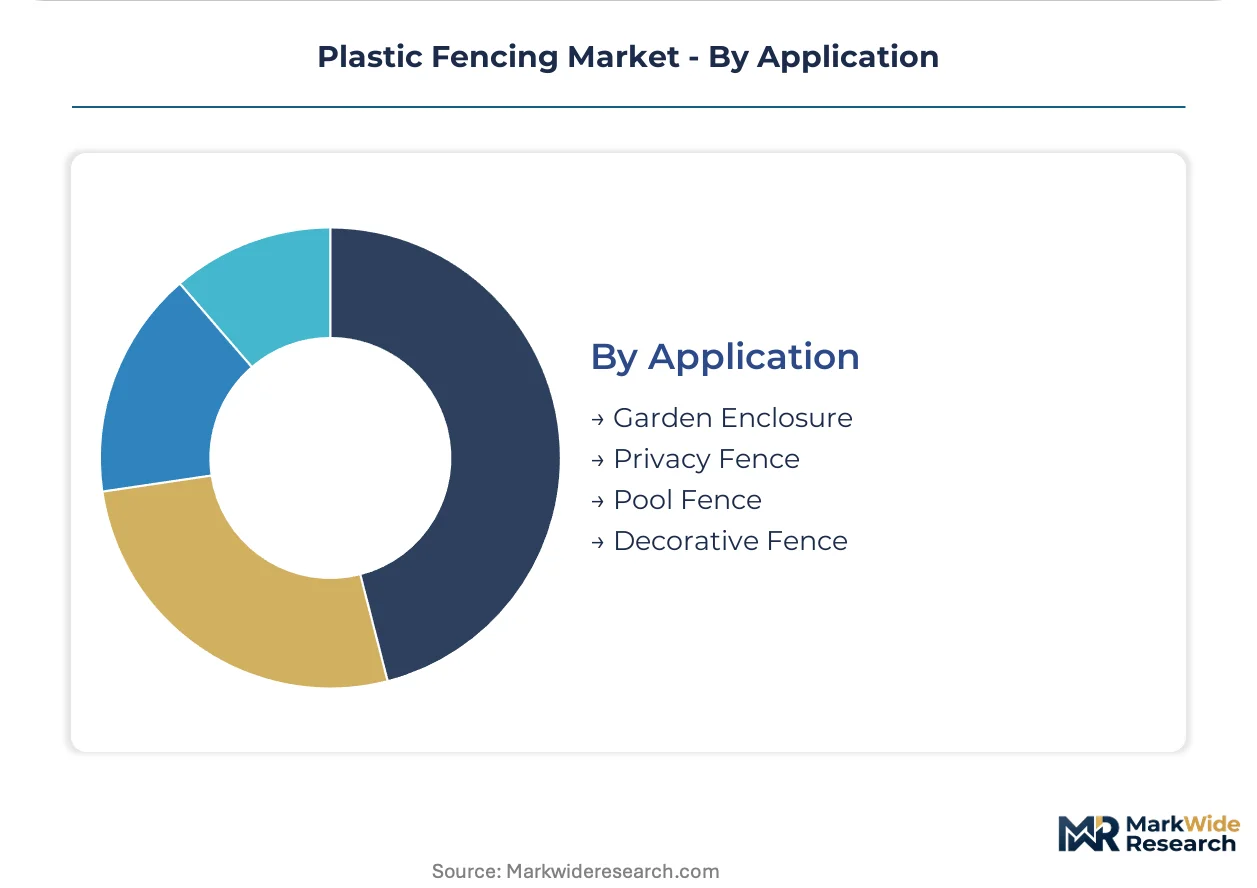
Plastic fencing denotes extruded or molded barrier systems manufactured from thermoplastic resins—primarily PVC, polyethylene, or wood-plastic composites—typically formulated with UV stabilizers and impact modifiers to achieve weather resistance ratings of 10+ years. These systems replace timber and metal in perimeter demarcation, privacy screening, and safety enclosure roles across residential, commercial, and institutional properties. Vinyl fencing leads the product type category due to established color retention technology and lower maintenance requirements versus painted wood alternatives. Composite fencing represents the fastest-expanding segment as homeowners accept premium pricing for wood-grain aesthetics combined with moisture immunity. Privacy fence applications command the deepest margin pools among application segments, driven by custom height and texture specifications in affluent suburban markets.
EPA guidelines on vinyl chloride emissions and REACH restrictions on phthalate plasticizers constrain formulation choices for manufacturers selling into the United States and European Union. China's GB standards on plastic building materials and the EU F-Gas Regulation on blowing agents for foamed profiles add compliance layers for cross-border suppliers. Stakeholders must monitor evolving extended producer responsibility frameworks in California and the European Union, as these jurisdictions test take-back mandates that would reshape post-consumer collection economics and resin cost structures.
Market Dynamics
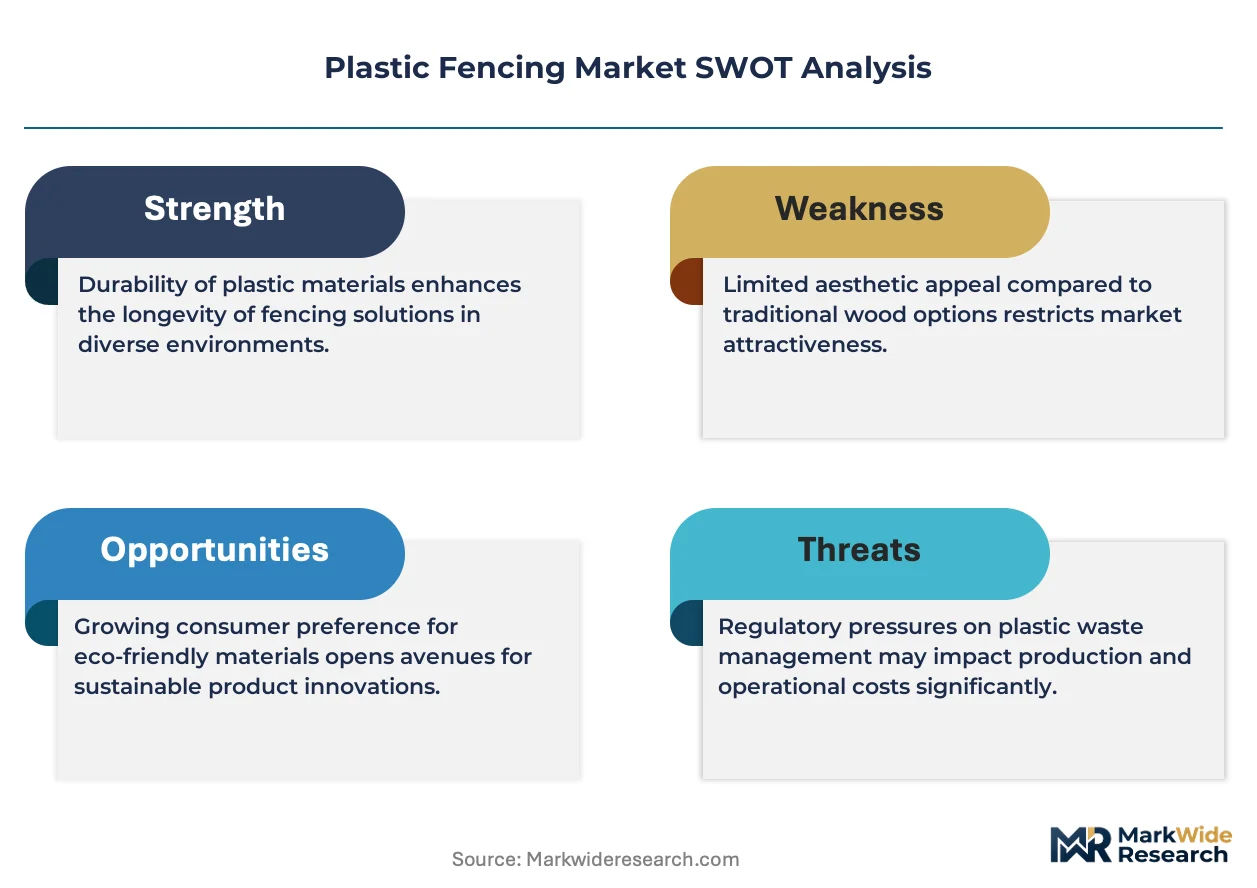
REACH compliance and EPA recycled-content guidelines are forcing reformulation across PVC and composite fencing supply chains, compressing margins for converters while opening pathways for bio-based feedstock adopters.
Growth Catalysts
- Suburban residential development:Property developers in the United States are specifying vinyl privacy systems for master-planned communities, drawn to 10-year weather resistance warranties and reduced maintenance labor.
- REACH plasticizer restrictions:ECHA's tightening controls on phthalate additives are accelerating non-phthalate stabilizer adoption among European extruders, creating first-mover advantages for compliant converters.
- Wood-plastic composite technology:Moisture-immune composite formulations are capturing premium segments as homeowners accept higher upfront costs for wood-grain aesthetics without rot susceptibility.
Market Restraints
- Resin cost volatility:PVC and polyethylene feedstock prices fluctuate with crude oil and natural gas benchmarks, squeezing extrusion margins during energy price spikes.
- Chinese supply concentration:A significant share of global UV stabilizer and impact modifier production clusters in eastern China, creating geographic vulnerability for non-integrated converters.
- Metal substitution threat:Galvanized steel and aluminum fencing retain structural advantage in high-wind and security applications, limiting plastic penetration in commercial perimeter markets.
Strategic Opportunities
- Extended producer responsibility frameworks:California and EU take-back mandate pilots are reshaping post-consumer collection economics, rewarding converters with in-house recycling capabilities.
- Municipal infrastructure budgets:German and Dutch highway barrier replacement cycles are opening utility-scale contracts for crash-rated plastic systems with lower lifecycle costs than concrete.
- Direct-to-contractor digital channels:E-procurement platforms are disintermediating traditional building-products distributors, enabling margin capture by manufacturers with logistics scale.
Industry Challenges
- Formulation chemistry expertise:Compliance with evolving EPA vinyl chloride emission limits and EU F-Gas Regulation on foamed profiles demands specialized polymer science talent that converters struggle to recruit.
- Certification timeline compression:GB standards compliance for Chinese market entry and UL fire-rating approvals for US commercial projects extend product development cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Fencing Market |
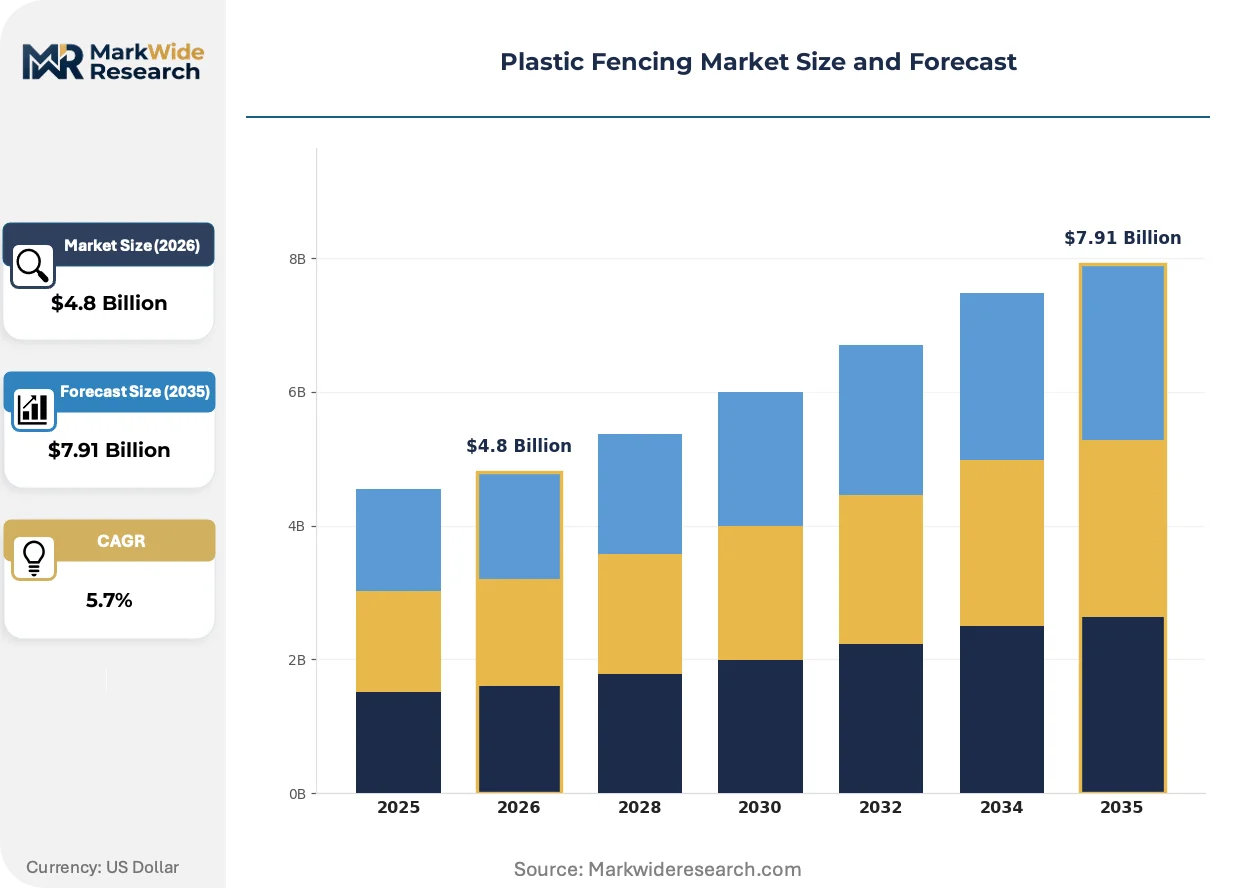
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vinyl Fencing, Composite Fencing, PVC Fencing, Polyethylene Fencing End User: Residential, Commercial, Industrial, Institutional Installation Type: DIY Installation, Professional Installation, Pre-assembled Panels, Custom Fit Application: Garden Enclosure, Privacy Fence, Pool Fence, Decorative Fence |
| Companies Covered | Pexco, Tenax, Barrette Outdoor Living, Seven Trust, Veka AG, CertainTeed, Superior Plastic Products, Planet Polynet, Durafence, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Fencing Market Emerging Trajectories
Material science advances and regulatory tightening are converging to reshape competitive positioning, with formulation compliance and digital channel integration now determining margin capture.
Co-extruded capstock technology is expanding into premium residential segments, delivering UV-stable color layers over recycled PVC cores. High-end homeowners in affluent US suburbs are specifying these systems for custom height privacy installations. This technology is expanding into mid-market price tiers as Chinese equipment manufacturers scale turnkey extrusion line supply.
ECHA's 2025 restrictions on lead-based heat stabilizers are forcing European converters to retool formulation lines ahead of enforcement deadlines. German and Italian extruders face 12-18 month requalification cycles for existing product portfolios. Vinyl fencing sold into EU markets is responding with calcium-zinc stabilizer blends that trade slight cost premiums for compliance certainty.
Builder and contractor buying patterns are consolidating through integrated e-procurement platforms that bundle fencing with complementary exterior products. Traditional two-step distribution through regional building-products wholesalers is losing share to direct manufacturer portals with project-based quoting tools. This channel shift is most visible in United States residential construction markets where national homebuilders centralize specification authority.
Plastic Fencing Market Segmentation
Plastic fencing procurement patterns diverge sharply across material chemistry, end-use environment, and installation complexity. Specification authority sits with distinct decision-makers in each segment, requiring targeted formulation and channel strategies.
Product Type:
Vinyl and composite systems function as standalone perimeter solutions with integrated color and weathering technology, while PVC and polyethylene grades often embed as components within larger building envelope assemblies.
- Vinyl Fencing:Extruded PVC formulations with co-extruded capstock layers deliver UV-stable color retention across 10-year warranty periods. Master-planned communities in the United States specify these systems for reduced maintenance labor and consistent aesthetic compliance across property lines.
- Composite Fencing:Wood-plastic hybrid formulations combine recycled polyethylene with cellulose fiber for moisture-immune wood-grain aesthetics. Affluent suburban homeowners accept premium positioning for rot-resistant privacy screening in high-humidity climates.
- PVC Fencing:Rigid unplasticized profiles serve utility-scale highway barriers and municipal infrastructure where crash-rating compliance and lifecycle cost calculations dominate procurement.
- Polyethylene Fencing:Flexible high-density formulations address temporary construction enclosures and agricultural boundary marking where cost minimization outweighs permanence requirements.
Volume placements concentrate in vinyl systems; the faster expansion belongs to composite formulations.
End User:
Cost tiers separate discretionary residential spending from institutional procurement governed by public budget cycles and safety certification mandates.
- Residential:Single-family homeowners and property developers drive specification of privacy and decorative systems, with aesthetic customization and warranty transferability influencing purchase decisions in suburban North American markets.
- Commercial:Retail property managers and office park developers prioritize perimeter security with brand-consistent visual presentation, sourcing through national building-products distributors with project-scale logistics.
- Industrial:Manufacturing facilities and logistics yards demand high-impact resistance and rapid installation turnaround, often specifying pre-assembled panel systems to minimize operational disruption.
- Institutional:School districts and municipal park departments navigate public procurement regulations, favoring products with established UL fire ratings and EPA-compliant recycled content documentation.
Residential channels move the highest unit volumes; institutional contracts carry the longest sales cycles but deepest margin pools.
Installation Type:
Customer capability and project scale determine whether fencing arrives as consumer-ready kits or engineered custom assemblies requiring specialized labor.
- DIY Installation:Pre-notched rail systems and snap-together post designs target homeowners with basic tools, distributed through home improvement retailers with instructional content and return policy support.
- Professional Installation:Full-service contractors handle site preparation, permitting, and warranty registration, capturing margin through labor bundling in affluent markets where time scarcity exceeds price sensitivity.
- Pre-assembled Panels:Factory-welded sections reduce field labor for commercial and industrial projects with standardized linear footage requirements and compressed construction schedules.
- Custom Fit:Site-measured and milled components address irregular terrain, heritage property restrictions, and architect-specified height or texture variations in premium residential segments.
Professional installation commands the largest revenue pool; DIY channels are climbing the fastest as digital tutorials reduce perceived complexity.
Application:
Functional requirements range from decorative boundary marking to safety-critical pool enclosure, with regulatory load varying dramatically across use cases.
- Garden Enclosure:Low-height picket and lattice configurations prioritize visual continuity with landscaping, specifying smaller dimensions and ornamental post caps for residential curb appeal.
- Privacy Fence:Tongue-and-groove or board-on-board constructions eliminate sightlines between properties, commanding custom height specifications and premium pricing in dense suburban developments.
- Pool Fence:Self-closing gates and climb-resistant vertical balusters must satisfy municipal building codes and insurance liability requirements, with height and latch specifications varying by jurisdiction.
- Decorative Fence:Scalloped profiles, post caps, and color-matched accessories serve aesthetic-first applications where perimeter definition matters more than security or screening function.
Privacy applications generate the deepest margins; pool safety fencing is expanding most quickly as code adoption spreads across US municipalities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Houston anchors North American resin supply for fencing converters, with Gulf Coast petrochemical corridors feeding extrusion plants across Texas and neighboring states. Suburban development patterns and municipal infrastructure cycles create divergent demand profiles across major economies.
United States
Master-planned communities in Arizona and Florida specify vinyl privacy systems for warranty transferability and reduced HOA maintenance disputes. EPA guidelines on recycled content documentation now apply to institutional procurement in California and New York. Extrusion capacity clusters in Ohio and Pennsylvania serve Midwest residential contractors through building-products distributors.
Germany
Highway barrier replacement programs in Bavaria and North Rhine-Westphalia generate utility-scale contracts for crash-rated PVC systems. ECHA restrictions on lead-based heat stabilizers force 12-18 month requalification cycles for existing product lines. Industrial extruders in the Ruhr region retool formulation lines toward calcium-zinc stabilizer blends ahead of enforcement deadlines.
China
Urban landscaping budgets in Shanghai and Shenzhen expand procurement of decorative fencing for park renovation projects. GB standards on plastic building materials add compliance layers for domestic manufacturers and cross-border suppliers alike. UV stabilizer and impact modifier production concentrates in eastern provinces, creating supply vulnerability for non-integrated converters elsewhere.
United Kingdom
Residential developers in Greater London commuter belts specify low-maintenance perimeter solutions for new-build housing estates. Building regulations on fire safety ratings influence specification authority for multi-unit residential projects. Distribution integration with national home improvement retailers shapes competitive positioning for mid-market vinyl systems.
India
Smart city initiatives in Maharashtra and Gujarat incorporate plastic fencing for municipal park enclosures and traffic barrier applications. BIS certification requirements for plastic building materials extend product development timelines for market entrants. Manufacturing activity concentrates in Pune and Ahmedabad industrial corridors serving western and central regional demand.
Plastic Fencing Market Vendor Landscape
The competitive structure tilts toward building-products conglomerates with distribution integration advantages. Mid-scale extrusion specialists occupy regional niches through contractor relationships and custom fabrication capabilities. Two archetypes dominate: vertically integrated resin-to-fence manufacturers with captive feedstock supply, and pure-play extruders competing on formulation agility and regional logistics. M&A activity concentrates on distribution assets and recycling capabilities, while capacity expansion targets southeastern United States and central European markets with favorable energy economics.
Among North American building-products conglomerates, CertainTeed and Barrette Outdoor Living exemplify distribution-integrated positioning through home improvement retail channels. Pexco occupies a position within the utility-scale extrusion segment, serving highway barrier and infrastructure contracts across the continent. European specialists including Veka AG and Tenax represent formulation-compliance-focused archetypes navigating ECHA regulatory tightening.
| Leading Market Players |
|---|
| Pexco |
| Tenax |
| Barrette Outdoor Living |
| Seven Trust |
| Veka AG |
| CertainTeed |
| Superior Plastic Products |
| Planet Polynet |
| Durafence |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between REACH-compliant European formulations and commodity-grade Asian exports manifests in both price stratification and supply chain routing. Premium calcium-zinc stabilizer blends command 15-20% cost premiums over legacy lead-based alternatives, with compliant extruders in Germany and Italy capturing margin through restricted supply access while non-compliant producers face market exclusion.
Pricing Analysis
Value-based pricing anchored to warranty transferability and lifecycle cost calculations dominates residential vinyl fencing procurement. Three-tier pricing structure across premium co-extruded capstock, standard monolayer vinyl, and economy polyethylene separates warranty-backed privacy systems from temporary agricultural enclosures. Price differentiation rests on UL fire-rating certification and EPA recycled-content documentation, with institutional buyers in California and New York least sensitive to upfront cost. Cost compression in standard-grade vinyl is intensifying because Chinese equipment manufacturers have scaled turnkey extrusion line supply, eroding technology-based margin protection.
Supply Chain Analysis
REACH and EPA qualification gating restricts formulation chemistry sourcing to approved additive suppliers in Germany, the United States, and Japan. Raw material dependencies center on Gulf Coast PVC resin, eastern Chinese UV stabilizer production, and Saudi Arabian plasticizer feedstocks. Single-source vulnerability concentrates in impact modifier supply from Shandong province facilities. Distribution runs through building-products wholesalers in North America and direct manufacturer portals displacing traditional two-step channels in residential construction markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where ECHA's lead-based heat stabilizer restrictions erect formulation expertise barriers that favor incumbent European extruders with established calcium-zinc requalification capabilities.
For Market Incumbents: Cement market position through backward integration into recycled PVC flake processing ahead of California and EU extended producer responsibility mandate expansion. Defend against composite fencing substitution by investing in co-extrusion equipment upgrades that match wood-grain aesthetic performance. Channel control through exclusive home improvement retail partnerships remains the priority lever for North American volume defense.
For New Entrants and Emerging Players: Launch via direct-to-contractor digital platforms targeting mid-market vinyl privacy systems in Texas and Florida master-planned communities where specification authority centralizes with national homebuilders. Municipal infrastructure replacement cycles in Germany and the Netherlands offer the most penetrable white-space for crash-rated PVC barrier contracts. A formulation-compliance-first go-to-market angle bypasses incumbent cost advantages in residential segments.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale extruders possessing in-house recycling capabilities given extended producer responsibility framework expansion across California and EU member states. Long-term viability over a multi-year horizon favors converters with captive stabilizer blending operations and established ECHA regulatory affairs infrastructure. The signal to watch is municipal procurement mandate adoption for recycled-content documentation in institutional fencing contracts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled PVC Processing | Captures margin from post-consumer collection economics under emerging EPR frameworks in California and the EU. |
| Co-Extrusion Equipment Upgrade for Capstock Technology | Matches composite wood-grain performance while maintaining PVC cost structure in premium residential privacy segments. |
| Direct-to-Contractor Digital Platform Launch | Disintermediates traditional building-products distributors consolidating specification authority with national homebuilders. |
| Calcium-Zinc Stabilizer Formulation Investment | Secures REACH compliance ahead of ECHA enforcement deadlines creating first-mover advantage in European markets. |
| Municipal Infrastructure Contract Pursuit | Accesses utility-scale highway barrier replacement programs in Germany and the Netherlands with lower lifecycle cost positioning. |
Methodological Framework
Independent corroboration across extrusion plant managers, building-products distribution channel partners, municipal procurement officers, and polymer formulation chemists underwrites the qualitative findings. Primary interviews with technical R&D directors at European and North American converters combined with secondary validation through customs trade data, ACC and Plastics Industry Association reports, and SEC 10-K disclosures from building-products conglomerates established demand and supply parameters. Bottom-up unit economics from individual product lines and top-down sectoral sizing from construction spending data were triangulated to resolve estimation variance.
Comparable-period anchoring to historical residential construction permit issuance and municipal infrastructure budget cycles structured the projection horizon. The analytical framework segmented volume and value across material chemistry, end-use environment, installation complexity, and regional regulatory cluster dimensions. CAGRs were derived from elasticity-adjusted demand curves incorporating resin cost volatility and compliance cost pass-through assumptions. Industry-specific forecast inputs included master-planned community development pipelines and highway barrier replacement schedules.
Resin cost volatility, regulatory enforcement timing, and substitution elasticity between vinyl and composite formulations are the dominant revision risks. Forecasts reflect assumptions regarding ECHA implementation consistency and EPA guideline adoption pace across US states. A model refresh is warranted upon material change in extended producer responsibility mandate scope or breakthrough composite moisture-resistance technology.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Global Wood Cement Boards Market
Building & Construction Materials
Ceramic Wall Tiles Market
Building & Construction Materials
North America Cast-In-Place Concrete Flooring Market
Building & Construction Materials
France Oriented Strand Board Market
Building & Construction Materials
Global Steel Wire Rod Market
Building & Construction Materials
Russia Ceramic Tiles Market
Building & Construction Materials
Building Vibration Isolation Market
Building & Construction Materials
Pre-Insulated Pipes Market
Building & Construction Materials
Residential Non-metal Electrical Conduit Market
Building & Construction Materials
Carbon Textile Reinforced Concrete Market
Building & Construction Materials
Asia-Pacific Ready-Mix Concrete Market
Building & Construction Materials
Australia Industrial Insulation Market
Building & Construction Materials
Foldable Houses Market
Building & Construction Materials
India Manufacturing Market
Building & Construction Materials
Corrugated Steel Panels Market
Building & Construction Materials
Bamboo Engineered Wood Market