
 Asia-Pacific Road Marking Machine Market | 2026-2036
Asia-Pacific Road Marking Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Road Marking Machine Market Insights
The EU Green Deal's influence on Asian export standards is consolidating procurement criteria for road marking equipment buyers. Zhengzhou Dayu Machinery Co., Ltd leverages its Henan manufacturing base to dominate domestic thermoplastic applicator supply. XCMG sustains technology leadership through integrated chassis-applicator platforms for highway fleets. Roadsky anchors Southeast Asian distribution networks with localized service capabilities in Thailand and Vietnam.
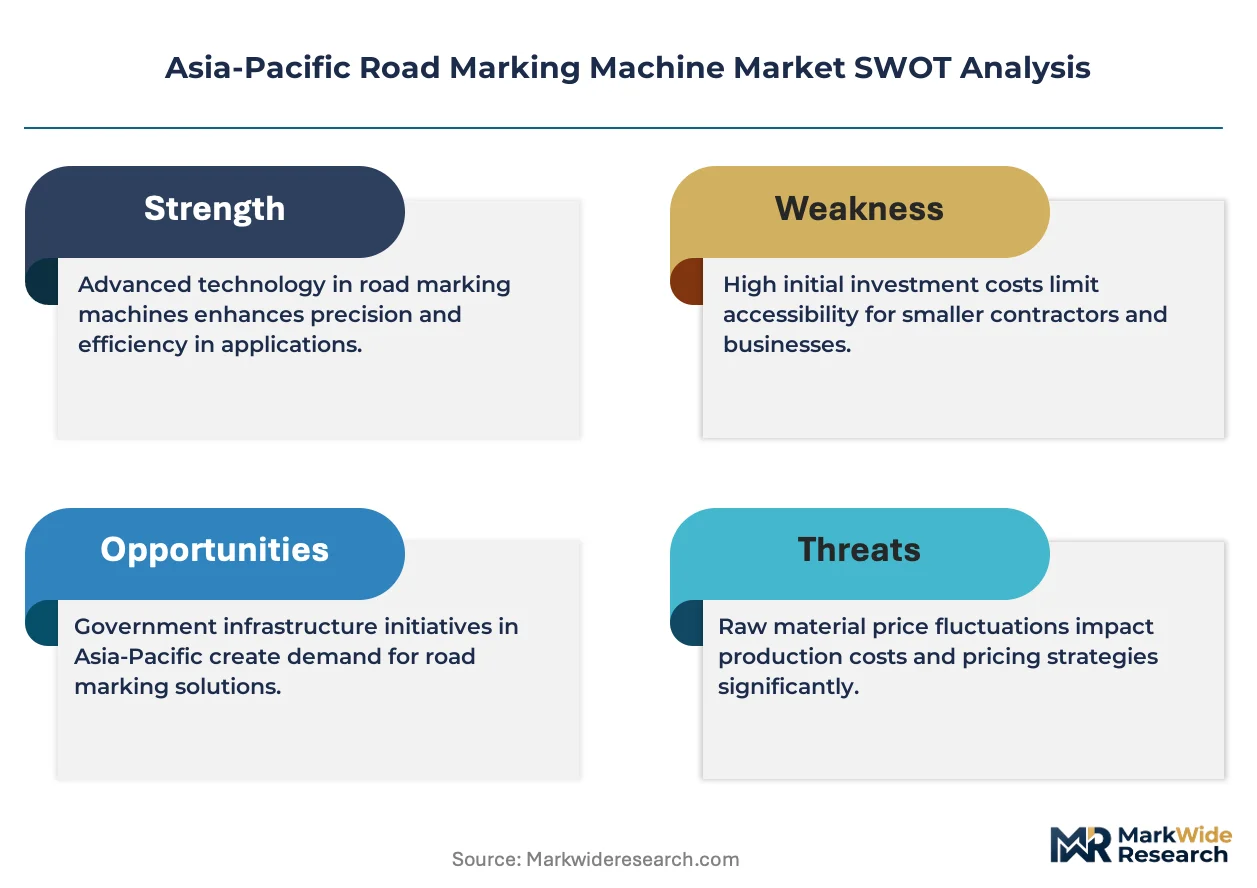
Road marking machines are specialized vehicles and portable units that apply retroreflective materials to pavement surfaces, typically operating at application temperatures between 180°C and 200°C for thermoplastic compounds to achieve durable lane delineation on asphalt and concrete substrates. Truck-mounted systems command the largest installed base across Asia-Pacific highway agencies due to throughput advantages on multi-lane corridors, while compact units represent the fastest-growing category as urban road maintenance shifts toward narrow-street accessibility and reduced traffic disruption. Thermoplastic technology leads value generation given material longevity and regulatory preference for high-performance road markings, though water-based paint retains volume share in parking lot and secondary road applications where cost sensitivity dominates.
China's MEE enforces VOC emission ceilings on road marking materials that directly constrain cold plastic formulation choices and elevate thermoplastic system demand. India's BIS certification requirements for retroreflectivity standards on national highways create compliance barriers for uncertified equipment imports. Japan's METI energy-efficiency guidelines shape diesel-powered machine specifications. Stakeholders must monitor evolving green procurement mandates and material substitution timelines across these regulatory jurisdictions.
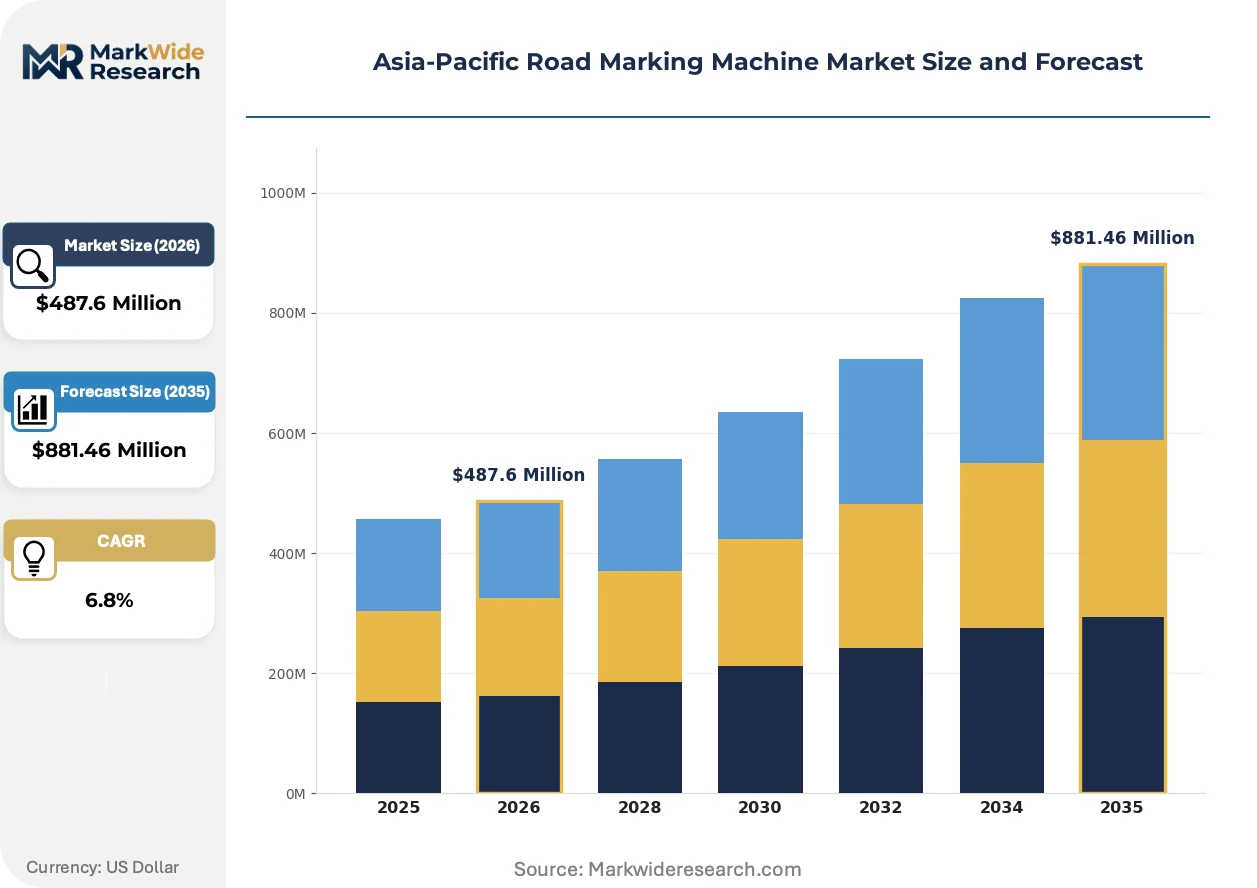
Market Dynamics
China's dual carbon goals are compressing thermoplastic system adoption timelines across municipal procurement, while India's National Highways Authority lane marking upgrades concentrate demand in truck-mounted platforms. Southeast Asian highway maintenance budget expansions are reshaping equipment specification standards.
Growth Catalysts
- MEE VOC ceilings:China's Ministry of Ecology and Environment emission limits on road marking materials are elevating thermoplastic applicator demand over cold plastic alternatives.
- National highway retroreflectivity mandates:India's BIS certification requirements for lane marking visibility standards are forcing equipment upgrades across state road agencies.
- Urban narrow-street accessibility:Compact road marking machine demand is accelerating in Vietnam and Thailand as municipalities prioritize reduced traffic disruption during maintenance.
Market Restraints
- Petroleum-based binder volatility:Thermoplastic compound feedstock costs fluctuate with crude oil indices, squeezing applicator fleet operating margins.
- Henan manufacturing concentration:Domestic Chinese supply dominance in thermoplastic applicator production creates geographic single-source vulnerability for regional buyers.
- Water-based paint substitution:Parking lot and secondary road segments retain cost-driven preference for lower-performance marking materials.
Strategic Opportunities
- Indonesia trans-Sumatra highway corridor:Underpenetrated equipment installation base across the archipelago's emerging toll road network offers first-mover positioning.
- EU Green Deal procurement alignment:Export-oriented manufacturers can capture premium positioning by certifying to consolidated European sustainability criteria.
- Chassis-applicator integration:Convergence of dedicated vehicle platforms with automated marking systems enables highway fleet efficiency gains.
Industry Challenges
- Thermoplastic application technician certification:Specialized 180°C to 200°C operating temperature training requirements constrain workforce scalability.
- Retroreflectivity testing equipment integration:BIS compliance verification delays extend project commissioning timelines for imported systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Road Marking Machine Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact, Truck-mounted, Self-propelled, Hand-held Technology: Thermoplastic, Water-based Paint, Cold Plastic, Preformed Markings End User: Government Agencies, Contractors, Municipalities, Private Sector Application: Highways, Parking Lots, Airports, Urban Roads |
| Companies Covered | Zhengzhou Dayu Machinery Co., Ltd, Roadsky, XCMG, Jiangsu Luxinda Traffic Facilities Co., Ltd, MRL, SANY, Automark Industries (India) Pvt Ltd, Siam Traffic, Zoomlion, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Road Marking Machine Market Trends and Innovations
Equipment specification is pivoting toward integrated performance systems that compress material-application-verification workflows. Buyers are prioritizing platforms that reduce crew size and eliminate separate quality assurance passes.
Automated guidance and material-dosage control systems are unifying application precision with real-time retroreflectivity monitoring in next-generation truck-mounted platforms. Japan's METI energy-efficiency guidelines are accelerating adoption of these integrated systems among highway maintenance contractors. The technology is unifying what were previously three distinct equipment categories into single-pass operational units.
EU Green Deal sustainability criteria are reshaping Asian export certification requirements for road marking equipment manufacturers. REACH-aligned material disclosure standards are becoming default procurement preconditions for Southeast Asian infrastructure tenders. Thermoplastic system suppliers are responding by reformulating binder compounds to eliminate Substances of Very High Concern.
After-sales service unbundling is disrupting traditional equipment-vendor relationships across Asia-Pacific highway agencies. Municipal buyers are separating maintenance contracts from original equipment purchases, favoring localized service networks over manufacturer-direct support. Thailand and Vietnam are witnessing the fastest channel restructuring as Roadsky and regional distributors build captive technician pools.
Asia-Pacific Road Marking Machine Market Segmentation
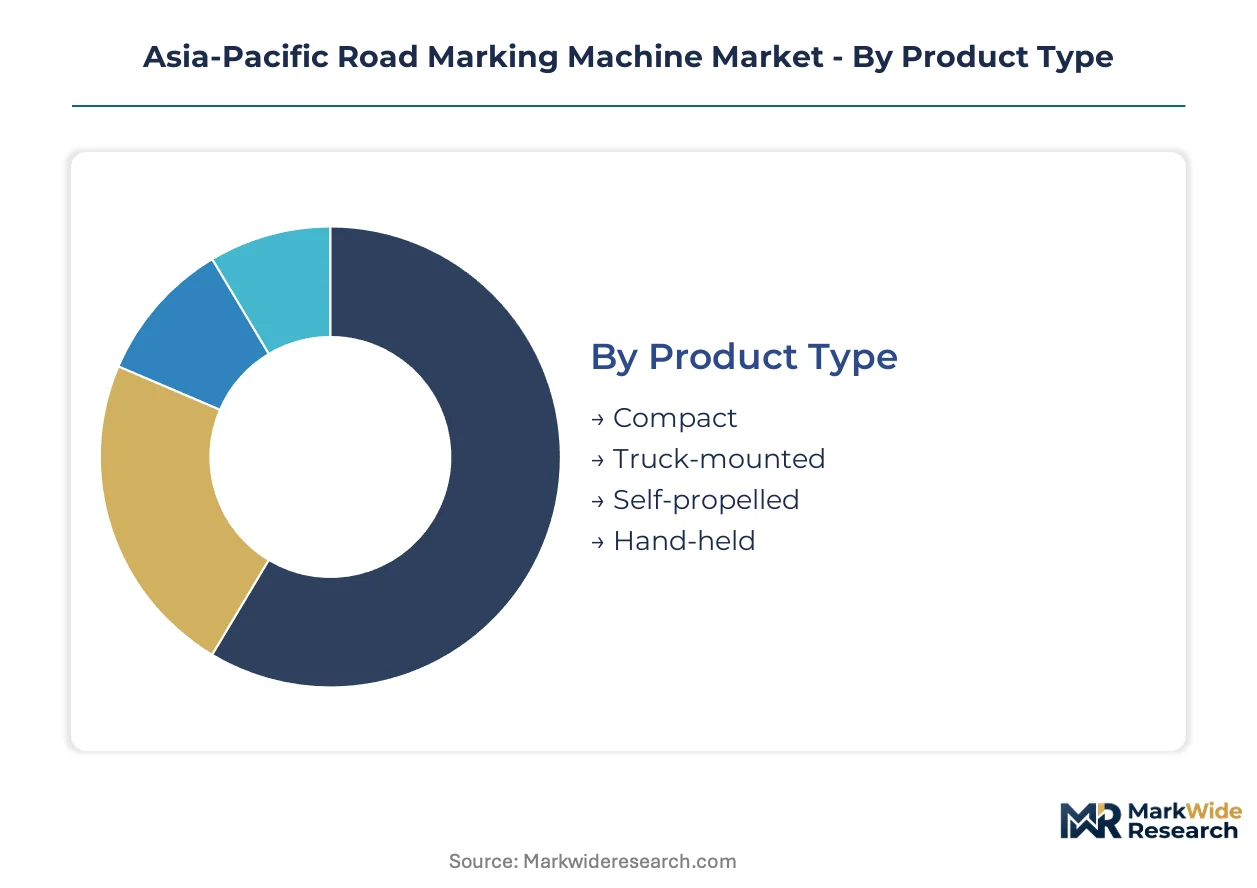
Road marking machine procurement in Asia-Pacific follows distinct capital-deployment patterns across product configurations, material systems, and end-user governance structures. Equipment specification diverges sharply between highway-scale fleet investments and municipal maintenance programs.
Product Type:
Capital intensity escalates dramatically with chassis integration and application throughput capacity, separating fleet-scale highway contractors from decentralized urban maintenance units.
- Truck-mounted:Integrated chassis-applicator platforms require substantial upfront fleet investment but deliver continuous multi-lane throughput. India's National Highways Authority concentrates procurement here for lane marking upgrades across trans-state corridors.
- Compact:Narrow-street accessibility dominates municipal specifications in Vietnam and Thailand, where traffic disruption penalties reshape maintenance scheduling. Reduced crew size and rapid deployment offset lower hourly output.
- Self-propelled:Mid-tier capital requirements suit regional contractors serving secondary road networks in Indonesia's emerging toll road system.
- Hand-held:Minimal equipment outlay supports parking lot specialists and small-scale striping operations across Southeast Asian urban centers.
Truck-mounted systems absorb the bulk of installed capacity; compact units are expanding most quickly.
Technology:
Material chemistry determines equipment thermal management specifications and regulatory compliance pathways across Asia-Pacific jurisdictions.
- Thermoplastic:Application systems operating at 180°C to 200°C dominate highway retroreflectivity mandates. China's MEE VOC emission ceilings are compressing adoption timelines as municipalities abandon cold plastic alternatives.
- Water-based Paint:Ambient-temperature application equipment retains volume share where cost sensitivity dominates parking lot and secondary road segments.
- Cold Plastic:Two-component mixing systems face feedstock volatility pressures from petroleum-based binder cost fluctuations.
- Preformed Markings:Tape-application equipment serves temporary traffic control and airport surface marking niches requiring rapid installation without thermal curing.
Thermoplastic platforms command the largest equipment investment base; preformed marking systems are gaining share fastest in specialized airfield applications.
End User:
Procurement governance structures separate centralized highway authority tenders from fragmented municipal maintenance budgets.
- Government Agencies:India's state road agencies and China's provincial transport bureaus deploy standardized fleet specifications with BIS and GB compliance verification.
- Contractors:Highway maintenance concessionaires in Indonesia and the Philippines balance equipment utilization rates across multi-year toll road contracts.
- Municipalities:Urban public works departments in Thailand and Vietnam prioritize localized service networks over manufacturer-direct support.
- Private Sector:Commercial parking operators and logistics facility managers drive compact equipment demand with performance-based maintenance contracts.
Government agencies deploy the predominant share of truck-mounted fleet capacity; municipalities are climbing the fastest in compact unit procurement.
Application:
Surface substrate and traffic loading conditions dictate material durability requirements and corresponding equipment thermal specifications.
- Highways:Multi-lane asphalt corridors require continuous thermoplastic application at specified retroreflectivity thresholds enforced by national regulators.
- Urban Roads:Concrete and composite surfaces with frequent maintenance cycles favor adaptable compact platforms in dense Japanese and Korean metropolitan areas.
- Parking Lots:Low-speed environments with color-coded zoning tolerate water-based paint systems and corresponding ambient-temperature equipment.
- Airports:Precision tolerance requirements for runway and taxiway markings demand specialized preformed and thermoplastic systems with enhanced visibility specifications.
Highway applications concentrate the heaviest equipment investment; urban roads are seeing the steepest expansion trajectory in compact platform deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zhengzhou anchors thermoplastic applicator manufacturing across the Asia-Pacific region, with Henan province's industrial corridor supplying highway maintenance fleets from Indonesia to India. Provincial transport bureaus and national highway authorities drive procurement concentration in four distinct national markets.
China
Provincial transport bureaus in Henan and Shandong provinces deploy standardized thermoplastic fleets under MEE VOC emission ceilings that eliminate cold plastic alternatives. The dual carbon goals compress municipal procurement timelines toward low-emission systems. Zhengzhou's manufacturing cluster dominates domestic supply while exporting chassis-integrated platforms across Southeast Asia.
India
The National Highways Authority concentrates truck-mounted platform demand across trans-state corridors including the Delhi-Mumbai Industrial Corridor. BIS certification requirements for retroreflectivity standards create compliance barriers for uncertified equipment imports. Maharashtra and Gujarat state road agencies lead fleet modernization with performance-linked maintenance contracts.
Japan
Metropolitan expressway operators in the Kanto region prioritize compact platforms for dense urban maintenance with minimal traffic disruption. METI energy-efficiency guidelines shape diesel-powered machine specifications for highway contractors. Osaka-based maintenance consortia integrate automated guidance systems with real-time quality verification.
Vietnam
Municipal public works departments in Ho Chi Minh City and Hanoi accelerate compact unit procurement for narrow-street accessibility. Localized service networks displace manufacturer-direct support as procurement governance shifts toward maintenance unbundling. The Mekong Delta corridor generates secondary demand for mid-tier self-propelled systems.
Indonesia
The trans-Sumatra highway corridor presents underpenetrated equipment installation base across emerging toll road concessions. Regional contractors balance fleet utilization across multi-year maintenance contracts in Java and Sumatra. Jakarta-based distributors build captive technician pools to capture after-sales service separation.
Asia-Pacific Road Marking Machine Market Competitive Landscape
The competitive structure tilts toward domestic Chinese manufacturers with integrated supply chains. Henan province hosts multiple fabrication clusters serving both domestic highway agencies and export markets. Three archetypes dominate: chassis-integrated platform specialists, compact urban maintenance equipment fabricators, and regional distributors with localized service capabilities. Capacity expansion and geographic distribution partnerships represent the primary competitive moves as manufacturers respond to procurement unbundling trends.
Among Chinese fabricators, Zhengzhou Dayu Machinery Co., Ltd and XCMG occupy positions reflecting distinct strategic emphases within the thermoplastic applicator segment. Roadsky exemplifies the distributor archetype with Southeast Asian service network development. These three anchors illustrate how domestic manufacturing concentration, integrated chassis-applicator platforms, and localized after-sales capabilities define competitive positioning across the region's fragmented procurement landscape.
| Leading Market Players |
|---|
| Zhengzhou Dayu Machinery Co., Ltd |
| Roadsky |
| XCMG |
| Jiangsu Luxinda Traffic Facilities Co., Ltd |
| MRL |
| SANY |
| Automark Industries (India) Pvt Ltd |
| Siam Traffic |
| Zoomlion |
| Others |
Pricing and Supply Chain Analysis
Thermoplastic formulation shifts toward low-VOC binder systems are simultaneously elevating equipment thermal specifications and concentrating procurement leverage among Henan province fabricators. Municipal buyers face compressed negotiation room as standardized chassis-applicator platforms displace fragmented equipment sourcing.
Pricing Analysis
Throughput-linked pricing anchors equipment valuation, with truck-mounted platforms commanding premiums tied to lane-kilometers per hour. Price differentiation separates MEE-compliant thermal systems from legacy cold plastic alternatives, with certification-grade retroreflectivity thresholds widening spreads. Cost compression in compact urban units is intensifying as Vietnamese and Thai municipalities unbundle maintenance contracts. Parking lot operators exhibit highest price sensitivity; highway concessionaires absorb premium positioning for integrated quality-verification systems.
Supply Chain Analysis
Petroleum-based binder supply rests on South Korean and Chinese petrochemical producers, with titanium dioxide feedstock drawing from Australian mineral processors. Critical component dependencies span diesel engine blocks, precision extrusion dies, and retroreflectivity glass bead formulations. Single-source vulnerability concentrates in Henan thermoplastic applicator fabrication clusters. Distribution runs through Jakarta-based distributors building captive technician pools and Bangkok service hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Integrated chassis-applicator platforms are displacing standalone marking units, compressing adoption timelines for highway fleet operators. This technology transition favors manufacturers with captive vehicle integration capabilities.
For Market Incumbents: Acquire localized service network assets in Indonesia and Vietnam to counter procurement unbundling trends. Secure backward integration into thermoplastic binder formulation to offset petroleum feedstock volatility. Invest in BIS certification pre-clearance capabilities to accelerate Indian National Highways Authority tender participation.
For New Entrants and Emerging Players: Municipal maintenance departments in secondary Vietnamese cities represent the most penetrable buyer archetype. Target compact equipment demand in Ho Chi Minh City peripheral districts with rapid-deployment service models. Pursue chassis-applicator integration partnerships with regional vehicle assemblers rather than greenfield manufacturing.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to construction equipment conglomerates seeking highway maintenance verticals. Five-to-ten year viability hinges on MEE VOC enforcement consistency and India's BIS retroreflectivity mandate expansion. Monitor Indonesia trans-Sumatra highway concession award velocity as demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Chassis-Applicator Integration | Unifies vehicle platform and marking system procurement for highway fleet operators. |
| Localized Service Network Buildout | Captures after-sales revenue as Thai and Vietnamese municipalities unbundle maintenance contracts. |
| Thermoplastic Binder Backward Integration | Secures captive supply of MEE-compliant low-VOC formulation against petrochemical volatility. |
| BIS Certification Pre-Investment | Accelerates Indian National Highways Authority equipment approval timelines. |
| Compact Platform Rapid Deployment | Addresses narrow-street accessibility requirements in dense Vietnamese urban corridors. |
Research Methodology
Multi-period observation of thermoplastic applicator procurement volumes, MEE enforcement intensity, and BIS certification timelines anchored the trend analysis, supplemented by interviews with highway maintenance directors, municipal public works engineers, thermoplastic equipment procurement officers, and aftermarket service network managers. Secondary validation drew from China customs trade data, India NHAI tender disclosures, provincial transport bureau fleet deployment records, and ASEAN infrastructure investment databases. Bottom-up equipment shipment tracking and top-down highway maintenance budget allocation analysis provided triangulation.
Segment-weighting applied product type, technology system, end-user governance structure, and application surface substrate as dimensional anchors across the projection horizon. CAGRs derived from equipment replacement cycle analysis, highway lane-kilometer expansion schedules, and regulatory compliance deadline clustering. Forecast inputs incorporated MEE VOC ceiling phase-in schedules and India's BIS retroreflectivity mandate enforcement trajectories.
Revisions become necessary when MEE enforcement intensity deviates from provincial implementation timelines, BIS certification pathways extend unexpectedly, or petroleum-based binder costs spike beyond fleet operator absorption capacity. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Drilling Machine Market
Construction Equipment
Europe Construction Machinery Rental Market
Construction Equipment
Middle East and Africa Construction Equipment Market
Construction Equipment
Hybrid Excavator Market
Construction Equipment
Earthmoving Equipment Undercarriage Market
Construction Equipment
Radial Drilling Machine Market
Construction Equipment
US Waterjet Cutting Machines Market
Construction Equipment
Refurbished Construction Equipment Market
Construction Equipment
Global Compact Construction Equipment Market
Construction Equipment
India Heavy Construction Equipment Rental Market
Construction Equipment
Demolition Vessels Market
Construction Equipment
Europe Welding Equipment Market
Construction Equipment
Japan Heavy Construction Equipment Rental Market
Construction Equipment
Automatic Clay Brick Making Machine Market
Construction Equipment
Excavator Wheels Market
Construction Equipment
Static Crane Market