
 Heavy Construction Equipment Rental Market | 2026-2036
Heavy Construction Equipment Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Heavy Construction Equipment Rental Market Foresight
Market Context
Data center construction is restructuring demand patterns for heavy construction equipment rental across the United States. United Rentals, Inc. leverages its national branch network to dominate multi-year fleet contracts for hyperscaler campus builds. Sunbelt Rentals anchors its position through specialized crane and material handling inventories concentrated in Sun Belt growth corridors. H&E Equipment Services differentiates via technician-staffed maintenance depots that reduce contractor downtime on compressed project schedules.
Technical Definition and Segment Structure
Heavy construction equipment rental denotes the commercial provision of mobile, engine-powered machinery—typically weighing above 12,000 pounds with diesel or hybrid-electric propulsion—used for earthmoving, lifting, and site preparation activities without transfer of ownership. The primary industrial purpose centers on converting fixed capital expenditures into operational flexibility for contractors facing volatile project pipelines and utilization uncertainty. Excavators and cranes capture the dominant share of rental revenue pools, with excavators sustaining the broadest cross-application utilization and cranes commanding premium rate structures due to certified operator requirements and mobilization complexity. Short-term rental and long-term rental together constitute the core service architecture, though maintenance services increasingly embed into bundled agreements as fleet telematics enable predictive uptime guarantees.
Regulatory Environment and Outlook
The EPA enforces Tier 4 Final emissions standards that constrain diesel engine availability and elevate equipment procurement costs for rental fleet operators. OSHA crane certification mandates and state-level weight limit regulations shape equipment specification and interstate logistics planning. The EU Green Deal and F-Gas Regulation impose parallel decarbonization pressures on European fleet composition, while India's CEA construction safety codes tighten equipment inspection protocols. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate fleet standardization costs and residual value risk across multi-national rental portfolios.
Market Dynamics
Data center construction across Texas, Virginia, and Arizona is compressing rental fleet cycles and forcing rental operators to reconfigure equipment mix toward high-lift cranes and large excavators. Tier 4 Final compliance costs are simultaneously elevating fleet procurement barriers.
Growth Catalysts
- Hyperscaler facility expansion:Amazon Web Services, Microsoft Azure, and Google Cloud are committing multi-billion-dollar capital programs to campus builds in Phoenix, Ashburn, and Dallas-Fort Worth, creating sustained multi-year equipment demand.
- EPA Tier 4 Final mandates:Emissions standards are accelerating diesel-electric hybrid deployments as rental operators preempt regulatory obsolescence and capture green procurement preferences from ESG-conscious contractors.
- Compressed project timelines:Data center developers are imposing 18-24 month completion schedules that favor rental over ownership for contractors managing utilization risk across volatile pipelines.
Market Restraints
- Diesel engine supply concentration:Cummins, Caterpillar, and Volvo Penta control Tier 4 Final-certified powertrain supply, exposing rental operators to production allocation constraints and extended lead times.
- Steel and hydraulic component volatility:Boom cylinder and track assembly input costs fluctuate with commodity markets, compressing fleet procurement margins and complicating long-term rate planning.
- OSHA crane operator certification scarcity:NCCCO-certified operator shortages constrain crane fleet utilization and elevate labor attachment costs for rental providers.
Strategic Opportunities
- Telematics-enabled predictive maintenance:IoT sensor networks and edge analytics are converging to allow rental operators to guarantee uptime SLAs and embed service bundles into base rate structures.
- Battery-electric compact equipment:California CARB incentives and municipal zero-emission mandates are creating early-adopter channels for electric mini-excavators and skid steers in urban infill construction.
- Secondary market residual value capture:Export demand from Latin American and Southeast Asian contractors for Tier 3 equipment is extending fleet economic life and improving ROIC on initial procurement.
Industry Challenges
- Technician workforce pipeline gaps:Diesel-electric hybrid and full-electric propulsion systems require mechatronics competencies that traditional equipment mechanic training programs have not addressed.
- Interstate weight limit fragmentation:State-level permitting variations for oversize crane transport create logistics friction and mobilization cost uncertainty for multi-state rental contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heavy Construction Equipment Rental Market |
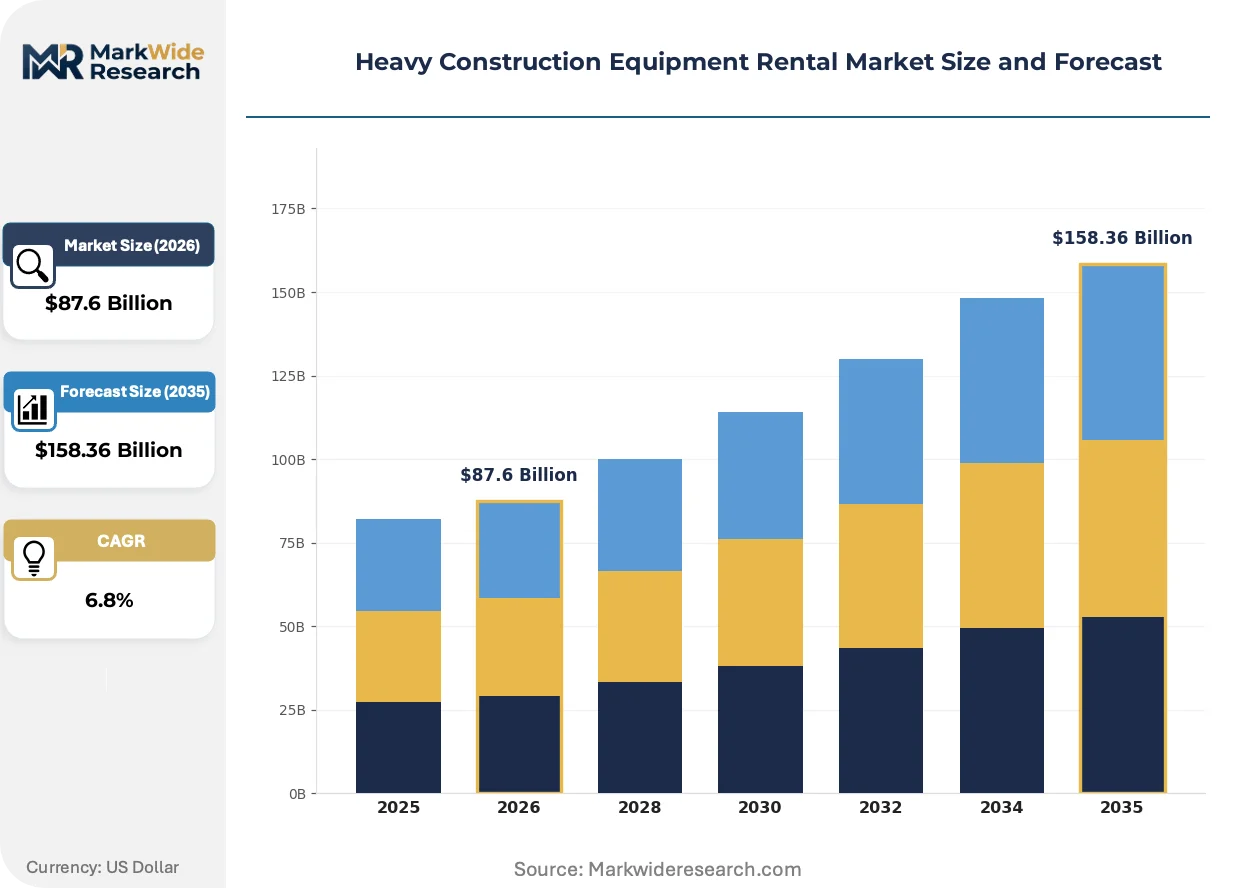
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $158.36 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Excavators, Bulldozers, Cranes, Backhoes End User: Construction Companies, Government Agencies, Industrial Firms, Contractors Application: Infrastructure Development, Soil Excavation, Material Handling, Site Preparation Service Type: Short-Term Rental, Long-Term Rental, Leasing, Maintenance Services |
| Companies Covered | United Rentals, Inc., Sunbelt Rentals, Herc Rentals, Loxam Group, H&E Equipment Services, Ahern Rentals, Maxim Crane Works, Ashtead Group plc, Neff Rental, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heavy Construction Equipment Rental Market Shifts & Advancements
Fleet digitization and alternative propulsion are restructuring competitive advantage around data-driven uptime guarantees rather than asset scale alone. Rental operators are repositioning as logistics partners rather than equipment lessors.
Machine telematics platforms are integrating GPS tracking, engine diagnostics, and predictive failure algorithms into unified fleet management dashboards. Large general contractors deploying these systems across multi-site data center programs are demanding API-accessible equipment status feeds. This capability compression is integrating rental providers into prime contractor project control centers rather than leaving them as external vendors.
The EPA's Tier 4 Final implementation timeline is forcing premature retirement of pre-2015 diesel fleets and accelerating capital redeployment toward compliant assets. Rental operators in California and Texas face the steepest compliance cliffs due to state-level enforcement intensity and hyperscaler ESG procurement standards. Fleet managers are responding with sale-leaseback structures and extended rental terms to smooth capital absorption.
Equipment-as-a-service contracting is displacing traditional day-rate and monthly rental structures among data center developers seeking to convert fixed fleet costs into variable construction line items. Tier-1 contractors in Northern Virginia and Phoenix are negotiating all-in per-cubic-yard earthmoving rates that bundle fuel, maintenance, and operator provision. This shift is most visible in markets where developer concentration permits standardized scope definition and performance benchmarking.
Heavy Construction Equipment Rental Market Segmentation
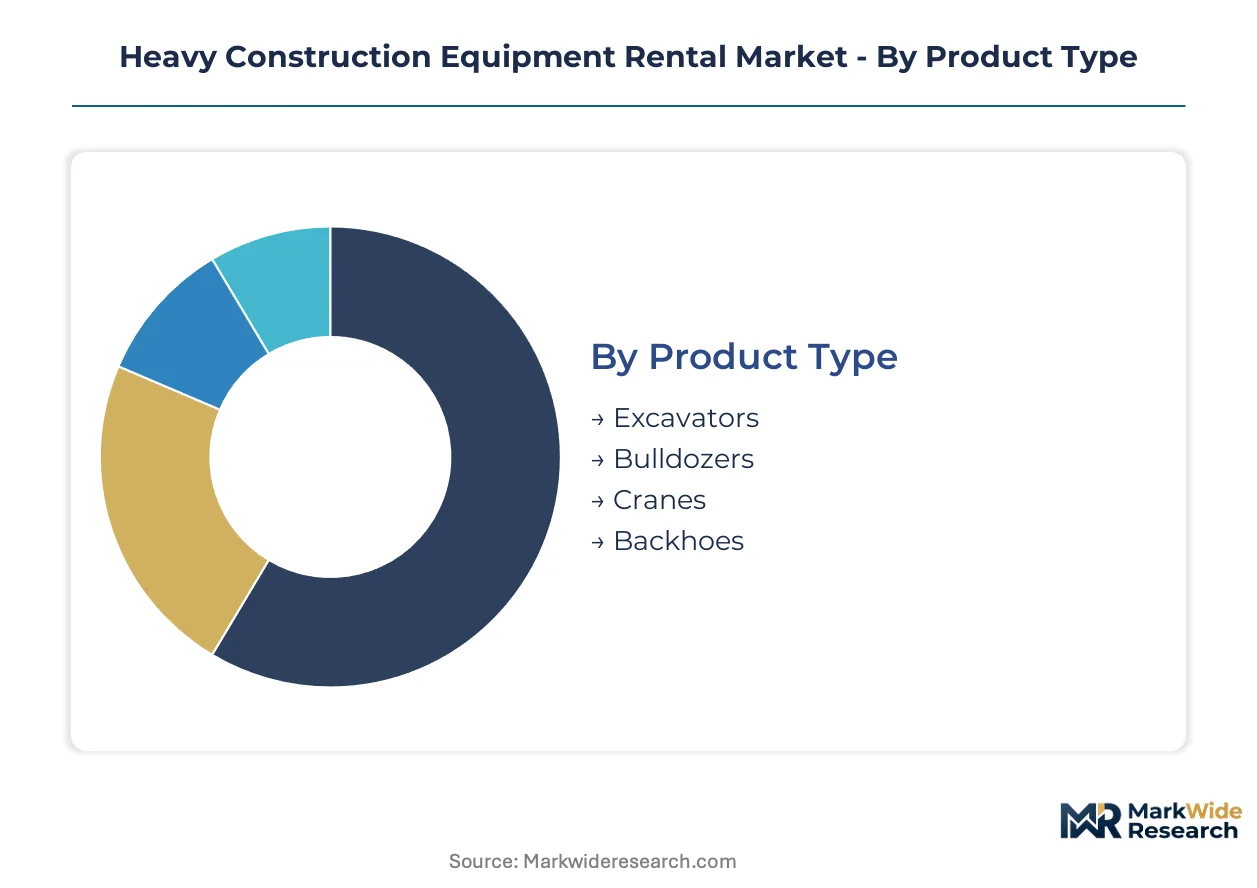
Equipment rental operators configure fleet composition and pricing architecture around how contractors manage capital intensity and utilization risk across volatile project pipelines. Segmentation reveals where rental providers can capture premium rate structures versus commodity day-rate competition.
Product Type:
Contractor procurement priorities diverge sharply between general earthmoving versatility and specialized lifting certification requirements.
- Excavators:Hydraulic track and wheel-mounted units spanning compact mini-excavators to 400,000-pound mining-class machines dominate cross-application utilization. Demand clusters in Texas data center earthwork where 30-40 ton units move mass quantities on compressed schedules, though EPA Tier 4 Final engine availability constrains fleet expansion.
- Cranes:Mobile hydraulic, crawler, and tower configurations command the steepest rate premiums due to NCCCO-certified operator attachment requirements and complex mobilization logistics. Virginia hyperscaler campuses are absorbing crawler crane capacity for multi-year lifts, creating sustained utilization premiums unavailable to other equipment categories.
- Bulldozers:Tracked dozers with powertrain ratings above 200 horsepower serve high-volume grading and push operations where Arizona desert site preparation demands dust-sealed undercarriages and extended track wear warranties.
- Backhoes:Loader-excavator combinations anchor utility and residential construction segments with lower capital barriers and shorter rental cycles, though margins compress against compact excavator substitution.
Excavators lead volumes today; cranes are gaining share fastest through data center construction concentration.
End User:
Capital structure and procurement sophistication separate price-sensitive volume buyers from relationship-driven premium accounts.
- Construction Companies:Tier-1 general contractors with bonded balance sheets negotiate multi-year master service agreements bundling equipment, fuel, and maintenance into unit-rate structures. Texas-based firms building hyperscaler campuses are converting fixed fleet ownership into variable operational expenditure through embedded service contracting.
- Government Agencies:Federal, state, and municipal procurement offices issue RFP-driven awards with prevailing wage attachments and domestic content preferences that extend award cycles and compress rental rate premiums.
- Industrial Firms:Petrochemical, mining, and manufacturing owner-operators favor long-term rental with purchase options that preserve capital allocation flexibility for core production assets rather than construction equipment.
- Contractors:Subcontractor trades—demolition, grading, concrete—rely on spot rental markets with highest price elasticity and shortest booking windows, driving rental operators toward telematics-enabled utilization optimization.
Construction companies anchor revenue concentration; industrial firms are expanding contract duration fastest.
Application:
Project scale and technical specification intensity determine where rental providers can embed service value beyond equipment provision.
- Infrastructure Development:Highway, bridge, and utility construction programs with multi-year funding visibility support fleet planning and rate stability, though federal appropriation uncertainty compresses contractor commitment horizons.
- Soil Excavation:Mass earthmoving for data center pads and residential subdivision grading consumes high-horsepower excavator and dozer capacity in Phoenix and Dallas-Fort Worth markets where equipment availability now constrains project scheduling.
- Material Handling:Telehandler and rough-terrain forklift demand tracks commercial construction verticality, with reach and load-chart specifications tightening as multi-story data center builds proliferate.
- Site Preparation:Clearing, grubbing, and initial grading operations require versatile equipment fleets with rapid mobilization capability to capture weather-dependent construction windows.
Infrastructure development sustains the largest equipment base; soil excavation is climbing the fastest on hyperscaler facility expansion.
Service Type:
Contract structure innovation is separating logistics-integrated providers from commodity lessors.
- Short-Term Rental:Daily and weekly bookings with highest fleet turnover and rate volatility serve emergency replacement and peak workload smoothing for contractors managing utilization uncertainty.
- Long-Term Rental:Multi-month to multi-year agreements with fixed rate structures and embedded maintenance provisions dominate data center construction where 18-24 month project timelines favor operational expenditure treatment.
- Leasing:Capital lease and lease-to-own structures with end-of-term purchase options appeal to contractors building owned fleet capacity without upfront capital deployment.
- Maintenance Services:Predictive uptime guarantees and on-site technician deployment are converting rental relationships into performance-based partnerships, particularly for crane fleets where OSHA certification requirements elevate service value.
Long-term rental captures the dominant revenue share; maintenance services are expanding most quickly through telematics-enabled SLA contracting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping fleet procurement patterns as rental operators migrate capital toward jurisdictions with favorable emissions enforcement timelines and infrastructure stimulus concentration. Cost-of-compliance gaps between Tier 4 Final jurisdictions and transitional markets are accelerating cross-border equipment flows.
United States
Hyperscaler data center construction in Texas, Virginia, and Arizona is absorbing crawler crane and large excavator capacity at premium utilization rates. The EPA enforces Tier 4 Final standards that constrain pre-2015 diesel fleet deployment and elevate procurement costs for compliant assets. Dallas-Fort Worth and Phoenix metropolitan clusters now face equipment availability constraints that compress rental cycles and elevate rate structures.
Germany
Industrial construction and renewable energy infrastructure sustain demand for precision lifting equipment and compact electric excavators in urban corridors. The EU Green Deal and F-Gas Regulation impose decarbonization mandates that accelerate battery-electric fleet trials in Bavaria and North Rhine-Westphalia. Munich-based contractors are negotiating performance-based equipment contracts that bundle carbon accounting with uptime guarantees.
China
Mega-infrastructure programs and urban rail expansion absorb high-volume earthmoving fleets across the Yangtze River Delta and Pearl River Delta regions. The Ministry of Ecology and Environment enforces dual carbon goals that constrain diesel equipment deployment in Beijing-Tianjin-Hebei air quality priority zones. Shanghai municipal authorities are piloting zero-emission construction zones that favor electric mini-excavators and telehandlers.
India
National highway expansion and smart city programs drive demand for motor graders and backhoe loaders across Maharashtra and Gujarat. The Central Electricity Authority construction safety codes tighten equipment inspection protocols and operator certification requirements. The Delhi-Mumbai Industrial Corridor is concentrating rental fleet deployment where contractor consolidation permits multi-year master service agreements.
United Arab Emirates
Expo legacy infrastructure and renewable energy projects sustain demand for all-terrain cranes and heavy-lift crawler configurations in Dubai and Abu Dhabi. Federal transport authorities enforce axle load regulations that shape oversize equipment logistics planning across emirate boundaries. Mohammed bin Rashid Al Maktoum Solar Park construction is absorbing specialized lifting capacity on compressed schedules that favor rental over ownership.
Heavy Construction Equipment Rental Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with national-scale rental networks commanding multi-year hyperscaler contracts while regional operators capture spot-market volatility. The vendor base concentrates around three strategic archetypes: integrated fleet networks with maintenance infrastructure, specialized crane and lifting providers with certified operator pools, and regional independents with flexible mobilization capabilities. Dominant competitive moves include telematics-enabled service bundling and geographic densification through branch network expansion.
Within the integrated network tier, United Rentals, Inc. and Sunbelt Rentals occupy positions defined by national branch coverage and multi-year contract capture. H&E Equipment Services exemplifies the maintenance-integrated archetype through technician-staffed depot positioning. These three operators anchor competitive dynamics as rental relationships shift from equipment provision toward logistics partnership models with uptime guarantee structures.
| Leading Market Players |
|---|
| United Rentals, Inc. |
| Sunbelt Rentals |
| Herc Rentals |
| Loxam Group |
| H&E Equipment Services |
| Ahern Rentals |
| Maxim Crane Works |
| Ashtead Group plc |
| Neff Rental |
| Others |
Supply & Pricing Matrix
Hyperscaler data center developers in Texas, Virginia, and Arizona anchor pricing power for rental operators through multi-year master service agreements that bundle equipment, fuel, and maintenance into unit-rate structures. This buyer concentration enables premium capture for telematics-enabled uptime guarantees while compressing spot-market margins for regional independents.
Pricing Analysis
Distributor margins on Tier 4 Final-compliant diesel-electric hybrids absorb elevated procurement costs passed through from Cummins and Caterpillar powertrain allocations. Three-tier pricing structure across premium certified-operator-attached cranes, standard excavator day-rates, and economy backhoe spot rentals reflects certification burden and mobilization complexity. Cost compression in the standard tier intensifies because steel and hydraulic component volatility erodes fleet procurement margins. Subcontractor trades exhibit highest price sensitivity due to volatile project pipelines and shortest booking windows, while Tier-1 general contractors with bonded balance sheets negotiate least-sensitive embedded service contracting.
Supply Chain Analysis
Mechatronics technician shortages in Illinois, Ohio, and Texas constrain service depot expansion for diesel-electric hybrid maintenance. Powertrain manufacturing concentrates in the United States, Sweden, and Japan, drawing from specialized steel forgings, high-pressure hydraulic cylinders, and EPA-certified emission control modules. Single-source vulnerability runs through Cummins, Caterpillar, and Volvo Penta Tier 4 Final engine allocations, exposing rental operators to production bottlenecks. Distribution runs through national branch networks with technician-staffed depots and regional independents with flexible mobilization capabilities serving spot-market demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The heavy construction equipment rental market functions as a stable compounder anchored by sustained hyperscaler facility expansion across Sun Belt growth corridors. Infrastructure stimulus concentration and emissions compliance barriers protect incumbent returns while limiting disruptive entry.
For Market Incumbents: Hedge residual value exposure on pre-2015 diesel fleets through accelerated export to Latin American and Southeast Asian markets before Tier 4 Final enforcement cliffs. Deepen backward integration into telematics platform development to capture service bundling premiums and defend against equipment-as-a-service displacement from prime contractors. For New Entrants and Emerging Players: Begin with battery-electric compact equipment deployment in California urban infill construction where CARB incentives and municipal zero-emission mandates create protected early-adopter channels. Target maintenance services for NCCCO-certified crane fleets where OSHA compliance requirements elevate technician attachment value and incumbent coverage gaps persist in secondary markets. For Investors and Strategic Acquirers: Regional equipment rental consolidators with maintenance-integrated branch networks are the most active acquirer in this space, pursuing geographic densification to capture multi-year hyperscaler contracts. Five-to-ten-year viability hinges on telematics-enabled service transformation and electric fleet transition execution. Monitor EPA enforcement intensity variance across state jurisdictions as the inflection signal for fleet standardization cost absorption and residual value realization.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | United Rentals and Sunbelt Rentals embed IoT sensors to guarantee uptime SLAs for data center contractors. |
| Electric Fleet Transition | California CARB incentives accelerate battery-electric mini-excavator trials in municipal zero-emission construction zones. |
| Maintenance Service Expansion | H&E Equipment Services positions technician-staffed depots to reduce downtime on compressed 18-24 month project schedules. |
| Geographic Densification | National operators expand branch networks in Dallas-Fort Worth and Phoenix to capture hyperscaler equipment availability constraints. |
| Secondary Market Export | Tier 3 equipment flows to Latin American contractors extend fleet economic life and improve ROIC on initial procurement. |
Research Methodology
Coverage spans the United States, Germany, China, India, and the United Arab Emirates, with primary inputs from each market. Fleet managers at United Rentals and Sunbelt Rentals, maintenance directors at H&E Equipment Services, procurement leads at Tier-1 data center contractors, and OEM powertrain specialists provided structured interviews. Secondary validation drew from EPA enforcement filings, EU Green Deal implementation reports, SEC 10-K disclosures from listed rental operators, and customs data on equipment export flows. Bottom-up equipment utilization modeling and top-down infrastructure capex aggregation enabled triangulation.
Rate-of-change decomposition across the projection horizon separates volume expansion from mix-shift effects and pricing evolution. Segmentation dimensions modeled include equipment type, service duration structure, end-user capital sophistication, and application technical intensity. CAGRs derive from equipment stock replacement cycles, hyperscaler facility construction pipelines, and regulatory compliance cost absorption curves. Tier 4 Final engine availability constraints and NCCCO-certified operator supply elasticity served as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including abrupt shifts in federal infrastructure appropriations, rapid battery-electric technology cost parity achievement, and trade policy disruptions affecting steel and hydraulic component sourcing. Forecasts reflect assumptions about sustained hyperscaler capital commitment and gradual EPA enforcement harmonization. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Hydraulic Breaker for Excavator Market
Construction Equipment
Backhoes Market
Construction Equipment
CNC Router Market
Construction Equipment
Hose End Sprayers Market
Construction Equipment
Wheeled Excavators Market
Construction Equipment
Mobile Asphalt Plant Market
Construction Equipment
Suction Excavator Market
Construction Equipment
Global Riveting Equipment Market
Construction Equipment
Welding Equipment and Consumables Market
Construction Equipment
Crossover Ladder Market
Construction Equipment
Snow Removal Equipment Market
Construction Equipment
Down-The-Hole (DTH) Hammer Bits Market
Construction Equipment
Global Dragline Excavator Market
Construction Equipment
Collating Machinery Market
Construction Equipment
Truck Mounted Knuckle Boom Cranes Market
Construction Equipment
Compact Excavator Market