
 Small Bulldozers Market | 2026-2036
Small Bulldozers Market Size, Share, and Industry Trends Forecast 2026-2036
Small Bulldozers Market Analytics
The capital-intensity divergence between full-line manufacturers and compact specialists is redrawing competitive boundaries in small bulldozers. Caterpillar Inc. leverages its integrated powertrain manufacturing to control cost structures across the under-100 HP range. Komatsu Ltd. anchors its position through proprietary hydrostatic transmission technology that reduces operator fatigue in tight-site applications. The Struck Corporation competes by specializing in ultra-lightweight designs for residential contractors with limited equipment budgets.
Small bulldozers denote tracked or wheeled earthmoving machines typically below 150 HP, engineered with hydrostatic or powershift transmissions and blade capacities under 4 cubic yards for precision grading, backfilling, and site preparation in confined spaces. Crawler bulldozers dominate rental fleet composition due to superior flotation on unprepared surfaces, while mini bulldozers represent the fastest-expanding product class as landscaping contractors and municipalities replace manual labor with mechanized solutions. The 50-100 HP engine power band captures the deepest margin pool by balancing sufficient breakout force for commercial construction against fuel economy demands from cost-sensitive farmers and municipal buyers.
EPA Tier 4 Final and EU Stage V emissions frameworks have forced widespread adoption of diesel particulate filters and selective catalytic reduction across sub-150 HP engines, adding cost but opening aftermarket service revenue streams for OEM dealer networks. Japan's METI energy-efficiency benchmarks and China's GB 20891 non-road emissions standards further fragment certification requirements for manufacturers serving multiple export destinations. Stakeholders must monitor how battery-electric powertrain trials in municipal fleets reshape total-cost-of-ownership calculations and residual value assumptions for diesel-dominated product lines.
Market Dynamics
EPA Tier 4 Final and EU Stage V emissions mandates are restructuring engine architecture across sub-150 HP bulldozers, forcing diesel particulate filter adoption and compressing margin pools for manufacturers without captive powertrain production.
Growth Catalysts
- Urban infrastructure renewal:Road-building and residential earthworks across Vietnam, Indonesia, and the Philippines are accelerating contractor procurement of compact dozers for confined-site applications.
- Emissions compliance differentiation:Stage V certification creates procurement preference hierarchies among municipal buyers in France, Germany, and Italy seeking residual value protection.
- Hydrostatic transmission maturation:Proprietary drive systems reduce operator fatigue in tight-site conditions, expanding addressable demand among landscaping contractors replacing manual labor.
Market Restraints
- Emissions hardware cost inflation:Diesel particulate filters and selective catalytic reduction systems add fixed cost to sub-100 HP engines, squeezing price-sensitive farmer and municipal segments.
- Engine supply concentration:Certified powertrain sourcing clusters among three European and Japanese suppliers, creating allocation risk during demand surges.
- Battery-electric substitution pressure:Municipal fleet electrification trials in Scandinavian cities and California counties are compressing residual value assumptions for diesel-dominated rental fleets.
Strategic Opportunities
- Philippines residential construction penetration:Mechanization rates in provincial home-building remain below 15%, creating white space for ultra-lightweight dozer specialists.
- EU Green Deal procurement preference:Carbon footprint disclosure requirements for public infrastructure tenders favor Stage V-compliant machines with verified lifecycle data.
- Telematics-RFID convergence:Integrated fleet tracking and automated maintenance scheduling enable subscription revenue models for OEM dealer networks serving multi-site contractors.
Industry Challenges
- Certification timeline fragmentation:Japan's METI energy-efficiency benchmarks, China's GB 20891 standards, and EPA Tier 4 Final create parallel testing burdens for multi-destination exporters.
- Service technician scarcity:Aftertreatment system diagnostics and SCR reagent management require specialized training that dealer networks struggle to staff in secondary Vietnamese and Indonesian markets.
- Legacy fleet integration friction:Rental companies face downtime penalties when mixing telematics-enabled new units with non-connected existing inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Small Bulldozers Market |
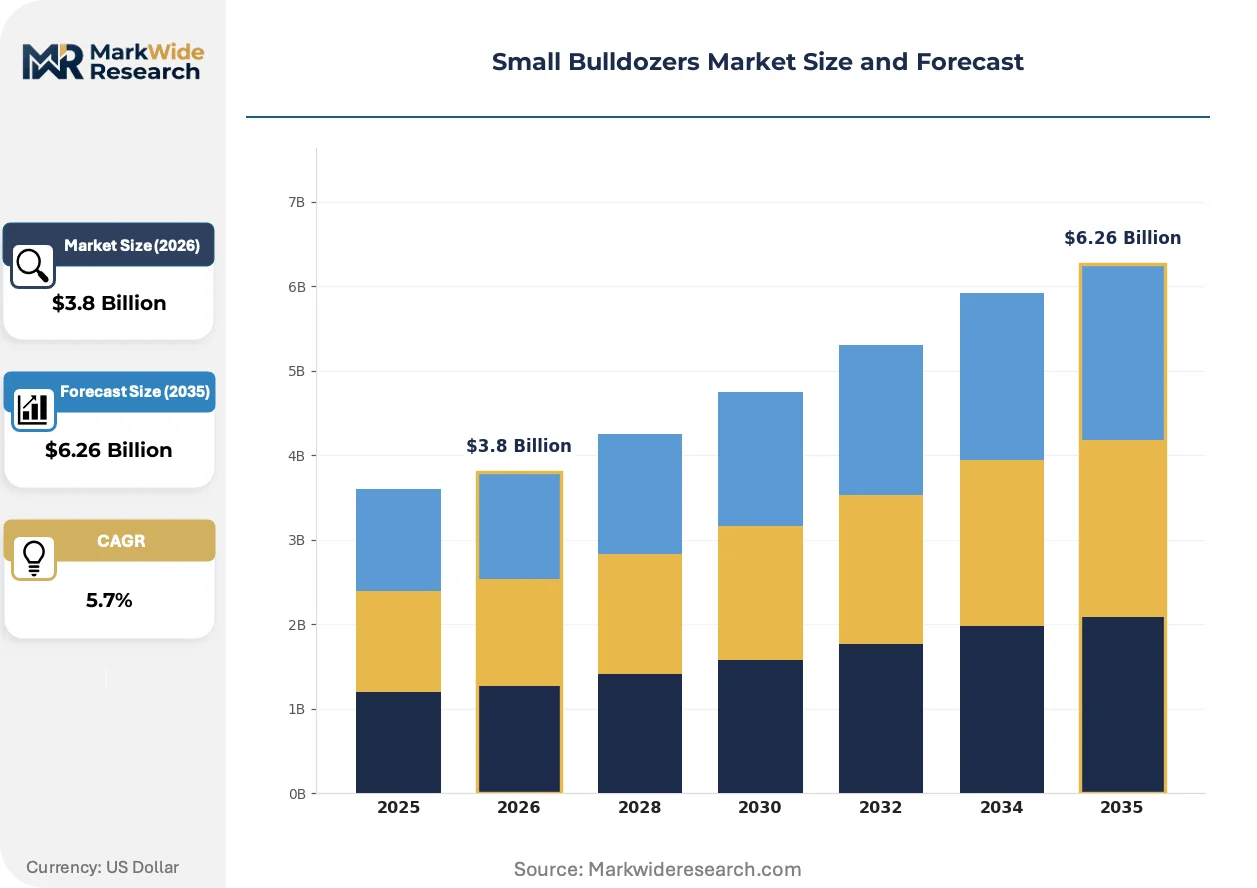
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crawler Bulldozers, Wheel Bulldozers, Mini Bulldozers, Compact Bulldozers Application: Construction, Landscaping, Mining, Agriculture End User: Contractors, Farmers, Municipalities, Resource Companies Engine Power: Less than 50 HP, 50-100 HP, 100-150 HP, More than 150 HP |
| Companies Covered | Caterpillar Inc., Komatsu Ltd, John Deere, Shantui Construction Machinery Co., Ltd., Case Construction Equipment, DEVELON, CHANGLIN, The Struck Corporation, LiuGong Machinery Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Small Bulldozers Market Evolving Landscape
Electrification pilots and digital fleet integration are compressing traditional diesel product lifecycles while opening aftermarket revenue streams for connected machine platforms.
Battery-electric powertrain architecture is decomposing the historical link between engine displacement and breakout force in sub-100 HP applications. Municipal fleet operators in Oslo and Copenhagen are trialing lithium-ion dozers for noise-sensitive urban earthworks. This technology is decomposing residual value curves for conventional diesel rental assets as carbon accounting enters procurement scoring.
EU Stage V and EPA Tier 4 Final are mandating onboard diagnostics and permanent emissions data logging across non-road engines below 150 HP. Manufacturers must now engineer tamper-proof aftertreatment systems and remote monitoring capability as standard. Compact dozers in the 50-100 HP band face the steepest compliance cost escalation, pushing procurement preference toward higher-displacement units with better fixed-cost absorption.
Rental fleet operators are unbundling maintenance contracts from equipment leases and pricing them as usage-indexed subscriptions. Independent rental houses in Texas and Florida are piloting per-hour service fees tied to telematics-reported operating severity. This shift is most visible among multi-site residential contractors in the US Sun Belt who prioritize cash-flow predictability over capital ownership.
Small Bulldozers Market Segmentation
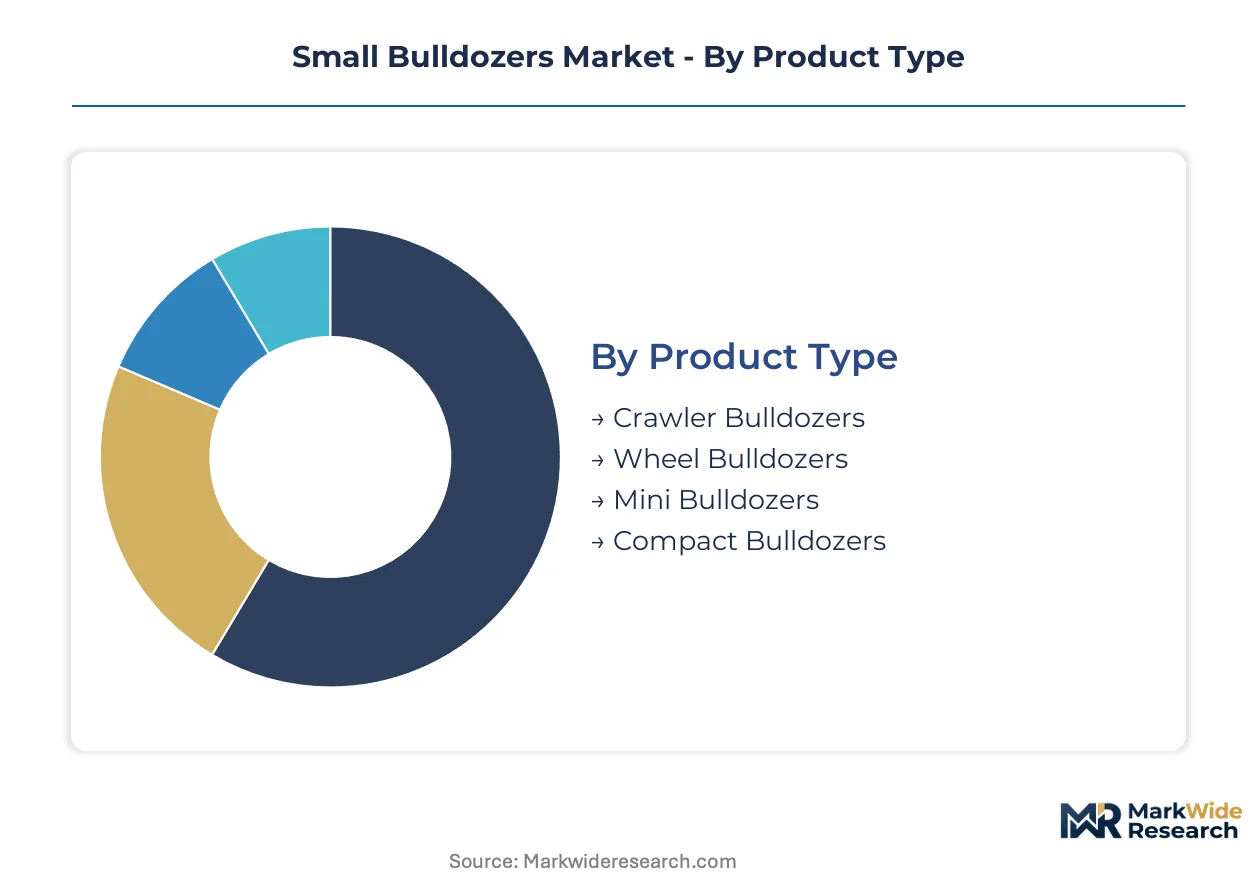
Segmentation in small bulldozers reveals how emissions certification tiers, transmission architectures, and end-use intensity create divergent margin pools across otherwise similar machine specifications. Procurement patterns fragment sharply between rental fleet operators prioritizing residual value protection and owner-operators minimizing acquisition cost.
Product Type:
EPA Tier 4 Final and EU Stage V compliance costs distribute unevenly across chassis configurations, with hydrostatic drive systems absorbing aftertreatment hardware more efficiently than mechanical powershift alternatives.
- Crawler Bulldozers:Tracked undercarriage designs distribute ground pressure below 4 psi for flotation on unprepared surfaces. Rental fleet operators in Texas and Florida concentrate procurement here for residential earthworks where site access remains unimproved.
- Mini Bulldozers:Sub-50 HP machines with blade capacities under 2 cubic yards enable precision grading in confined spaces. Landscaping contractors in Copenhagen and Oslo are piloting battery-electric variants for noise-sensitive municipal contracts.
- Wheel Bulldozers:Wheeled mobility suits hard-surface transport between dispersed job sites.
- Compact Bulldozers:Mid-range envelope balancing breakout force with transportability.
Crawler configurations handle the majority of throughput; mini bulldozers are expanding most quickly on share.
Application:
End-use intensity determines depreciation schedules and aftermarket service attach rates more than initial equipment specification.
- Construction:Commercial and residential earthmoving demands 2,000+ annual operating hours with severe duty cycles. Contractors in Vietnam, Indonesia, and the Philippines are accelerating procurement as urban infrastructure renewal intensifies.
- Mining:Surface extraction operations require reinforced undercarriage components and extended warranty coverage. Resource companies in Australia prioritize Stage V certification for carbon disclosure compliance.
- Landscaping:Intermittent usage patterns favor lease structures over ownership.
- Agriculture:Seasonal demand concentration creates utilization challenges for owner-operators.
Construction absorbs the dominant share of unit shipments; mining commands the steepest premium pricing.
End User:
Procurement sophistication varies sharply between institutional buyers with lifecycle cost models and price-sensitive owner-operators.
- Contractors:Multi-site operators with fleet standardization requirements negotiate telematics-enabled service subscriptions. Sun Belt residential specialists in the US prioritize cash-flow predictability through usage-indexed maintenance contracts.
- Municipalities:Public procurement frameworks in France, Germany, and Italy embed carbon footprint disclosure requirements favoring Stage V-compliant machines with verified lifecycle data.
- Farmers:Cost-sensitive owner-operators in secondary Vietnamese and Indonesian markets face technician scarcity for aftertreatment diagnostics.
- Resource Companies:Long-term asset holders with captive maintenance infrastructure.
Contractors drive volume absorption; municipalities are gaining procurement influence fastest through green public purchasing mandates.
Engine Power:
Fixed emissions hardware costs compress margin pools disproportionately at the low end of the power spectrum.
- 50-100 HP:The deepest margin pool balances sufficient breakout force for commercial construction against fuel economy demands. This band faces the steepest Stage V compliance cost escalation, pushing preference toward higher-displacement alternatives with better fixed-cost absorption.
- Less than 50 HP:Mini dozer segment where battery-electric trials are decomposing historical links between engine displacement and breakout force. Lithium-ion architectures in Scandinavian municipal fleets are compressing residual value assumptions for diesel rental assets.
- 100-150 HP:Upper compact range approaching mid-size equipment classification.
- More than 150 HP:Exits small bulldozer definition into standard dozer category.
The 50-100 HP band captures the majority of revenue contribution; sub-50 HP electrics are climbing the fastest on technology investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Vietnam and Indonesia exhibit the highest price elasticity, deferring procurement until equipment financing aligns with project cash flows, while municipalities in France and Germany absorb Stage V premiums without volume reduction.
United States
Sun Belt residential contractors in Texas and Florida are standardizing telematics-enabled service subscriptions to replace capital-intensive ownership models. EPA Tier 4 Final enforcement has compressed rental fleet residual values for non-compliant legacy inventory. Houston and Dallas construction clusters are absorbing the majority of crawler bulldozer shipments for unimproved site earthworks.
Germany
Municipal procurement frameworks in Bavaria and North Rhine-Westphalia embed EU Green Deal carbon disclosure requirements that favor Stage V-certified machines. KBA certification timelines for non-road engines have lengthened, creating allocation bottlenecks for compact dozer powertrains. Stuttgart industrial machinery networks are integrating aftertreatment diagnostics into dealer service portfolios.
China
Provincial infrastructure stimulus in Sichuan and Shandong is accelerating compact dozer procurement for road-building applications. GB 20891 non-road emissions standards are fragmenting certification requirements for manufacturers serving both domestic and export destinations. Yangtze River Delta fabrication clusters are absorbing the majority of hydrostatic transmission component sourcing.
Vietnam
Provincial home-building mechanization rates remain below 15%, creating white space for ultra-lightweight dozer specialists targeting cost-sensitive contractors. The country's national construction regulator has delayed equivalent emissions mandates, preserving price competitiveness for imported equipment. Ho Chi Minh City and Hanoi urban renewal corridors are concentrating demand for confined-site grading applications.
Indonesia
Island-hopping logistics constraints favor wheeled bulldozer configurations for transport between dispersed job sites. The central government's infrastructure procurement guidelines lack carbon accounting requirements, preserving diesel equipment preference. Java construction corridors around Jakarta and Surabaya are absorbing the majority of compact dozer volumes for residential earthworks.
Small Bulldozers Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated powertrain manufacturers controlling margin structures while compact specialists exploit underpenetrated price tiers. The market structures around three tiers: full-line OEMs with captive engine production, transmission-technology specialists, and regional fabricators with modular sourcing strategies. Dominant competitive moves include backward integration into aftertreatment system manufacturing and geographic expansion through distributor acquisition in Southeast Asian secondary markets.
Within the full-line OEM tier, Caterpillar Inc. and Komatsu Ltd. occupy positions defined by integrated manufacturing footprints and proprietary hydrostatic architectures. The Struck Corporation exemplifies the ultra-lightweight specialist archetype targeting residential contractors with constrained equipment budgets. Shantui Construction Machinery Co., Ltd. anchors the China-based regional fabricator segment with modular platform strategies serving price-sensitive Asian markets.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| Komatsu Ltd |
| John Deere |
| Shantui Construction Machinery Co., Ltd. |
| Case Construction Equipment |
| DEVELON |
| CHANGLIN |
| The Struck Corporation |
| LiuGong Machinery Co., Ltd. |
| Others |
Value Network & Pricing Analysis
EPA Tier 4 Final and EU Stage V emissions frameworks gate both powertrain supplier qualification and tiered price differentiation across the sub-150 HP bulldozer spectrum. Manufacturers without captive aftertreatment production absorb disproportionate cost escalation, compressing margin pools at the low-power end while Stage V certification commands procurement premiums from municipal buyers in France and Germany.
Pricing Analysis
After-sales service contracts and telematics-enabled maintenance subscriptions now drive lifetime value capture across rental fleet operators. Three-tier pricing structure across premium Stage V-certified, standard Tier 4 Final-compliant, and economy non-certified equipment segments reflects emissions hardware absorption capacity. Cost compression in the sub-50 HP band is intensifying because fixed aftertreatment costs overwhelm smaller engine displacement economics. Municipal buyers in Scandinavia exhibit lowest price sensitivity, while provincial contractors in Vietnam defer procurement until project financing aligns.
Supply Chain Analysis
Strait of Malacca transit underwrites just-in-time hydrostatic transmission component flows from Yangtze River Delta fabrication clusters to Southeast Asian assembly plants. Certified engine sourcing concentrates in Japan, Germany, and the United States, with diesel particulate filter substrates drawing from South Korean ceramic suppliers. Single-source vulnerability runs through European SCR catalyst coating capacity. Distribution runs through OEM captive dealer networks in primary markets and independent rental houses in secondary Indonesian and Vietnamese provinces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telematics-RFID convergence is transforming small bulldozers from capital equipment into connected service platforms, with interoperability standards across municipal fleet management systems reshaping competitive moats.
For Market Incumbents: Consolidate aftermarket service capacity through dealer network acquisition in Vietnamese and Indonesian secondary markets where technician scarcity threatens Stage V rollout. Deepen backward integration into aftertreatment system manufacturing to defend margin structures against European engine supplier concentration. Battery-electric substitution pressure from Oslo and Copenhagen municipal trials demands accelerated R&D allocation to lithium-ion powertrain architectures.
For New Entrants and Emerging Players: Lead with ultra-lightweight mini dozer designs targeting Philippines provincial home-building contractors where mechanization rates remain below 15%. Penetrate the landscaping contractor segment in Scandinavian cities through battery-electric variants purpose-built for noise-sensitive municipal contracts. Go-to-market execution should emphasize usage-indexed subscription pricing to displace capital-intensive ownership models among cash-flow-focused residential specialists.
For Investors and Strategic Acquirers: EU Stage V enforcement reshapes the acquisition landscape toward Stage V-certified regional fabricators with verified lifecycle data and established municipal procurement relationships. Long-term viability centers on powertrain technology transitions over the coming decade, with residual value compression risk for diesel-dominated rental fleet operators. Watch battery-electric trial expansion in California counties and Scandinavian cities as the signal for electrification inflection timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aftertreatment Manufacturing | Captive DPF and SCR production insulates margin structures against European supplier concentration. |
| Telematics-Enabled Service Subscription Launch | Per-hour maintenance fees tied to operating severity data transform rental economics for Sun Belt contractors. |
| Battery-Electric Powertrain Platform Development | Lithium-ion architectures decompose residual value curves for diesel assets in carbon-accounting procurement frameworks. |
| Dealer Network Acquisition in Southeast Asia | Control over service technician training addresses Stage V diagnostic scarcity in Vietnamese and Indonesian markets. |
| EU Green Deal Lifecycle Data Certification | Verified carbon footprint disclosure unlocks preferential scoring in French, German, and Italian public tenders. |
Research Methodology
A spread of perspectives from equipment fleet managers, municipal procurement officers, aftermarket service directors, and compact dozer OEM product planners converged on the working assumptions underlying this analysis. Primary field engagement combined structured interviews with secondary validation against customs records, EPA certification databases, EU type-approval registries, and construction equipment rental industry association filings. Bottom-up unit shipment modeling and top-down value triangulation anchored the quantitative framework.
Segmentation dimensions modeled span product type, engine power band, transmission architecture, emissions certification tier, end-use intensity, and regional regulatory cluster across the projection horizon. CAGRs were derived from elasticity-adjusted demand curves and replacement cycle analysis. Forecast inputs incorporated provincial infrastructure stimulus timelines in Vietnam and Indonesia, municipal fleet electrification trial trajectories in Scandinavia, and Stage V compliance cost absorption curves by horsepower segment.
The analysis sits within stated boundaries; outcomes outside sustained Southeast Asian infrastructure investment, stable emissions enforcement timelines, or manageable battery-electric technology cost curves would require recalibration. Forecasts reflect documented assumptions about technician training pipeline development and certified powertrain allocation capacity. Practitioners should keep alternative scenarios live as municipal electrification mandates and carbon accounting integration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Garage Equipment Market
Construction Equipment
Mortar Testing Equipment Market
Construction Equipment
Crossover Ladder Market
Construction Equipment
Friction Stir Welding Market
Construction Equipment
Welding and Cutting Equipment Market
Construction Equipment
Crane Buffer Market
Construction Equipment
Compaction Equipment Market
Construction Equipment
Global Crane and Hoist Market
Construction Equipment
Global Skid Steer Attachments Market
Construction Equipment
Sweden Construction Equipment Market
Construction Equipment
Plastic Molding Machine Market
Construction Equipment
Road Marking Equipment Market
Construction Equipment
GCC Construction Machinery Market
Construction Equipment
Cutting and Bending Machine Market
Construction Equipment
United States Crane Market
Construction Equipment
Global Dragline Excavator Market