
 Philippines Construction Equipment Market | 2026-2036
Philippines Construction Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Philippines Construction Equipment Market Insights
The gap between premium-tier and commodity-grade construction equipment is broadening as Filipino contractors face diverging project requirements. Caterpillar sustains its premium positioning through advanced telematics integration and aftermarket service density across Luzon. XCMG Group competes aggressively on upfront cost, anchoring its volume in mid-scale residential developments where capital constraints dominate procurement decisions.
Construction equipment encompasses heavy machinery engineered for earthmoving, material handling, and structural lifting operations, typically powered by diesel engines rated above 75 horsepower and built with high-tensile steel booms and reinforced undercarriages to withstand tropical humidity and monsoon exposure. Excavators dominate fleet composition due to versatility across trenching, demolition, and foundation work, while crane demand accelerates fastest as Metro Manila vertical construction intensifies. Hydraulic systems retain the largest installed base, though electric drives are gaining traction in environmentally sensitive zones near watershed areas where emissions restrictions tighten.
The Department of Public Works and Highways enforces equipment certification protocols that shape import flows and local distributor compliance costs, while the Bureau of Product Standards mandates alignment with ISO 10987 for machinery durability under tropical conditions. Contractors and fleet operators must monitor regulatory shifts around emissions benchmarking and localized assembly incentives as these will reshape total cost of ownership calculations and sourcing strategies.
Market Dynamics
The Build Better More program is compressing procurement cycles as DPWH accelerates contractor pre-qualification for road and bridge packages, forcing fleet operators to front-load equipment commitments before project awards finalize.
Growth Catalysts
- Build Better More program:The Department of Public Works and Highways is releasing multi-year infrastructure packages that lock in excavator and crane demand through guaranteed project pipelines.
- Metro Manila vertical construction:High-rise residential and commercial towers in Makati and Bonifacio Global City are driving tower crane procurement at twice the rate of other Philippine regions.
- Flood control mandates:DPWH watershed rehabilitation projects in Pampanga and Bulacan provinces require specialized amphibious excavators with reinforced undercarriages.
Market Restraints
- Diesel price volatility:Fleet operators face margin compression as fuel constitutes 35-40% of hourly operating costs for hydraulic excavators across Luzon job sites.
- Import concentration:Equipment distributors depend on single-source supply chains from Chinese and Japanese manufacturers, exposing procurement to port congestion at Manila and Batangas.
- ISO 10987 certification delays:Bureau of Product Standards tropical durability testing adds 8-12 weeks to import clearance timelines for European and North American machinery.
Strategic Opportunities
- Calabarzon secondary cities:Laguna and Cavite industrial zones lack adequate rental fleet coverage, creating white space for regional depot expansion.
- Electric drive convergence:Battery-hydraulic hybrid systems are penetrating watershed-adjacent projects where DPWH enforces emissions restrictions near Angat Dam catchments.
- Telematics unbundling:Equipment-as-a-service platforms are emerging in Davao and Cebu, separating hardware ownership from utilization-based payment structures.
Industry Challenges
- Certified hydraulic technician scarcity:Philippine vocational institutes produce insufficient graduates trained in high-pressure system diagnostics for modern excavator fleets.
- Legacy fleet integration:Contractors operating pre-2015 Japanese equipment face parts obsolescence when integrating DPWH-mandated telematics reporting modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Philippines Construction Equipment Market |
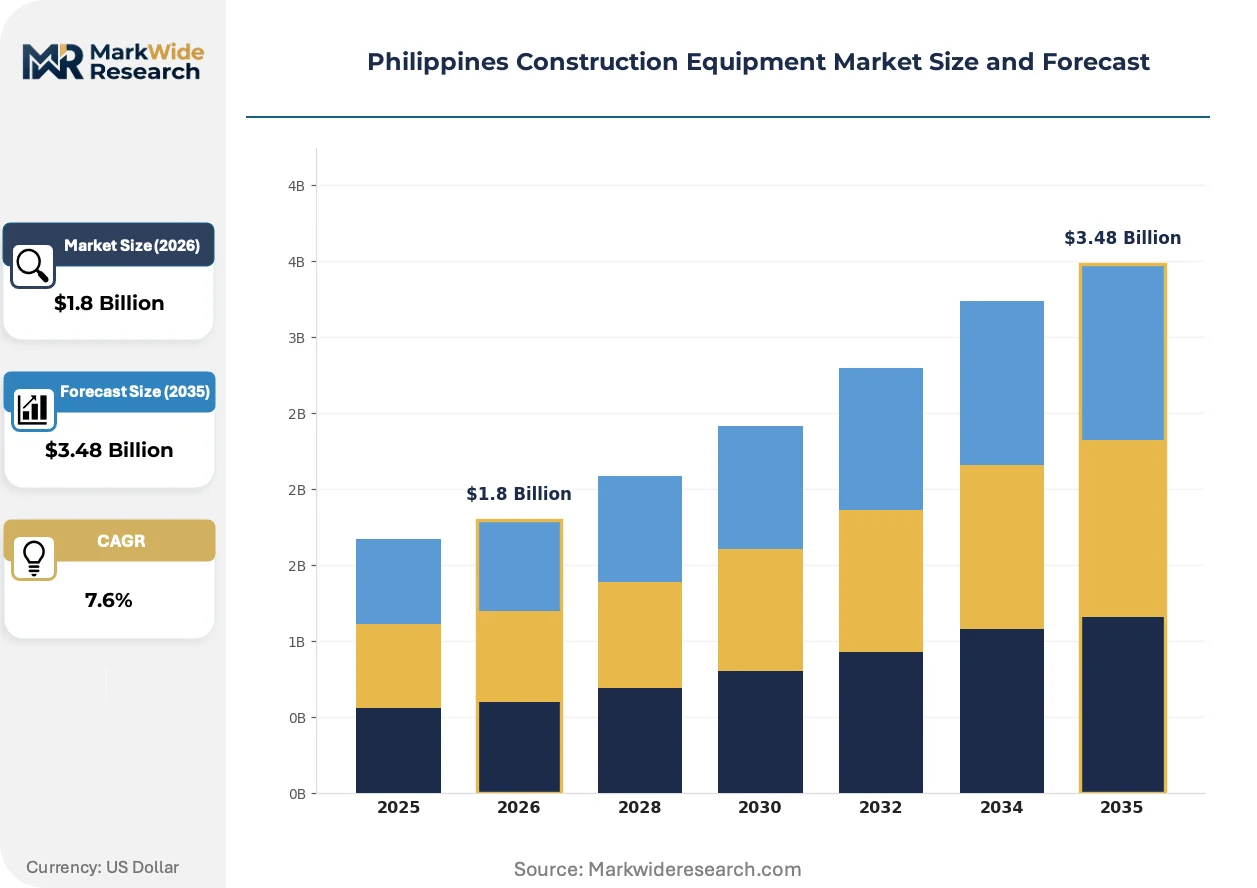
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Excavators, Cranes, Bulldozers, Loaders Application: Residential Projects, Commercial Projects, Infrastructure Development, Landscaping End User: Construction Firms, Government Agencies, Real Estate Developers, Contractors Technology: Telematics, Hydraulic Systems, Electric Drives, Robotics |
| Companies Covered | Hitachi Construction Machinery, XCMG Group, Caterpillar, Liebherr, JCB, Komatsu, SANY Group, Kobelco, Volvo Construction Equipment, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Philippines Construction Equipment Market Trends and Innovations
Three forces are restructuring how contractors acquire and operate machinery: powertrain electrification at the equipment level, regulatory tightening around emissions and durability standards, and unbundling of ownership from utilization in commercial arrangements.
Electrification is electrifying the compact equipment segment first, with battery-powered mini-excavators penetrating Metro Manila residential foundations where noise ordinances restrict diesel operation hours. Ayala Land and SM Prime contractors are piloting 3-ton electric units for basement excavation, compressing the total cost of ownership advantage that diesel historically held below 10-ton operating weights.
DPWH is tightening equipment certification protocols through alignment with ISO 10987 tropical durability standards, forcing importers to submit accelerated corrosion testing data for steel booms and undercarriage components. Japanese and Korean manufacturers with existing Southeast Asian testing facilities are adapting fastest, while European suppliers face extended validation timelines that disadvantage their bid competitiveness for government packages.
Rental-with-telemetry arrangements are displacing traditional equipment purchase-and-leaseback structures among mid-tier contractors in Calabarzon. United Rentals Philippines and local fleet operators are offering hourly-rate contracts with embedded maintenance and fuel provisioning, transferring residual value risk from contractors to lessors while capturing utilization data that shapes future procurement specifications.
Philippines Construction Equipment Market Segmentation
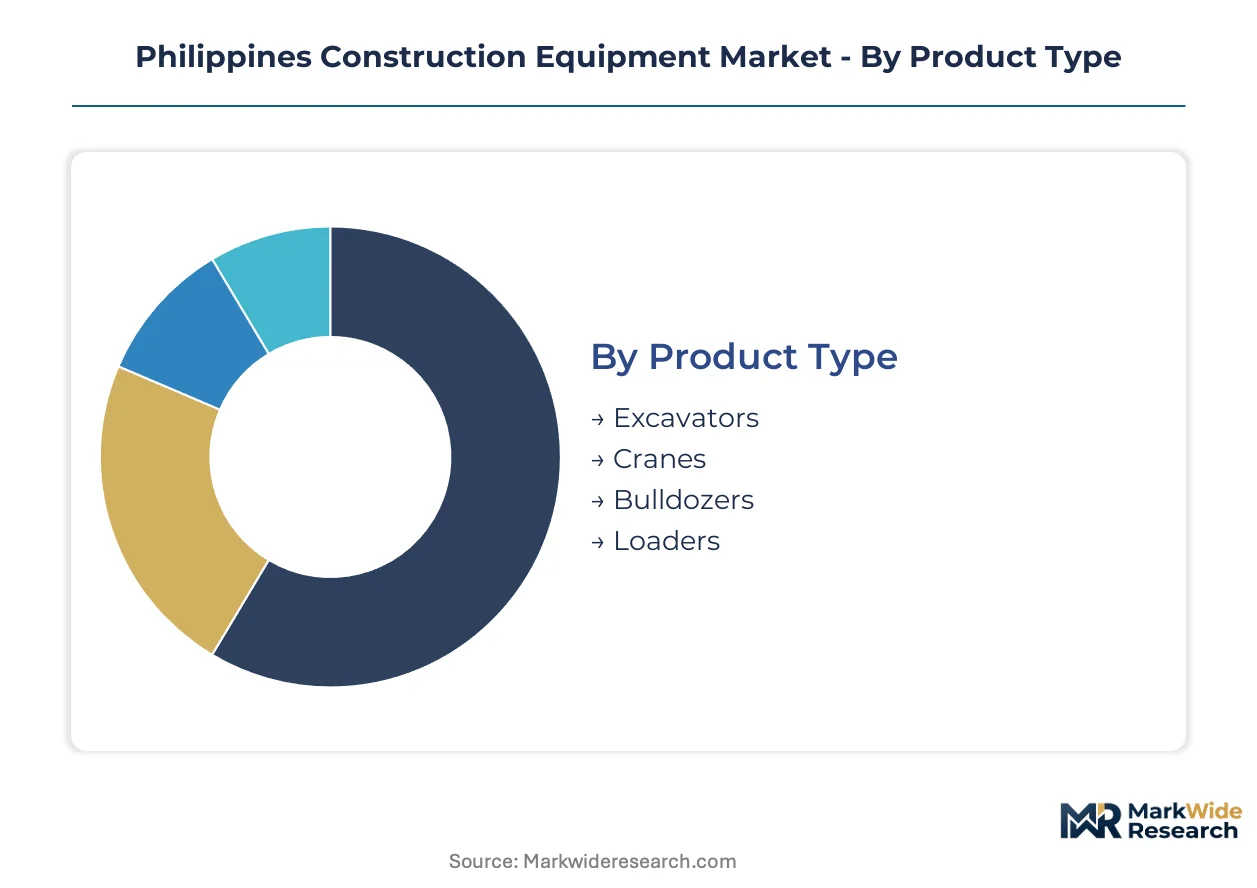
Equipment segmentation in the Philippines reveals how capital allocation priorities diverge between government infrastructure mandates and private vertical construction. Fleet operators configure procurement portfolios around project duration, regulatory compliance burdens, and residual value risk.
Product Type:
Capital intensity varies sharply across equipment categories, with long-reach excavators and tower cranes demanding the heaviest upfront outlays while commanding premium hourly rates on DPWH contracts.
- Excavators:Hydraulic crawler units with reinforced undercarriages dominate fleet composition due to versatility across trenching, demolition, and foundation work. Metro Manila basement excavation and Calabarzon flood control projects absorb the majority of new unit deployments as contractors front-load commitments ahead of Build Better More package awards.
- Cranes:Tower cranes and mobile hydraulic units engineered for structural lifting operations carry the highest capital intensity per unit. Makati and Bonifacio Global City vertical construction is driving procurement at twice the rate of other Philippine regions, with DPWH-mandated telematics integration adding compliance costs to import timelines.
- Bulldozers:Track-type tractors with high-tensile steel blades serve earthmoving and grading applications across road construction packages.
- Loaders:Wheel loaders with articulated steering handle material handling at aggregate quarries and batching plants surrounding Metro Manila.
Excavators absorb the bulk of installed capacity; cranes are expanding most quickly.
Application:
Project type determines equipment specification tiers, with infrastructure mandates enforcing ISO 10987 durability standards that residential developers often bypass.
- Infrastructure Development:DPWH road, bridge, and flood control projects require machinery certified for tropical humidity and monsoon exposure. Pampanga and Bulacan watershed rehabilitation is pulling specialized amphibious excavators with corrosion-resistant undercarriages.
- Commercial Projects:High-rise towers in central business districts demand precision lifting equipment with embedded telematics for real-time load monitoring. SM Prime and Ayala Land contractors are piloting electric mini-excavators for basement work where noise ordinances restrict diesel hours.
- Residential Projects:Mid-scale housing developments in Laguna and Cavite prioritize upfront cost over specification, anchoring demand for Chinese-manufactured hydraulic systems.
- Landscaping:Compact equipment serves aesthetic earthmoving at mixed-use developments and golf course renovations.
Infrastructure Development commands the largest equipment allocation; Commercial Projects are climbing the fastest as vertical construction intensifies.
End User:
Procurement authority concentrates differently across customer types, with government agencies enforcing standardization while developers optimize for project-specific returns.
- Construction Firms:Tier-one contractors with DPWH pre-qualification status maintain diversified fleets spanning excavators, cranes, and auxiliary equipment. These operators face compressed procurement cycles as Build Better More packages accelerate contractor selection timelines.
- Government Agencies:DPWH direct procurement enforces BIS-aligned equipment standards and ISO 10987 tropical durability certification, shaping import flows and distributor compliance costs.
- Real Estate Developers:Vertically integrated developers like Ayala Land and SM Prime specify equipment for captive construction subsidiaries, prioritizing telematics integration for fleet optimization.
- Contractors:Subcontractor fleets concentrate in rental-with-telemetry arrangements that transfer residual value risk to lessors.
Construction Firms hold the deepest installed base; Government Agencies are scaling procurement most aggressively.
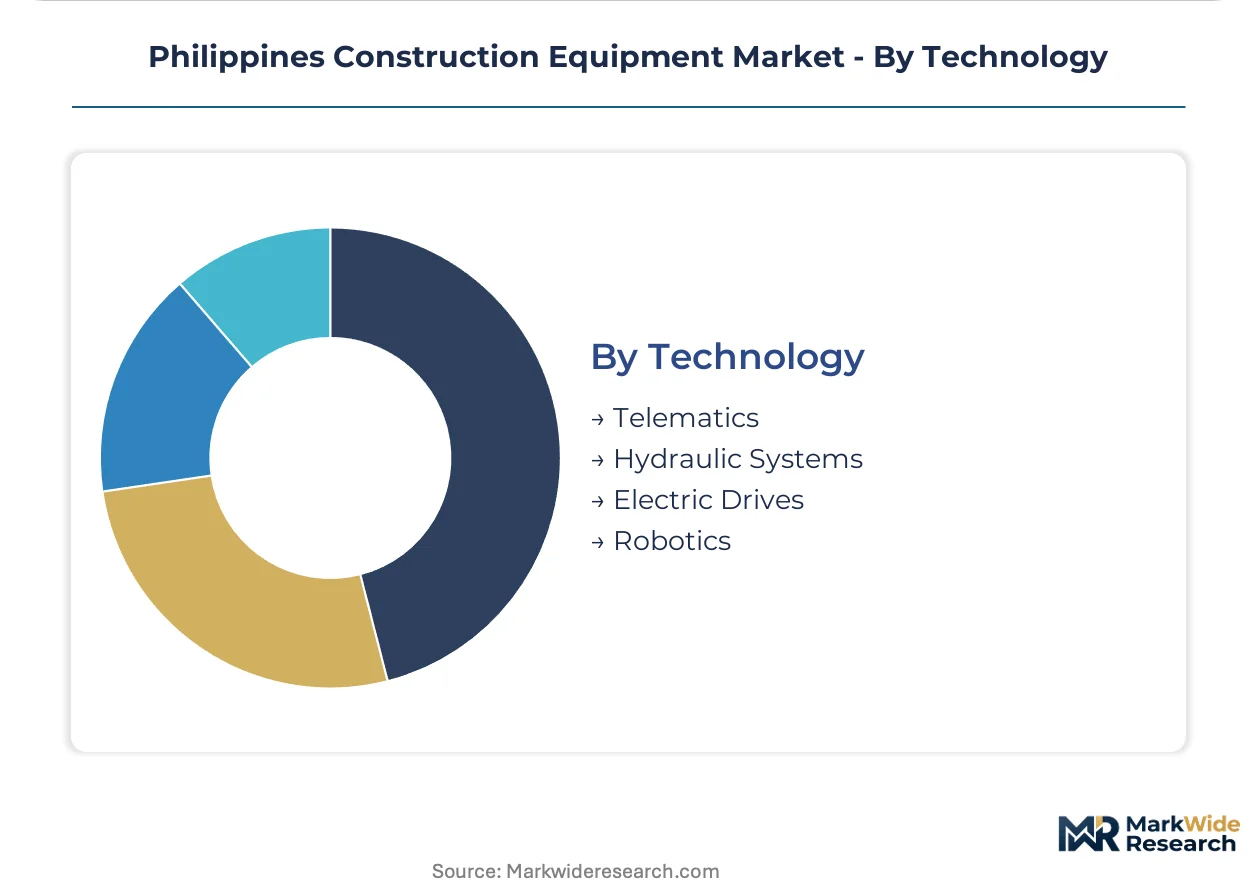
Technology:
Technology adoption stratifies by regulatory pressure and operating environment constraints, with electric penetration highest near emissions-restricted watershed zones.
- Hydraulic Systems:Diesel-powered high-pressure circuits retain the largest installed base across Luzon job sites. Fleet operators face margin compression as fuel constitutes 35-40% of hourly operating costs, though hydraulic reliability in tropical conditions sustains dominance.
- Telematics:GPS-enabled fleet management systems with real-time diagnostics are becoming mandatory for DPWH contract eligibility. Japanese and Korean manufacturers with existing Southeast Asian testing facilities are adapting fastest to certification protocols.
- Electric Drives:Battery-hydraulic hybrid systems are penetrating watershed-adjacent projects where DPWH enforces emissions restrictions near Angat Dam catchments.
- Robotics:Semi-autonomous grading and excavation functions remain nascent in Philippine adoption.
Hydraulic Systems anchor the current fleet; Telematics is gaining share fastest as regulatory mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metro Manila dominates Philippine construction equipment deployment through vertical construction clusters in Makati and Bonifacio Global City, while DPWH infrastructure corridors radiate into surrounding provinces.
Metro Manila
Tower crane demand concentrates in Makati and Bonifacio Global City high-rise developments, with basement excavation projects driving mini-excavator procurement. The Department of Public Works and Highways enforces ISO 10987 tropical durability certification for all imported machinery. Quezon City and Pasig industrial zones host fleet depots serving private contractors with rental-with-telemetry arrangements.
Calabarzon
Laguna and Cavite industrial zones absorb excavator deployments for mid-scale residential developments where capital constraints favor Chinese-manufactured hydraulic systems. The Build Better More program releases multi-year infrastructure packages that lock in equipment demand through guaranteed project pipelines. Batangas port congestion shapes import lead times for distributors serving this corridor.
Central Luzon
Pampanga and Bulacan watershed rehabilitation projects pull specialized amphibious excavators with corrosion-resistant undercarriages. DPWH flood control mandates require machinery certified for tropical humidity and monsoon exposure. Clark Freeport Zone hosts contractor pre-qualification centers accelerating fleet commitments ahead of project awards.
Visayas
Cebu and Iloilo construction markets lack adequate rental fleet coverage, creating white space for regional depot expansion. Equipment-as-a-service platforms are emerging in Cebu, separating hardware ownership from utilization-based payment structures. Mactan-Cebu International Airport expansion drives crane procurement for terminal infrastructure.
Mindanao
Davao industrial zones concentrate earthmoving demand for agro-industrial processing facilities and port modernization. DPWH Mindanao road packages accelerate excavator procurement cycles as contractor pre-qualification compresses lead times. General Santos fisheries infrastructure requires specialized material handling equipment.
Philippines Construction Equipment Market Competitive Landscape
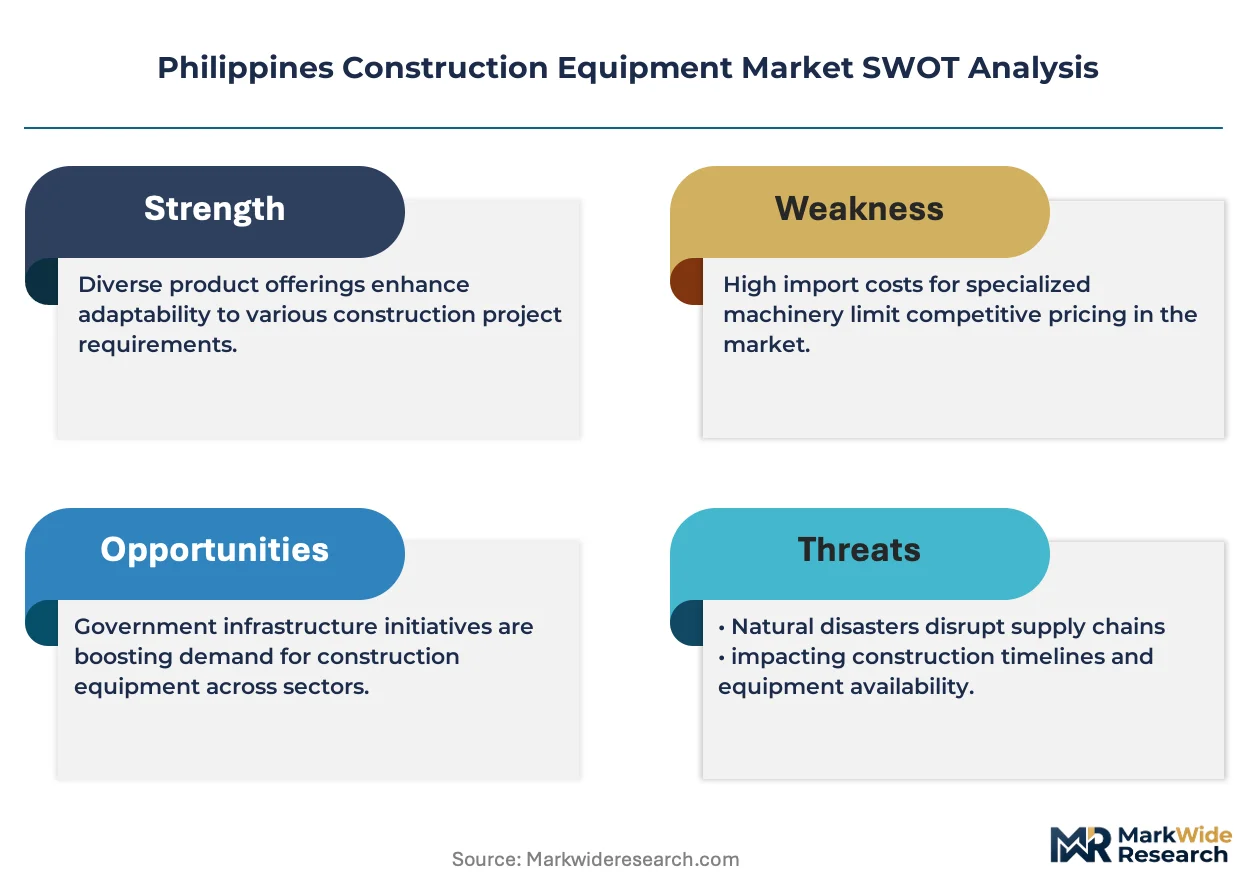
Capital-heavy producers compete with asset-light distributors across three distinct tiers. Japanese and Korean manufacturers with existing Southeast Asian testing facilities adapt fastest to DPWH certification protocols. Chinese suppliers anchor the upfront-cost-sensitive segment. European and North American suppliers face extended validation timelines. Strategic moves concentrate on telematics integration partnerships and regional depot expansion into underserved secondary cities.
Among Japanese heavy machinery specialists, Hitachi Construction Machinery and Komatsu occupy positions within the premium-tier certification-advantaged segment. Caterpillar exemplifies the integrated-service-density archetype through aftermarket coverage across Luzon. XCMG Group and SANY Group represent the volume-driven Chinese manufacturing tier competing on capital efficiency for mid-scale residential developments.
| Leading Market Players |
|---|
| Hitachi Construction Machinery |
| XCMG Group |
| Caterpillar |
| Liebherr |
| JCB |
| Komatsu |
| SANY Group |
| Kobelco |
| Volvo Construction Equipment |
| Others |
Pricing and Supply Chain Analysis
Battery-hydraulic hybrid powertrain adoption is compressing total cost of ownership calculations for compact excavators while concentrating procurement authority among lessors with capital to absorb residual value risk. This technology transition simultaneously reshapes hourly rate structures and distributor consolidation patterns across Luzon.
Pricing Analysis
Hourly utilization rates anchor equipment pricing in the Philippines, with rental-with-telemetry arrangements transferring fuel cost volatility from contractors to fleet operators. Pricing stratifies across premium, standard, and economy tiers based on ISO 10987 certification status and embedded telematics capability. Cost compression in the Chinese-manufactured tier is intensifying because Batangas port congestion extends import lead times and inflates working capital requirements. Mid-scale residential developers in Laguna and Cavite exhibit highest price sensitivity, while DPWH pre-qualified tier-one contractors prioritize uptime guarantees over upfront capital outlays.
Supply Chain Analysis
Authorized distributor networks with regional depot coverage handle downstream equipment flows to contractor fleets across Metro Manila and Calabarzon. Manufacturing concentration rests on China, Japan, and South Korea for hydraulic system components and complete machine assemblies. High-tensile steel booms, corrosion-resistant undercarriage plating, and Tier 4 diesel powertrains constitute critical input dependencies. Single-source vulnerability runs through Manila and Batangas port corridors where customs clearance delays cascade into project timeline disruptions. Distribution runs through Japanese and Korean OEMs with established Southeast Asian testing facilities that accelerate ISO 10987 certification timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Philippines construction equipment market is becoming a vertical-integration race as fleet operators seek captive control over maintenance labor pools and telematics data streams to defend margin structures.
For Market Incumbents: To counter XCMG Group's capital-efficiency challenge in mid-scale residential procurement, tier-one distributors should anchor backward integration into certified hydraulic technician training academies and expand regional depot coverage into underserved Visayas secondary cities. Channel control over aftermarket parts inventory represents the priority defensive lever. For New Entrants and Emerging Players: The premium-to-economy price-point gap in amphibious excavator specifications offers entry traction for specialized manufacturers targeting DPWH watershed rehabilitation mandates in Pampanga and Bulacan. Equipment-as-a-service platforms in Cebu and Davao present the most penetrable white space, with utilization-based payment structures as the differentiated go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with regional rental fleet operators possessing telematics infrastructure and DPWH pre-qualification status given Build Better More program acceleration. Long-term viability hinges on residual value risk management capabilities and technician labor pool depth. Monitor DPWH emissions restriction expansion beyond Angat Dam catchments as the inflection signal for electric drive penetration rates.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Technician Training Academy | Addresses Bureau of Product Standards compliance gaps while locking in aftermarket service revenue streams. |
| Regional Depot Expansion | Captures underserved Visayas demand where rental fleet coverage remains inadequate for contractor procurement cycles. |
| Telematics Platform Integration | Enables DPWH-mandated real-time reporting while generating utilization data for future equipment specifications. |
| Electric Drive Pilot Programs | Positions fleets for watershed-adjacent project eligibility where emissions restrictions tighten near Angat Dam. |
| Long-Term Supply Agreement | Secures high-tensile steel boom allocations from Japanese mills to buffer against port congestion volatility. |
Research Methodology
DPWH procurement databases, Bureau of Product Standards certification records, and customs import declarations formed the secondary backbone of this analysis. Primary interviews with fleet operations directors, equipment maintenance supervisors, DPWH contract procurement officers, and regional distributor sales heads validated demand assumptions. Bottom-up triangulation against top-down infrastructure spending allocations ensured segmentation integrity across the analysis window.
Historical trendline analysis of equipment import volumes and rental fleet utilization rates established baseline growth patterns. The analytical framework modeled product type, application, end user, and technology dimensions throughout the forecast period. CAGRs were derived from project pipeline commitments under Build Better More program releases and vertical construction permit approvals in Makati and Bonifacio Global City.
Inputs from DPWH contractor pre-qualification registries were available through the study window; gaps in real-time rental rate transparency introduce uncertainty bands around equipment-as-a-service platform penetration assumptions. Forecasts reflect documented assumptions regarding diesel price trajectories and certification timeline standardization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Construction Site Preparation Equipment Market
Construction Equipment
Global Crane and Hoist Market
Construction Equipment
Screw Compressor Rental Market
Construction Equipment
Collating Machinery Market
Construction Equipment
Vertical Mill Market
Construction Equipment
Compaction Equipment Market
Construction Equipment
Heavy Construction Equipment Rental Market
Construction Equipment
Global Light Towers Market
Construction Equipment
Stamping Machines Market
Construction Equipment
Autonomous Construction Equipment Market
Construction Equipment
Global Cone Crusher Market
Construction Equipment
Crane Buffer Market
Construction Equipment
Wood Chipping Machinery Market
Construction Equipment
Bale Openers Market
Construction Equipment
Malaysia Plastic Injection Molding Machine Market
Construction Equipment
North America Drilling Market