
 Self-Pierce Riveting (SPR) Equipment Market | 2026-2036
Self-Pierce Riveting (SPR) Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Self-Pierce Riveting (SPR) Equipment Market Insights
Aftermarket service revenue for die refurbishment and process calibration is reshaping margin distribution across the SPR value chain. Atlas Copco sustains technology leadership through its automated fastening platforms for automotive assembly lines. TOX PRESSOTECHNIK specializes in precision press-fit systems that dominate European appliance and automotive supplier networks. Henrob Ltd. anchors its position in aerospace-grade SPR applications requiring fatigue-resistant joint performance.
Self-pierce riveting equipment mechanically joins sheet materials without pre-drilled holes by driving a rivet through multiple layers using a punch and die set operating at forces between 30 and 200 kN, creating a permanent mechanical interlock primarily used in aluminum and mixed-metal assemblies where welding introduces thermal distortion or material incompatibility. Pneumatic riveting machines lead unit shipments across high-volume automotive body shops, while semi-automatic riveting systems capture expanding margins in electronics and medical device enclosures where lot-size flexibility outweighs pure cycle speed. Automated control systems integrating force-displacement monitoring represent the fastest-growing technology segment as manufacturers tighten joint traceability under quality mandates.
FDA device manufacturing standards and EU MDR traceability requirements shape SPR equipment specifications in medical and aerospace end uses, while OSHA machine guarding directives and CE marking obligations govern equipment deployment across US and European factory floors. China's GB standards and MIIT equipment certification create parallel compliance pathways for suppliers serving domestic automotive joint ventures. Stakeholders must weigh captive SPR deployment against contract fastening services as aluminum content thresholds in vehicle platforms reset tooling investment timelines.
Market Dynamics
Automotive OEMs are reconfiguring body-in-white assembly architectures around aluminum-intensive platforms, forcing a wholesale replacement of resistance spot welding infrastructure with mechanical fastening systems that accommodate dissimilar metal stacks without thermal distortion.
Growth Catalysts
- EU F-Gas Regulation:Restrictions on fluorinated greenhouse gases in manufacturing processes eliminate adhesive bonding alternatives for mixed-metal joints, compelling adoption of purely mechanical fastening solutions in European automotive supplier networks.
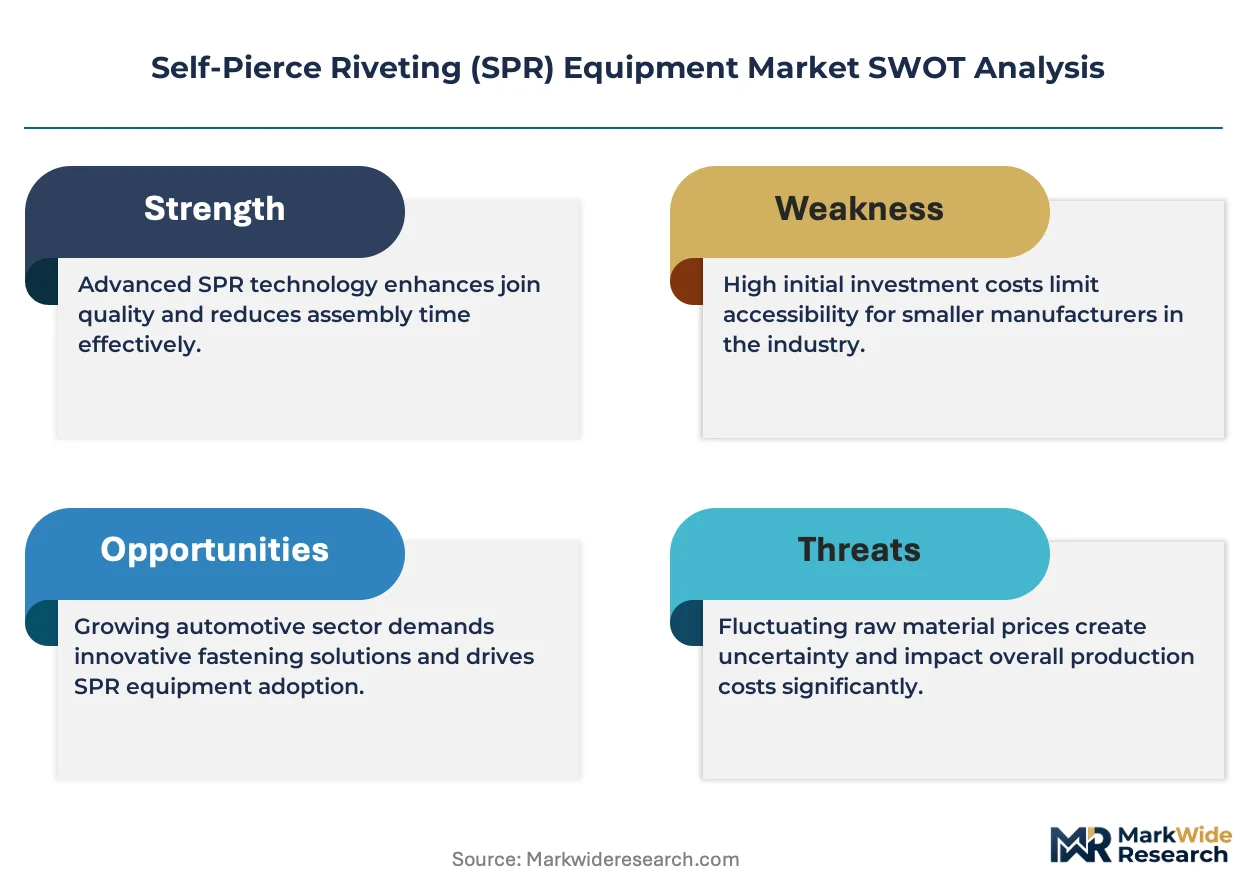
- Aluminum sheet penetration:Vehicle platform architectures now specify aluminum content thresholds exceeding 50% by mass in closure panels and structural members, creating captive demand for cold-forming joining technologies incompatible with conventional fusion welding.
- Force-displacement monitoring:Real-time process control systems integrating piezoelectric sensors and predictive algorithms enable 100% joint traceability, satisfying aerospace and medical device quality mandates without destructive testing protocols.
Market Restraints
- Tool steel input volatility:Punch and die sets require vacuum-remelted tool steels with carbide coatings; supply concentration in Austrian and Swedish specialty steel mills exposes equipment margins to alloy surcharge fluctuations.
- Die refurbishment economics:High-volume automotive lines consume dies every 50,000-80,000 cycles, creating recurring capital intensity that favors contract fastening service providers over captive equipment ownership.
- Structural adhesive substitution:Two-part epoxy systems from Henkel and 3M achieve comparable shear strength in laboratory conditions, threatening SPR penetration in non-structural cosmetic panels where fatigue resistance is secondary.
Strategic Opportunities
- India automotive joint ventures:Maruti Suzuki and Hyundai Motor India are localizing aluminum body manufacturing for export markets, creating first-mover advantage for SPR equipment suppliers establishing technical service presence in Manesar and Sriperumbudur.
- Battery enclosure assembly:Electric vehicle battery tray architectures require hermetic sealing of aluminum extrusions with steel mounting brackets, an application where SPR's cold-forming mechanism preserves cell-adjacent thermal management coatings.
- EU MDR traceability mandates:Medical device manufacturers must maintain device history records per Article 10, creating pull for automated riveting systems with integrated data logging that satisfies notified body audit requirements without manual documentation.
Industry Challenges
- Process engineer scarcity:Joint design optimization for multi-layer aluminum-to-magnesium stacks requires expertise in finite element modeling of plastic deformation zones, a skill set concentrated among retired aerospace specialists and thinly distributed across automotive supplier engineering departments.
- CE marking compliance timelines:Machinery Directive conformity assessment for automated SPR cells involves third-party review of safety control systems, extending equipment delivery schedules by 12-16 weeks and compressing window for production line commissioning.
- Legacy welding infrastructure stranding:Body shops with depreciated resistance spot welding robots face sunk-cost bias against full-line replacement, requiring hybrid retrofit solutions that integrate SPR heads onto existing gantry systems with compromised cycle time performance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self-Pierce Riveting (SPR) Equipment Market |
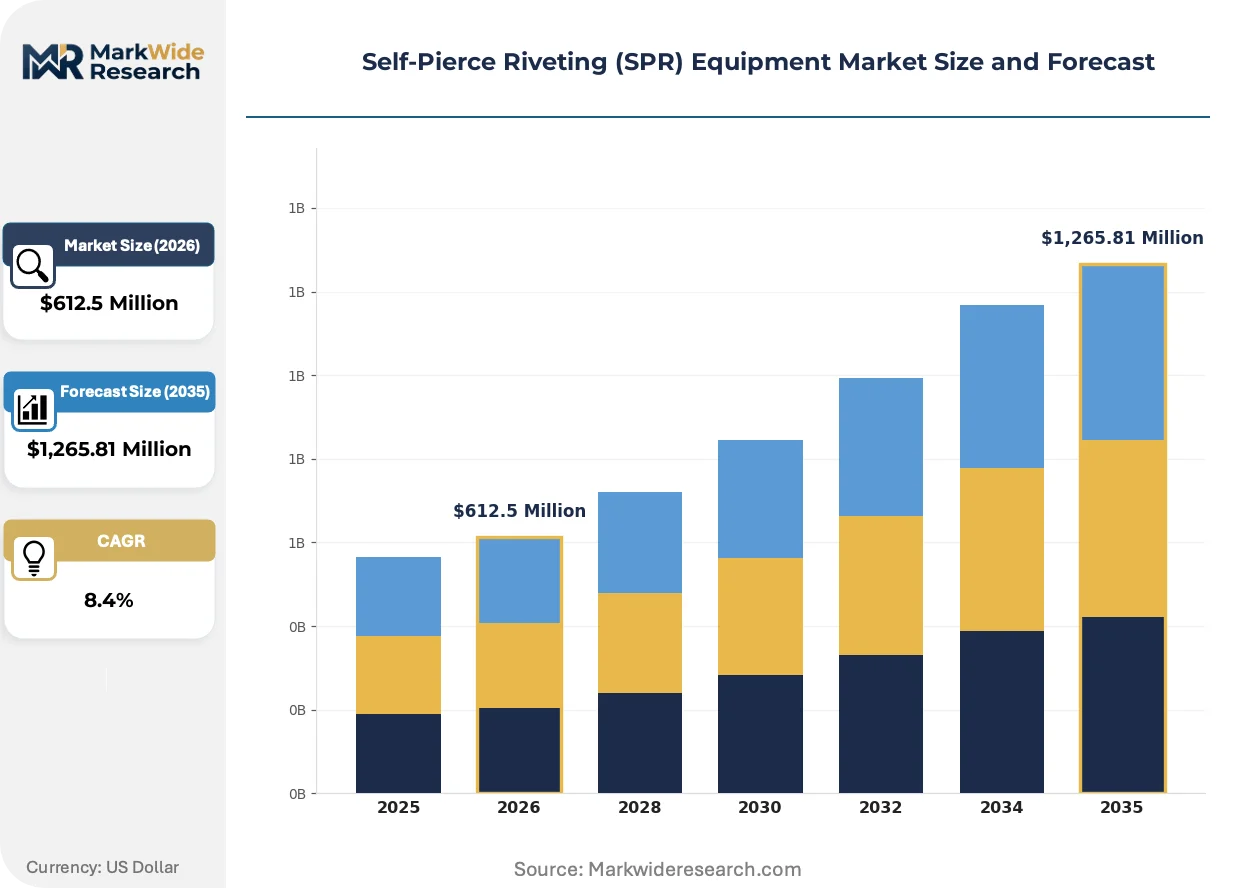
| Market Size in 2026 | $612.5 Million |
| Market Size in 2035 | $1,265.81 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Riveting Machines, Pneumatic Riveting Machines, Manual Riveting Tools, Semi-Automatic Riveting Systems Technology: Laser-Assisted, Ultrasonic Riveting, Magnetic Riveting, Automated Control Systems End User: Aerospace, Automotive Manufacturing, Electronics, Construction Equipment Installation: Fixed Installation, Mobile Units, Integrated Solutions, Standalone Systems |
| Companies Covered | STANLEY Engineered Fastening, Atlas Copco, TOX PRESSOTECHNIK, GESIPA, Bollhoff, ECKOLD, Hilti Corporation, SFS Group, Henrob Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self-Pierce Riveting (SPR) Equipment Market Trends and Innovations
Servo-electric press technology is displacing hydraulic actuation across precision joining applications, enabling force-profile programming that adapts to material stack variations in real time without mechanical adjustment.
Electromechanical servo presses with ball-screw or linear motor drives deliver closed-loop force control within 1% tolerance across 30-200 kN ranges, rendering obsolete hydraulic systems with their fluid maintenance burden and thermal drift limitations. Tier 1 automotive suppliers in Germany and Japan are specifying all-electric platforms for new greenfield installations. The shift compresses equipment footprint by 40% while eliminating EPA-regulated hydraulic fluid disposal liabilities.
REACH Annex XVII restrictions on chromium(VI) compounds in surface treatments are forcing conversion from conventional zinc-phosphate pretreatments to thin-film organic coatings for aluminum sheet. This regulatory pressure elevates SPR's competitive position against clinching technologies that rely on coefficient-of-friction consistency. European coil coating lines serving automotive OEMs are certifying rivet-penetration performance on new substrate preparations ahead of 2026 enforcement deadlines.
Aftermarket service contracts are unbundling from initial equipment sales as buyers prioritize operational expenditure flexibility over capital ownership. Tier 2 automotive suppliers in China's Yangtze River Delta increasingly procure fastening-as-a-service arrangements where die refurbishment and process calibration are vendor-managed. This consumption-pattern shift concentrates margin capture with equipment manufacturers possessing regional technical service density rather than pure hardware vendors.
Self-Pierce Riveting (SPR) Equipment Market Segmentation
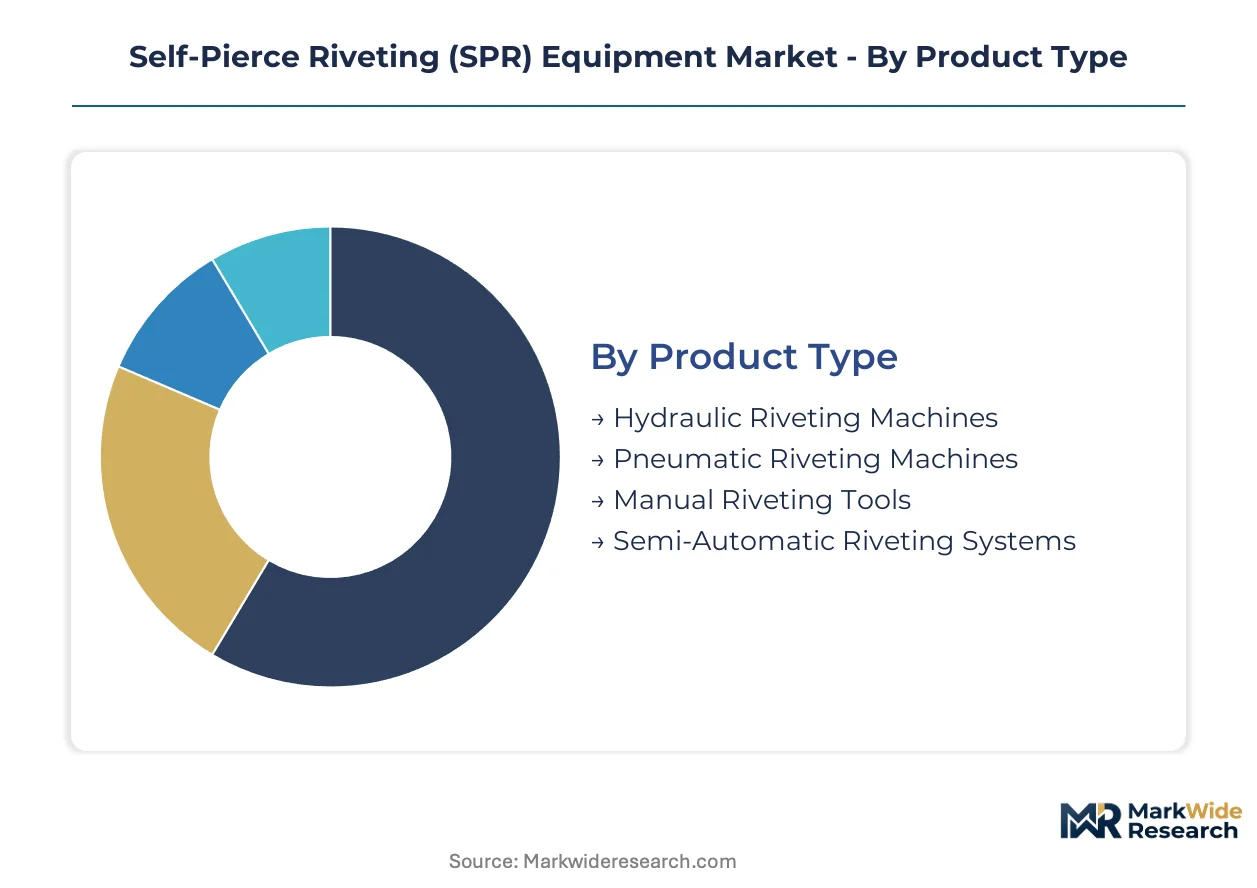
SPR equipment segmentation reveals how joining technology adapts to divergent production environments, from high-volume automotive lines demanding cycle-time precision to medical device workshops requiring lot-size flexibility. Equipment specifications, actuation methods, and integration architectures segment the market into distinct procurement categories with incompatible performance profiles.
Product Type:
Actuation technology defines the cost-performance frontier across factory floors, with pneumatic and hydraulic systems anchoring opposite ends of the capital-intensity spectrum.
- Hydraulic Riveting Machines:Fluid-power actuation delivers 100-200 kN force ranges for thick-stack aluminum extrusions in commercial vehicle chassis. Demand concentrates in Germany's commercial vehicle supplier belt around Munich, where MAN and Scania joint ventures specify hydraulic platforms for frame rail assembly.
- Pneumatic Riveting Machines:Compressed-air systems achieve 30-80 kN outputs with faster cycle times and lower capital outlay, dominating high-volume automotive body shops. Volkswagen's Wolfsburg and Chattanooga plants specify pneumatic cells for closure panel lines where throughput exceeds 60 joints per minute.
- Manual Riveting Tools:Hand-held pneumatic units serve prototype shops and low-volume aerospace MRO facilities.
- Semi-Automatic Riveting Systems:Operator-assisted platforms with programmable force profiles capture medical device and electronics enclosure applications.
The dominant share belongs to Pneumatic Riveting Machines, while Semi-Automatic Riveting Systems are expanding most quickly as contract manufacturers prioritize operational expenditure flexibility over capital ownership.
Technology:
Process innovation clusters around energy-assisted joining and closed-loop quality assurance, with automation architectures commanding premium positioning.
- Automated Control Systems:Force-displacement monitoring with piezoelectric sensors enables real-time joint quality verification without destructive testing. EU MDR traceability mandates and FDA 21 CFR Part 820 requirements pull these systems into medical device manufacturing, where device history records must capture 100% of critical joining operations.
- Laser-Assisted:Pre-heating of high-strength aluminum alloys reduces punch force requirements and extends die life in aerospace-grade applications.
- Ultrasonic Riveting:High-frequency vibration assists rivet penetration in brittle magnesium alloys for electronics housings.
- Magnetic Riveting:Electromagnetic pulse forming enables micro-joining for consumer electronics with sub-millimeter material thicknesses.
Automated Control Systems command the highest equipment margins, while Laser-Assisted platforms are gaining share fastest in aerospace tier-1 supplier networks.
End User:
Industry-specific quality mandates and material portfolios dictate equipment specification divergence across vertical markets.
- Automotive Manufacturing:Body-in-white and battery enclosure assembly drive volume demand, with aluminum-intensive platforms from Tesla, BMW, and Mercedes-Benz specifying SPR for mixed-metal joints where welding introduces thermal distortion. The EU F-Gas Regulation accelerates mechanical fastening substitution for adhesive bonding in European supplier networks.
- Aerospace:Fatigue-resistant joint performance for aluminum-lithium fuselage panels requires precision force control and aerospace-grade die materials.
- Electronics:Miniaturization trends push demand for micro-riveting in smartphone and laptop chassis.
- Construction Equipment:Thick-gauge steel and aluminum cab structures require high-force hydraulic platforms.
Automotive Manufacturing absorbs the largest equipment shipments, though Aerospace applications sustain the steepest pricing premiums per installed unit.
Installation:
Deployment architecture reflects capital strategy preferences and production layout constraints across manufacturing footprints.
- Integrated Solutions:Robot-mounted SPR heads on existing gantry systems address stranded welding infrastructure in legacy body shops. Tier 1 suppliers in Stuttgart's automotive cluster favor retrofit integration to preserve depreciated automation assets while adding aluminum joining capability.
- Fixed Installation:Dedicated cells for high-volume single-product lines dominate OEM captive operations.
- Mobile Units:Portable systems serve MRO and field repair applications in aerospace and construction equipment.
- Standalone Systems:Self-contained workcells accommodate job-shop environments with frequent product changeovers.
Integrated Solutions hold the largest installed base, while Mobile Units are climbing fastest as aftermarket service models expand beyond factory walls.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany's automotive supplier belt show the lowest price elasticity, absorbing premium equipment costs for force-displacement traceability. India's emerging joint ventures exhibit highest sensitivity, prioritizing operational expenditure models over capital ownership. China's domestic OEMs occupy a middle position, balancing MIIT certification requirements against total cost of ownership pressures.
Germany
Stuttgart's automotive cluster drives demand for servo-electric press platforms with real-time quality monitoring. The EU F-Gas Regulation eliminates adhesive bonding alternatives for mixed-metal joints, compelling mechanical fastening adoption. Wolfsburg and Munich supplier networks specify automated SPR cells for aluminum-intensive body-in-white architectures.
United States
OSHA machine guarding directives and EPA hydraulic fluid disposal liabilities accelerate electromechanical platform adoption. NHTSA fuel economy standards push aluminum content thresholds in closure panels. Detroit's Tier 1 suppliers retrofit existing gantry systems with integrated SPR heads to preserve depreciated welding assets.
China
MIIT equipment certification and GB standards create parallel compliance pathways for domestic automotive joint ventures. Dual carbon goals elevate aluminum penetration in vehicle platforms to reduce mass-related emissions. Yangtze River Delta contract manufacturers increasingly procure fastening-as-a-service arrangements with vendor-managed die refurbishment.
India
Maruti Suzuki and Hyundai Motor India localize aluminum body manufacturing for export markets, creating first-mover opportunity for technical service presence. PLI scheme incentives for advanced automotive components support capital equipment investment. Manesar and Sriperumbudur industrial corridors concentrate demand for semi-automatic systems with lot-size flexibility.
Japan
METI industrial standards and JIS certification requirements shape equipment specifications for precision joining applications. Automotive OEMs specify force-profile programming capabilities for high-strength aluminum-lithium alloys. Nagoya's aerospace supplier network demands fatigue-resistant joint performance with 100% traceability documentation.
Self-Pierce Riveting (SPR) Equipment Market Competitive Landscape
Capability concentration sits with specialized European press-fit system builders; scale advantage sits with diversified industrial automation conglomerates. The vendor base organizes into three strategic archetypes: integrated fastening platform providers, precision press specialists, and regional equipment fabricators. Consolidation pressures favor technology licensing partnerships over horizontal mergers. Geographic expansion through technical service density represents the dominant competitive move alongside portfolio diversification into battery enclosure assembly applications.
Among diversified industrial technology groups, Atlas Copco anchors the integrated platform tier with automated fastening systems for high-volume automotive lines. TOX PRESSOTECHNIK GmbH & Co. KG exemplifies the precision press specialist archetype, occupying a dominant position in European appliance and automotive supplier networks. Henrob Ltd. represents the aerospace-grade application segment, sitting within the fatigue-resistant joint performance tier where regulatory traceability mandates command premium positioning.
| Leading Market Players |
|---|
| STANLEY Engineered Fastening |
| Atlas Copco |
| TOX PRESSOTECHNIK |
| GESIPA |
| Bollhoff |
| ECKOLD |
| Hilti Corporation |
| SFS Group |
| Henrob Ltd. |
| Others |
Pricing and Supply Chain Analysis
Austrian and Swedish vacuum-remelted tool steel concentration determines both three-tier pricing structure across premium, standard, and economy levels and supply chain configuration for punch and die sets. Buyers absorbing CE-marked servo-electric platforms with force-displacement monitoring pay 40-60% premiums over pneumatic baseline systems, while contract fastening-as-a-service arrangements compress upfront capital requirements into operational expenditure streams.
Pricing Analysis
Long-term offtake contracts with automotive OEMs anchor pricing for high-volume pneumatic installations, while project-based procurement dominates battery enclosure and medical device applications. Price differentiation rests on certification tier—EU MDR traceability systems and FDA 21 CFR Part 820 compliant platforms command substantial premiums over baseline CE-marked equipment. Pricing pressure stems from die refurbishment cycle economics favoring vendor-managed service models over captive ownership. Tier 2 suppliers in China's Yangtze River Delta exhibit highest price sensitivity; German automotive clusters show lowest elasticity for traceability-integrated systems.
Supply Chain Analysis
Extended payment terms from European automotive OEMs cascade through supplier financing facilities to Austrian and Swedish specialty steel mills producing vacuum-remelted tool steels. Manufacturing concentration centers on Germany, China, and Japan for complete system assembly, with critical punch and die coatings sourced from Austrian carbide deposition specialists. Single-source vulnerability concentrates in vacuum-remelted tool steel supply. Distribution runs through Tier 1 automotive supplier networks and contract fastening service providers with regional technical service density.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive aluminum platform cycles position this market for recovery as OEMs refresh body-in-white architectures and battery enclosure assembly expands.
For Market Incumbents: Pre-empt adhesive bonding substitution threats by deepening force-displacement monitoring integration and securing exclusive die refurbishment contracts with high-volume automotive lines. Anchor position through backward integration into vacuum-remelted tool steel sourcing or captive carbide coating capabilities. Prioritize technical service density in India's emerging joint venture corridors. For New Entrants and Emerging Players: India's Manesar and Sriperumbudur industrial corridors offer underpenetrated demand for semi-automatic systems with lot-size flexibility serving export-oriented aluminum body manufacturing. Battery enclosure assembly for electric vehicle platforms presents adjacent white-space with hermetic sealing requirements. Enter through fastening-as-a-service partnerships with Yangtze River Delta contract manufacturers to bypass capital ownership barriers. For Investors and Strategic Acquirers: EU F-Gas Regulation enforcement reshapes the acquisition landscape toward mechanical fastening specialists with proven mixed-metal joint capability. Five-to-ten-year viability favors precision press technology platforms over hydraulic legacy exposure. Target servo-electric specialists with aerospace-grade traceability certification. Monitor REACH Annex XVII chromium(VI) conversion timelines as inflection signal for SPR competitive positioning against clinching alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Servo-Electric Platform Migration | Atlas Copco and TOX PRESSOTECHNIK lead electromechanical adoption eliminating hydraulic fluid liabilities. |
| Force-Displacement Monitoring Integration | EU MDR and FDA traceability mandates pull piezoelectric sensor systems into medical device manufacturing. |
| Fastening-as-a-Service Expansion | Vendor-managed die refurbishment concentrates margin capture with technical service-dense suppliers. |
| Battery Enclosure Assembly Specialization | Hermetic aluminum-to-steel joining preserves cell-adjacent thermal management coatings for EV platforms. |
| India Technical Service Establishment | Maruti Suzuki and Hyundai Motor India localization creates first-mover advantage for service presence. |
Research Methodology
A standing panel of automotive platform engineers, Tier 1 supplier procurement directors, aftermarket service heads, and aerospace joint design specialists provided ongoing calibration across primary fieldwork. Secondary validation drew from SEC equipment manufacturer filings, MIIT certification registries, EU F-Gas Regulation implementation guidance, and IHS Markit vehicle production databases. Bottom-up equipment shipment tallies triangulated against top-down automotive aluminum content penetration models.
Scenario-bracketing framed projections across the analysis window, with segmentation modeling across actuation technology, automation architecture, end-use vertical, and regional production cluster dimensions. CAGRs derived from equipment replacement cycle analysis, aluminum platform adoption curves, and regulatory compliance timeline impacts. Industry-specific inputs included die consumption rates per automotive line and force-displacement monitoring penetration by certification tier.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese domestic equipment fabricators or accelerated adhesive bonding substitution would shift outcomes. Macroeconomic deviation in automotive capital expenditure, regulatory enforcement timeline shifts, or breakthroughs in solid-state battery architectures eliminating aluminum enclosure requirements would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Dozer Blade Market
Construction Equipment
Construction Equipment Rental Market
Construction Equipment
Compact Power Equipment Rental Market
Construction Equipment
Robotic Total Stations (RTS) Market
Construction Equipment
Bulldozer Rental Market
Construction Equipment
Vertical Grinding Mills Market
Construction Equipment
Saudi Arabia Construction Equipment Market
Construction Equipment
Stamping Machines Market
Construction Equipment
Self-Driving Dumpers Machine Market
Construction Equipment
Stick Welding Electrode Market
Construction Equipment
Excavator Augers Market
Construction Equipment
Demolition Vessels Market
Construction Equipment
Pile Cage Welding Machine Market
Construction Equipment
Concrete Testers Market
Construction Equipment
Hammer Unions Market
Construction Equipment
India Construction Equipment Market