
 Tower Crane Market | 2026-2036
Tower Crane Market Size, Share, and Industry Trends Forecast 2026-2036
Tower Crane Market Analysis
Buyer concentration among infrastructure developers is hardening across major metropolitan construction corridors. Zoomlion Heavy Industry Science and Technology Co. Ltd leverages its integrated mast and jib manufacturing to control cost curves in the self-erecting segment. Liebherr sustains premium positioning through European certification density and wind-load engineering leadership. Manitowoc Company Inc. anchors North American aftermarket revenue through its dealer-service network and remanufacturing infrastructure.
A tower crane is a fixed or climbing lifting machine characterized by a vertical tower supporting a horizontal jib, with load capacities typically spanning 2 to 25 tonnes and hook heights exceeding 300 meters in luffing configurations; manufacturers produce these structures through welded box-section mast fabrication, high-strength bolted splice joints, and modular counterweight systems to enable vertical transport of construction materials, precast elements, and heavy equipment at dense urban sites. Hammerhead configurations dominate high-rise commercial deployment due to their radial reach stability and established operator familiarity, while self-erecting units represent the fastest-expanding product category as residential builders pursue reduced mobilization costs and smaller crew footprints. Static tower cranes retain the largest installed base but face margin compression from rental fleet saturation in mature European and East Asian cities.
The Occupational Safety and Health Administration enforces crane operator certification and assembly oversight across United States job sites, while China's Ministry of Emergency Management and State Administration for Market Regulation coordinate GB standard updates for structural integrity and anti-collision systems. The European Union's Machinery Directive and CE marking requirements shape export competitiveness for Asian manufacturers seeking continental market access. Stakeholders must monitor regulatory divergence between OSHA's forthcoming crane technology provisions and China's accelerating smart-crane connectivity mandates to anticipate compliance-driven product redesign cycles.
Market Dynamics
Long-term fleet partnerships between infrastructure developers and equipment providers are hardening procurement patterns across major metropolitan construction corridors, compressing spot rental margins while rewarding manufacturers with integrated service capabilities.
Growth Catalysts
- NEOM and Red Sea gigaproject absorption:Saudi Arabia's megadevelopments are absorbing unprecedented lifting capacity, creating sustained demand for luffing and hammerhead configurations with hook heights exceeding 300 meters.
- GB standard tightening:China's State Administration for Market Regulation is mandating enhanced structural integrity and anti-collision systems, accelerating replacement cycles for older domestic and imported units.
- Self-erecting crane adoption:Residential builders are pursuing reduced mobilization costs and smaller crew footprints, driving fastest-expanding product category demand in urban infill markets.
Market Restraints
- High-strength steel price volatility:Welded box-section mast fabrication faces input cost pressure from specialty steel alloy markets, squeezing margins for standardized product lines.
- European rental fleet saturation:Mature cities in Germany and France exhibit static tower crane oversupply, compressing utilization rates and daily rental yields.
- Modular counterweight logistics:Transport of segmented ballast systems faces road weight restrictions and permitting delays, limiting rapid deployment flexibility.
Strategic Opportunities
- Wind-load engineering premiumization:European CE marking density and certification sophistication enable margin capture in high-rise commercial segments exposed to coastal and alpine conditions.
- Remanufacturing aftermarket expansion:North American dealer-service networks can extend revenue capture through certified rebuild programs for aging hammerhead installed base.
- Smart-crane connectivity mandates:China's Ministry of Emergency Management is accelerating telemetry and anti-collision integration requirements, opening retrofit and new-build technology insertion points.
Industry Challenges
- Certified operator scarcity:OSHA crane operator certification timelines and assembly oversight requirements create bottlenecks for rapid project mobilization across United States job sites.
- Regulatory divergence compliance:Manufacturers must simultaneously satisfy OSHA's forthcoming crane technology provisions and China's smart-crane mandates, forcing parallel product redesign cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tower Crane Market |
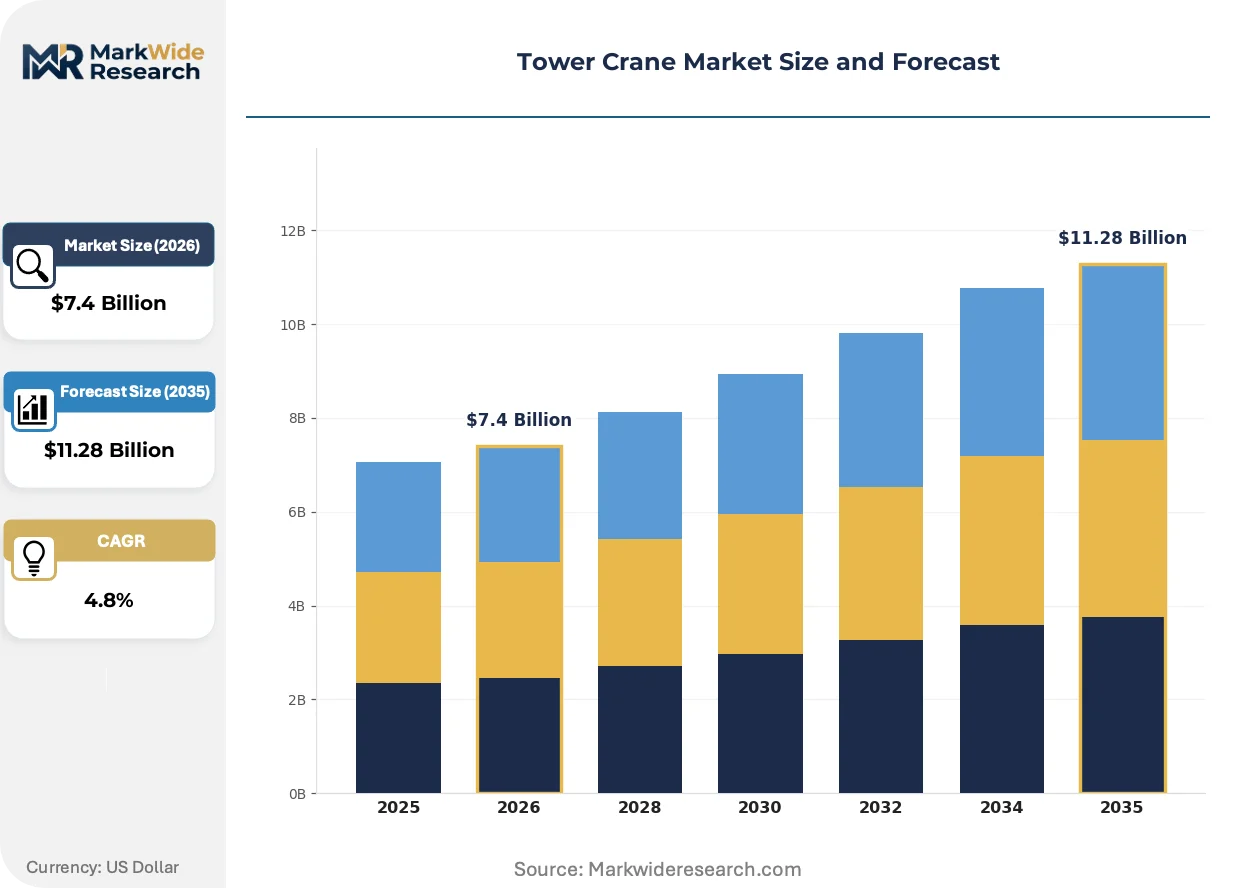
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $11.28 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Static, Mobile, Self-Erecting, Hammerhead End User: Construction Companies, Infrastructure Developers, Residential Builders, Industrial Contractors Deployment: On-Site, Off-Site, Urban Areas, Industrial Sites Installation: Fixed, Demountable, Modular, Temporary |
| Companies Covered | Zoomlion Heavy Industry Science and Technology Co. Ltd, Favelle Favco Berhad, Liebherr, Manitowoc Company Inc., JASO Tower Cranes, Terex Corporation, WOLFFKRAN International AG, Linden Comansa SL, Sany Heavy Industry Co. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tower Crane Market Emerging Trajectories
Digital telemetry and predictive maintenance systems are penetrating tower crane fleets, while regulatory pressure on structural safety and operator certification accelerates hardware refresh cycles across developed construction markets.
Anti-collision telemetry is converging with real-time wind monitoring to enable autonomous load management. High-rise commercial developers in coastal zones are adopting these integrated sensor suites fastest. The technology is converging with fleet management platforms to compress insurance premiums and reduce incident liability exposure.
China's GB standards for structural safety and operator certification are tightening product requirements for imported and domestic units alike. Manufacturers must redesign splice joint specifications and mast section welding protocols to achieve compliance. Domestic Chinese producers and European exporters face equivalent compliance burdens under State Administration for Market Regulation oversight.
Equipment procurement consolidation around long-term fleet partnerships is displacing spot rental dominance. Infrastructure developers in Saudi Arabia's gigaproject corridor are negotiating multi-year availability guarantees with integrated service commitments. This pattern is most visible where NEOM and Red Sea developments require sustained lifting capacity with minimized mobilization friction.
Tower Crane Market Segmentation
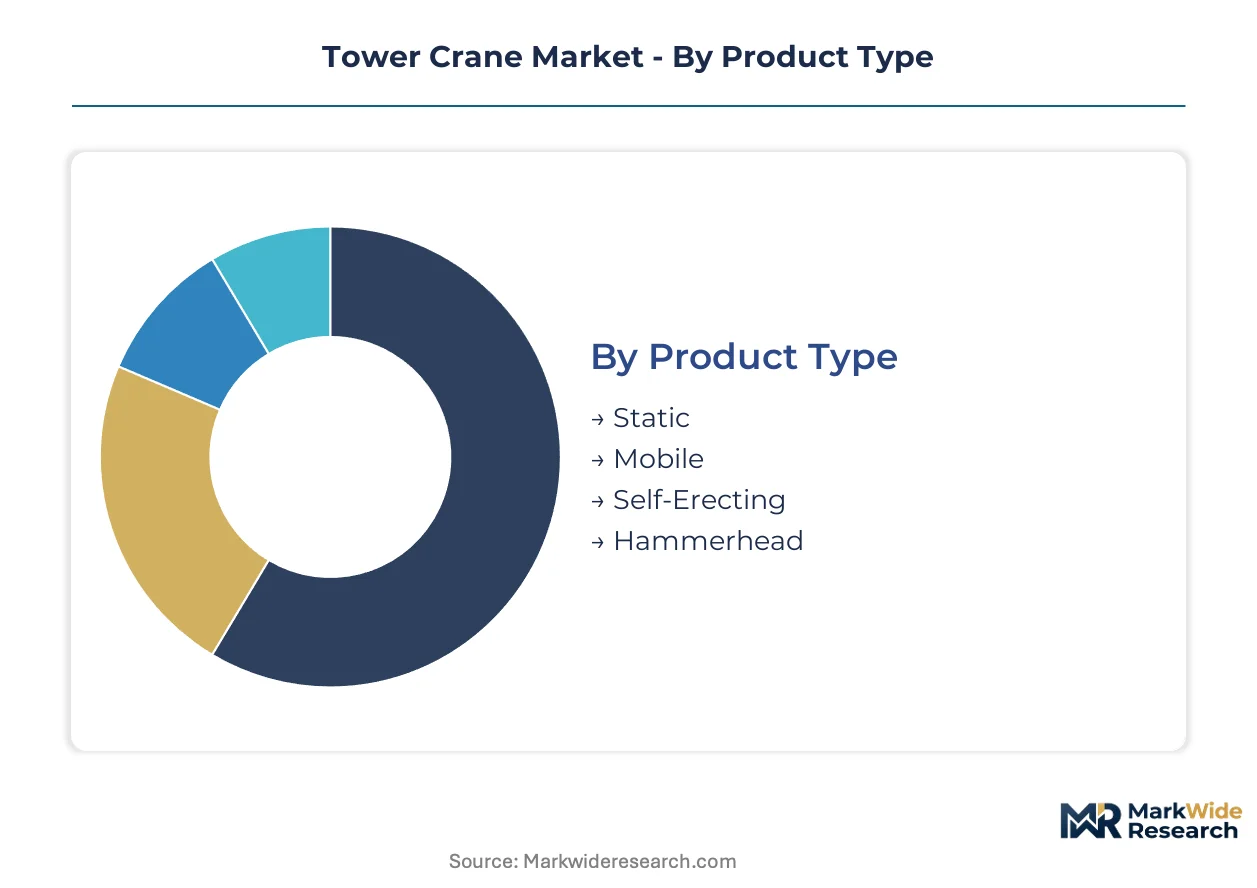
Equipment refresh cycles vary sharply across tower crane configurations, with regulatory mandates and project scale dictating replacement velocity. Manufacturers align production capacity to these divergent upgrade timelines, prioritizing segments where compliance burdens or gigaproject absorption accelerate fleet turnover.
Product Type:
Replacement urgency concentrates in configurations facing regulatory pressure or mobilization cost scrutiny, with hook height requirements and certification density driving differential upgrade intensity.
- Hammerhead:Radial reach stability derives from trolley-mounted hook block traversal along fixed horizontal jibs, enabling precise load positioning at extreme heights. Demand concentrates in Saudi Arabia's gigaproject corridor where NEOM and Red Sea developments require hook heights exceeding 300 meters for high-rise commercial superstructures.
- Self-Erecting:Hydraulic mast extension and automated jib unfolding eliminate external assembly crews, reducing mobilization timelines from days to hours. Residential builders across dense European and East Asian urban infill markets are absorbing these units fastest as labor availability tightens and site access constrains conventional erection sequences.
- Static:Fixed-base tower configurations with climbing frames enable vertical extension alongside building cores, retaining the largest installed base despite margin compression from rental fleet saturation in mature markets.
- Mobile:Truck-mounted or crawler-based undercarriages permit rapid redeployment between dispersed job sites, serving infrastructure contractors with fragmented project portfolios.
Volume placements concentrate in Hammerhead configurations; the faster expansion belongs to Self-Erecting units.
End User:
Procurement consolidation patterns diverge sharply by contractor scale and project duration, with long-term fleet partnerships displacing spot rentals among volume buyers.
- Infrastructure Developers:Multi-year megaproject commitments demand availability guarantees with integrated service provisions, compressing spot rental margins while rewarding manufacturers with telemetry-enabled fleet management capabilities. Saudi Arabia's gigaproject corridor exemplifies this pattern where NEOM and Red Sea developments negotiate sustained lifting capacity contracts.
- Residential Builders:Smaller crew footprints and reduced mobilization costs drive preference for self-erecting configurations in urban infill markets where site constraints limit conventional assembly sequences.
- Construction Companies:General commercial contracting spans hammerhead and static configurations depending on project height and duration, with rental fleet relationships dominating procurement for standardized high-rise work.
- Industrial Contractors:Heavy process equipment installation and power plant construction require luffing jib configurations with exceptional load charts at radius, typically procured through specialized lifting subcontractors.
Contract value concentrates with Infrastructure Developers; the steepest expansion trajectory appears among Residential Builders adopting self-erecting technologies.
Deployment:
Site classification determines regulatory jurisdiction and logistics complexity, with urban density imposing the strictest assembly oversight and transport constraints.
- Urban Areas:Dense construction corridors subject to OSHA crane operator certification requirements and municipal road weight restrictions for modular counterweight transport. Anti-collision telemetry mandates from China's Ministry of Emergency Management accelerate hardware refresh cycles in metropolitan clusters.
- Industrial Sites:Process facility and power generation construction occurs on controlled-access properties with fewer transport constraints but stringent wind-load engineering requirements for coastal and alpine exposure zones.
- On-Site:Conventional fixed installation at single-project locations remains the dominant deployment mode for standard commercial and residential construction.
- Off-Site:Prefabrication yard and modular construction factory deployment enables centralized lifting operations serving distributed final installation points.
Equipment density peaks in Urban Areas; Industrial Sites are gaining share fastest as energy transition investments accelerate.
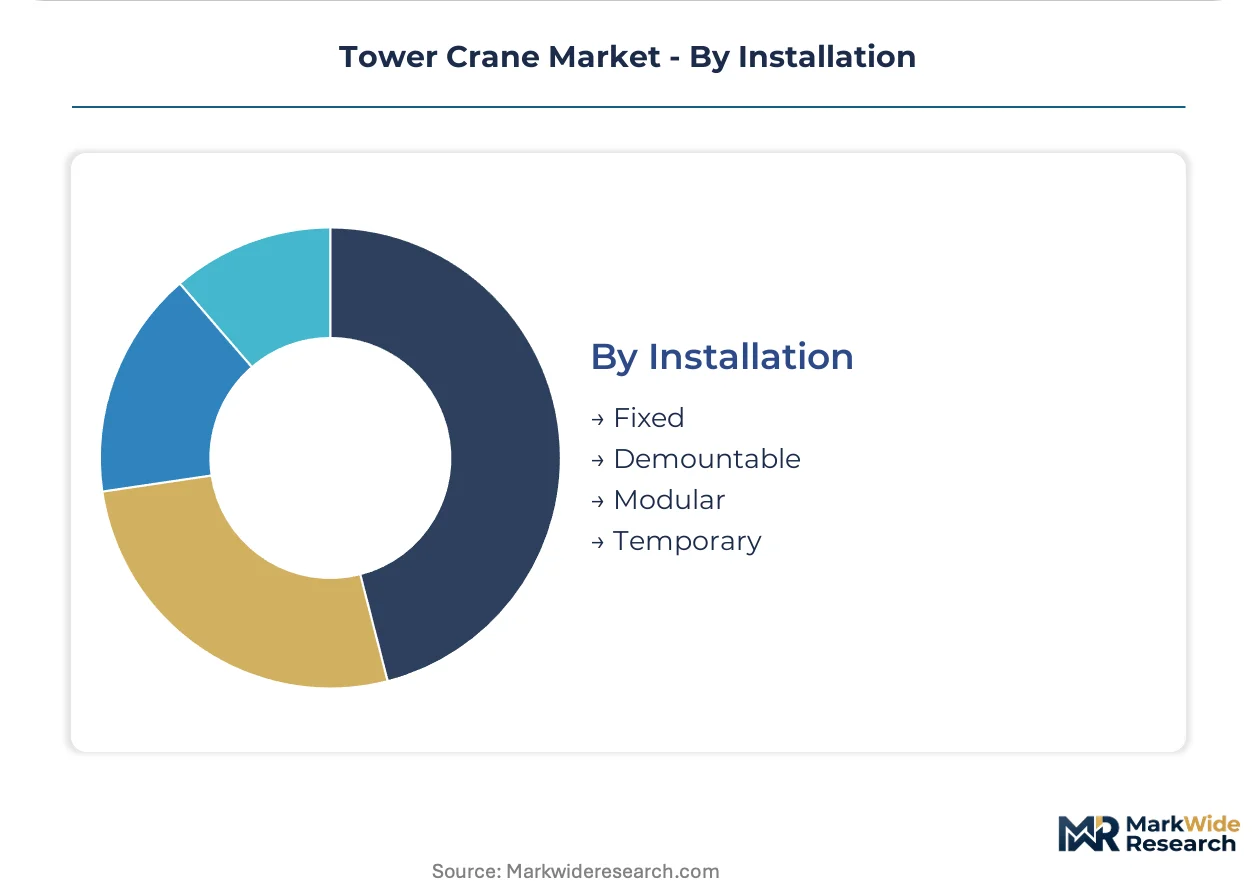
Installation:
Foundation permanence and reconfigurability trade off against mobilization speed and capital recovery timelines, with project duration and site recurrence dictating optimal attachment mode.
- Fixed:Reinforced concrete pad or embedded anchor bolt foundations support permanent or long-term installations typical of megaproject durations exceeding 24 months.
- Demountable:Ballasted chassis or grillage foundations enable complete removal without subsurface penetration, serving infrastructure contractors with sequential project portfolios.
- Modular:Segmented mast sections and splittable counterweight systems permit transport under road weight restrictions, with high-strength bolted splice joints accelerating field assembly.
- Temporary:Short-duration installations under 12 months dominate rental fleet utilization, with climbing frame compatibility enabling vertical extension alongside building construction.
Installation volume concentrates in Fixed configurations; Modular systems are climbing the fastest as logistics constraints tighten across metropolitan construction corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Saudi Arabia's gigaproject corridor, where sustained megadevelopment programs are absorbing unprecedented lifting capacity. Infrastructure developers across the Middle East are consolidating procurement around multi-year fleet partnerships rather than spot rentals. This pattern is reshaping equipment deployment economics across major construction markets.
Saudi Arabia
NEOM and Red Sea developments are driving sustained demand for luffing configurations with hook heights exceeding 300 meters. The Saudi Standards, Metrology and Quality Organization is aligning local safety protocols with European CE marking benchmarks. Riyadh and the northwestern gigaproject zone are absorbing the highest equipment density in the region.
China
Urban infill construction and high-rise residential towers are sustaining replacement demand for self-erecting and static configurations. The State Administration for Market Regulation is mandating enhanced structural integrity and anti-collision systems under revised GB standards. The Yangtze River Delta and Pearl River Delta clusters are experiencing accelerated fleet refresh cycles.
United States
High-rise commercial development in dense metropolitan corridors is sustaining hammerhead configuration demand. The Occupational Safety and Health Administration enforces crane operator certification and assembly oversight requirements. The New York Metro and Pacific Northwest construction clusters are absorbing premium wind-load engineered equipment.
Germany
Rental fleet saturation in mature cities is compressing utilization rates for static tower cranes. The Federal Motor Transport Authority enforces road weight restrictions affecting modular counterweight logistics. The North Rhine-Westphalia and Bavaria industrial corridors remain the primary equipment distribution nodes.
United Arab Emirates
Energy transition investments and coastal high-rise development are driving demand for wind-load engineered luffing cranes. The Ministry of Energy and Infrastructure coordinates building code alignment with Gulf Cooperation Council safety standards. Dubai and Abu Dhabi construction clusters are prioritizing telemetry-enabled fleet management capabilities.
Tower Crane Market Vendor Landscape
European producers anchor the premium certification tier; Chinese fabricators hold volume leadership through integrated mast and jib manufacturing. The vendor base organizes around three strategic archetypes: full-line manufacturers with captive component production, specialized luffing crane engineers, and rental fleet operators with remanufacturing capabilities. Competitive moves concentrate on long-term fleet partnership negotiations and smart-crane connectivity integration.
Within the premium-tier segment, Liebherr and WOLFFKRAN International AG exemplify European certification density and wind-load engineering positioning. Zoomlion Heavy Industry Science and Technology Co. Ltd and Sany Heavy Industry Co. Ltd occupy the scale-driven tier through integrated manufacturing structures. Manitowoc Company Inc. anchors North American aftermarket revenue capture through dealer-service network positioning.
| Leading Market Players |
|---|
| Zoomlion Heavy Industry Science and Technology Co. Ltd |
| Favelle Favco Berhad |
| Liebherr |
| Manitowoc Company Inc. |
| JASO Tower Cranes |
| Terex Corporation |
| WOLFFKRAN International AG |
| Linden Comansa SL |
| Sany Heavy Industry Co. Ltd |
| Others |
Supply Flow & Price Mechanics
High-strength steel alloy prices cascade through tower crane manufacturing tiers, with specialty welded box-section mast fabrication costs separating premium European CE-certified producers from volume-tier Chinese fabricators serving Saudi Arabia's gigaproject corridor.
Pricing Analysis
Volume placements concentrate in standardized hammerhead configurations where Zoomlion and Sany compete on manufacturing scale, while margin capture concentrates in wind-load engineered luffing cranes where Liebherr and WOLFFKRAN command certification premiums. Three-tier pricing structure across premium, standard, and economy levels reflects differential CE marking density, anti-collision telemetry integration, and aftermarket service bundling. Cost compression in the standard tier is intensifying because rental fleet saturation in Germany and France compresses daily yields. Residential builders represent the most price-sensitive segment, prioritizing self-erecting units with minimal mobilization timelines, while infrastructure developers in NEOM and Red Sea developments exhibit lowest sensitivity due to multi-year availability guarantee structures.
Supply Chain Analysis
Single-source vulnerability sits with Chinese producers of high-strength bolted splice joints and modular counterweight castings, which feed mast fabrication lines across European and Middle Eastern assembly plants. Manufacturing gravity centers on China for integrated mast and jib production, Germany for precision-engineered luffing mechanisms, and South Korea for specialty steel alloys. Raw material dependencies span high-strength structural steel, copper windings for hoist motors, and rare-earth elements for sensor telemetry. Tariff exposure on Chinese steel imports into Europe and the United States threatens margin structures for standardized product lines. Distribution runs through manufacturer-direct fleet partnerships for infrastructure developers and dealer-service networks for rental fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
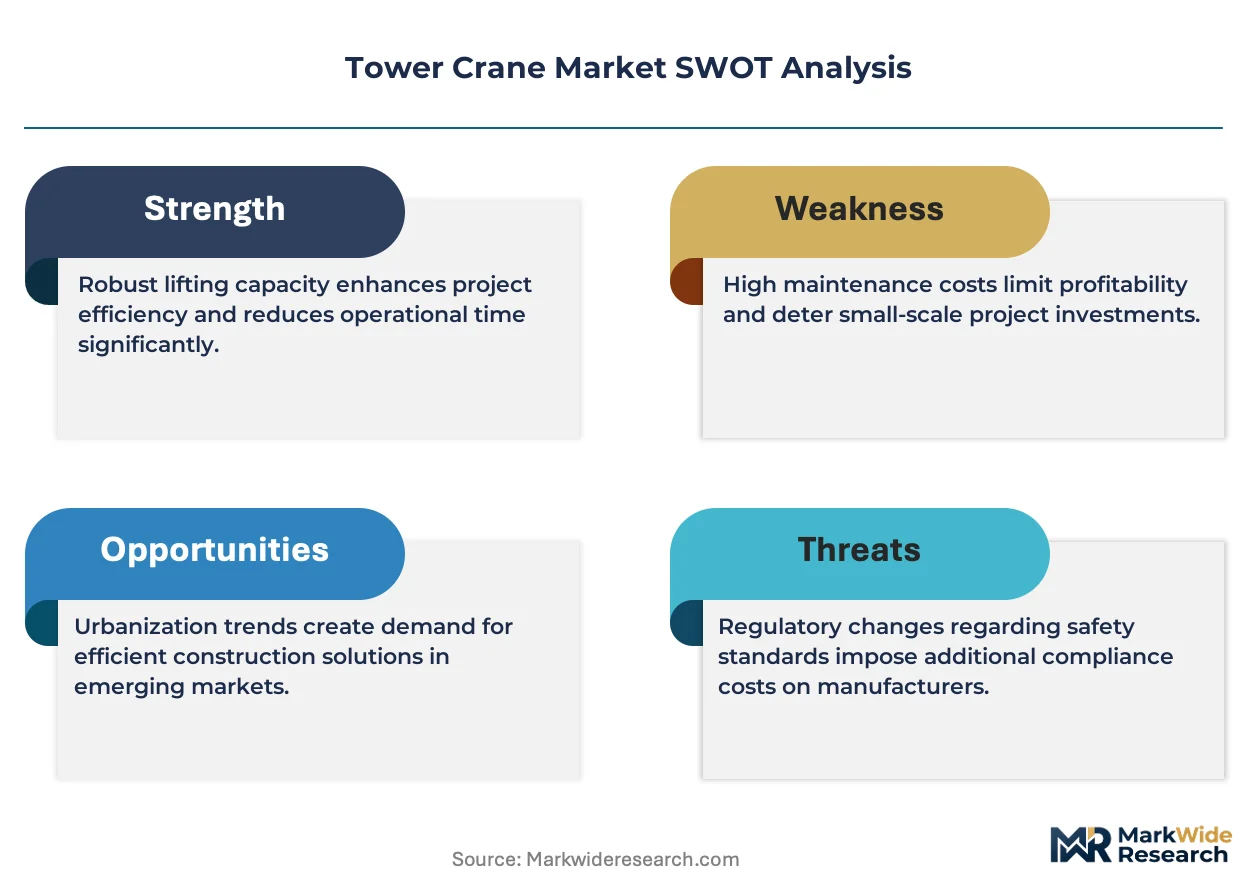
This market reads as a cost-of-compliance story where China's GB standard tightening and Saudi Arabia's alignment with European CE marking benchmarks erect barrier-to-entry moats favoring manufacturers with captive certification infrastructure and integrated telemetry development.
For Market Incumbents: Deepen backward integration into high-strength steel processing and captive splice joint manufacturing to insulate margin structures from alloy price volatility. Expand remanufacturing infrastructure in North America to capture aftermarket revenue from aging hammerhead installed base threatened by Chinese self-erecting substitution. Prioritize smart-crane connectivity R&D to satisfy divergent OSHA and SAMR mandates without parallel product lines. For New Entrants and Emerging Players: Launch via specialized luffing crane engineering partnerships serving Saudi Arabia's gigaproject corridor, where wind-load certification scarcity creates white-space opportunity. Target residential builder segments in dense European urban infill markets with demountable self-erecting configurations that bypass established rental fleet relationships. Pursue OEM-private-label arrangements with Chinese mast fabricators to bypass capital-intensive manufacturing scale requirements. For Investors and Strategic Acquirers: China's anti-collision telemetry mandate acceleration is the leading indicator that retrofit technology providers and smart-crane software specialists will command acquisition premiums. Long-term viability favors vertically integrated manufacturers with captive component production and multi-regional certification density. Monitor Saudi Standards, Metrology and Quality Organization alignment announcements with European benchmarks as the signal for gigaproject procurement consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Smart-Crane Connectivity Integration | Anti-collision telemetry mandates from China's SAMR and OSHA provisions force hardware redesign cycles across all tiers. |
| Remanufacturing Infrastructure Expansion | Certified rebuild programs extend revenue capture from aging hammerhead installed base in North American markets. |
| Long-Term Fleet Partnership Negotiation | Multi-year availability guarantees with NEOM and Red Sea developers displace spot rental dominance in Saudi Arabia. |
| Wind-Load Engineering Certification Investment | CE marking density enables premium positioning for coastal and alpine high-rise commercial segments. |
| Self-Erecting Product Line Expansion | Hydraulic mast automation addresses labor scarcity and site access constraints in dense European urban infill. |
Methodological Framework
Independent corroboration across equipment procurement directors at infrastructure developers, aftermarket service heads at dealer networks, and regulatory affairs leads at certification bodies underwrites the qualitative findings. Primary fieldwork encompassed interviews with fleet managers at Saudi gigaproject consortia, plant engineers at Chinese mast fabrication facilities, and maintenance directors at German rental operators. Secondary validation drew from SAMR GB standard filings, OSHA crane technology provision drafts, customs records for high-strength steel alloy trade flows, and EPC contractor equipment procurement disclosures. Bottom-up unit placement tallies triangulated against top-down construction spending allocations across the analysis window.
Rate-of-change decomposition across product type, end-user archetype, deployment site classification, and installation foundation mode structured the analytical framework. CAGRs derived from regression against construction output indices, megaproject pipeline tracking, and regulatory mandate implementation timelines. Industry-specific forecast inputs incorporated crane density per construction dollar, hook height requirements by building class, and fleet age distributions triggering replacement cycles.
Steel price volatility, regulatory implementation delays, and gigaproject financing disruptions are the dominant revision risks to modeled trajectories. Forecasts reflect documented assumptions regarding compliance timeline adherence and construction spending continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Electric Excavators Market
Construction Equipment
Cable Winches Market
Construction Equipment
Draw Heat Setting Winder Market
Construction Equipment
Log Splitters Rental Market
Construction Equipment
Boom Lifts Market
Construction Equipment
Mini Excavators Market
Construction Equipment
Construction Lasers Market
Construction Equipment
UK Heavy Construction Equipment Rental Market
Construction Equipment
Cement Consistometer Market
Construction Equipment
Rail Welding Equipment Market
Construction Equipment
Aerial Work Platform (AWP) Market
Construction Equipment
Rockbreakers Market
Construction Equipment
Crane Pumps Market
Construction Equipment
Baler Market
Construction Equipment
Gear Shaping Machine Market
Construction Equipment
Drone-Based Solutions in Construction Market