
 Rotomolding Market | 2026-2036
Rotomolding Market Size, Share, and Industry Trends Forecast 2026-2036
Rotomolding Market Outlook
North American resin compounders is decoupling from spot polyethylene pricing as captive supply agreements harden. ExxonMobil leverages its Gulf Coast polymer production base to secure long-term feedstock pipelines for rotomolding grade resins. LyondellBasell Industries Holdings B.V. sustains technology leadership through proprietary metallocene catalyst platforms that yield consistent melt flow indices for hollow-part manufacturing. Matrix Polymers Limited specializes in color-compounded and UV-stabilized grades for outdoor durability applications across Northern European markets.
Rotomolding is a hollow-part manufacturing process wherein powdered thermoplastic resin, typically polyethylene with melt flow index between 2 and 8 g/10min, rotates within a heated mold to form seamless, stress-free containers and structural components. The method produces tanks, toys, and industrial housings with uniform wall thickness and complex geometries without weld lines or material waste from sprues. Polyethylene dominates material consumption across the analysis window due to its processability, impact resistance, and cost position for bulk storage and playground equipment. Multi-Axis Rotomolding captures expanding margin pools in medical device housings and precision furniture where dimensional tolerances exceed conventional machine capabilities. Storage Tanks anchors volume demand from agricultural chemical containment and rainwater harvesting systems in water-stressed regions.
The US EPA regulates potable water tank materials under NSF/ANSI 61 certification requirements that restrict extractable contaminants from plastic contact surfaces. REACH compliance in Europe governs phthalate and heavy metal content in PVC rotomolding compounds used for consumer goods and toys. India's BIS certification mandates dimensional and material standards for plastic water storage tanks under IS 12701 to ensure structural integrity in tropical UV exposure conditions. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions across multiple jurisdictions that threaten conventional mold-release agent formulations and may force process chemistry transitions.
Market Dynamics
Multi-axis rotomolding machinery is consolidating production economics for complex hollow parts, compressing cycle times for medical device housings and precision furniture while forcing conventional single-arm equipment into commodity tank fabrication.
Growth Catalysts
- NSF/ANSI 61 Certification Mandates:US EPA amendments to the Safe Drinking Water Act are accelerating tank replacement cycles as municipal utilities face compliance deadlines for potable water contact surfaces.
- Agricultural Mechanization:India's rural infrastructure programs are driving container procurement for chemical storage and irrigation systems across water-stressed agricultural belts.
- Metallocene Catalyst Platforms:Proprietary polymerization technologies are delivering consistent melt flow indices that reduce defect rates in large-volume hollow-part manufacturing.
Market Restraints
- Polyethylene Feedstock Volatility:Gulf Coast resin production concentration exposes compounders to hurricane disruption and ethylene monomer price swings.
- Per- and Polyfluoroalkyl Substance Restrictions:REACH and emerging state-level bans on PFAS-containing mold-release agents are forcing process chemistry transitions without drop-in alternatives.
- Blow Molding Substitution:High-volume packaging applications are migrating to extrusion blow molding where cycle economics favor thinner-wall construction.
Strategic Opportunities
- Rainwater Harvesting System Demand:Climate adaptation spending in Australia and the southwestern United States is creating specification opportunities for UV-stabilized above-ground storage tanks.
- Electric Vehicle Battery Enclosures:Flame-retardant rotomolded polyethylene housings are penetrating EV thermal management systems as OEMs seek seamless, corrosion-resistant protection.
- BIS IS 12701 Certification Expansion:India's mandatory dimensional and material standards for plastic water tanks are raising barriers for uncertified imports and favoring domestic production scale-up.
Industry Challenges
- Multi-Axis Programming Expertise Scarcity:Machine toolpath optimization for complex geometries requires specialized CAD/CAM competencies that outpace vocational training pipeline output.
- NSF/ANSI 61 Certification Timelines:Extractables testing protocols for potable water contact surfaces extend product qualification cycles by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rotomolding Market |
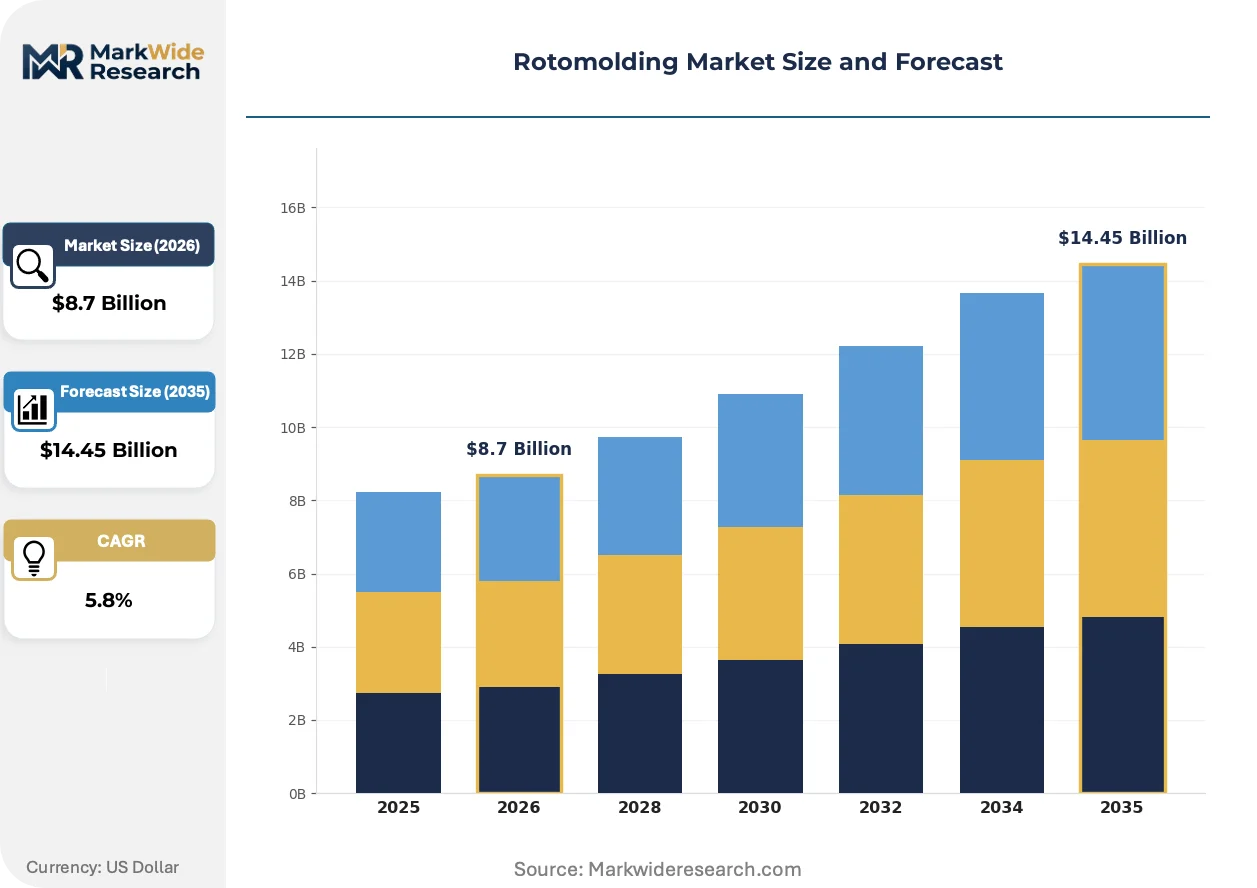
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, PVC, Nylon End User: Automotive, Consumer Goods, Industrial Equipment, Toys Application: Storage Tanks, Playground Equipment, Medical Devices, Furniture Technology: Conventional Rotomolding, Multi-Axis Rotomolding, Advanced Rotomolding, Robotics |
| Companies Covered | ExxonMobil, Reliance Industries Limited, SABIC, LyondellBasell Industries Holdings B.V., PTT Global Chemical Public Company Limited, Matrix Polymers Limited, GreenAge Industries, Phychem Technologies, Ferry Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rotomolding Market Strategic Shifts
Process automation and material science advances are compressing the frontier between commodity tank production and precision hollow-part fabrication, reshaping equipment investment priorities and resin specification hierarchies.
Multi-axis rotomolding is consolidating control over high-margin medical device and aerospace applications where dimensional tolerances below 0.5% are non-negotiable. Tier-one automotive suppliers are adopting five-axis machines for HVAC ducting and fluid reservoirs. The technology is consolidating supplier bases by disqualifying single-axis competitors from specification-driven procurement.
REACH Annex XVII restrictions on phthalate plasticizers in PVC compounds are forcing compounders toward bio-based alternatives or full material substitutions in consumer goods. The industrial consequence is a 15-20% raw material cost premium for compliant formulations. Toy manufacturers and playground equipment fabricators in Northern Europe are accelerating polyethylene conversion to preempt enforcement.
Specification-driven procurement is compressing vendor qualification cycles as municipal utilities and agricultural cooperatives consolidate purchasing through framework agreements. Distributor networks are losing share to direct manufacturer relationships in the United States and India. Water-stressed regions of Gujarat and Rajasthan are exhibiting the most pronounced consolidation, with state tender boards mandating BIS-certified suppliers exclusively.
Rotomolding Market Segmentation
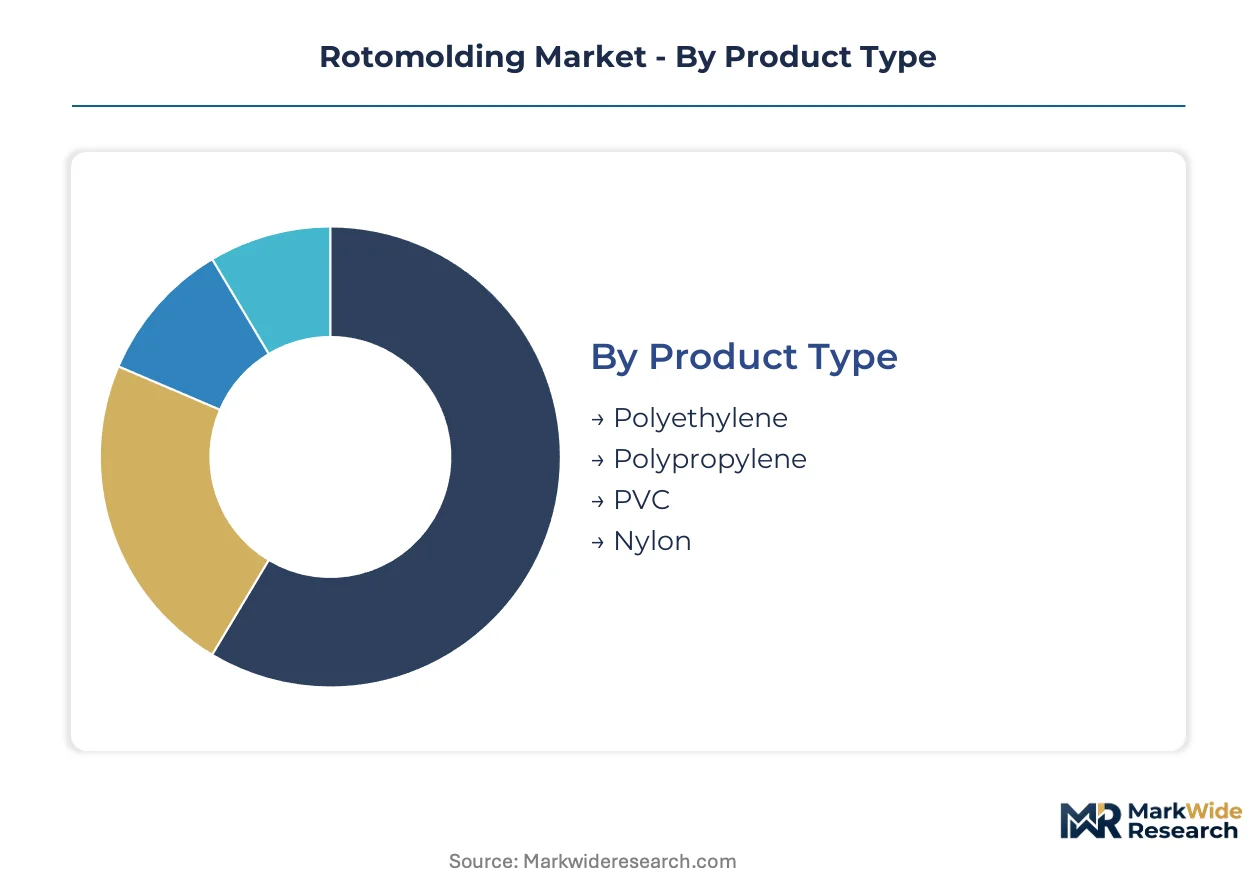
Rotomolding segmentation reveals how certification requirements fragment procurement across end-use applications. Material specifications, dimensional tolerances, and regulatory contact surfaces create distinct competitive arenas with divergent margin structures.
Product Type:
Polyethylene grades dominate municipal water tank procurement under NSF/ANSI 61 and BIS IS 12701 certification regimes, while specialty polymers face REACH Annex XVII constraints on plasticizer content.
- Polyethylene:Linear low-density and cross-linked grades process within 2-8 g/10min melt flow indices for seamless hollow-part formation. Water storage tank demand concentrates in Gujarat and Rajasthan where state tender boards mandate BIS-certified suppliers exclusively for agricultural and municipal procurement.
- Polypropylene:Higher melting point and chemical resistance suit automotive fluid reservoirs and industrial chemical containment. Specification-driven procurement from tier-one automotive suppliers in Germany and the United States favors flame-retardant compounded grades for under-hood thermal management applications.
- PVC:REACH phthalate restrictions force compounders toward bio-based plasticizers or full material substitution in European consumer goods.
- Nylon:Engineering-grade applications in aerospace ducting and precision industrial housings require multi-axis machine capabilities.
Polyethylene sits at the top of the volume ranking, with polypropylene climbing the fastest as automotive thermal management specifications proliferate.
End User:
Customer procurement patterns separate specification-heavy industrial buyers from price-sensitive consumer channels, with certification timelines and volume scale driving vendor selection criteria.
- Automotive:OEM thermal management systems specify flame-retardant polyethylene battery enclosures with sub-0.5% dimensional tolerances. Five-axis rotomolding machinery disqualifies single-axis competitors from EV supplier qualification programs in Michigan and Stuttgart manufacturing clusters.
- Industrial Equipment:Agricultural chemical containment and HVAC ducting demand UV-stabilized grades for outdoor durability. Procurement concentrates through framework agreements in water-stressed Australian and southwestern United States regions.
- Consumer Goods:Cost pressure from blow molding substitution limits rotomolding to complex geometries unsuited to extrusion processes.
- Toys:Northern European playground equipment fabricators accelerate polyethylene conversion to preempt REACH enforcement on phthalate-containing PVC compounds.
Industrial Equipment captures the largest revenue pool, though Automotive is expanding most quickly as EV battery enclosure specifications harden.
Application:
Application segmentation tracks how dimensional precision requirements separate commodity tank fabrication from premium hollow-part manufacturing.
- Storage Tanks:Above-ground rainwater harvesting and agricultural chemical containment drive volume demand. Climate adaptation spending in Australia and India accelerates UV-stabilized tank replacement cycles under municipal compliance deadlines.
- Medical Devices:Housings for diagnostic equipment and patient monitoring systems require multi-axis programming expertise for complex internal geometries. Extractables testing protocols extend qualification cycles by 12-18 months under FDA and EMA device regulations.
- Playground Equipment:Seamless construction eliminates pinch points and weld-line failure modes for safety-critical consumer applications.
- Furniture:Precision rotational molding enables complex aesthetic geometries for commercial interior installations.
Storage Tanks anchors absolute volume, while Medical Devices gains share fastest as diagnostic equipment housing specifications tighten.
Technology:
Technology segmentation reflects capital equipment differentiation between commodity production and precision manufacturing, with programming expertise scarcity constraining high-capability deployment.
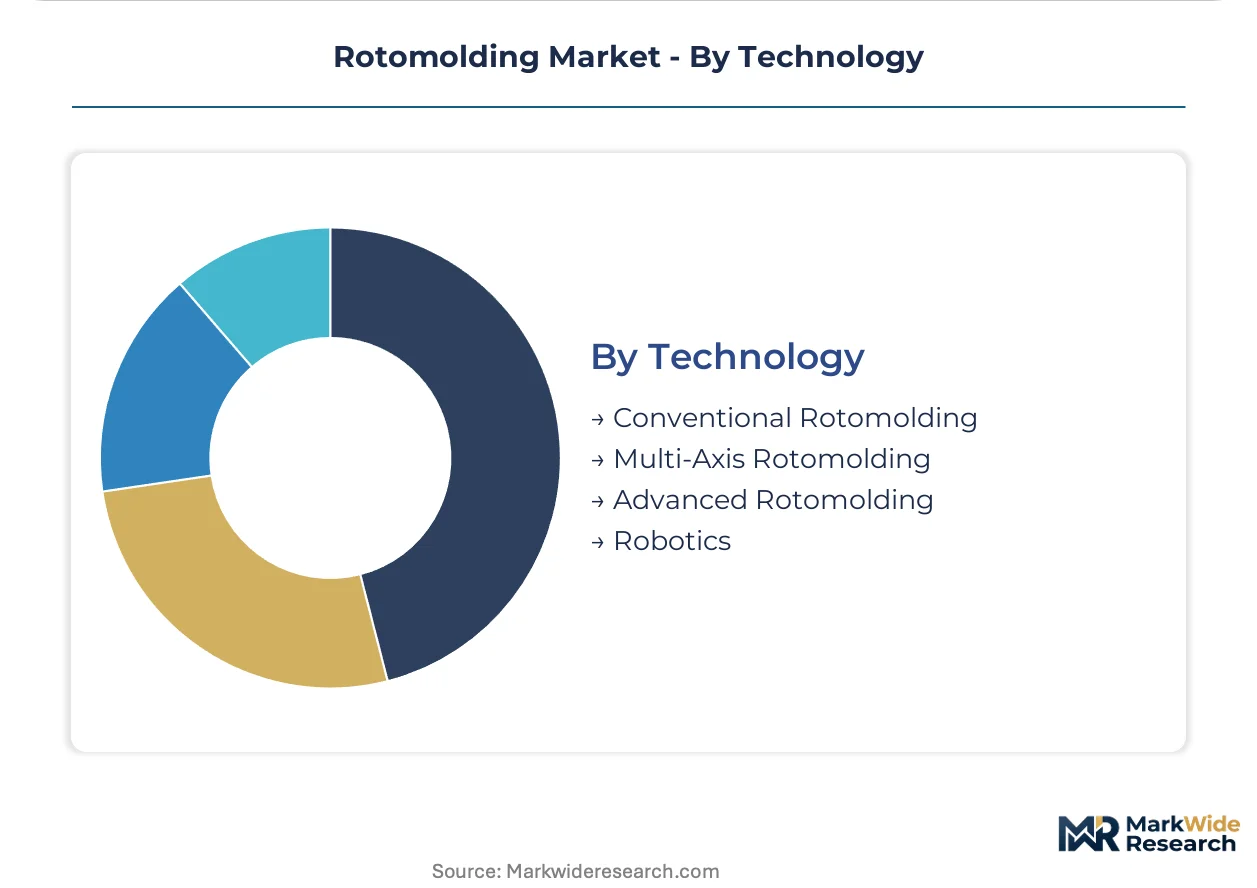
- Multi-Axis Rotomolding:Five-axis and six-axis machines consolidate control over medical device, aerospace, and precision furniture applications where conventional equipment cannot meet tolerance requirements. Machine toolpath optimization demands specialized CAD/CAM competencies that outpace vocational training output in Ohio and Bavaria manufacturing regions.
- Conventional Rotomolding:Single-arm and shuttle machines dominate water tank and bulk container fabrication. Cycle economics favor large-volume, simple-geometry production without the capital burden of multi-axis systems.
- Advanced Rotomolding:Process automation and in-mold labeling integration compress labor content for mid-complexity parts.
- Robotics:Automated mold handling and finishing operations reduce cycle variability in high-volume production environments.
Conventional Rotomolding maintains installed base dominance, with Multi-Axis Rotomolding showing the steepest expansion trajectory as specification-driven procurement disqualifies legacy equipment from premium applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting rotomolding capacity toward jurisdictions with streamlined certification timelines and lower compliance burdens, while mature markets tighten material standards for potable water contact surfaces.
United States
Municipal water infrastructure replacement cycles are accelerating under EPA Safe Drinking Water Act amendments. NSF/ANSI 61 certification mandates for potable water tanks are forcing utilities in Arizona and California to retire non-compliant legacy installations. The Gulf Coast polymer production cluster around Houston anchors captive resin supply for domestic compounders.
India
Rural infrastructure programs and agricultural mechanization are driving container procurement across water-stressed agricultural belts. BIS IS 12701 certification mandates for plastic water storage tanks are raising barriers for uncertified imports. State tender boards in Gujarat and Rajasthan now exclusively source from certified domestic suppliers.
Germany
Automotive thermal management specifications for EV battery enclosures are tightening dimensional tolerance requirements. REACH Annex XVII restrictions on phthalate plasticizers are forcing PVC compounders toward bio-based alternatives. The Stuttgart manufacturing cluster is consolidating five-axis rotomolding capacity for precision HVAC ducting.
Australia
Climate adaptation spending is accelerating above-ground rainwater harvesting system deployment across drought-affected regions. UV-stabilized tank specifications are hardening as municipal compliance deadlines approach. Queensland and New South Wales agricultural cooperatives are consolidating procurement through framework agreements.
China
Industrial chemical containment demand is expanding alongside petrochemical capacity growth in coastal provinces. GB standards for plastic storage vessels are converging with international extractables testing protocols. The Yangtze River Delta manufacturing belt is absorbing multi-axis machinery for precision hollow-part export production.
Rotomolding Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue specialized certification niches and regional compliance arbitrage. The vendor base stratifies across resin compounders, machinery fabricators, and finished-part manufacturers with limited cross-tier integration. Three archetypes dominate: Gulf Coast petrochemical majors with captive polymer supply, European specialists in color-compounded UV-stabilized grades, and Asian fabricators scaling BIS-certified tank production. Competitive moves concentrate on long-term feedstock agreements and multi-axis equipment licensing to secure specification-driven procurement.
Among petrochemical-based compounders, ExxonMobil, LyondellBasell Industries Holdings B.V., and SABIC exemplify the scale-driven archetype with integrated polymerization capabilities. Matrix Polymers Limited occupies a specialist position within the European tier. These entities represent the prevailing competitive structure rather than discrete strategic postures.
| Leading Market Players |
|---|
| ExxonMobil |
| Reliance Industries Limited |
| SABIC |
| LyondellBasell Industries Holdings B.V. |
| PTT Global Chemical Public Company Limited |
| Matrix Polymers Limited |
| GreenAge Industries |
| Phychem Technologies |
| Ferry Industries |
| Others |
Value Chain & Pricing Dynamics
Multi-axis machinery adoption simultaneously compresses per-unit conversion costs for precision hollow parts and concentrates production economics among capital-rich compounders capable of five-axis equipment deployment. This technology transition rewards Gulf Coast resin producers with captive polyethylene supply while squeezing single-axis fabricators into undifferentiated tank commodity tiers.
Pricing Analysis
Distributor margins in municipal water tank procurement are collapsing as state tender boards in Gujarat and Rajasthan mandate direct manufacturer relationships for BIS-certified suppliers. Three-tier pricing structure across premium NSF/ANSI 61-certified, standard UV-stabilized, and economy non-certified grades separates specification-driven utility buyers from price-sensitive agricultural cooperatives. Pricing pressure stems from blow molding substitution in thin-wall packaging applications. Agricultural chemical containment buyers exhibit highest price sensitivity; medical device housing procurement shows lowest.
Supply Chain Analysis
Regional distribution centers in Houston, Rotterdam, and Singapore anchor hub-and-spoke patterns for rotomolding grade resins. Supply concentrates in the United States, Saudi Arabia, and India for polyethylene feedstock; Germany and Japan for multi-axis machinery; China for finished tank exports. Raw material dependencies include ethylene monomer, metallocene catalyst systems, and UV stabilizer packages. Single-source vulnerability runs through Gulf Coast polymer production exposed to hurricane disruption. Distribution runs through direct OEM relationships displacing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rotomolding capacity arbitrage favors India over Europe as BIS certification mandates raise import barriers while REACH compliance costs inflate European compounder operating bases.
For Market Incumbents: Deploy captive resin supply agreements to lock in feedstock cost advantages against spot polyethylene volatility. ExxonMobil and LyondellBasell should extend Gulf Coast polymerization capacity into rotomolding grade compounding to capture municipal tank replacement cycles. Multi-axis equipment licensing partnerships with machinery fabricators in Stuttgart and Michigan manufacturing clusters defend specification-driven procurement positions against emerging Asian competitors. For New Entrants and Emerging Players: BIS IS 12701 certification expansion in India opens a window for domestic tank fabricators to displace uncertified Chinese imports in Gujarat and Rajasthan state tenders. Target rainwater harvesting system specification in drought-affected Australian regions where climate adaptation spending accelerates UV-stabilized tank procurement. Pursue direct-to-utility go-to-market positioning bypassing distributor networks losing share to manufacturer relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among conventional single-axis tank fabricators facing multi-axis equipment obsolescence risk. Long-term viability centers on compounders with backward integration into polymerization and certification depth across NSF/ANSI 61 and REACH Annex XVII regimes. Watch EV battery enclosure specification hardening as inflection signal for flame-retardant polyethylene housing demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymerization | Gulf Coast producers secure captive ethylene supply against hurricane disruption and monomer price swings. |
| Multi-Axis Equipment Licensing | Five-axis machine partnerships with German and US fabricators capture medical device housing specifications. |
| BIS Certification Investment | Domestic Indian compounders preempt import barriers in Gujarat and Rajasthan state tender boards. |
| REACH-Compliant Formulation Transition | European specialists convert PVC playground equipment demand to polyethylene ahead of phthalate enforcement. |
| Direct Utility Relationship Building | Manufacturers displace distributor margins in US municipal water infrastructure replacement procurement. |
Study Parameters
Bottom-up end-use modeling reconciled against top-down resin supply tracking forms the analytical core of this study. Primary interviews with rotomolding plant managers, municipal procurement officers, automotive Tier 1 supplier engineers, and agricultural cooperative purchasing heads combined with secondary validation from customs trade data, SEC 10-K filings, BIS certification registries, and EPA Safe Drinking Water Act amendment documentation. Triangulation across stakeholder inputs and published regulatory filings ensures segmentation integrity.
Input-output matrices link polyethylene consumption by melt flow index grade to finished part production across storage tank, automotive housing, and medical device applications over the projection horizon. Segmentation dimensions include material type, end-use industry, technology tier, and regional regulatory cluster. CAGRs derive from installed base replacement cycles, certification deadline schedules, and machinery capacity utilization trends. Forecast inputs incorporate climate adaptation spending trajectories and EV battery enclosure specification timelines.
Revisions become necessary when EPA Safe Drinking Water Act enforcement timelines shift, REACH Annex XVII restrictions expand to additional plasticizer categories, or Gulf Coast hurricane patterns disrupt ethylene monomer supply. Forecasts reflect documented assumptions regarding municipal infrastructure replacement rates and agricultural mechanization penetration. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Hydraulic Breaker for Excavator Market
Construction Equipment
Construction Lasers Market
Construction Equipment
Portable Welding Generators Market
Construction Equipment
Construction Pump Market
Construction Equipment
Pipe Manufacturing Machines Market
Construction Equipment
GCC Construction Machinery Market
Construction Equipment
Europe Construction Equipment Rental Market
Construction Equipment
All-Terrain Crane Market
Construction Equipment
Crawler Dozers Market
Construction Equipment
Cold Forming Equipment Market
Construction Equipment
GCC Crane Market
Construction Equipment
Dozer Tire Market
Construction Equipment
Asia Pacific Construction Equipment Rental Market
Construction Equipment
Vertical Machining Centers Market
Construction Equipment
Escalator Cleaning Machine Market
Construction Equipment
Mobile Light Tower Market