
 Concrete Testers Market | 2026-2036
Concrete Testers Market Size, Share, and Industry Trends Forecast 2026-2036
Concrete Testers Market Analysis
Equipment leasing and performance-based service contracts is tilting competitive dynamics toward vendors with balance-sheet capacity to carry long-term receivables. PCE Instruments leverages its German manufacturing base to sustain premium positioning across European calibration networks. Humboldt Mfg. Co. anchors North American distribution through direct field-service teams that control aftermarket revenue streams. ELE International competes aggressively on rental penetration in emerging markets where capital constraints limit outright purchases.
Concrete testers comprise instruments that measure compressive strength, permeability, elastic modulus, and internal flaw propagation in hardened or fresh concrete, typically operating within load frames rated from 50 kN to 5,000 kN or emitting ultrasonic pulses at 50–100 kHz for non-destructive evaluation. Their primary purpose is to verify that cured concrete meets design specifications before structural elements enter service. Compression testing machines dominate installed base value due to mandatory batch verification protocols, while ultrasonic pulse velocity testers represent the fastest-expanding category as bridge owners shift toward non-destructive condition monitoring. Digital technology platforms command margin premiums over mechanical alternatives through automated data logging and cloud-connected reporting that satisfies third-party audit requirements.
ASTM International governs test method standards including C39 for compressive strength and C597 for pulse velocity, while ISO 4012 and EN 12390 shape European product certification and cross-border market access. The US Occupational Safety and Health Administration and the EU Machinery Directive impose operational safety specifications that filter out uncertified suppliers. Stakeholders must monitor evolving building code harmonization between national standards bodies and regional economic blocs to anticipate where certification reciprocity will unlock procurement scale.
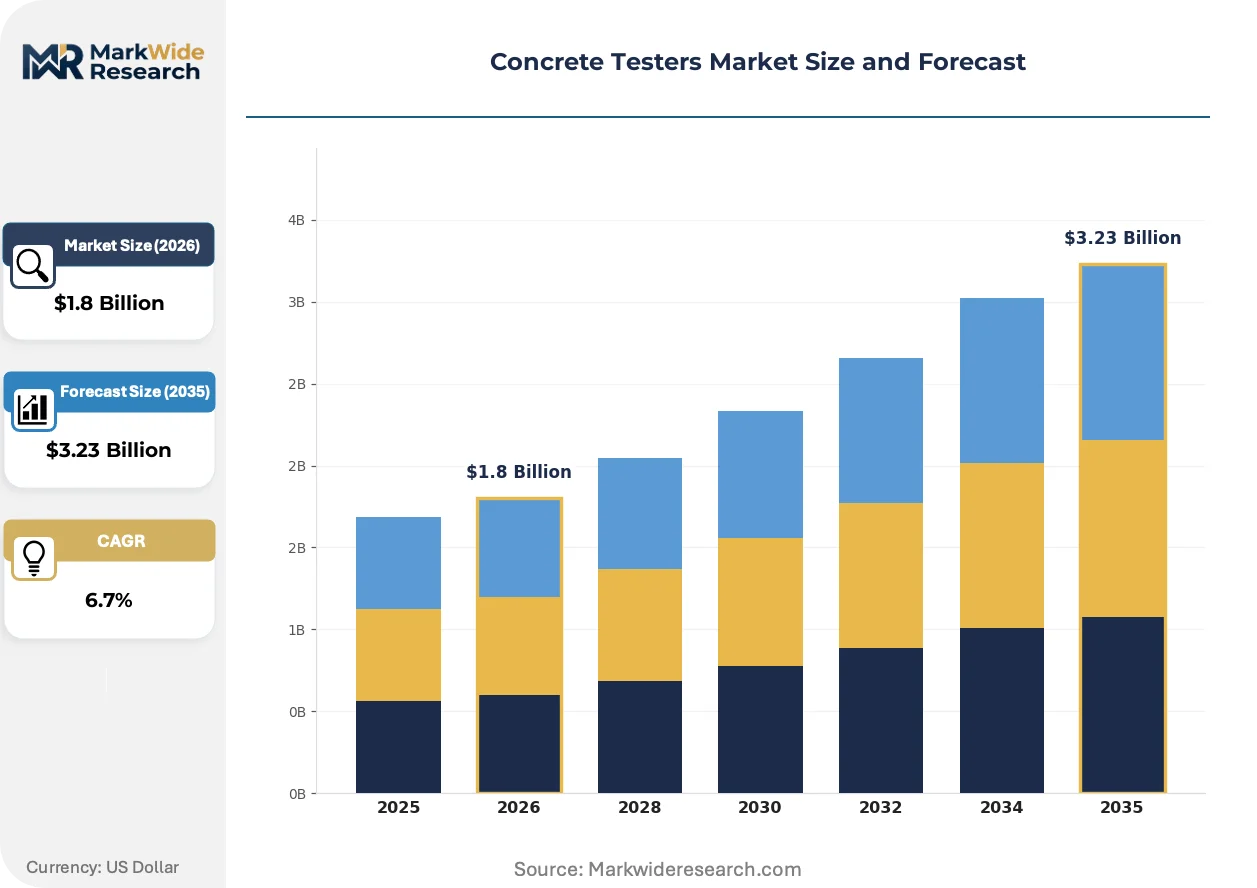
Market Dynamics
Bridge condition monitoring mandates from the US Federal Highway Administration and the EU Construction Products Regulation are forcing asset owners to replace mechanical testers with digital systems that log compression data automatically. This regulatory pressure is compressing replacement cycles and redistributing procurement budgets toward connected equipment platforms.
Growth Catalysts
- Infrastructure resilience mandates:The US Federal Highway Administration requires documented compressive strength verification for federal-aid highway projects, mandating digital logging capabilities that accelerate equipment turnover among state DOT contractors.
- Autobahn maintenance programs:Germany's precision engineering corridor around Stuttgart concentrates demand for calibration-intensive electromechanical systems, with procurement volumes tied to federal transport infrastructure renewal schedules.
- Ultrasonic pulse velocity adoption:Bridge owners across North America and Europe are deploying 50–100 kHz non-destructive evaluation systems to monitor internal flaw propagation without core sampling, expanding the addressable instrument base.
Market Restraints
- Calibration labor intensity:Electromechanical load frames require annual third-party calibration against ISO 7500-1 standards, creating recurring cost burdens that deter small contractors from premium system adoption.
- Steel and electronics input volatility:Load frame fabrication depends on structural steel and precision load cell components, with price swings compressing margins for manufacturers lacking long-term supplier contracts.
- Mechanical tester installed base:Decades of accumulated analog compression machines in emerging markets create substitution resistance where capital constraints limit outright replacement purchases.
Strategic Opportunities
- Performance-based service contracts:Highway contractors in capital-constrained markets are shifting from equipment purchase to leasing models with guaranteed uptime, opening recurring revenue streams for vendors with balance-sheet capacity.
- Cloud-connected reporting platforms:Automated data logging that satisfies third-party audit requirements commands margin premiums over mechanical alternatives, particularly among contractors serving federally funded projects.
- Non-destructive condition monitoring:Bridge inspection protocols are expanding beyond compressive strength to permeability and elastic modulus testing, creating demand for multi-parameter field instruments.
Industry Challenges
- Field calibration technician scarcity:Electromechanical systems require specialists trained to ISO 7500-1 procedures, with certification bottlenecks limiting service network expansion in secondary markets.
- Legacy data integration:Contractors operating mixed fleets of analog and digital testers face workflow fragmentation when cloud platforms cannot ingest historical mechanical test records.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Concrete Testers Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rebound Hammer, Penetration Tester, Ultrasonic Pulse Velocity Tester, Compression Testing Machine End User: Construction Companies, Quality Control Labs, Research Institutions, Contractors Technology: Digital, Mechanical, Electromechanical, Hydraulic Application: Field Testing, Laboratory Testing, Non-Destructive Testing, Structural Analysis |
| Companies Covered | PCE Instruments, Humboldt Mfg. Co., ELE International, Matest S.p.A., Controls S.p.A., Aimil Ltd., Gilson Co., Canopus Instruments, EIE Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Concrete Testers Market Emerging Trajectories
Digital automation is collapsing the operational gap between laboratory-grade precision and field-deployable durability. Three interconnected developments are restructuring how compression data is captured, validated, and transmitted across construction workflows.
Wireless load cell arrays with embedded strain gauges are collapsing the distinction between fixed laboratory frames and portable field units. State DOT inspection teams in the US and German autobahn maintenance crews are deploying battery-powered 500 kN systems that transmit results directly to cloud databases, eliminating manual transcription errors and compressing report generation from days to hours.
ASTM International's pending revisions to C39 compressive strength protocols are mandating automated rate-of-loading control and continuous data capture, effectively disqualifying hand-cranked mechanical machines from certified testing. US highway contractors facing OSHA workplace safety inspections are preemptively retiring hydraulic systems that lack electronic load feedback, accelerating the obsolescence of analog installed bases.
Equipment-as-a-service contracting is displacing outright purchase for municipal agencies with constrained capital budgets. Brazilian state infrastructure departments and Indian highway authorities are procuring tester capacity through monthly subscription models that bundle calibration, maintenance, and software updates, transferring asset ownership risk to vendors while locking in multi-year revenue commitments.
Concrete Testers Market Segmentation
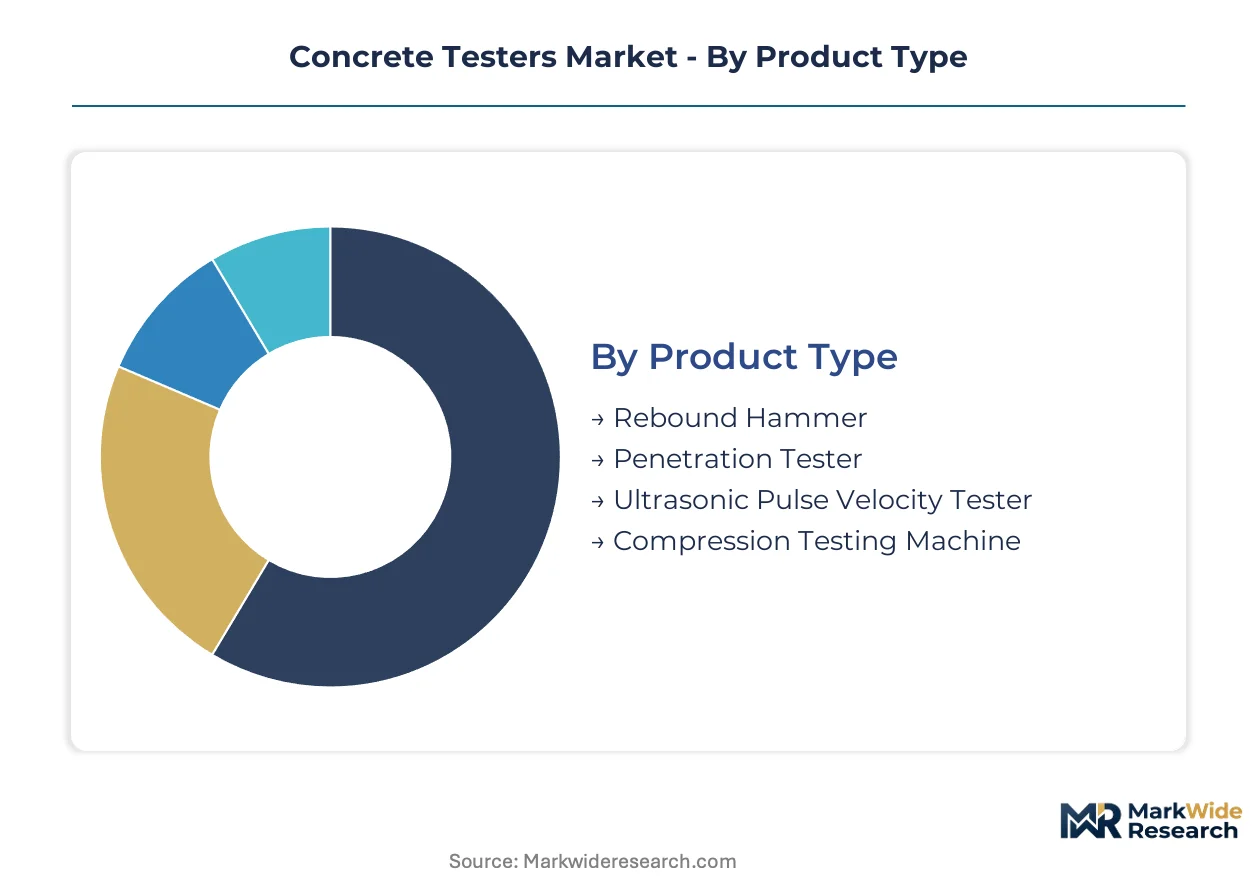
Concrete tester procurement patterns diverge sharply across use cases. Compression testing machines carry decade-long depreciation schedules while ultrasonic systems refresh every three to five years as sensor technology advances.
Product Type:
Replacement cycles stretch from three years for handheld digital units to fifteen years for fixed-frame compression systems, creating distinct revenue timing across vendor portfolios.
- Compression Testing Machine:Stationary load frames rated 50 kN to 5,000 kN dominate batch verification protocols for highway concrete. German autobahn maintenance programs concentrate procurement of calibration-intensive electromechanical variants where ISO 7500-1 compliance is mandatory.
- Ultrasonic Pulse Velocity Tester:Portable 50–100 kHz pulse generators assess internal flaw propagation without core extraction. Bridge inspection teams across the US Federal Highway Administration's jurisdiction are displacing mechanical rebound hammers with these units, compressing replacement cycles to four-year intervals.
- Rebound Hammer:Spring-driven Schmidt hammers deliver surface hardness estimates for field screening. Emerging market contractors lacking capital budgets retain these mechanical units despite ASTM C39 protocol revisions.
- Penetration Tester:Probe-based systems measure concrete cover depth and rebar location. Quality control labs in India's infrastructure corridors deploy these for pre-pour verification where speed outweighs precision.
Compression testing machines dominate installed base. Ultrasonic pulse velocity testers are where expansion concentrates.
End User:
Procurement authority clusters where federal funding flows, with equipment specifications written by regulators rather than end users.
- Construction Companies:General contractors on federally aided highway projects must deploy ASTM C39-compliant digital loggers. OSHA workplace safety inspections are accelerating retirement of hydraulic systems lacking electronic load feedback.
- Quality Control Labs:Third-party certification bodies operate under ISO 17025 accreditation mandates. These facilities concentrate in Germany's precision engineering corridor around Stuttgart, sourcing calibration-intensive electromechanical frames.
- Contractors:Highway specialty firms lease equipment through performance-based service contracts where uptime guarantees substitute for capital expenditure. Brazilian state infrastructure departments favor monthly subscription models.
- Research Institutions:University laboratories and national standards bodies validate new test protocols. These users pilot wireless load cell arrays before commercial deployment to state DOT inspection teams.
Construction companies generate the highest equipment turnover. Quality control labs concentrate margin capture through calibration services.
Technology:
Cost tiers separate mechanical legacy systems from digital platforms commanding premium pricing through automated compliance reporting.
- Digital:Embedded sensors and cloud connectivity satisfy third-party audit requirements for federal-aid projects. Battery-powered 500 kN field units transmit results directly to databases, eliminating transcription errors.
- Electromechanical:Servo-controlled load frames balance precision with operational safety under EU Machinery Directive specifications. These systems require annual third-party calibration, creating recurring revenue for service networks.
- Hydraulic:Fluid-powered compression remains prevalent in emerging market installed bases. Capital constraints and technician scarcity delay replacement despite ASTM protocol revisions.
- Mechanical:Hand-cranked analog machines face obsolescence as ASTM C39 mandates automated rate-of-loading control. Decades of accumulated stock in secondary markets create substitution resistance.
Electromechanical systems anchor the premium tier. Digital platforms are gaining share fastest through regulatory mandate compliance.
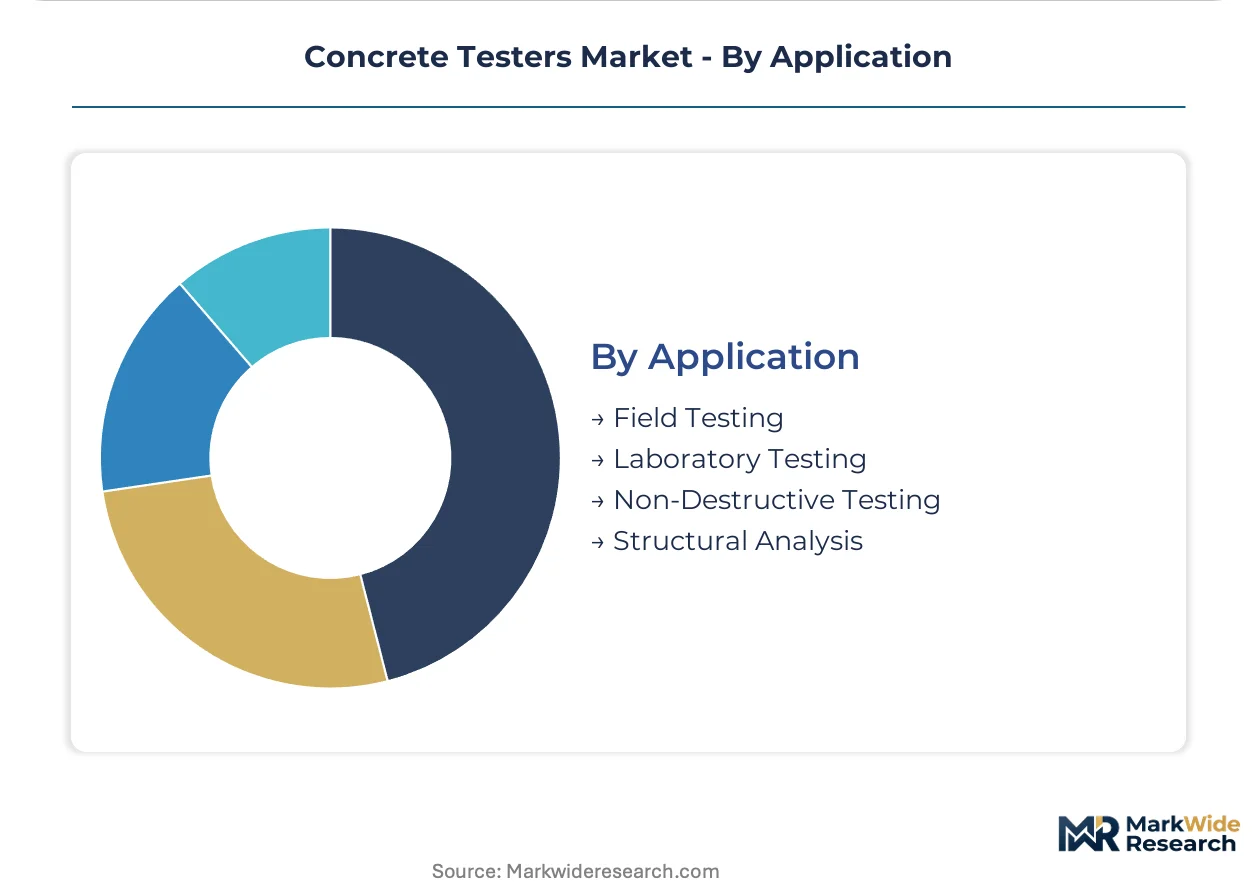
Application:
Volume concentration follows infrastructure inspection schedules, with field deployment growing faster than laboratory certification.
- Field Testing:Portable units for fresh and hardened concrete assessment at construction sites. US state DOT inspection teams deploy wireless 500 kN systems for bridge condition monitoring mandated by federal highway administration protocols.
- Non-Destructive Testing:Ultrasonic and rebound methods evaluate internal integrity without specimen damage. Expansion concentrates here as asset owners shift from destructive core sampling to continuous condition assessment.
- Laboratory Testing:Controlled environment compression and permeability analysis for mix design validation. German autobahn concrete suppliers maintain captive labs for batch release certification.
- Structural Analysis:Post-construction evaluation of load-bearing capacity and remaining service life. Research institutions pilot multi-parameter instruments measuring elastic modulus alongside compressive strength.
Field testing commands the largest equipment population. Non-destructive testing represents the steepest expansion trajectory as inspection protocols evolve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in concrete testing equipment favor German and US manufacturers supplying calibration-intensive systems to infrastructure programs across Asia-Pacific and Latin America. Trade balances reflect concentrated precision engineering capabilities in Stuttgart's industrial corridor and regulatory-driven replacement demand in federal highway jurisdictions.
United States
Federal-aid highway programs and state DOT inspection mandates drive procurement of digital logging systems. The US Federal Highway Administration requires documented compressive strength verification with automated data capture. Equipment leasing concentrates in Texas and California where municipal agencies face capital budget constraints.
Germany
Autobahn maintenance schedules and ISO 17025 accreditation requirements sustain demand for electromechanical calibration services. The EU Construction Products Regulation mandates third-party verification protocols. Stuttgart's precision engineering corridor hosts quality control labs sourcing high-load frames for federal transport infrastructure renewal.
China
High-speed rail expansion and urban infrastructure investment create demand for field-deployable testing units. GB standards for construction materials testing shape procurement specifications. Yangtze River Delta contractors are displacing mechanical rebound hammers with ultrasonic systems for bridge condition assessment.
India
National highway development programs and smart city initiatives accelerate instrument procurement despite capital constraints. BIS certification requirements for construction materials create compliance-driven replacement cycles. Maharashtra and Gujarat infrastructure contractors favor rental models for compression testing capacity.
Brazil
Federal infrastructure investment programs and state-level road maintenance contracts sustain equipment demand. ANVISA-equivalent construction safety protocols influence testing equipment specifications. São Paulo state infrastructure departments lead adoption of subscription-based service contracts for municipal concrete verification.
Concrete Testers Market Vendor Landscape
On the supply side, the industry is structured around three tiers: precision calibration specialists serving accredited laboratories, rental-service providers targeting capital-constrained contractors, and regional fabricators supplying mechanical legacy systems. Strategic archetypes include German electromechanical precision houses, North American field-service organizations, and emerging market rental penetration specialists. Competitive moves concentrate on balance-sheet capacity for long-term receivables and geographic expansion of calibration technician networks.
Among European precision specialists, PCE Instruments and Matest S.p.A. exemplify the calibration-intensive tier anchored in German and Italian manufacturing bases. Humboldt Mfg. Co. represents the North American field-service archetype with direct distribution control. These three occupy positions defined by regulatory compliance capabilities and aftermarket service infrastructure rather than manufacturing scale alone.
| Leading Market Players |
|---|
| PCE Instruments |
| Humboldt Mfg. Co. |
| ELE International |
| Matest S.p.A. |
| Controls S.p.A. |
| Aimil Ltd. |
| Gilson Co. |
| Canopus Instruments |
| EIE Instruments |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese load frame fabrication is compressing margins for European precision manufacturers while simultaneously expanding pricing leverage for calibration-intensive electromechanical specialists in Germany. This utilization divergence is bifurcating procurement negotiations, with buyers in federally funded highway programs absorbing premium pricing for ISO 7500-1 compliant systems while emerging market contractors exploit commoditized hydraulic alternatives.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on certification grade—ASTM C39 digital loggers command substantial premiums over mechanical units—and after-sales calibration bundling. Cost compression in the hydraulic tier is intensifying because of steel input volatility and surplus Chinese manufacturing capacity. Municipal agencies with constrained capital budgets exhibit highest price sensitivity, while accredited quality control labs in Germany demonstrate lowest sensitivity due to regulatory compliance mandates.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for load cell and electronics sourcing. Manufacturing gravity centers on Germany for precision electromechanical systems, China for structural steel fabrication and electronic components, and Italy for specialized calibration equipment. Raw material dependencies draw from structural steel, precision load cells, and embedded sensor arrays. Distribution runs through direct field-service teams controlling aftermarket revenue in North America, manufacturer-owned calibration networks in Europe, and third-party rental specialists in Latin America and South Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among federal highway contractors and state infrastructure departments, with procurement authority consolidating around performance-based service contracts that transfer asset ownership risk to vendors.
For Market Incumbents: Build calibration-service moats by expanding ISO 17025 accredited technician networks into secondary markets where certification bottlenecks limit competitor entry. Deepen backward integration into precision load cell production to insulate margins from steel and electronics volatility. Preempt displacement threats from ultrasonic non-destructive systems by bundling multi-parameter field instruments with existing compression testing platforms. For New Entrants and Emerging Players: Mid-market highway contractors in India and Brazil represent the most penetrable entry point, where capital constraints and rental model acceptance lower barriers to equipment-as-a-service deployment. Brazilian state infrastructure departments already favor subscription procurement, providing a proven go-to-market template. Target wireless load cell arrays for portable field deployment, as bridge inspection mandates accelerate replacement of fixed laboratory systems. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vendors with captive calibration networks and long-term service contracts. Long-term viability favors precision specialists with regulatory compliance capabilities rather than commodity fabricators. Acquisition target archetypes include regional rental-service providers with established municipal relationships and emerging market distribution platforms. Monitor ASTM protocol revision timing for inflection signals on analog equipment obsolescence acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Network Expansion | ISO 17025 accreditation in secondary markets locks out uncertified competitors serving federal highway contractors. |
| Equipment-as-a-Service Launch | Monthly subscription models transfer capital risk to vendors while capturing multi-year revenue from Brazilian and Indian infrastructure agencies. |
| Wireless Load Cell Development | Battery-powered field units with cloud connectivity satisfy US Federal Highway Administration digital logging mandates for bridge inspections. |
| Backward Integration into Load Cells | In-house production of precision strain gauge components insulates margins from electronics supply volatility and tariff exposure. |
| Multi-Parameter Instrument Platform | Combined compressive strength and ultrasonic pulse velocity testing addresses expanding bridge condition monitoring protocols beyond core sampling. |
Methodological Framework
Operator-level perspectives from highway contractors, state DOT procurement officers, calibration service technicians, and quality control laboratory managers anchored the qualitative base. Primary interviews combined with secondary validation from ASTM International protocol documentation, US Federal Highway Administration procurement records, EU Construction Products Regulation filings, and ISO 7500-1 calibration standard archives. Customs data on load frame trade flows and SEC filings from publicly traded testing equipment manufacturers provided quantitative triangulation. Bottom-up equipment unit economics and top-down infrastructure spending forecasts were reconciled across modeling approaches.
Scenario-bracketing framed the projection horizon, with analytical outputs tested against regulatory acceleration cases and capital constraint scenarios. Segmentation dimensions modeled include product type, end user category, technology tier, and application setting alongside regional regulatory cluster alignment. CAGRs were derived from replacement cycle analysis and infrastructure renewal schedule correlation. Forecast inputs incorporated autobahn maintenance program timelines, federal highway aid disbursement patterns, and emerging market rental model penetration rates.
Practitioners should monitor ASTM C39 protocol revision implementation timing and EU Machinery Directive enforcement intensity for early signals of analog equipment obsolescence acceleration. Forecasts reflect assumptions on regulatory compliance adoption curves and steel input price stability that could revise with trade policy shifts or construction sector demand shocks. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Foundry Sand Cleaning Machine Market
Construction Equipment
India Crane Market
Construction Equipment
Heavy Construction Equipment Rental Market
Construction Equipment
Earthmoving Equipment Market
Construction Equipment
Earthmoving Equipment Tyres Market
Construction Equipment
Field Marking Equipment Market
Construction Equipment
Electrofusion Welding Machines Market
Construction Equipment
Demolition Equipment Market
Construction Equipment
Garage Equipment Market
Construction Equipment
Mobile Asphalt Plant Market
Construction Equipment
Shield Machines Market
Construction Equipment
Mini Excavators Market
Construction Equipment
Southern Africa Construction Equipment Rental Market
Construction Equipment
Extrusion Equipment Market
Construction Equipment
Rail Welding Equipment Market
Construction Equipment
Drilling Machine Market