
 Crane Aftermarket Market | 2026-2036
Crane Aftermarket Market Size, Share, and Industry Trends Forecast 2026-2036
Crane Aftermarket Market Analysis
Aftermarket service revenue is tilting from break-fix contracts toward predictive maintenance agreements tied to IoT-enabled load monitoring. Konecranes leverages its TRUCONNECT remote monitoring platform to anchor long-term service relationships across port and industrial installations. Manitowoc competes through its EnCORE remanufacturing program, which extends component life cycles for crawler and tower crane operators. Palfinger AG specializes in knuckle-boom aftermarket support, dominating service density in European utility and construction channels.
The crane aftermarket encompasses the supply of replacement components, functional accessories, system upgrades, and technical services that sustain operational cranes beyond original manufacture, typically involving high-strength steel assemblies rated for dynamic load cycles in excess of 500,000 lifts. Replacement parts and services capture the dominant margin pools given the non-discretionary nature of safety-critical component renewal, while upgrades represent the fastest-expanding category as fleet owners retrofit older machines with anti-collision systems and electrified drivetrains. Direct sales and distributor channels remain structurally entrenched for complex assemblies requiring factory technical support, though online retail gains traction for standardized consumables such as wire rope and brake pads.
OSHA crane inspection standards in the United States mandate annual comprehensive assessments, directly sustaining demand for certified inspection services and replacement of fatigued structural elements. The EU Machinery Directive and CE marking requirements enforce traceability for aftermarket safety components, creating compliance-driven preference for OEM-authorized parts across European installations. China GB standards and MEE emissions protocols are tightening retrofit obligations for domestic port equipment, reshaping upgrade demand in East Asian logistics corridors. Stakeholders must weigh captive service network investments against third-party platform partnerships as telematics data becomes the primary interface for aftermarket customer retention.
Market Dynamics
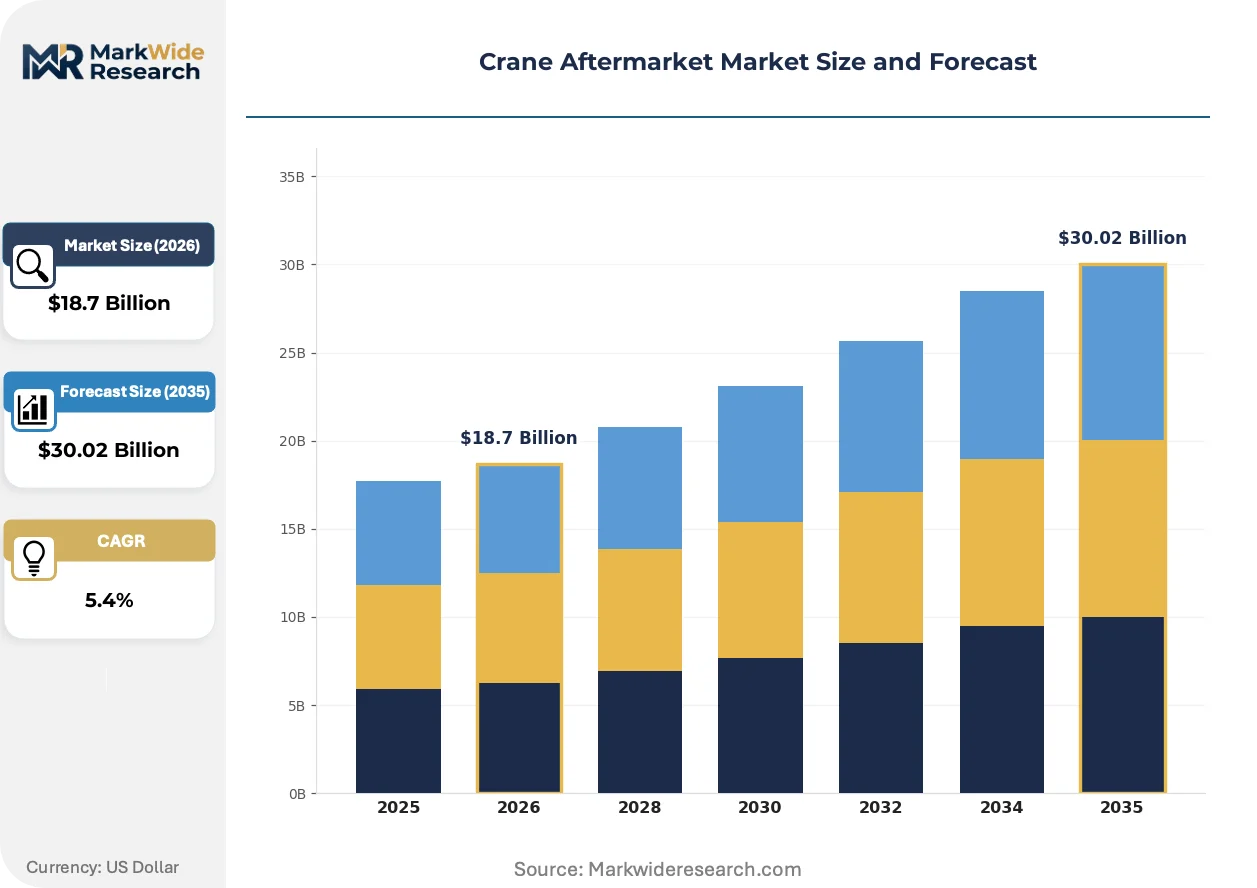
The crane aftermarket is compressing around predictive maintenance architectures as IoT-enabled load monitoring restructures service contract economics and customer retention mechanics.
Growth Catalysts
- EPA emissions tightening:Construction fleet operators in the United States face mandatory diesel equipment retrofits, accelerating procurement of electrified drivetrain upgrades and exhaust after-treatment systems for legacy crawler and tower crane installations.
- Port modernization in Germany:Hamburg and Bremerhaven infrastructure investments drive replacement parts demand for ship-to-shore crane systems, particularly high-cycle steel assemblies rated for container handling volumes exceeding 500,000 lifts annually.
- Wire rope consumables:Standardized replacement cables and brake pads migrate toward online retail channels, expanding addressable reach for independent distributors serving utility and construction maintenance programs.
Market Restraints
- High-strength steel input volatility:Alloy price fluctuations for crane-rated structural materials compress margin predictability for replacement boom and mast component fabricators.
- OEM captive network concentration:Factory-authorized service density in North American industrial corridors limits third-party penetration for complex assembly repairs requiring proprietary technical documentation.
- CE marking traceability friction:EU Machinery Directive compliance costs for aftermarket safety component documentation create preference lock-in toward OEM-authorized parts, disadvantaging independent suppliers.
Strategic Opportunities
- Anti-collision system retrofits:Aging fleet operators in Japan seek tower crane proximity sensor upgrades to satisfy METI construction safety guidelines and reduce job site liability exposure.
- Telematics-platform partnerships:Third-party service providers can access predictive maintenance data streams through API integrations with established remote monitoring architectures, bypassing captive network investments.
- India port corridor expansion:Jawaharlal Nehru Port Trust and Mundra Port capacity additions under the PLI scheme for logistics infrastructure generate replacement parts demand for rubber-tired gantry crane systems.
Industry Challenges
- Certified inspector scarcity:OSHA-mandated annual comprehensive assessments require qualified personnel for structural fatigue evaluation, constraining service capacity expansion in high-demand construction corridors.
- Legacy system integration complexity:Electrified drivetrain retrofits onto mechanically controlled crane architectures demand custom control system engineering, extending project timelines and technical risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crane Aftermarket Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $30.02 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Replacement Parts, Accessories, Upgrades, Services End User: Construction Companies, Industrial Facilities, Rental Services, Shipping Firms Sales Channel: Direct Sales, Online Retail, Distributors, Auctions Service Type: Maintenance, Repair, Inspection, Consulting |
| Companies Covered | Altec Industries, Konecranes, Manitowoc, Tadano Ltd., Palfinger AG, Manitex International, Hiab, Sany Group, XCMG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crane Aftermarket Market Emerging Trajectories
Predictive analytics and connected infrastructure are restructuring how crane operators contract for maintenance, shifting economic value from reactive repair toward data-driven uptime guarantees.
Telematics-enabled condition monitoring is migrating from break-fix service models toward subscription-based availability contracts. Port operators and heavy industrial facilities now specify guaranteed uptime clauses backed by real-time load cycle data. This architecture compresses pricing power for traditional time-and-materials service providers while elevating retention value for platform-integrated OEMs.
China's GB standards and MEE emissions protocols are tightening retrofit obligations for domestic port equipment. Domestic logistics corridor operators must document compliance with particulate matter thresholds for diesel-powered rubber-tired gantry systems. East Asian port authorities are responding by accelerating electrification procurement timelines and consolidating upgrade vendor relationships.
Service contract unbundling is fragmenting traditional aftermarket relationships. Large construction fleet operators now separate inspection, parts supply, and repair execution across specialized providers. This pattern is most visible in German-speaking European markets where utility sector procurement teams apply category management discipline to crane maintenance spend.
Crane Aftermarket Market Segmentation
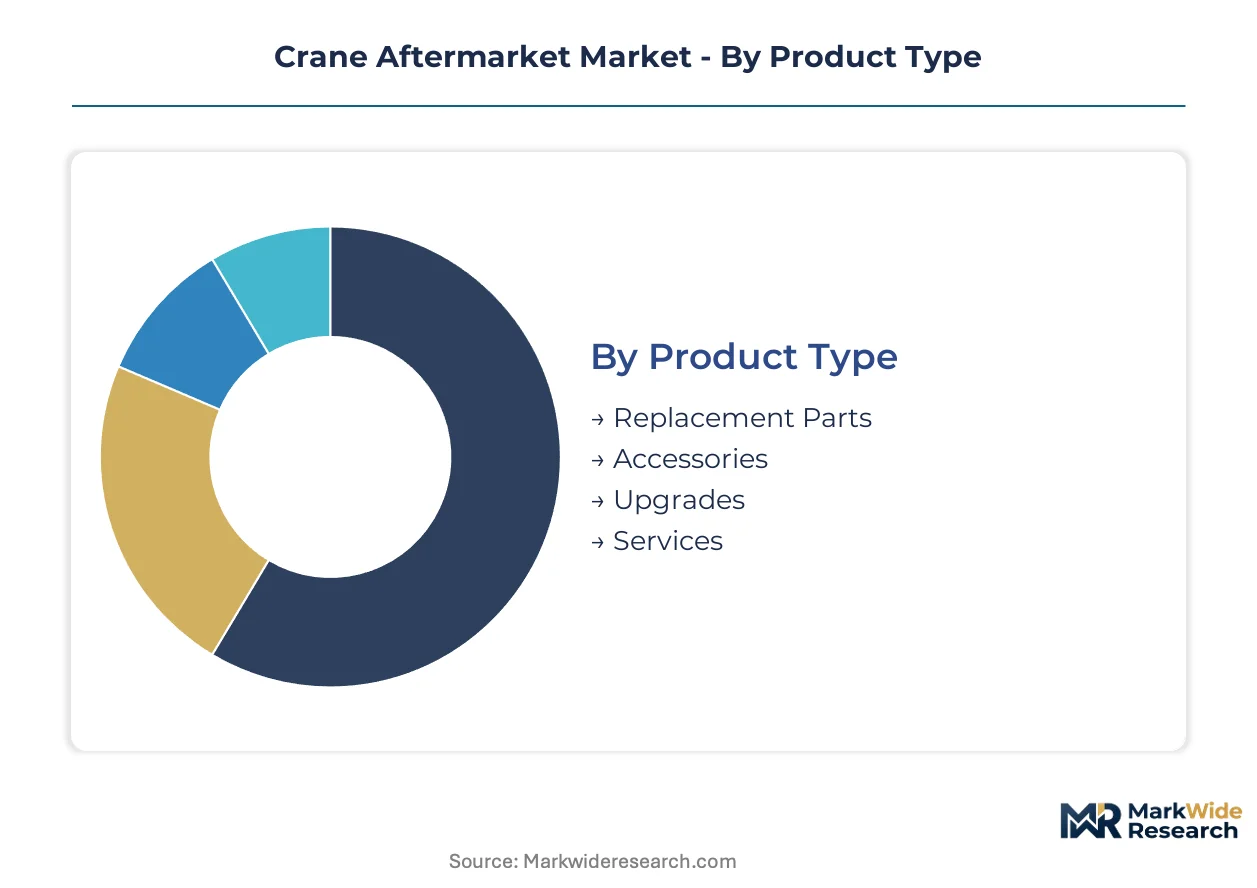
Segmentation in the crane aftermarket reveals how service intensity, procurement patterns, and technical complexity fragment revenue pools across distinct customer workflows and equipment life cycle stages.
Product Type:
After-sales service intensity varies dramatically by product category, with safety-critical components demanding captive OEM relationships while consumables migrate toward price-transparent channels.
- Replacement Parts:High-strength steel assemblies rated for dynamic load cycles exceeding 500,000 lifts dominate procurement spend. Hamburg and Bremerhaven port operators drive demand for ship-to-shore crane structural elements as container handling volumes strain legacy systems.
- Services:Predictive maintenance agreements anchored to IoT-enabled load monitoring platforms are restructuring contract economics. EPA emissions tightening for diesel-powered lifting equipment accelerates service bundling with electrified drivetrain retrofit programs across United States construction fleets.
- Upgrades:Anti-collision system retrofits and electrified drivetrain conversions represent the steepest expansion trajectory as fleet owners extend asset life.
- Accessories:Functional add-ons including enhanced lighting packages and operator comfort systems capture niche demand from rental fleet standardization programs.
By volume, Replacement Parts leads. By growth pace, Upgrades is ahead.
End User:
Cost tier differentiation separates capital-intensive owner-operators from price-sensitive rental intermediaries, reshaping contract structures and parts procurement authority.
- Construction Companies:Fleet refurbishment programs concentrate in North America as EPA emissions standards tighten for diesel-powered equipment. These operators prioritize OEM-authorized parts for safety-critical structural renewals.
- Industrial Facilities:Heavy process industry installations specify guaranteed uptime clauses backed by real-time load cycle data, elevating predictive maintenance contract penetration.
- Shipping Firms:Port modernization in Germany drives replacement parts procurement for rubber-tired gantry and ship-to-shore systems.
- Rental Services:Equipment intermediaries unbundle inspection, parts supply, and repair execution across specialized providers to optimize category management discipline.
Construction Companies generate the largest absolute spend. Industrial Facilities are expanding most quickly.
Sales Channel:
Supply concentration patterns favor direct factory relationships for complex assemblies while standardized consumables fragment toward digital marketplaces.
- Direct Sales:Factory-authorized channels retain structural dominance for boom and mast assemblies requiring proprietary technical documentation and certified installation support.
- Distributors:Independent networks sustain penetration in European utility and construction channels through localized inventory positioning and field service capability.
- Online Retail:Wire rope and brake pad consumables migrate toward digital procurement platforms, expanding addressable reach for price-sensitive maintenance programs.
- Auctions:Secondary market liquidation channels serve fleet operators disposing of obsolete component inventories and salvage-grade assemblies.
Direct Sales captures the highest transaction values. Online Retail is gaining share fastest.
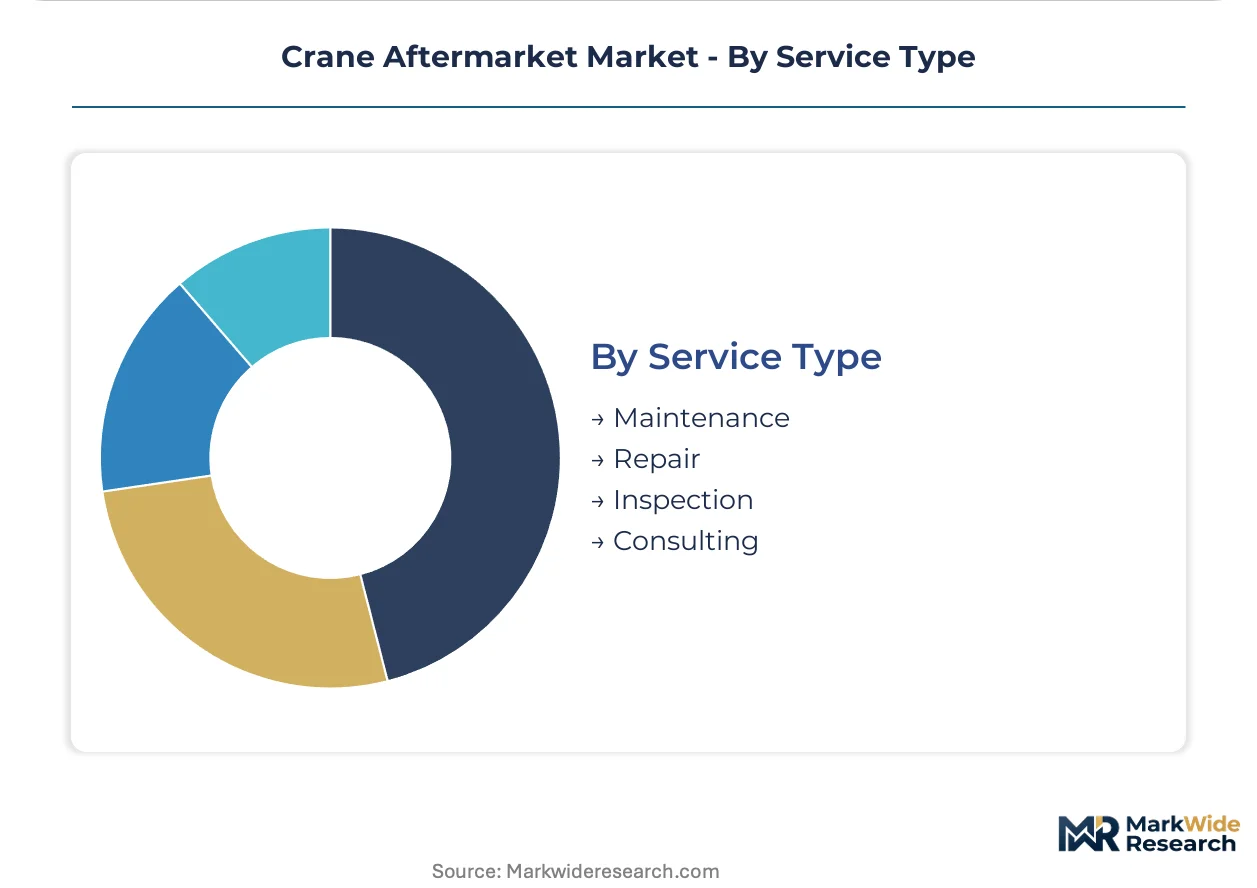
Service Type:
Maturity gradients separate commoditized break-fix repair from high-margin predictive offerings, with inspection services locked in by regulatory mandate.
- Maintenance:Subscription-based availability contracts backed by telematics data are displacing traditional time-and-materials arrangements in port and industrial installations.
- Inspection:OSHA-mandated annual comprehensive assessments create non-discretionary demand for certified structural fatigue evaluation services across United States construction corridors.
- Repair:Break-fix execution remains concentrated in captive OEM networks for complex assembly work, though third-party providers penetrate standardized component replacement.
- Consulting:Technical advisory services support electrification retrofit planning and compliance documentation for EU Machinery Directive traceability requirements.
Maintenance commands the largest contract values. Inspection exhibits the most regulatory stability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. United States operators prioritize EPA-compliant electrification retrofits, while German port authorities concentrate procurement on high-cycle structural assemblies, and Chinese logistics corridors accelerate domestic emissions standard alignment.
United States
Construction fleet operators drive diesel equipment retrofit demand as EPA emissions standards tighten for legacy crawler and tower crane installations. OSHA mandates annual comprehensive crane inspections, sustaining certified structural fatigue evaluation services. Gulf Coast petrochemical corridors and Texas shale basins anchor aftermarket service density for heavy industrial lifting equipment.
Germany
Hamburg and Bremerhaven port modernization investments propel replacement parts procurement for ship-to-shore crane systems rated beyond 500,000 annual lifts. EU Machinery Directive CE marking requirements enforce traceability for aftermarket safety components. North Rhine-Westphalia industrial clusters concentrate predictive maintenance contract penetration for steel-handling gantry systems.
China
Domestic port operators face MEE emissions protocol retrofit obligations for rubber-tired gantry crane fleets. GB standards mandate particulate matter compliance documentation for diesel-powered logistics equipment. Yangtze River Delta logistics corridors consolidate electrification vendor relationships under accelerated procurement timelines.
Japan
Aging tower crane fleet operators seek anti-collision system upgrades to satisfy METI construction safety guidelines. JIS standards govern structural component replacement specifications for high-rise building projects. Kanto region metropolitan construction density concentrates demand for proximity sensor retrofit installations.
India
Jawaharlal Nehru Port Trust and Mundra Port capacity additions under the PLI scheme for logistics infrastructure generate rubber-tired gantry crane replacement parts demand. CEA technical standards shape procurement specifications for port material handling equipment. Gujarat maritime corridor investments anchor aftermarket service network expansion for container terminal operators.
Crane Aftermarket Market Vendor Landscape
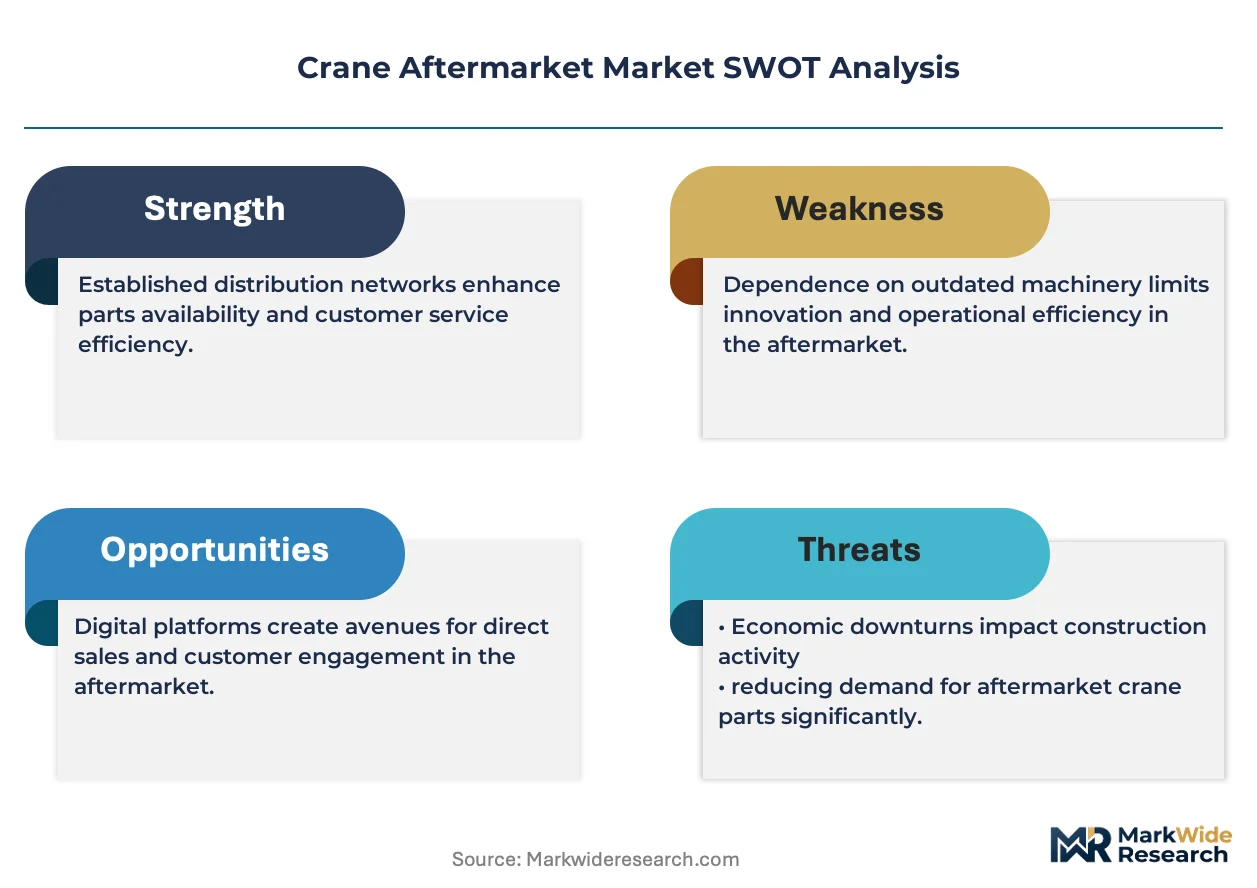
Capability concentration sits with specialized OEMs commanding proprietary technical documentation; scale advantage sits with diversified industrial conglomerates leveraging cross-sector service infrastructure. The vendor base organizes around three strategic archetypes: platform-integrated OEMs with captive telematics networks, independent component fabricators serving price-sensitive consumables demand, and regional service specialists anchoring localized field support. Dominant competitive moves include strategic partnerships for predictive maintenance data access and geographic expansion of authorized service territories.
Among platform-integrated specialists, Konecranes anchors remote monitoring service relationships across port installations. Manitowoc occupies a position within the remanufacturing archetype for crawler and tower crane life cycle extension. Palfinger AG exemplifies regional density strategy, concentrating aftermarket support within European utility and construction channels. These three represent distinct competitive vectors: data-platform retention, component life cycle extension, and geographic service specialization.
| Leading Market Players |
|---|
| Altec Industries |
| Konecranes |
| Manitowoc |
| Tadano Ltd. |
| Palfinger AG |
| Manitex International |
| Hiab |
| Sany Group |
| XCMG |
| Others |
Supply Flow & Price Mechanics
Ruhr Valley steel fabrication clusters anchor high-strength alloy supply for crane structural components, translating upstream capacity discipline into pricing power for replacement boom and mast assemblies across European port and industrial installations.
Pricing Analysis
Long-term service contracts with embedded parts procurement dominate the crane aftermarket, displacing spot transactions for safety-critical assemblies. Three-tier pricing structure across OEM-authorized, certified aftermarket, and economy consumable levels segments buyers by risk tolerance and compliance requirements. Cost compression in standard wire rope and brake pad categories intensifies as online retail channels expand price transparency. Rental fleet operators exhibit the highest price sensitivity, while owner-operators of port handling systems prioritize OEM-authorized parts for liability protection.
Supply Chain Analysis
Extended payment terms from German and Japanese component fabricators to raw material processors stabilize alloy procurement through high-strength steel price cycles. Supply concentration rests in Germany, China, and Japan for crane-rated structural forgings and precision-machined assemblies. Specialty alloy dependencies for fatigue-resistant boom sections and high-cycle wire rope constructions create single-source vulnerability for certain specification grades. Distribution runs through factory-authorized service networks for complex assemblies, while independent distributors and digital platforms capture standardized consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The crane aftermarket functions as a service-attach opportunity where predictive maintenance subscriptions and electrification retrofit programs expand faster than transactional parts replacement, rewarding platform-integrated vendors with recurring revenue density.
For Market Incumbents: Pre-empt third-party telematics encroachment by deepening API integration with port operator enterprise systems, locking data architecture before independent platforms achieve critical mass. Capture certified inspector capacity through vocational partnerships in OSHA-mandated United States construction corridors, constraining competitor service expansion. Vertical integration into high-strength steel component forging secures margin control against alloy price volatility.
For New Entrants and Emerging Players: Build out specialized electrification retrofit engineering capabilities for legacy mechanically controlled crane architectures, where OEMs lack incentive to support aging fleet segments. Target India's Jawaharlal Nehru Port Trust and Mundra Port expansion corridors under PLI scheme logistics infrastructure investments, where authorized service density remains underdeveloped. Pursue telematics-platform partnerships through API access rather than captive network investment, bypassing capital-intensive field service buildout.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platform-integrated service providers with predictive maintenance data streams over pure-play component fabricators facing commodity pricing pressure. Long-term viability hinges on electrification retrofit execution capability and regulatory compliance documentation infrastructure. The signal to watch is EPA enforcement intensity for diesel equipment emissions and corresponding acceleration of fleet refurbishment program timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Konecranes' TRUCONNECT architecture anchors long-term port service relationships through real-time load monitoring data retention. |
| Remanufacturing Program Expansion | Manitowoc's EnCORE initiative extends component life cycles for crawler and tower crane operators facing capital constraints. |
| Electrification Retrofit Engineering | Custom control system integration for legacy crane architectures addresses EPA emissions tightening across United States construction fleets. |
| Certified Inspector Network Development | OSHA-mandated annual comprehensive assessments create structural demand for qualified structural fatigue evaluation personnel. |
| Regional Service Density Concentration | Palfinger AG's European utility and construction channel specialization demonstrates geographic focus as competitive moat. |
Methodological Framework
A spread of perspectives from maintenance directors at port authorities, plant engineers at heavy industrial facilities, aftermarket service heads at OEMs, and procurement leads at construction fleet operators converged on the working assumptions for crane aftermarket demand modeling. Primary field engagement combined with secondary validation from customs and trade data, SEC 10-K filings of listed equipment manufacturers, and port authority procurement disclosures. Bottom-up segmentation sizing and top-down macroeconomic anchoring were triangulated to constrain variance.
Demand-supply balance dynamics across replacement parts procurement, predictive maintenance contract penetration, and electrification retrofit installation rates structured the analytical framework over the projection horizon. Segmentation dimensions modeled include product type, end-user industry, sales channel, and service contract structure, with regional regulatory cluster effects layered across geographies. CAGRs were derived from installed base aging profiles, regulatory compliance timelines, and technology substitution curves for diesel-to-electric drivetrain conversions.
Stress conditions across high-strength steel alloy price volatility, EPA enforcement intensity variations, and certified inspector labor availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about fleet age distributions and regulatory implementation pacing. Macroeconomic construction cycle downturns, accelerated emissions standard adoption, or breakthrough battery technology for mobile cranes would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Case Erectors Market
Construction Equipment
Global Construction Industry Core Drill Market
Construction Equipment
Industrial Agitators Market
Construction Equipment
Hydraulic Intensifiers Market
Construction Equipment
Europe Used Construction Machinery Market
Construction Equipment
Welding Equipment Market
Construction Equipment
BRICS Aerial Work Platforms Market
Construction Equipment
Garage Equipment Market
Construction Equipment
Heavy Duty IBC Market
Construction Equipment
Trenchers Market
Construction Equipment
Mortar Testing Equipment Market
Construction Equipment
Truck Mounted Knuckle Boom Cranes Market
Construction Equipment
Vertical Grinding Mills Market
Construction Equipment
North America Mobile Crane Market
Construction Equipment
Concrete Placing Booms Market
Construction Equipment
Asia-Pacific Mobile Light Tower Market