
 Crushing, Screening, and Mineral Processing Equipment Market | 2026-2036
Crushing, Screening, and Mineral Processing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Crushing, Screening, and Mineral Processing Equipment Market Analysis
High-capacity mobile crushing configurations is rotating demand away from static plant investments in remote quarrying environments. Sandvik AB dominates European underground mining equipment through its automated drill-and-crush portfolios. Caterpillar Inc. leverages its dealer network density to control aftermarket parts revenue across North American construction corridors. Komatsu Ltd. anchors Asian mining demand with hybrid diesel-electric drive systems for open-pit operations.
Crushing, screening, and mineral processing equipment encompasses mechanical systems designed to reduce raw material dimensions to specified particle size distributions, typically between 150 mm feed and sub-10 mm product, using compressive, impact, or attrition forces followed by mechanical separation and density-based concentration. These systems serve as the primary material conditioning stage for downstream metal extraction, aggregate grading, and construction material preparation. Crushers and screens together command the largest product revenue pool, though automation technology delivers the fastest expansion as operators deploy remote monitoring and autonomous haulage integration to compress operating cost structures. Mobile equipment leads capital deployment in quarrying applications where deposit mobility and short mine life favor transportable circuits over fixed infrastructure.
EPA particulate standards in the United States and REACH material compliance requirements in Europe are forcing manufacturers to redesign wear components with reduced toxic alloy content and improved dust containment architectures. Australia's state-level environmental protection agencies impose progressive rehabilitation bonds that accelerate demand for modular, relocatable processing plants minimizing ground disturbance footprints. Stakeholders must weigh capex flexibility against automation integration depth as regulatory thresholds tighten and labor availability constrains remote site operations.
Market Dynamics
Mobile crushing configurations are rotating capital deployment away from static infrastructure as quarry operators prioritize circuit relocation flexibility over fixed-plant economies of scale.
Growth Catalysts
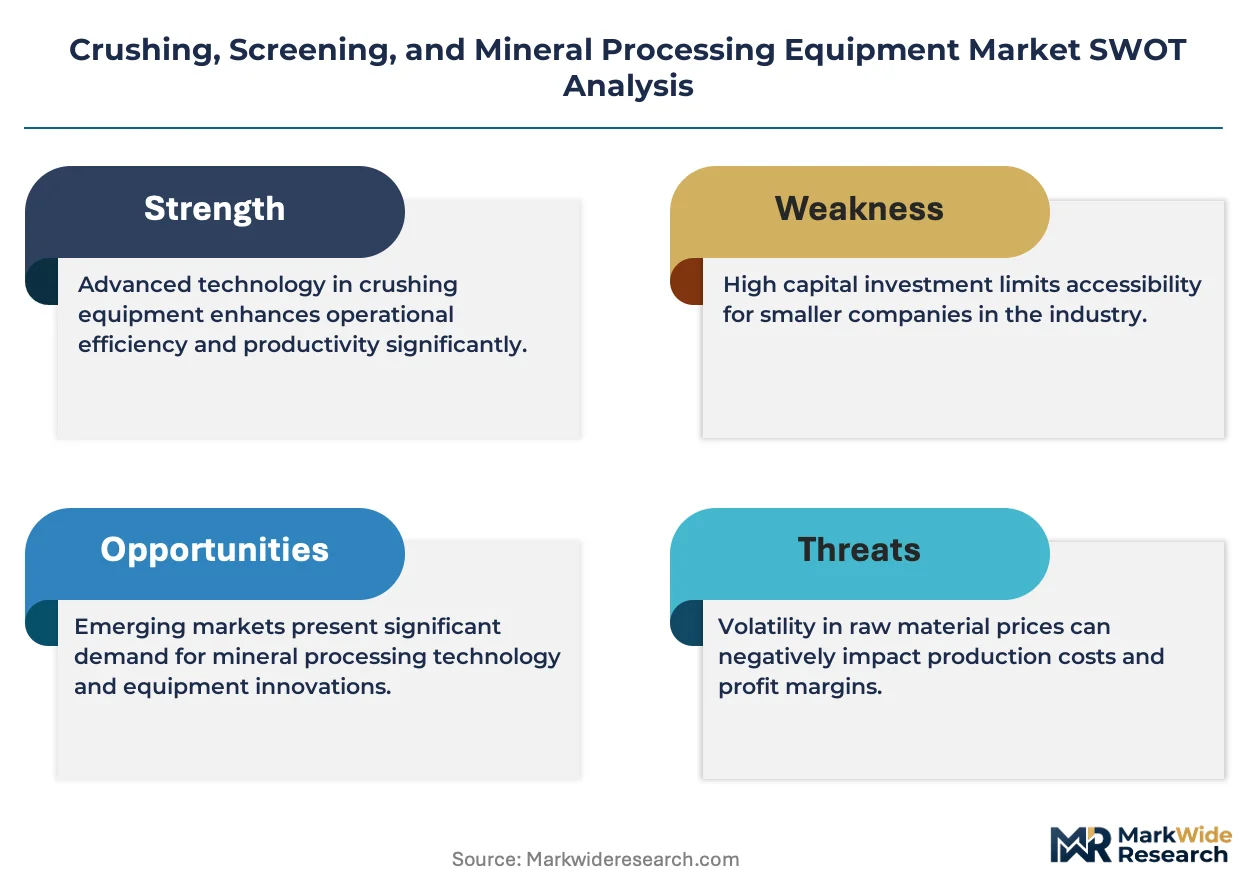
- Australia's progressive rehabilitation bonds:State environmental protection agencies impose financial guarantees that accelerate modular processing plant procurement to minimize ground disturbance footprints and accelerate site closure timelines.
- Iron ore belt automation:Brazil's Carajás and Quadrilátero Ferrífero districts drive automated screening circuit retrofits as Vale and junior miners compress operating cost structures through remote monitoring integration.
- Hybrid diesel-electric drive systems:Open-pit operations across Asian mining corridors adopt electrified haulage and crushing trains to reduce fuel consumption volatility and particulate emissions compliance costs.
Market Restraints
- High-alloy wear component costs:Manganese steel and chromium carbide overlay plate prices fluctuate with ferroalloy feedstock volatility, compressing margin structures for original equipment manufacturers.
- Supply concentration in Nordic engineering:Underground crushing and automated drill technologies concentrate among a narrow supplier base in Sweden and Finland, creating procurement bottlenecks for non-European mine developers.
- EPA particulate containment mandates:United States dust suppression architectures require redesigned hooding and negative-pressure enclosures that extend engineering lead times and inflate capex thresholds for greenfield projects.
Strategic Opportunities
- Underpenetrated African copper-cobalt belt:Democratic Republic of Congo and Zambian operations lag in automation penetration, creating first-mover advantage for remote monitoring and autonomous haulage integration vendors.
- Construction aggregates urbanization:Metropolitan quarrying near São Paulo, Mexico City, and Jakarta favors mobile circuit configurations that eliminate fixed infrastructure write-downs against shorter reserve lives.
- EU Green Deal embodied carbon tracking:REACH compliance extensions into Scope 3 emissions accounting creates preference for refurbished and remanufactured crushing components with documented carbon footprints.
Industry Challenges
- Automation-technician scarcity:Remote site operations struggle to recruit PLC programmers and predictive maintenance specialists capable of integrating autonomous haulage with crushing circuit control systems.
- Legacy analog integration complexity:Brownfield mineral processing plants with 1980s-era DCS architectures require expensive middleware layers to connect new sensor networks and cloud-based analytics platforms.
- Multi-jurisdictional certification timelines:Equipment destined for cross-border mining projects must satisfy divergent mechanical safety standards across Australian state regulators, Canadian provincial authorities, and Chilean mining ministry requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crushing, Screening, and Mineral Processing Equipment Market |
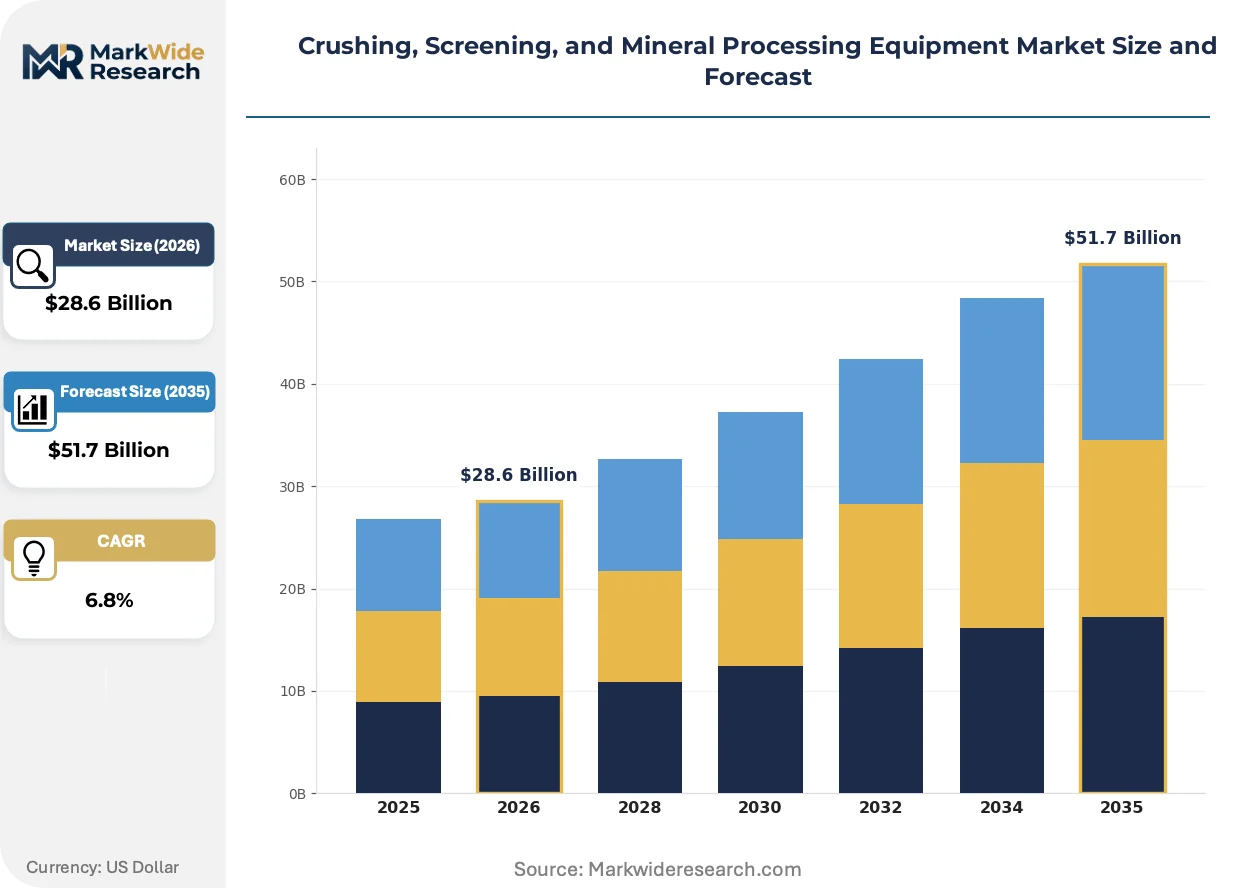
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crushers, Screens, Feeders, Washers Application: Quarrying, Mining, Construction, Recycling End User: Mining Companies, Construction Firms, Contractors, Aggregate Producers Technology: Mobile Equipment, Fixed Equipment, Hybrid Solutions, Automation |
| Companies Covered | Caterpillar Inc., Komatsu Ltd., Terex Corporation, FLSmidth & Co. A/S, Weir Group PLC, Sandvik AB, Astec Industries Inc., McCloskey International, Metso Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crushing, Screening, and Mineral Processing Equipment Market Emerging Trajectories
Digital thread technologies and electrified drive architectures are compressing the traditional separation between mechanical processing equipment and autonomous material handling systems.
Sensor-embedded jaw and cone crusher liners is miniaturizing condition monitoring from external accelerometer arrays to embedded piezoelectric strain gauges that transmit real-time wear profiles. Underground hard-rock operators in Canadian Shield operations deploy these smart liners to eliminate unplanned shutdowns from undetected fatigue cracking. The technology is miniaturizing maintenance crew deployment requirements and extending planned outage intervals from quarterly to semi-annual cycles.
REACH material compliance extensions are forcing redesign of high-chromium grinding media and screen deck alloys to eliminate hexavalent chromium exposure risks during fabrication and end-of-life recycling. European aggregate producers now specify low-toxicity manganese alternatives that sacrifice some abrasion resistance for regulatory certainty. Crushing circuit OEMs serving EU markets absorb additional metallurgical testing costs to maintain CE marking validity under evolving ECHA substance restrictions.
After-sales service unbundling is fragmenting the traditional bundled maintenance contract model as large mining houses insource routine wear part replacement and outsource only specialized rebuilds. Australian iron ore operators now procure direct from foundries for standard manganese components while retaining OEM relationships for crusher frame remanufacturing. This bifurcation is most visible in Western Australia's Pilbara region where Rio Tinto and BHP have established captive parts warehouses independent of dealer networks.
Crushing, Screening, and Mineral Processing Equipment Market Segmentation
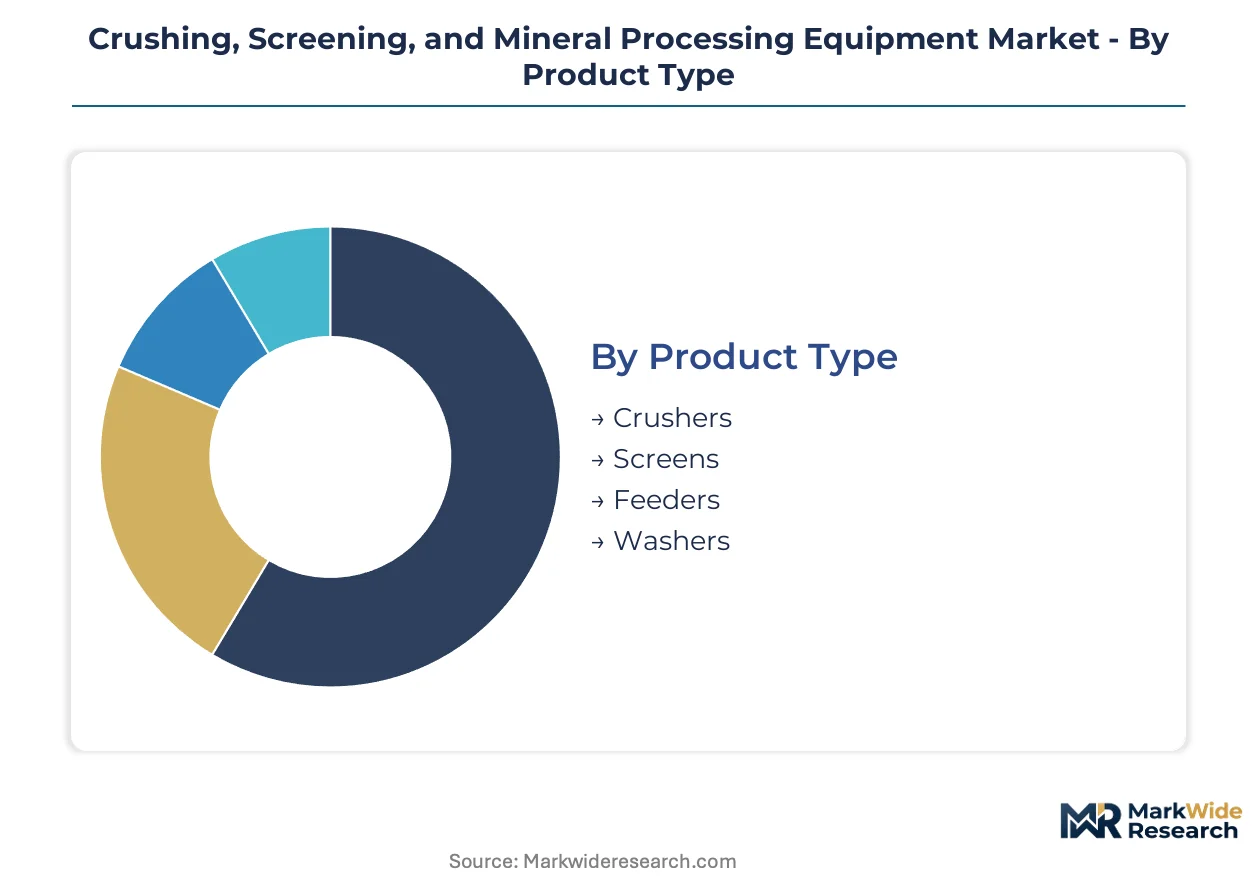
Equipment specification varies sharply across ore hardness, deposit mobility, and regulatory jurisdiction. Segmentation reveals where capital deployment favors transportable circuits over fixed infrastructure, and which technology tiers command premium pricing.
Product Type:
Domestic production concentrates crushers and screens in Nordic engineering clusters, while feeders and washers see heavier Asian manufacturing integration for export markets.
- Crushers:Jaw, cone, and gyratory configurations reduce feed material from 1500 mm to sub-100 mm using compressive and impact forces. Australian iron ore operators in the Pilbara region prioritize high-throughput gyratory installations to match autonomous haulage fleet capacity, though manganese steel wear component costs fluctuate with ferroalloy feedstock volatility.
- Screens:Vibrating and banana screen architectures mechanically separate crushed material into specified particle size distributions. Brazilian iron ore belt operations at Vale's Carajás complex drive automated screening circuit retrofits that integrate remote monitoring to compress operating cost structures.
- Feeders:Apron and vibrating feeder systems regulate material flow from extraction faces to primary crushing stations.
- Washers:Log and screw configurations remove fines and clay contamination from aggregate feedstocks prior to grading.
Crushers hold the largest share; momentum sits with screens as automation penetration accelerates.
Application:
Cost tier stratification separates high-capex mining installations from lower-threshold quarrying and recycling deployments.
- Quarrying:Mobile crushing configurations dominate metropolitan extraction sites near São Paulo, Mexico City, and Jakarta where shorter reserve lives eliminate fixed infrastructure write-downs. Circuit relocation flexibility commands premium pricing over static plant economies of scale.
- Mining:Open-pit and underground hard-rock operations deploy hybrid diesel-electric drive systems to reduce fuel consumption volatility and EPA particulate compliance costs. Canadian Shield underground operators embed sensor-equipped liners to extend planned outage intervals.
- Construction:Infrastructure material preparation favors transportable equipment for highway and dam project mobility.
- Recycling:Construction and demolition waste processing demands robust wear-resistant configurations for reinforced concrete and asphalt fragmentation.
Mining commands the dominant revenue pool; quarrying gains share fastest as urbanization compresses deposit access timelines.
End User:
Customer type determines procurement sophistication, with mining houses insourcing routine maintenance while contractors rely on dealer networks.
- Mining Companies:Large integrated operators in Western Australia's Pilbara region have established captive parts warehouses independent of dealer networks, procuring direct from foundries for standard manganese components while retaining OEM relationships for crusher frame remanufacturing.
- Construction Firms:Project-based aggregate demand favors rental and lease structures over capital ownership for temporary infrastructure works.
- Contractors:Mobile equipment leasing dominates short-term quarrying contracts where deposit mobility prevents fixed-plant investment recovery.
- Aggregate Producers:Long-term reserve holders balance static plant efficiency against modular relocation options under Australia's progressive rehabilitation bond requirements.
Mining companies hold the largest share; aggregate producers climb fastest as environmental bond structures accelerate modular procurement.
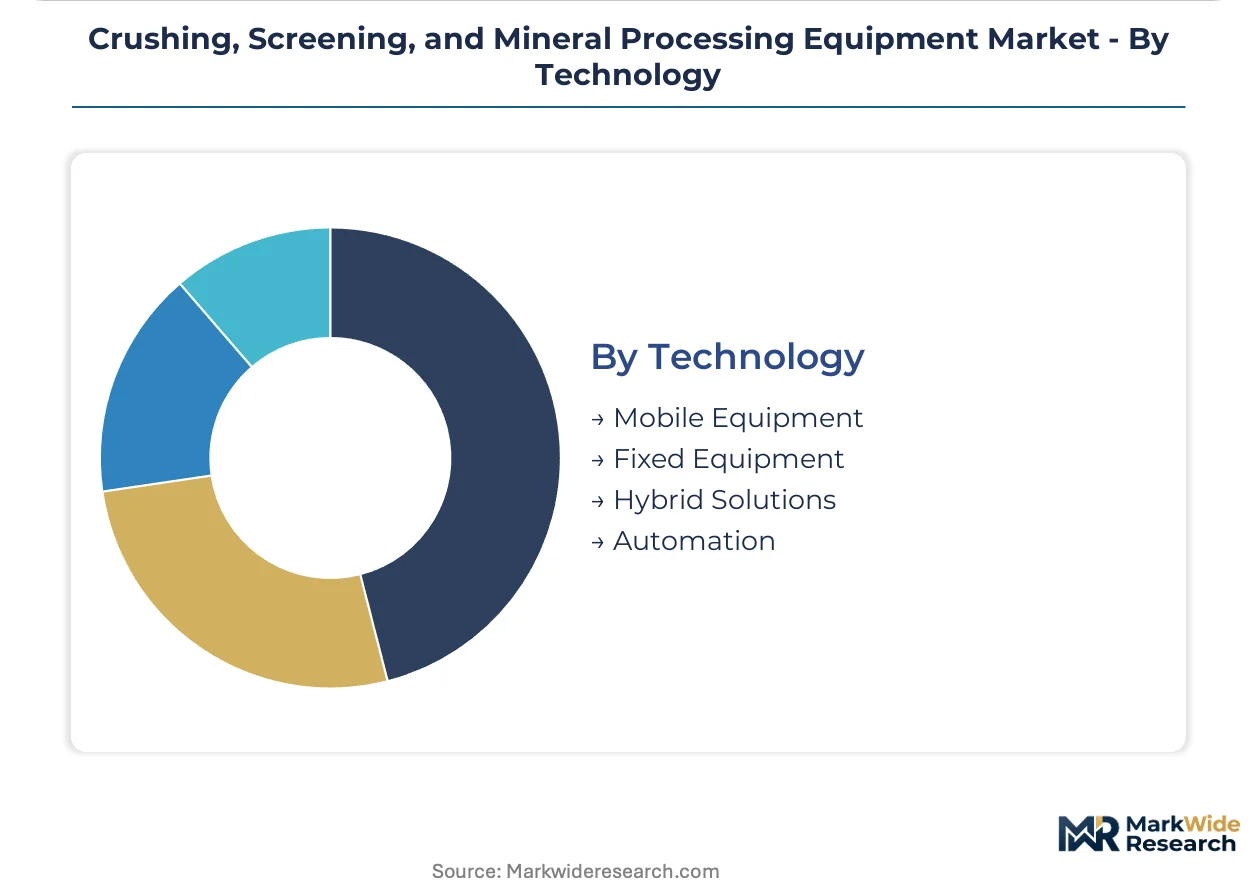
Technology:
Volume deployment still favors fixed equipment, though margin concentration sits with automation and hybrid architectures.
- Mobile Equipment:Transportable crushing and screening circuits mounted on skid or crawler configurations serve quarrying applications where deposit mobility and short mine life favor relocation flexibility. Australian state environmental protection agencies accelerate demand through progressive rehabilitation bonds that minimize ground disturbance footprints.
- Automation:Remote monitoring, autonomous haulage integration, and PLC-controlled circuit optimization deliver the steepest expansion trajectory as operators compress labor requirements and unplanned shutdown intervals.
- Fixed Equipment:Static plant installations dominate high-volume mining operations with decades-long reserve horizons.
- Hybrid Solutions:Diesel-electric drive trains reduce fuel consumption volatility in Asian open-pit corridors.
Fixed equipment holds the largest share; automation gains share fastest as technician scarcity intensifies remote site operational pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances tilt toward Nordic engineering clusters supplying automated underground systems while Asian fabrication centers dominate mobile equipment for quarrying markets. Equipment flows concentrate from Sweden and Finland toward Australian and Canadian mining corridors, with Chinese and South Korean manufacturers capturing modular plant demand across Southeast Asian construction corridors.
Australia
Western Australia's Pilbara region drives autonomous haulage integration with crushing circuits as Rio Tinto and BHP expand fleet renewals. State environmental protection agencies impose progressive rehabilitation bonds that accelerate modular processing plant procurement. Queensland's Bowen Basin coal operations favor hybrid diesel-electric drive systems to reduce particulate emissions compliance costs.
Brazil
Vale's Carajás complex and junior miners throughout the Quadrilátero Ferrífero retrofit processing lines with automated screening circuits. ANVISA-aligned environmental frameworks push dust containment architectures in greenfield projects. São Paulo metropolitan quarrying favors mobile crushing configurations that eliminate fixed infrastructure write-downs against shorter reserve lives.
China
MIIT carbon reduction mandates accelerate electrified drive train adoption across Inner Mongolian and Shanxi coal processing corridors. Domestic manufacturers capture belt conveyor and feeder system demand for Belt and Road mining projects. Yangtze River Delta fabrication clusters export mobile screening units to Southeast Asian aggregate markets.
United States
EPA particulate standards force redesigned hooding and negative-pressure enclosures that extend engineering lead times for Appalachian and Mountain West mining projects. Texas and Arizona aggregate producers prioritize mobile equipment leasing structures over capital ownership. Dealer network density controls aftermarket parts revenue across North American construction corridors.
Germany
REACH material compliance requirements drive redesign of high-chromium grinding media to eliminate hexavalent chromium exposure risks. Bavarian and North Rhine-Westphalian engineering clusters supply sensor-embedded crusher liners to Canadian Shield underground operations. EU Green Deal embodied carbon tracking creates preference for refurbished components with documented footprints.
Crushing, Screening, and Mineral Processing Equipment Market Vendor Landscape
Concentration sits with diversified mining equipment conglomerates controlling integrated crushing-screening-hauling portfolios alongside specialized engineering houses dominating underground automation technologies. The vendor base spans three tiers: full-line mining systems suppliers, aggregate-focused mobile equipment fabricators, and component specialists in wear materials and control systems. Competitive dynamics center on vertical integration into aftermarket services and geographic expansion through distributor partnerships rather than direct sales force deployment.
Among Nordic engineering specialists, Sandvik AB and FLSmidth & Co. A/S exemplify the automation-intensive tier serving deep underground hard-rock operations. Caterpillar Inc. and Komatsu Ltd. occupy positions within the integrated systems tier, leveraging global dealer networks to capture recurring parts revenue. Terex Corporation represents the mobile equipment specialization vector, with portfolio concentration in transportable crushing and screening circuits for quarrying applications. These archetypes reflect divergent capital intensity thresholds and customer relationship models across mining house procurement functions.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| Komatsu Ltd. |
| Terex Corporation |
| FLSmidth & Co. A/S |
| Weir Group PLC |
| Sandvik AB |
| Astec Industries Inc. |
| McCloskey International |
| Metso Corporation |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between Australian iron ore operators and Nordic engineering houses lock in supply access for automated crushing systems while capping price volatility through indexed ferroalloy adjustments. These contracts bundle crusher frame remanufacturing with sensor-embedded liner procurement, creating visibility across multi-year fleet renewal cycles.
Pricing Analysis
Industrial OEM buyers anchor contract-based pricing structures that stratify across premium automation tiers, standard mobile configurations, and economy fixed-plant alternatives. Price differentiation hinges on CE marking compliance depth and aftermarket service bundling intensity. Cost compression in economy tiers is intensifying because captive parts warehousing by Pilbara mining houses bypasses dealer markups. Construction contractors exhibit highest price sensitivity due to project-based procurement, while integrated mining companies prioritize total cost of ownership over unit capex.
Supply Chain Analysis
Extended engineering lead times for EPA-compliant dust containment systems have stretched order-to-delivery intervals for greenfield projects in the Mountain West. Manufacturing gravity centers on Sweden and Finland for underground automation, China for mobile screening units, and Germany for sensor-embedded liner technologies. Ferroalloy feedstock volatility draws from manganese ore concentration in South Africa and chromium supply from Kazakhstan. Single-source vulnerability concentrates in Nordic engineering clusters serving deep hard-rock operations. Distribution runs through OEM dealer networks in North America and direct procurement channels in Australian mining corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Autonomous haulage-to-crushing circuit interoperability is emerging as the platform-economics inflection, with API-standardized control architectures enabling vendor-agnostic equipment mixing that reshapes procurement lock-in dynamics.
For Market Incumbents: Compound aftermarket revenue streams by embedding predictive maintenance software into liner and wear component sales, defending against direct foundry procurement by Australian mining houses. Deepen backward integration into manganese steel recycling to offset ferroalloy price volatility. Prioritize certification investment in EU Green Deal embodied carbon tracking to maintain premium positioning against remanufactured component competitors. For New Entrants and Emerging Players: Differentiate on PLC-native automation stacks that bypass legacy DCS middleware requirements in brownfield mineral processing plants. Target the underpenetrated African copper-cobalt belt with remote monitoring solutions purpose-built for unreliable grid infrastructure. Pursue joint venture structures with local contractors in São Paulo metropolitan quarrying to overcome capital barriers against mobile equipment incumbents. For Investors and Strategic Acquirers: Component specialists with captive metallurgical testing capabilities and ECHA pre-registration dossiers represent the most defensible acquisition profile through tightening REACH enforcement. Long-term viability hinges on automation penetration depth rather than equipment shipment volumes. Watch for inflection signals in technician training pipeline expansion by Australian state mining regulators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ferroalloy Recycling | Captive manganese recovery reduces exposure to South African supply disruptions and ESG scrutiny. |
| Sensor-Embedded Liner Technology Launch | Piezoelectric strain gauges extend planned outage intervals for Canadian Shield underground operators. |
| Joint Venture with Brazilian Aggregate Contractors | Local partnership structures unlock São Paulo metropolitan quarrying without direct capital deployment. |
| EU Green Deal Carbon Footprint Certification | Documented remanufactured component footprints create preference against virgin steel alternatives. |
| Remote Monitoring Platform Integration | API-standardized architectures enable interoperability with Komatsu and Caterpillar autonomous haulage fleets. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, customs trade databases, and mining ministry equipment registration records. Interviews with maintenance directors at Pilbara operations, plant engineers in the Quadrilátero Ferrífero, OEM procurement teams in Germany, and aftermarket service heads in North America inform demand-side validation. Bottom-up equipment shipment tracking triangulates against top-down capex disclosure analysis across the analysis window.
Segmentation dimensions modeled include equipment mobility configuration, automation technology tier, ore hardness application, and regional regulatory cluster. CAGRs derive from regression against historical fleet renewal cycles and projected emissions compliance investment schedules. Ferroalloy price indices and autonomous haulage adoption curves feed industry-specific forecast inputs throughout the projection horizon.
The analysis sits within stated boundaries; outcomes outside sustained mining capex commitment or accelerated REACH substance restriction timelines would require recalibration. Forecasts reflect assumptions regarding technician availability for automation deployment and progressive rehabilitation bond enforcement consistency. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment and Machinery
Woodworking Machines Market
Construction Equipment and Machinery
Sheet Metal Fabrication Equipment Market
Construction Equipment and Machinery
ASEAN Construction Machinery Market
Construction Equipment and Machinery
Universal Milling Machine Market
Construction Equipment and Machinery
Canada Metal Fabrication Equipment Market
Construction Equipment and Machinery
Benelux Metal Fabrication Equipment Market
Construction Equipment and Machinery
Global Construction Machinery Market
Construction Equipment and Machinery
Global Laundry Folding Machine Market
Construction Equipment and Machinery
GCC Construction Machinery Rental Market
Construction Equipment and Machinery
Steel Fabrication Market
Construction Equipment and Machinery
India Lathe Machines Market
Construction Equipment and Machinery
Global Conveyor Maintenance Market
Construction Equipment and Machinery
Global Metal Embossing Machine Market
Construction Equipment and Machinery
Robotic Mill Liner Market
Construction Equipment and Machinery
Lattice Cranes Market
Construction Equipment and Machinery
Double Decker Roll Forming Machine Market