
 Compact Power Equipment Rental Market | 2026-2036
Compact Power Equipment Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Compact Power Equipment Rental Market Outlook
Buyer consolidation among mid-sized construction contractors is restructuring how rental fleets negotiate volume commitments and service-level agreements. United Rentals, Inc. leverages its national branch network to sustain density advantages in urban construction corridors. Sunbelt Rentals anchors its position through specialized maintenance support capabilities that reduce customer downtime. Herc Rentals Inc. competes by controlling regional inventory pools that match localized project cycles.
Compact power equipment rental encompasses the temporary provision of mobile engine-driven machinery—typically rated below 50 horsepower for generators or under 10,000 pounds for earthmoving units—through contractual arrangements rather than asset purchase, with diesel-electric hybrid powertrains now penetrating the sub-75 kW generator class. The primary commercial purpose centers on converting fixed capital expenditures into operational costs while granting contractors access to emission-compliant, technologically current machinery without residual value risk. Generators occupy the largest margin pool within product type segments due to continuous uptime requirements across events and critical infrastructure maintenance. Short-term rental commands the fastest expansion within service type segments as project-based contractors resist long-term balance sheet commitments. Construction end users dominate volume absorption, though landscaping is gaining share as municipal green infrastructure budgets expand.
EPA Tier 4 Final and CARB standards in the United States compel rental providers to retire pre-2014 diesel inventories and absorb compliance premiums into rate structures. OSHA workplace safety mandates and ISO 8528 generator performance standards further shape equipment specification and operator training protocols. Stakeholders must monitor how electrification timelines intersect with rental fleet replacement cycles to avoid stranded diesel assets.
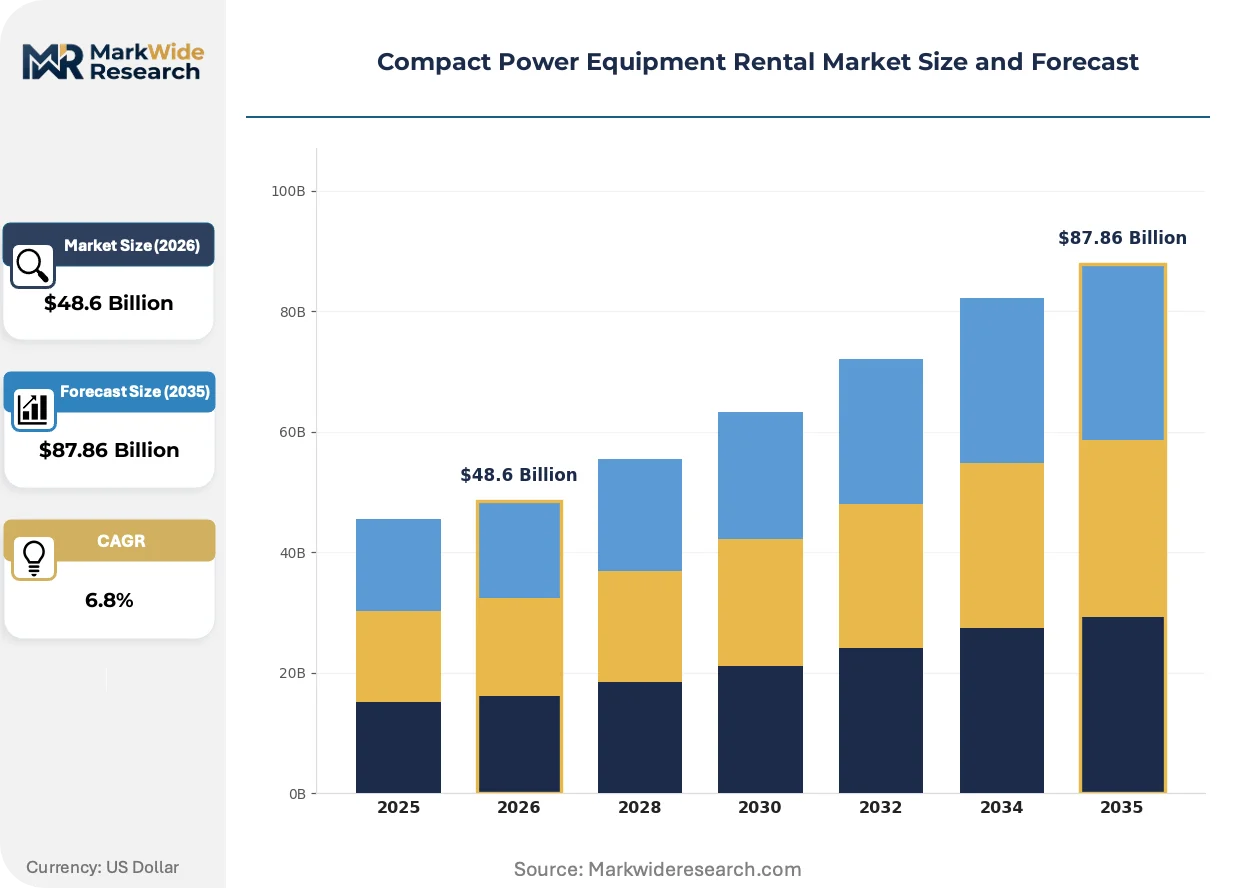
Market Dynamics
Construction contractors are consolidating equipment procurement through rental partnerships, converting fixed capital expenditures into operational costs while accessing EPA Tier 4 Final compliant machinery without residual value exposure.
Growth Catalysts
- EPA Tier 4 Final compliance:The United States emission standards accelerate fleet turnover toward cleaner-burning rental units as contractors retire pre-2014 diesel inventories.
- Petrochemical infrastructure:Gulf Coast metropolitan corridor projects drive sustained generator and earthmoving equipment utilization across Texas and Louisiana.
- Hybrid powertrains:Diesel-electric hybrid systems penetrating the sub-75 kW generator class expand addressable rental applications for critical infrastructure maintenance.
Market Restraints
- Diesel engine cost volatility:Tier 4 Final aftertreatment systems and DEF infrastructure requirements inflate unit procurement costs for rental providers.
- Inventory concentration risk:Regional pool imbalances strand underutilized assets when localized project cycles diverge from fleet positioning.
- Electrification timeline uncertainty:Battery-electric compact equipment range limitations constrain substitution for continuous-duty generator applications.
Strategic Opportunities
- Municipal green infrastructure:Landscaping segment share gains from expanding city budgets for urban canopy and stormwater management projects.
- Short-term rental expansion:Project-based contractors resisting long-term balance sheet commitments favor flexible duration structures over multi-year leases.
- OSHA-ISO convergence:Workplace safety mandates and ISO 8528 generator performance standards create certified equipment differentiation premiums.
Industry Challenges
- Tier 4 technician scarcity:Diesel aftertreatment diagnostics and SCR system maintenance require specialized training pipelines that rental providers must build internally.
- Fleet reconfiguration capex:Simultaneous compliance-driven diesel turnover and electrification pilot programs strain capital allocation across uncertain technology transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compact Power Equipment Rental Market |
| Market Size in 2026 | $48.6 Billion |
| Market Size in 2035 | $87.86 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Generators, Excavators, Loaders, Compressors End User: Construction, Landscaping, Events, Maintenance Service Type: Short-term Rental, Long-term Rental, Lease, Maintenance Support Distribution Channel: Online Platforms, Retail Stores, Direct Sales, Dealers |
| Companies Covered | United Rentals, Inc., Sunbelt Rentals, Herc Rentals Inc., Aggreko Plc, Loxam Group, Boels Rental, Atlas Copco AB, Caterpillar Inc., H&E Equipment Services, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compact Power Equipment Rental Market Strategic Shifts
Telematics integration and predictive maintenance systems are compressing equipment downtime windows, while regulatory emission deadlines force synchronized fleet refresh cycles across major rental networks.
Hybrid diesel-electric powertrains are consolidating sub-75 kW generator market share by delivering load-following efficiency gains. Data center contractors and event staging companies are adopting these units for fuel consumption reduction. The technology is consolidating rental provider margins by extending service intervals and reducing DEF consumption rates.
EPA Tier 4 Final and CARB standards in the United States compel rental providers to absorb compliance premiums into rate structures. Pre-2014 diesel inventories face accelerated retirement timelines. Generator rental segments bear the heaviest specification burden due to continuous uptime requirements across critical infrastructure applications.
Short-term rental contracting is displacing multi-year lease commitments among mid-sized construction contractors. Equipment-as-operational-expense models replace balance-sheet ownership. This behavioral shift concentrates most visibly in Gulf Coast metropolitan corridors where project-based petrochemical and infrastructure work dominates equipment utilization patterns.
Compact Power Equipment Rental Market Segmentation
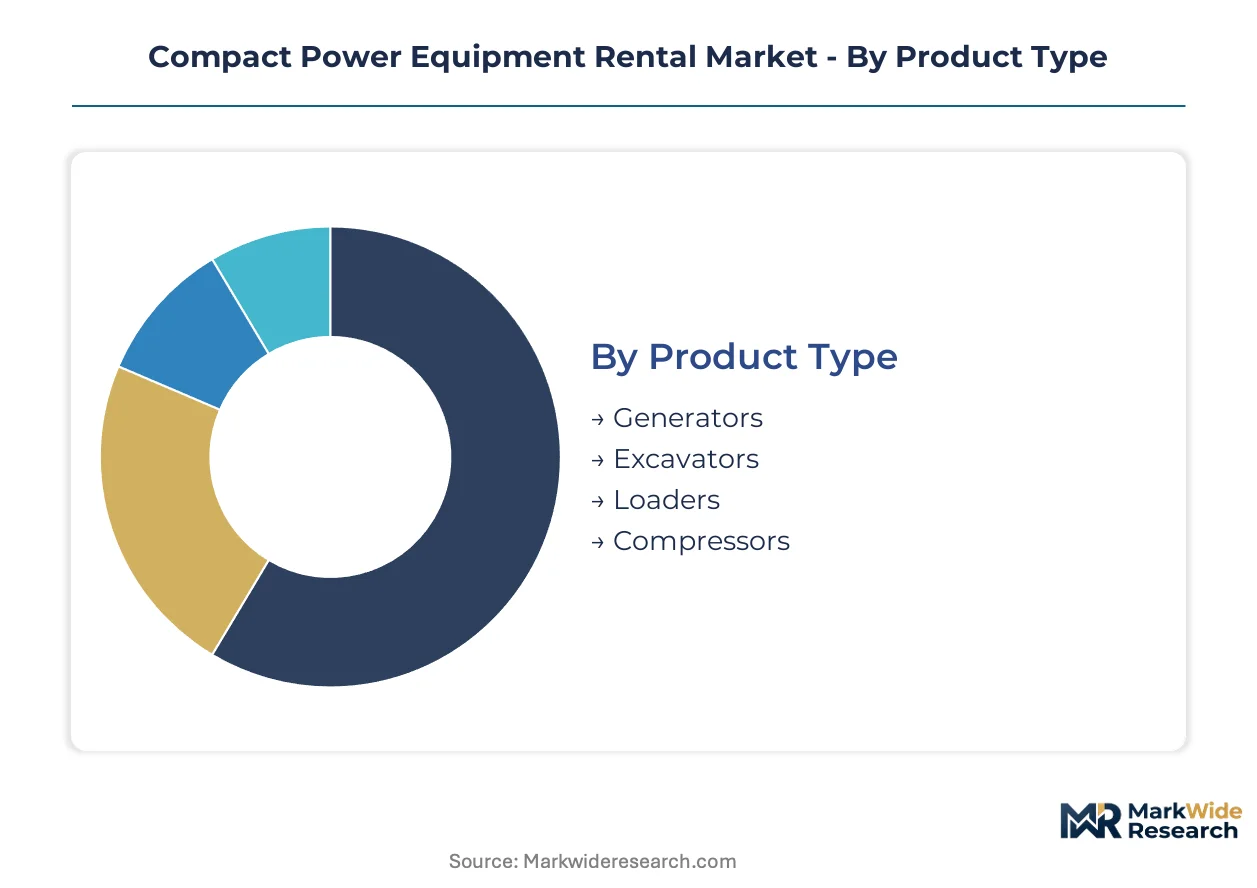
Segmentation in compact power equipment rental reveals how procurement patterns fragment across project duration, asset type, and customer sophistication. Rental providers configure fleet composition and pricing architecture around these divides to match utilization risk with revenue stability.
Product Type:
Generators function as standalone power infrastructure deployed independently of other equipment, while excavators, loaders, and compressors typically embed within coordinated construction systems requiring synchronized availability.
- Generators:Diesel-electric hybrid units rated below 75 kW dominate this segment through load-following efficiency that reduces DEF consumption. Demand concentrates in Gulf Coast petrochemical corridors where continuous uptime requirements across Texas and Louisiana refineries sustain premium rate structures. EPA Tier 4 Final compliance costs embed directly into rental pricing due to aftertreatment system maintenance complexity.
- Excavators:Compact units under 10,000 pounds serve trenching and foundation work with hydraulic systems optimized for fuel efficiency. Municipal green infrastructure budgets in urban canopy and stormwater projects absorb volume placements, though electrification timelines constrain substitution for continuous-duty applications requiring range certainty.
- Loaders:Skid-steer and compact track configurations handle material movement across grading and site preparation phases.
- Compressors:Portable air supply units support pneumatic tooling in remote or grid-constrained work environments.
Volume placements concentrate in generators; the faster expansion belongs to excavators.
End User:
Customer type determines contract structure flexibility, with project-based contractors demanding variable duration terms and institutional clients seeking predictable operational expenditure conversion.
- Construction:Mid-sized contractors consolidating procurement through rental partnerships convert fixed capital expenditures into operational costs while accessing EPA Tier 4 Final compliant machinery without residual value exposure. Gulf Coast metropolitan corridors anchor volume absorption where petrochemical and infrastructure project cycles drive sustained utilization.
- Landscaping:Municipal green infrastructure budgets expand urban canopy and stormwater management deployments, with seasonal demand patterns requiring flexible fleet positioning. Equipment specification emphasizes low-emission compliance for park district and municipal contract eligibility.
- Events:Temporary power and climate control for outdoor staging creates spike demand with premium rate tolerance.
- Maintenance:Critical infrastructure upkeep contracts require certified ISO 8528 generator performance standards with documented uptime guarantees.
Construction commands the dominant placement volume; landscaping gains share fastest from municipal budget expansion.
Service Type:
Duration commitment structures align with balance sheet strategy, separating customers seeking asset-light operations from those optimizing total cost of ownership over extended horizons.
- Short-term Rental:Project-based contractors resisting long-term balance sheet commitments favor flexible duration structures. This segment climbs the fastest as behavioral shifts concentrate visibly in Gulf Coast corridors where petrochemical work dominates utilization patterns and equipment-as-operational-expense models displace ownership.
- Long-term Rental:Multi-year arrangements suit customers with predictable project pipelines seeking rate stability over flexibility.
- Lease:Capital lease structures appeal to contractors with tax-positioning requirements or residual value capture objectives.
- Maintenance Support:Specialized service capabilities reduce customer downtime through predictive systems and Tier 4 technician networks.
Short-term rental absorbs the heaviest volume concentration; maintenance support expands most quickly as uptime guarantees differentiate provider positioning.
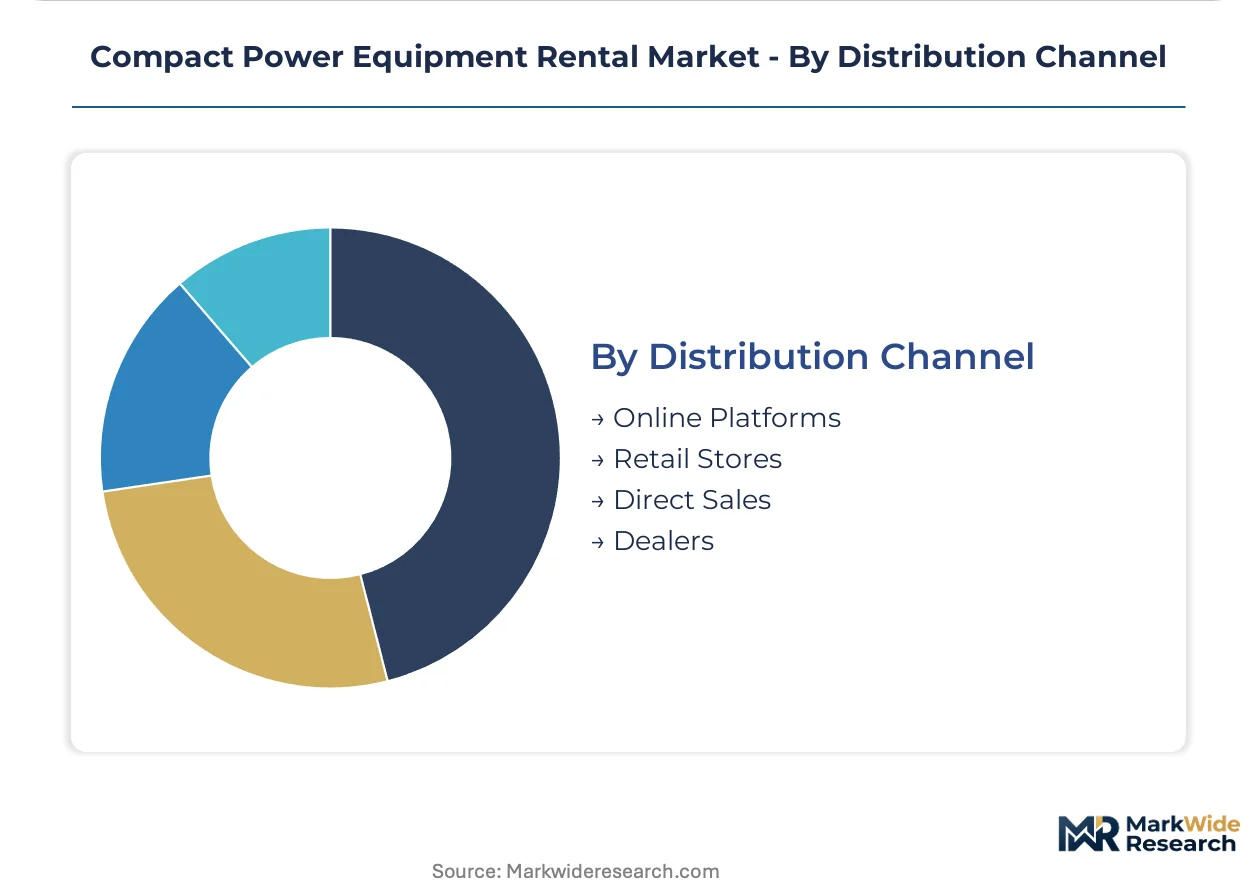
Distribution Channel:
Channel selection reflects customer digital maturity and the complexity of equipment specification requiring physical inspection or immediate availability assurance.
- Online Platforms:Digital booking interfaces streamline availability confirmation and rate comparison for standardized equipment categories. Adoption accelerates among event staging and maintenance contractors with predictable specification requirements and established brand relationships.
- Retail Stores:Branch networks provide same-day availability verification and immediate operator training for time-sensitive construction deployments.
- Direct Sales:National account teams negotiate volume commitments and service-level agreements for consolidated contractor procurement.
- Dealers:Regional inventory pools match localized project cycles through independent operators with embedded customer relationships.
Direct sales channels capture the largest committed volume; online platforms scale most rapidly from contractor digital procurement adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical feedstock corridors along the Gulf Coast anchor North American equipment rental density, with diesel generator deployment tracking refinery maintenance cycles and pipeline construction timelines across Texas and Louisiana.
United States
Gulf Coast metropolitan corridors concentrate generator and earthmoving utilization where Texas and Louisiana petrochemical projects sustain premium rental rates. EPA Tier 4 Final standards accelerate pre-2014 diesel fleet retirement, forcing rental providers to absorb aftertreatment compliance costs into rate structures. Houston and Baton Rouge anchor the heaviest equipment density, with continuous uptime requirements across refinery turnarounds driving sustained demand.
Germany
Industrial manufacturing maintenance and renewable energy construction absorb compact power equipment volumes across Baden-Württemberg and North Rhine-Westphalia. EU Green Deal emission targets and national diesel restrictions in urban zones push rental fleets toward hybrid generator adoption. The Rhine-Ruhr industrial cluster sustains consistent utilization for critical infrastructure backup power and factory maintenance windows.
China
Infrastructure stimulus programs and data center construction drive generator rental absorption across the Yangtze River Delta and Pearl River Delta regions. MIIT emission standards and provincial diesel restrictions in Beijing-Tianjin-Hebei accelerate fleet turnover toward cleaner-burning units. Shanghai and Shenzhen anchor equipment concentration where continuous power reliability requirements dominate contractor procurement decisions.
India
Metro rail construction and commercial real estate expansion concentrate equipment demand in Maharashtra and Karnataka. CEA grid reliability mandates and state-level construction safety regulations shape generator specification requirements for critical infrastructure projects. Mumbai and Bengaluru sustain rental utilization through data center commissioning and urban transit tunneling work.
United Arab Emirates
Expo legacy infrastructure and desalination plant construction drive sustained equipment utilization across Dubai and Abu Dhabi. MOHAP workplace safety protocols and federal emission standards for construction machinery influence rental fleet specification. The Dubai South logistics corridor and Khalifa Industrial Zone anchor generator deployment for continuous industrial process power.
Compact Power Equipment Rental Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue specialized maintenance capabilities and regional inventory pooling. The vendor base concentrates around three operational models: national branch networks delivering density advantages in urban corridors, specialized service providers reducing customer downtime through predictive systems, and regional pool operators matching inventory to localized project cycles. Consolidation pressures intensify as mid-sized contractors demand volume commitments and integrated service-level agreements. Competitive positioning hinges on fleet emission compliance velocity and technician training pipeline depth.
Within the national network tier, United Rentals, Inc. and Sunbelt Rentals exemplify scale-driven positioning through branch density and maintenance specialization respectively. Herc Rentals Inc. occupies a regional pool archetype, matching inventory positioning to localized construction cycles. Aggreko Plc represents the critical infrastructure specialist segment, with project-based power solutions for continuous uptime requirements. These three anchors demonstrate how competitive differentiation fragments across geographic coverage, service capability, and sector focus rather than converging on uniform scale advantages.
| Leading Market Players |
|---|
| United Rentals, Inc. |
| Sunbelt Rentals |
| Herc Rentals Inc. |
| Aggreko Plc |
| Loxam Group |
| Boels Rental |
| Atlas Copco AB |
| Caterpillar Inc. |
| H&E Equipment Services, Inc. |
| Others |
Value Chain & Pricing Dynamics
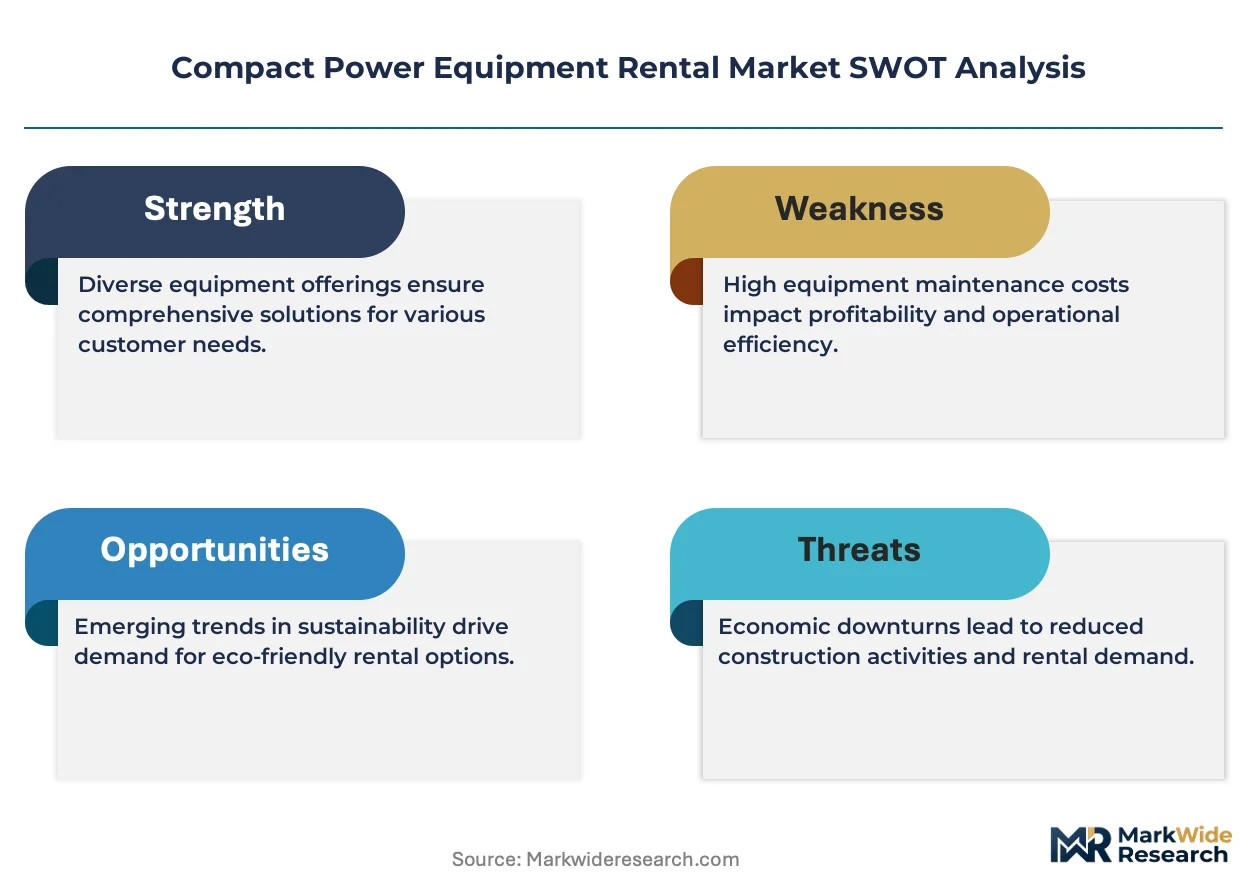
Mid-sized contractor consolidation into rental partnerships forces fleet operators to absorb EPA Tier 4 Final aftertreatment costs while maintaining rate competitiveness, compressing margins and accelerating procurement centralization toward national providers with volume leverage.
Pricing Analysis
Maintenance bundling separates premium rental tiers from unbundled economy offerings, with Tier 4 technician networks and predictive uptime guarantees commanding rate premiums. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 8528 certification status and DEF consumption efficiency. Cost compression in the standard tier is intensifying as regional pool operators undercut national networks on base rates. Project-based contractors in Gulf Coast corridors show highest price sensitivity, while data center maintenance clients tolerate premium pricing for documented uptime guarantees.
Supply Chain Analysis
Diesel-electric hybrid powertrain supply rests on German engine control specialists, Japanese inverter manufacturers, and Chinese battery pack assemblers. Rental fleets draw from Tier 4 Final-certified diesel engine producers in the United States, compact hydraulic system specialists in Italy, and telematics hardware fabricators in Taiwan. Single-source vulnerability in SCR aftertreatment components creates fleet reconfiguration risk when supplier allocations tighten. Distribution runs through national branch networks for immediate availability, supplemented by regional pool operators for localized cycle matching.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA Tier 4 Final compliance functions as a cost-of-compliance moat, with aftertreatment system maintenance complexity and technician training pipelines creating barriers that favor incumbent national networks over undercapitalized regional entrants.
For Market Incumbents: Anchor fleet positioning through predictive maintenance capability investments that reduce customer downtime and justify rate premiums. Absorb regional pool operators in Texas and Louisiana corridors to consolidate Gulf Coast density. Electrification pilot programs threaten stranded diesel assets; accelerate hybrid powertrain penetration in sub-75 kW generator classes to defend positioning. For New Entrants and Emerging Players: Telematics-first service models offer entry wedge into maintenance support segments where uptime guarantees differentiate provider positioning. Municipal green infrastructure landscaping contracts show lowest incumbent saturation and seasonal fleet flexibility requirements. Target direct sales channel partnerships with mid-sized contractors seeking consolidated procurement alternatives to national network rates. For Investors and Strategic Acquirers: The window for entry favors regional pool operators with embedded Gulf Coast petrochemical relationships and undervalued Tier 4 technician training infrastructure. Long-term viability hinges on fleet emission compliance velocity through the diesel-to-hybrid transition. Watch hybrid generator adoption rates in data center maintenance contracts as inflection indicator for technology substitution timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Electrification Pilot Programs | Hybrid powertrain deployment in sub-75 kW generators reduces DEF consumption and extends service intervals for data center contractors. |
| Predictive Maintenance Platform Integration | Telematics systems compress equipment downtime windows and differentiate premium rental tiers through ISO 8528-certified uptime guarantees. |
| Regional Pool Operator Acquisition | Consolidation of Texas and Louisiana inventory pools matches fleet positioning to localized petrochemical project cycles. |
| Tier 4 Technician Training Pipeline | Internal SCR system diagnostics capability addresses scarcity constraints and reduces third-party maintenance dependency. |
| Municipal Green Infrastructure Partnership | Landscaping segment expansion captures urban canopy and stormwater management volume from expanding city budgets. |
Study Parameters
Document review covered SEC 10-K filings from publicly traded rental operators, EPA enforcement action records, and customs trade data on diesel engine imports, complemented by interviews with fleet procurement directors, maintenance supervisors at petrochemical facilities, branch operations managers, and telematics platform engineers. Secondary validation drew from OSHA incident databases, ISO certification registries, and state-level construction expenditure reports. Bottom-up equipment utilization estimates triangulated against top-down regional construction spending projections.
Historical utilization patterns cross-referenced against panel input from rental network executives informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, service duration structure, end-user industry vertical, and regional project cycle intensity. CAGRs derived from equipment replacement cycle analysis and emission compliance deadline impacts. Forecast inputs incorporated hybrid powertrain cost curves and DEF infrastructure penetration rates.
Several conditions sit outside the modeled scope, including unannounced federal emission standard accelerations, battery-electric range breakthroughs, and macroeconomic construction spending contractions. Forecasts reflect documented assumptions about fleet turnover timelines and technician training pipeline development. A small set of named triggers warrants ongoing watch: EPA Tier 5 proposal timing, data center power reliability contract migrations, and Gulf Coast hurricane disruption frequency.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Bulldozer Market
Construction Equipment
Baler Market
Construction Equipment
Earthmoving Equipment Undercarriage Market
Construction Equipment
Vietnam Crane Market
Construction Equipment
Global Floor Grinding Machine Market
Construction Equipment
Stud Welding Machine Market
Construction Equipment
CNC Machine Tools Market
Construction Equipment
Hydraulic Cylinders Market
Construction Equipment
Compact Excavator Market
Construction Equipment
Rotary Dryers Market
Construction Equipment
Part Feeder Market
Construction Equipment
Pressure Washer Market
Construction Equipment
Road Marking Equipment Market
Construction Equipment
Europe Construction Machinery Rental Market
Construction Equipment
Asia-Pacific Hydraulic Equipment Market
Construction Equipment
US Rental Equipment Market