
 North America Utility Locator Market | 2026-2036
North America Utility Locator Market Size, Share, and Industry Trends Forecast 2026-2036
North America Utility Locator Market Analytics
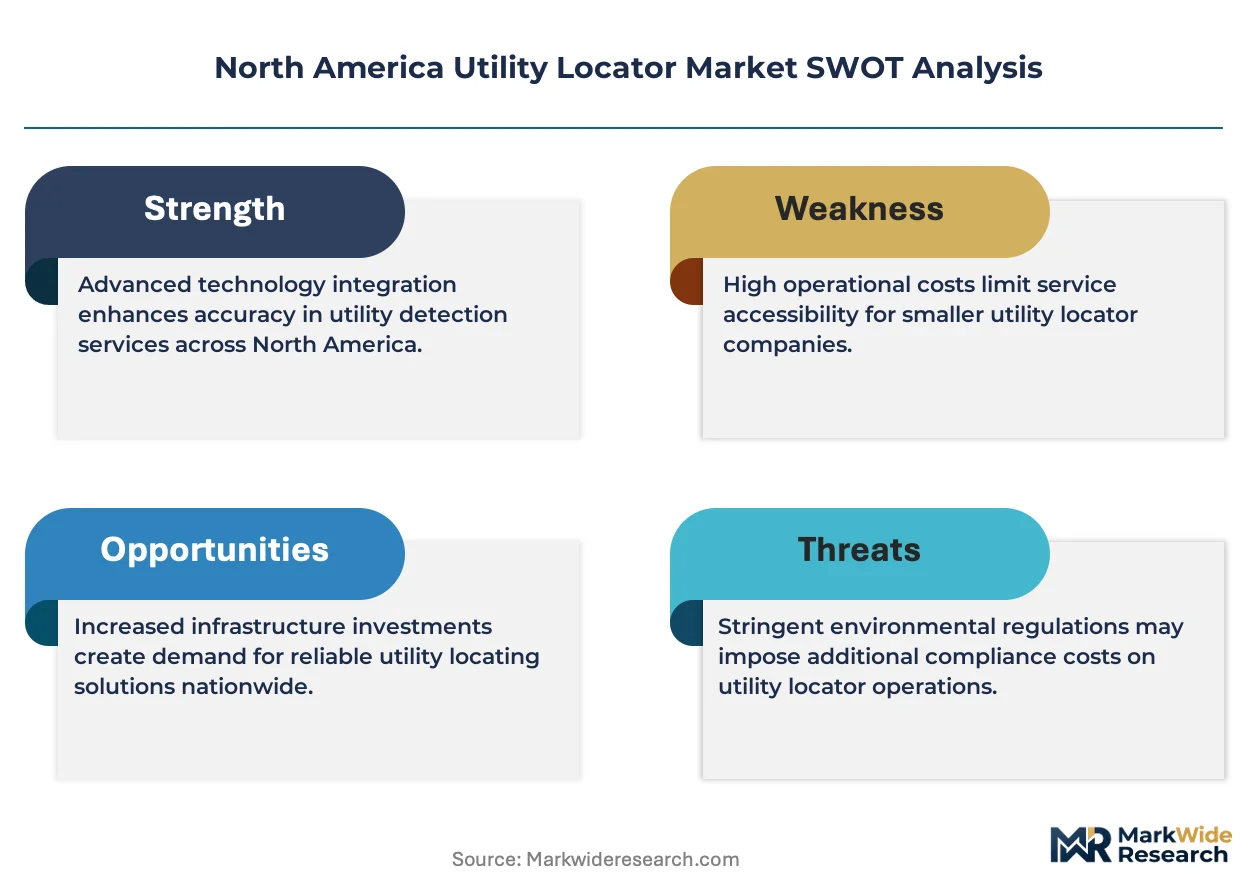
GIS-integrated hybrid detection is reshaping how utility locators capture, process, and deliver subsurface data to field crews and project managers. Emerson Electric Co. leverages its automation portfolio to anchor utility mapping within broader infrastructure digitalization strategies. Radiodetection Ltd. specializes in electromagnetic and ground-penetrating radar platforms for North American utility operators. Vermeer Corporation extends its horizontal directional drilling installed base into adjacent locator hardware and service revenue streams.
North America utility locators comprise electromagnetic sensors, ground-penetrating radar arrays, acoustic transducers, and software-integrated mapping platforms that detect and spatially record buried pipes, cables, and conduits with depth accuracy typically ranging from ±5% to ±10% of target depth; these systems prevent excavation damage, reduce project delays, and satisfy legal due-diligence requirements before ground disturbance. Electromagnetic locators occupy the largest product category due to decades of proven performance in metallic utility detection and lower capital barriers for municipal fleet procurement. Ground penetrating radar represents the fastest-expanding product segment as non-metallic pipe networks proliferate and resolution demands intensify for fiber-optic and composite material infrastructure. GIS integration across hybrid detection architectures commands premium pricing and recurring software revenue, concentrating margin pools in technology-integrated solution providers rather than hardware-only vendors.
The Federal Communications Commission's broadband equity programs and the Pipeline and Hazardous Materials Safety Administration's damage prevention rules collectively mandate pre-excavation locate notifications and documented utility mapping, directly expanding required locator deployment volumes and data retention standards. State-level one-call regulations across Texas, California, Illinois, and New York impose civil and criminal penalties for excavation damage, compelling construction companies and utilities to invest in higher-accuracy detection technologies and certified operator training programs. Stakeholders must monitor how artificial intelligence-enabled signal processing and autonomous drone-based electromagnetic surveys alter capital deployment timing, workforce skill requirements, and competitive differentiation between integrated platform vendors and specialized hardware manufacturers.
Market Dynamics
Fiber-optic deployment mandates from the Federal Communications Commission are forcing utilities and contractors to map non-metallic infrastructure with precision that electromagnetic sensors alone cannot deliver, compressing technology refresh cycles across municipal fleets.
Growth Catalysts
- Broadband equity programs:The FCC's infrastructure mandates require documented utility mapping before fiber trenching, expanding locator deployment volumes across Texas, California, and Florida construction markets.
- Pipeline safety enforcement:PHMSA damage prevention rules impose civil penalties for excavation strikes, compelling utilities to invest in certified operator training and higher-accuracy detection systems.
- Acoustic transducer adoption:Water utilities facing aging cast-iron replacement schedules are integrating acoustic detection for plastic pipe networks previously invisible to electromagnetic methods.
Market Restraints
- Semiconductor supply concentration:GPR array manufacturers depend on specialized analog-to-digital converters sourced primarily from East Asian foundries, creating lead time volatility for North American equipment assemblers.
- GIS software licensing costs:Esri platform subscription fees represent 15-25% of total system ownership costs, squeezing margins for municipal procurement departments with fixed capital budgets.
- Electromagnetic interference saturation:Dense urban environments with overlapping RF signals degrade locator accuracy in downtown Chicago, Manhattan, and downtown Toronto corridors.
Strategic Opportunities
- Drone-mounted electromagnetic surveys:FAA Part 107 commercial waivers are enabling aerial locator platforms for linear infrastructure corridors across rural Texas and Alberta oil sands regions.
- AI signal processing convergence:Machine learning algorithms trained on utility material databases are reducing false-positive rates in GPR interpretation, opening subscription revenue streams for software-integrated vendors.
- State-level training mandates:Illinois and New York one-call regulations now require certified locator operator credentials, creating accredited training program opportunities for equipment manufacturers.
Industry Challenges
- Electromagnetic-GPR data fusion expertise:Field crews require cross-training on hybrid system operation, stretching workforce development timelines for contractors in high-growth Sun Belt markets.
- Legacy CAD integration friction:Municipal engineering departments using decade-old AutoCAD installations face middleware costs and data format conversion delays when adopting cloud-native GIS platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Utility Locator Market |
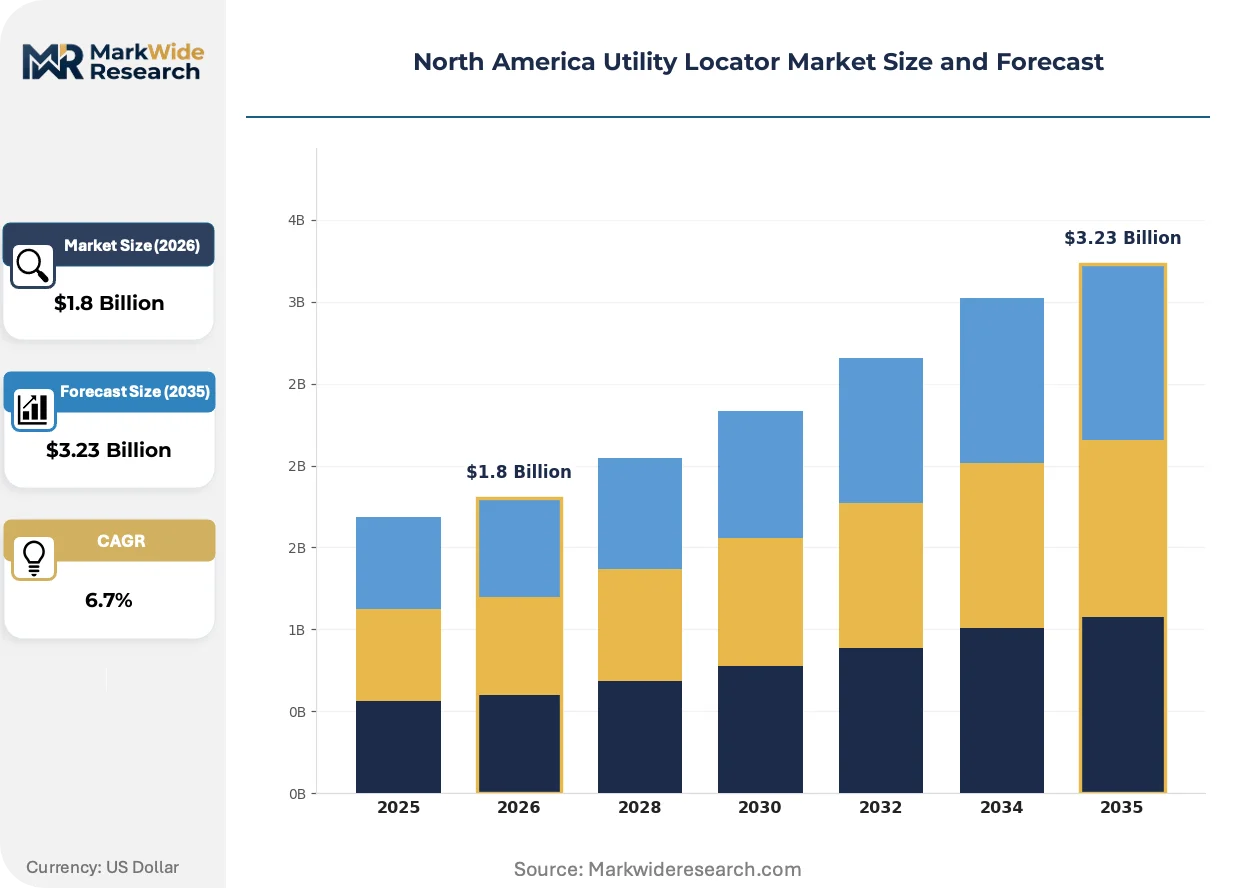
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electromagnetic Locators, Ground Penetrating Radar, Acoustic Locators, Utility Mapping Tools Service Type: Consulting Services, Installation Services, Maintenance Services, Training Services End User: Construction Companies, Municipalities, Utilities, Engineering Firms Technology: Passive Detection, Active Detection, Hybrid Detection, GIS Integration |
| Companies Covered | US Radar, 3M, Emerson Electric Co., Vermeer Corporation, Vivax-Metrotech Corp., Radiodetection Ltd., Guideline Geo, Subsite Electronics, Geophysical Survey Systems, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Utility Locator Market Evolving Landscape
Detection architecture is converging around multi-sensor fusion platforms that combine electromagnetic, GPR, and acoustic modalities into unified data streams, compressing the competitive advantage of single-technology vendors.
Multi-frequency electromagnetic locators are hybridizing with GPR arrays in single hardware packages, enabling simultaneous metallic and non-metallic utility detection. Water utilities in Florida and gas distribution operators in California are adopting these platforms to reduce truck rolls and crew dispatch costs. The technology is hybridizing procurement decisions, forcing municipal buyers to evaluate total lifecycle data value rather than capital expenditure alone.
PHMSA's forthcoming damage prevention rulemaking is tightening documentation requirements for pre-excavation locate notifications and retention periods. Construction firms and one-call centers must upgrade data management infrastructure to satisfy audit-ready utility mapping standards. Underground contractors in Texas and pipeline operators in Alberta are investing in GIS-integrated platforms to preempt enforcement actions.
Equipment-as-a-service contracts are displacing outright purchase models among mid-sized excavation contractors facing cash flow constraints. Rental channel partners in the Sun Belt are unbundling hardware, software, and certified operator provision into monthly subscription tiers. This shift concentrates most visibly in Texas and Arizona markets where private infrastructure investment funds are consolidating underground construction capacity.
North America Utility Locator Market Segmentation
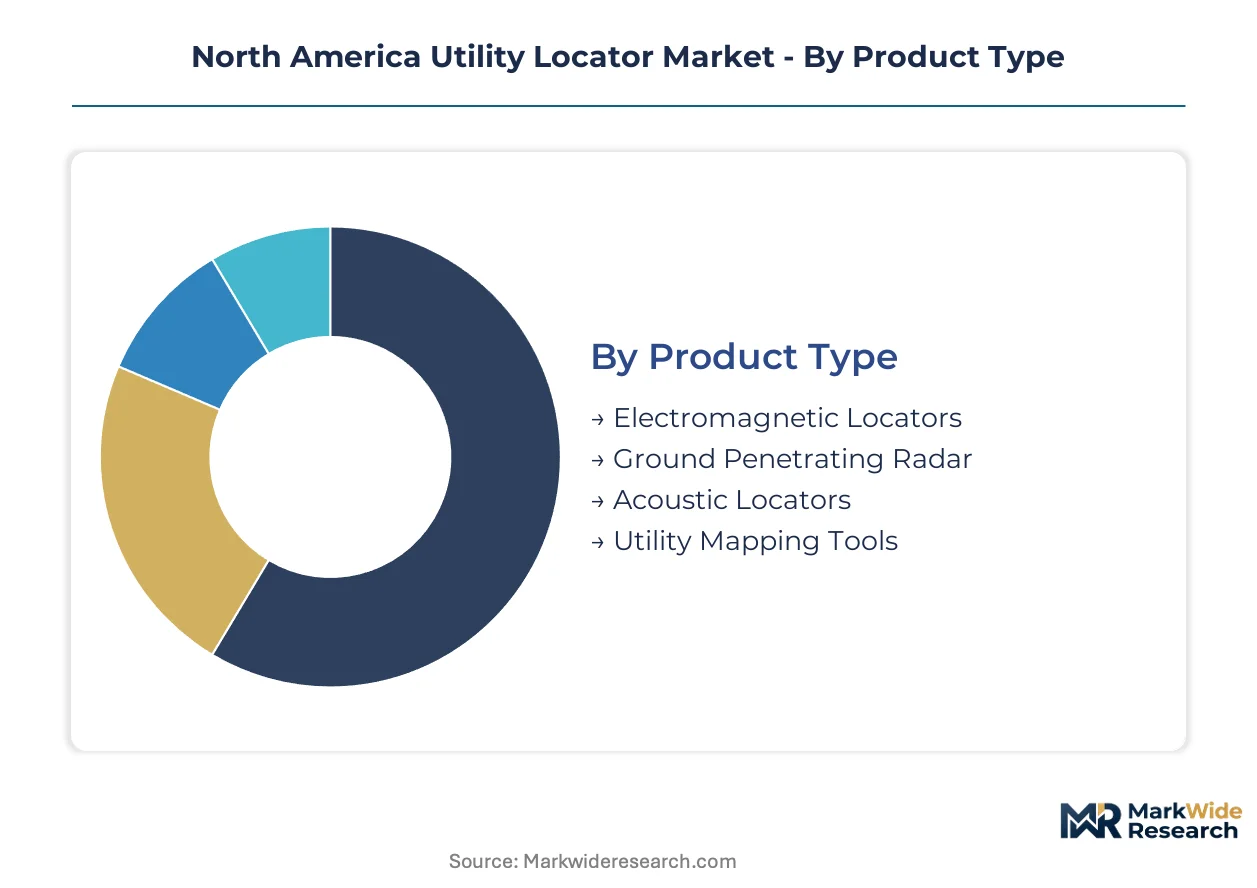
Segmentation in the North America utility locator market reveals distinct procurement rhythms across hardware, services, and technology tiers. Municipal fleet managers rotate electromagnetic equipment on 7-10 year cycles while GPR platforms refresh every 3-5 years due to software dependency.
Product Type:
Replacement cycles vary dramatically by detection modality, with software-dependent platforms turning over fastest and electromagnetic hardware proving most durable.
- Electromagnetic Locators:These systems transmit low-frequency signals through metallic pipes and cables, detecting field distortions via receiver coils. Texas municipalities and California water districts standardize on these units for iron and copper infrastructure mapping, though fiber-optic blind spots limit their utility for modern telecom deployments.
- Ground Penetrating Radar:GPR arrays emit high-frequency radio pulses into subsurface media, capturing reflections from dielectric discontinuities including plastic conduits and concrete structures. Florida contractors facing PVC pipe networks and Illinois gas operators mapping polyethylene distribution lines drive replacement demand as resolution specifications tighten.
- Acoustic Locators:Transducers detect pressure-wave signatures in pressurized water lines, filling detection gaps for non-metallic infrastructure.
- Utility Mapping Tools:Integrated hardware-software packages combine sensor data with spatial databases for as-built documentation.
Electromagnetic locators anchor the volume base while ground penetrating radar gains share at the steepest rate.
Service Type:
Revenue concentration shifts toward recurring service contracts as equipment complexity rises and certified operator mandates expand.
- Maintenance Services:Preventive calibration programs and sensor refurbishment contracts secure multi-year revenue streams. California one-call centers and Texas pipeline operators prioritize uptime guarantees over break-fix arrangements, particularly for GPR arrays where drift compensation demands quarterly attention.
- Training Services:Certification programs for electromagnetic-GPR hybrid operation address workforce gaps. Illinois and New York regulations now mandate documented operator credentials, compelling equipment vendors to develop accredited curricula and examination protocols.
- Consulting Services:Subsurface mapping specialists interpret complex geologies and utility congestion scenarios.
- Installation Services:Field deployment support for fleet integration and initial system commissioning.
Maintenance services generate the most predictable revenue streams while training services expand most quickly amid regulatory credential requirements.
End User:
Procurement authority and budget cycles diverge sharply between public infrastructure owners and private construction contractors.
- Utilities:Electric, gas, and water system operators maintain captive locator fleets for routine maintenance and emergency response. Florida power distributors and Alberta oil sands operators standardize on hybrid detection platforms to reduce third-party locate dependency and accelerate repair timelines.
- Construction Companies:Excavation contractors face cash flow constraints and project-based equipment utilization. Sun Belt infrastructure funds consolidating underground construction capacity favor equipment-as-a-service arrangements over capital purchases.
- Municipalities:City engineering departments balance fleet standardization against fragmented procurement authority across departments.
- Engineering Firms:Design consultants specify detection methodologies and validate contractor locate quality.
Utilities dominate capital procurement volumes while construction companies drive the fastest adoption of subscription-based service models.
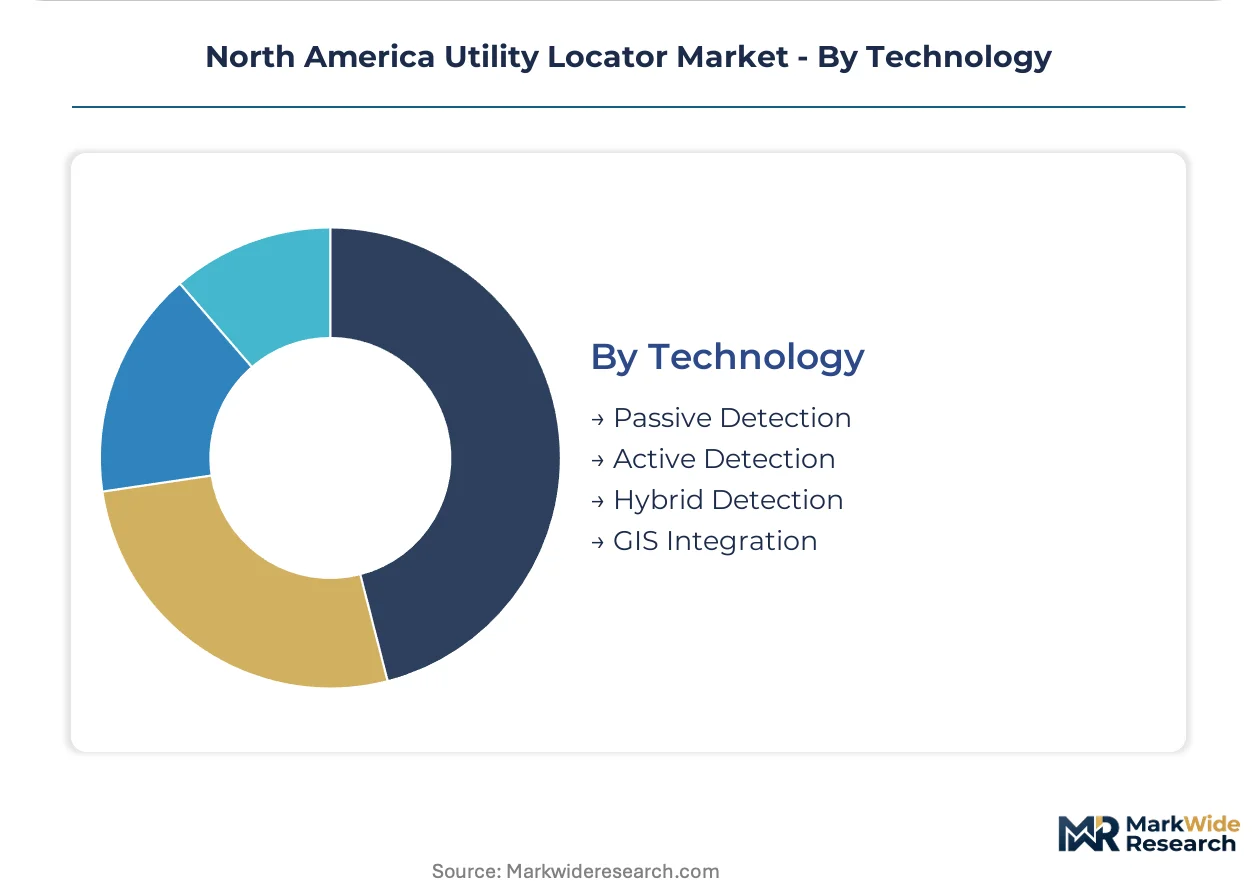
Technology:
Integration depth determines pricing power, with standalone detection methods commoditizing while fused data platforms command premium positioning.
- Hybrid Detection:Multi-sensor architectures combine electromagnetic, GPR, and acoustic modalities into unified interpretation workflows. California gas distribution operators and Florida water utilities adopt these platforms to reduce truck rolls and eliminate repeat site visits for complex utility corridors.
- GIS Integration:Real-time spatial database connectivity transforms field detection into enterprise asset management inputs. Municipal engineering departments in Chicago and Toronto face middleware friction with legacy CAD installations but prioritize cloud-native platforms for audit-ready documentation.
- Active Detection:Transmitter-based methods including direct connection and inductive clamp techniques for metallic utility tracing.
- Passive Detection:Receiver-only operation capturing ambient electromagnetic fields from energized power lines and cathodic protection systems.
GIS integration commands the highest margin tier while hybrid detection shows the steepest volume expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Construction contractors and municipal fleet managers across North America concentrate procurement authority in Texas, California, and Florida, where aging infrastructure and broadband deployment mandates converge. State-level one-call regulations and FCC infrastructure programs reshape capital deployment patterns.
United States
Texas pipeline operators and California water utilities drive hybrid detection platform adoption to reduce third-party locate dependency. FCC broadband equity programs mandate documented utility mapping before fiber trenching, accelerating equipment refresh cycles. The Permian Basin and Houston-Galveston corridor anchor oil and gas infrastructure mapping demand.
Canada
Alberta oil sands operators and Ontario municipal engineering departments standardize on GIS-integrated systems for audit-ready documentation. Federal pipeline safety enforcement tightens pre-excavation notification requirements. The Calgary-Edmonton corridor concentrates locator fleet procurement for linear infrastructure corridors.
Mexico
Federal energy infrastructure expansion and urban water system modernization create detection equipment import demand. CFE transmission projects require subsurface mapping for new corridor development. The Mexico City metropolitan area and northern border states concentrate municipal procurement activity.
North America Utility Locator Market Competitive Landscape
Channel-controlling players compete with product-specialist players across electromagnetic, GPR, and integrated platform segments. The vendor base clusters around three strategic archetypes: diversified industrial conglomerates with automation portfolios, specialized detection technology developers, and equipment manufacturers extending from adjacent machinery categories. Competitive moves concentrate on technology licensing arrangements and portfolio diversification into software-integrated service models.
Among diversified industrial players, Emerson Electric Co. and 3M occupy positions anchoring utility mapping within broader infrastructure digitalization strategies. Radiodetection Ltd. and Vermeer Corporation exemplify specialization vectors—one in electromagnetic and GPR platforms, the other extending horizontal directional drilling expertise into adjacent locator hardware. These four represent distinct competitive positioning archetypes rather than overlapping market contests.
| Leading Market Players |
|---|
| US Radar |
| 3M |
| Emerson Electric Co. |
| Vermeer Corporation |
| Vivax-Metrotech Corp. |
| Radiodetection Ltd. |
| Guideline Geo |
| Subsite Electronics |
| Geophysical Survey Systems, Inc. |
| Others |
Value Network & Pricing Analysis
Dongguan and Shenzhen electronics clusters anchor GPR array production capacity, and their foundry utilization rates directly transmit into North American equipment pricing power through analog-to-digital converter availability.
Pricing Analysis
Cost-plus contracts with semiconductor indexation dominate municipal procurement for electromagnetic locator fleets. Pricing stratifies across GIS-integrated hybrid platforms, standalone GPR arrays, and basic electromagnetic wands based on software dependency and certification tier. Cost compression in entry-level electromagnetic hardware is intensifying because municipal buyers consolidate vendor relationships and demand volume discounts. Construction contractors exhibit the highest price sensitivity due to project-based cash flows, while utilities with captive fleet operations accept premium positioning for uptime guarantees and multi-year service bundling.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for North American locator assemblers. Specialized analog-to-digital converters, high-frequency antenna substrates, and precision electromagnetic coils draw from Taiwan, Japan, and South Korea fabrication facilities. Single-source vulnerability concentrates in FPGA programming for GPR signal processing chipsets. Distribution runs through authorized dealer networks and rental channel partners serving the Sun Belt construction corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Drone-based electromagnetic surveys and AI-enabled autonomous interpretation represent substitution threats that incumbent hardware vendors must neutralize through platform integration.
For Market Incumbents: Pre-empt pure-play drone survey operators by certifying aerial electromagnetic platforms under FAA Part 107 waivers and embedding machine learning interpretation into existing GIS software subscriptions. Channel control through captive rental fleet partnerships in Texas and Arizona defends against equipment-as-a-service disintermediation.
For New Entrants and Emerging Players: Mid-sized water utilities in the Great Lakes region with aging cast-iron replacement schedules represent the most penetrable entry point for acoustic-GPR hybrid platforms previously uneconomical for electromagnetic specialists. A training-certification bundled go-to-market angle satisfies Illinois and New York operator mandate requirements while building switching costs.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among GIS-integrated platform vendors with municipal software subscription attach rates above hardware-only peers. Long-term viability in this market hinges on data retention contract duration and audit-ready documentation compliance. Watch PHMSA enforcement action frequency as the inflection indicator for compliance-driven procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| GIS Platform Integration | Esri ArcGIS compatibility locks municipal engineering departments into recurring software revenue streams. |
| AI Signal Processing Development | Machine learning interpretation reduces GPR false-positive rates and opens subscription pricing tiers. |
| Certified Training Program Accreditation | Illinois and New York operator mandates create accredited curriculum revenue and vendor stickiness. |
| Drone Electromagnetic Survey Certification | FAA Part 107 waivers enable aerial linear corridor mapping across rural Texas and Alberta. |
| Equipment-as-a-Service Launch | Monthly subscription tiers capture cash-constrained Sun Belt excavation contractors. |
Research Methodology
Desk research of FCC broadband infrastructure filings, PHMSA damage prevention rulemaking dockets, and state one-call regulatory databases preceded structured interviews with municipal fleet managers, one-call center operations directors, GPR equipment engineering leads, and underground construction project supervisors. Secondary validation drew from equipment manufacturer technical specifications, municipal procurement records, and construction industry trade association surveys. Bottom-up demand modeling triangulated against top-down infrastructure investment forecasts.
Assumptions held fixed include FCC broadband equity program funding continuity, PHMSA enforcement rulemaking trajectory, and state-level one-call penalty structures across the projection horizon. Segmentation dimensions modeled encompass detection modality, service contract type, end-user procurement authority, and technology integration depth. CAGRs derived from equipment replacement cycle analysis, software subscription renewal rates, and infrastructure construction permit volumes. Forecast inputs included fiber-optic deployment pipeline data and water utility capital improvement schedules.
Practitioners should monitor semiconductor foundry utilization rates and FAA unmanned aircraft regulatory revisions for early signals of equipment availability and aerial survey market access. Forecasts reflect assumptions about municipal budget continuity and broadband subsidy program longevity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
High Pressure Grinding Rollers Market
Material Handling Equipment
High-Precision Gear Reducer Market
Material Handling Equipment
Loader Bucket Attachments Market
Material Handling Equipment
Coal Handling Equipment Market
Material Handling Equipment
Global Bucket Loader Market
Material Handling Equipment
Middle East Conveyor Belts Market
Material Handling Equipment
Conveyor Scales Market
Material Handling Equipment
Gravity Conveyor Market
Material Handling Equipment
Asia Pacific Mobile Crane Market
Material Handling Equipment
Weighbridge Market
Material Handling Equipment
Global Screw Conveyors Market
Material Handling Equipment
Global Bop Handling Systems Market
Material Handling Equipment
Bulk Material Handling System Market
Material Handling Equipment
Global Telescopic Boom Forklift Truck Market
Material Handling Equipment
Arrestor Cables Market
Material Handling Equipment
Vertical Baling Press Market