
 Construction Lifts Market | 2026-2036
Construction Lifts Market Size, Share, and Industry Trends Forecast 2026-2036
Construction Lifts Market Analysis
Aftermarket service revenue is reconfiguring margin pools away from pure equipment sales across the construction lifts industry. GEDA GmbH leverages its German engineering heritage to sustain premium positioning in vertical transportation systems for high-rise builds. JLG Industries dominates North American aerial platform supply through extensive dealer networks and telematics-enabled fleet management. CABR Construction Machinery Technology Co. Ltd anchors its competitive stance on manufacturing scale within China's domestic infrastructure cycle.
Construction lifts are electromechanical vertical transportation systems designed to move personnel, tools, and materials across building levels, typically achieving load capacities from 500 kg to over 3,000 kg and travel speeds up to 90 meters per minute depending on drive configuration. Their primary industrial purpose centers on eliminating crane dependency for mid-rise construction while improving site logistics efficiency and worker safety during structural assembly and finishing phases. Scissor lifts command the largest installed base among product types due to their stability on flat surfaces and lower operational complexity, though boom lifts are capturing disproportionate growth in infrastructure maintenance and irregular terrain applications. Electric power sources are displacing diesel alternatives in urban job sites where emission ordinances and indoor operation requirements restrict combustion equipment, while hybrid configurations are emerging as a transitional architecture for projects spanning enclosed and open environments.
OSHA in the United States enforces fall protection and aerial lift operator certification standards that directly shape equipment specification and training service bundling. The EU Machinery Directive and CE marking requirements mandate comprehensive risk assessments and conformity procedures that filter non-compliant suppliers from European procurement channels. China's SAMR administers GB standards for construction machinery safety that manufacturers must satisfy for domestic market access. Stakeholders must monitor regulatory divergence between jurisdictions as compliance fragmentation threatens to complicate global product platform strategies and service network standardization.
Market Dynamics
Aftermarket service revenue is reconfiguring margin pools away from pure equipment sales across the construction lifts industry. Electric powertrain conversion and telematics integration are compressing traditional maintenance intervals while creating recurring data-service revenue streams.
Growth Catalysts
- EU Machinery Directive:Tightening safety certification requirements for aerial work platforms are filtering non-compliant suppliers from European procurement channels, consolidating demand toward certified manufacturers.
- India high-rise construction:Urban vertical development in Mumbai and Bangalore is intensifying equipment rental demand as developers seek flexible fleet access over capital ownership.
- Telematics-enabled fleet management:Real-time equipment monitoring is reducing downtime and optimizing utilization rates for rental fleet operators managing distributed job sites.
Market Restraints
- Steel and aluminum input volatility:Structural material price swings compress manufacturing margins and complicate long-term contract pricing for lift fabricators.
- Chinese tier-one city concentration:Infrastructure demand clustering in Shanghai, Beijing, and Shenzhen creates geographic overexposure and cyclical demand vulnerability.
- Battery energy density limitations:Current lithium-ion configurations restrict runtime and lift capacity for all-electric models in heavy-load applications.
Strategic Opportunities
- India secondary cities:Hyderabad, Chennai, and Pune present underpenetrated rental markets as commercial real estate development spreads beyond established metros.
- Hybrid powertrain convergence:Dual diesel-electric architectures bridge emission-restricted urban zones and off-grid rural sites without fleet duplication.
- Outcome-based rental contracts:Equipment-as-a-service models bundle maintenance, training, and uptime guarantees, capturing lifetime value from risk-averse contractors.
Industry Challenges
- Certified operator shortage:OSHA aerial lift certification requirements exceed training pipeline capacity, constraining fleet deployment velocity.
- CE marking timeline compression:EU conformity assessment procedures extend product launch cycles, disadvantaging smaller manufacturers against established players.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction Lifts Market |
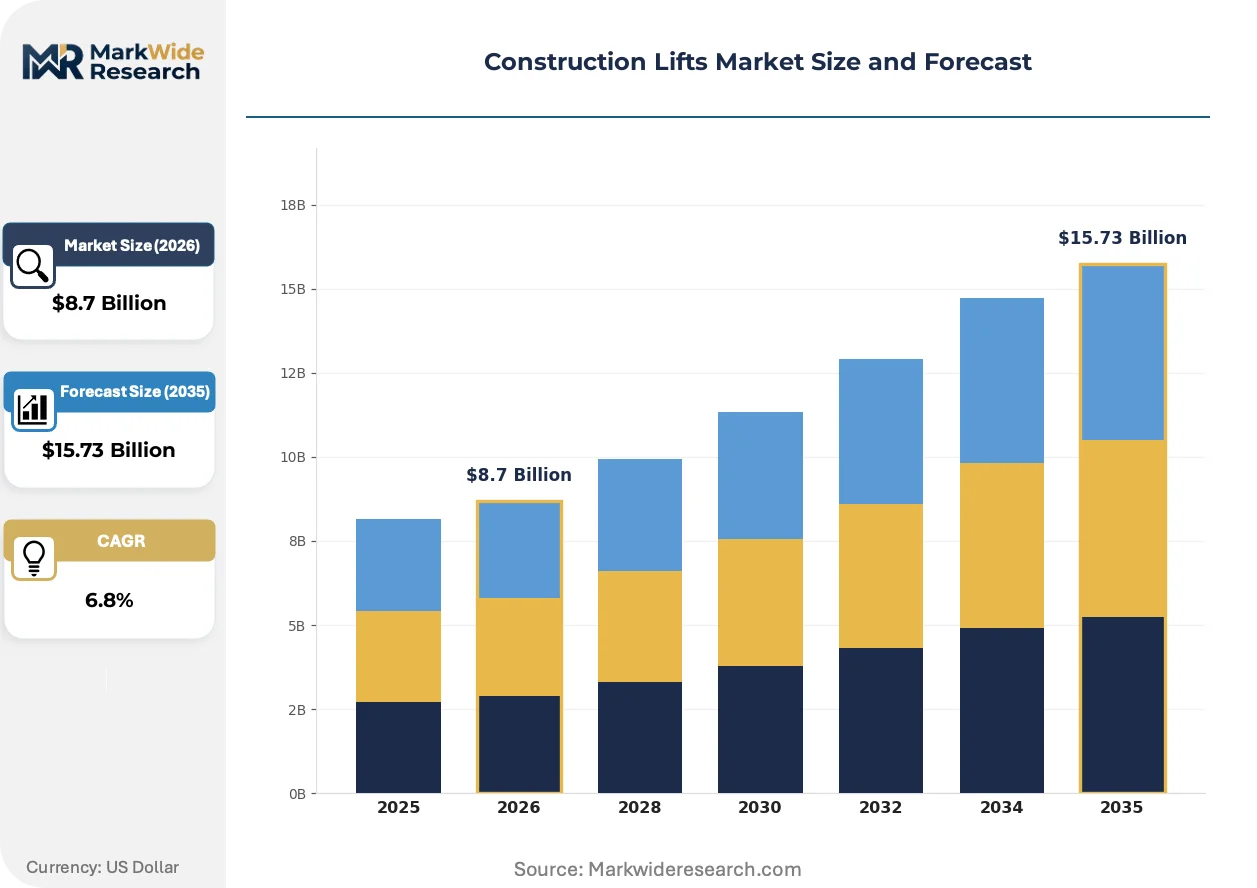
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scissor Lifts, Boom Lifts, Fork Lifts, Material Lifts End User: Construction Companies, Contractors, Rental Services, Warehouses Installation Type: Fixed, Mobile, Portable, Modular Power Source: Electric, Diesel, Gas, Hybrid |
| Companies Covered | Alimak Group AB, Fraco Products Ltd., XL Industries, CABR Construction Machinery Technology Co. Ltd, Electroelsa Srl, GEDA GmbH, Maber, STROS - Sedlcanské strojírny, a. s., JLG Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction Lifts Market Emerging Trajectories
Digital twin technology and predictive maintenance systems are transforming how fleet operators manage equipment lifecycle costs. These innovations compress downtime while shifting competitive advantage toward data-integrated service providers.
Digital twin platforms are virtualizing physical lift performance through real-time sensor feeds and physics-based simulation models. Major rental fleet operators in Germany and the United States are deploying these systems to predict component failures before operational impact. This technology is virtualizing traditional preventive maintenance schedules into condition-based interventions that reduce parts inventory and labor allocation.
OSHA fall protection enforcement is tightening operator certification documentation and inspection record retention requirements. Construction contractors now face elevated liability exposure from inadequate training verification, driving bundled equipment-rental-service agreements. North American aerial platform procurement is responding through third-party training partnerships that transfer compliance risk from end-users to rental providers.
Equipment rental preference is displacing ownership models among mid-sized contractors managing project portfolio volatility. Rental channel revenue is capturing a growing share of total industry value as capital-light operating structures gain favor. This shift is most pronounced in China's tier-one megacities where infrastructure modernization programs accelerate fleet turnover and technology refresh cycles.
Construction Lifts Market Segmentation
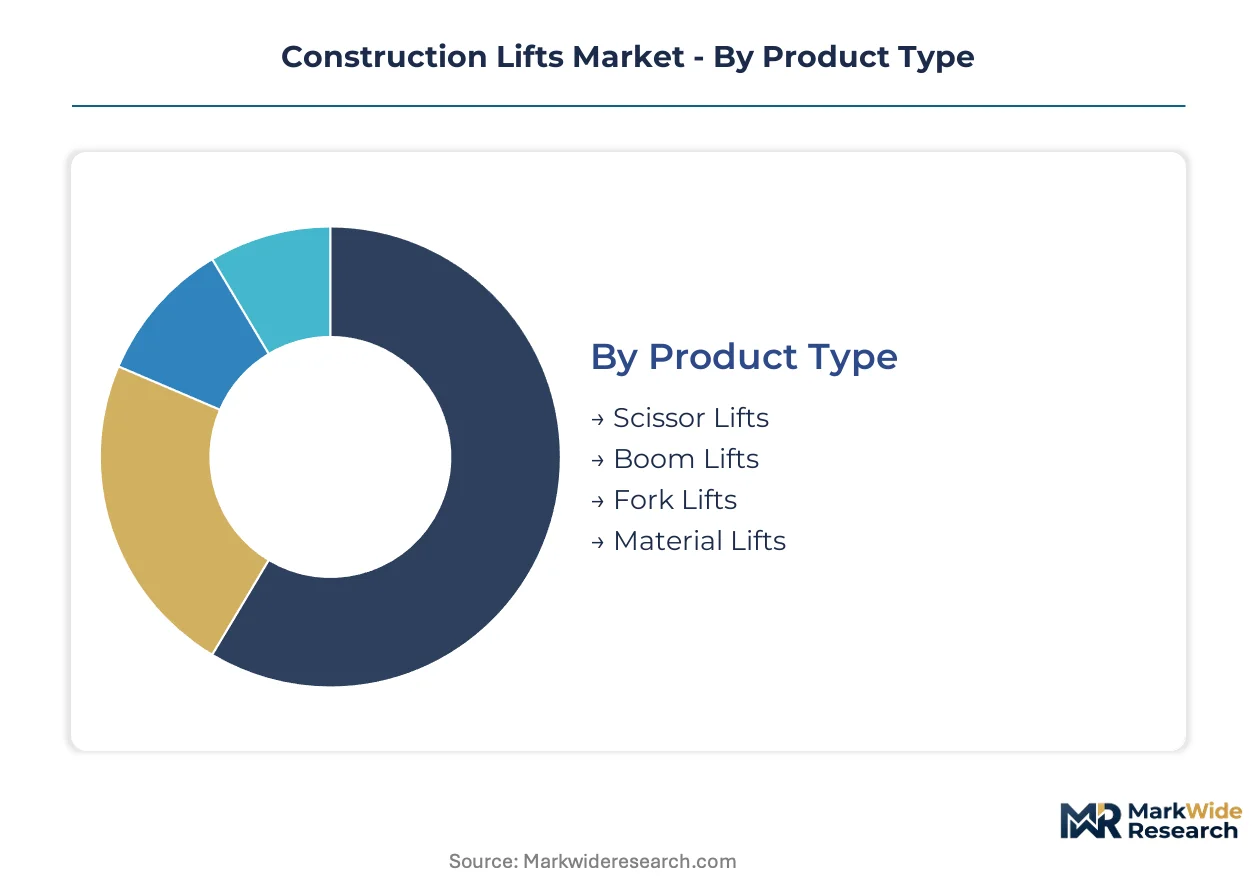
Segmentation reveals divergent equipment lifecycles across the construction lifts industry. Rental fleet operators track replacement intervals by product type, while end-user profiles determine service bundling intensity and financing structures.
Product Type:
Cycle times vary dramatically: scissor lifts turn over every 5-7 years under rental fleet pressure, while boom lifts stretch to 8-10 years given lower utilization rates and higher capital recovery thresholds.
- Scissor Lifts:These platforms deploy crossed hydraulic scissor mechanisms to achieve vertical elevation up to 18 meters with stable load distribution across flat surfaces. Demand clusters in India's high-rise residential towers and commercial complexes where repetitive floor-to-floor material movement dominates site logistics. Fleet operators in Mumbai and Bangalore favor these units for their lower operational complexity and reduced certification burden.
- Boom Lifts:Articulated or telescopic boom configurations extend reach beyond vertical limits, accessing irregular facades and infrastructure maintenance zones. Infrastructure modernization programs across China's tier-one megacities are accelerating deployment for bridge inspection, tunnel maintenance, and utility corridor work where terrain constraints exclude scissor alternatives.
- Fork Lifts:Counterbalanced mast trucks handle palletized material transport across construction staging areas and warehouse integration points.
- Material Lifts:Compact vertical conveyors move bulk construction supplies between floors without personnel carriage, occupying lower regulatory scrutiny tiers.
Scissor lifts dominate installed base. Boom lifts are where expansion concentrates.
End User:
Customer type shapes contract structure: rental services demand telematics integration and uptime guarantees, while direct purchasers prioritize acquisition cost over lifecycle service.
- Construction Companies:Large general contractors with sustained project pipelines favor capital ownership to capture depreciation benefits and maintain fleet control across multi-year developments. These operators in Germany and the United States are integrating digital twin platforms to compress maintenance intervals and reduce total cost of ownership.
- Contractors:Specialty trades—electrical, HVAC, glazing—operate smaller fleets with higher equipment specificity per trade. India's secondary city construction boom is pulling these operators toward rental models as project location volatility makes ownership economics unfavorable.
- Rental Services:Fleet aggregators bundle equipment, maintenance, and operator training into outcome-based contracts.
- Warehouses:Distribution center operators specify low-mast variants for indoor clearance constraints.
Construction companies anchor capital sales volume. Rental services are climbing the fastest as operating models shift.
Installation Type:
Deployment permanence determines regulatory pathway: fixed installations trigger building code integration and inspection protocols, while mobile units face transport and site-to-site compliance.
- Fixed:Permanent hoistways integrated into building structures serve high-rise construction through completion and transition to permanent elevator installation. These systems achieve highest load ratings and travel speeds, dominating superstructure assembly phases in Shanghai and Shenzhen where vertical transportation efficiency constrains critical path schedules.
- Mobile:Self-propelled or trailer-mounted units relocate between job sites without structural modification. European rental fleets are concentrating procurement here as CE marking requirements and conformity assessment procedures filter non-compliant suppliers from procurement channels.
- Portable:Lightweight aluminum units assemble without powered equipment for low-rise applications.
- Modular:Component-based systems scale height and capacity through standardized section addition.
Mobile units dominate fleet counts. Fixed installations concentrate margin capture.
Power Source:
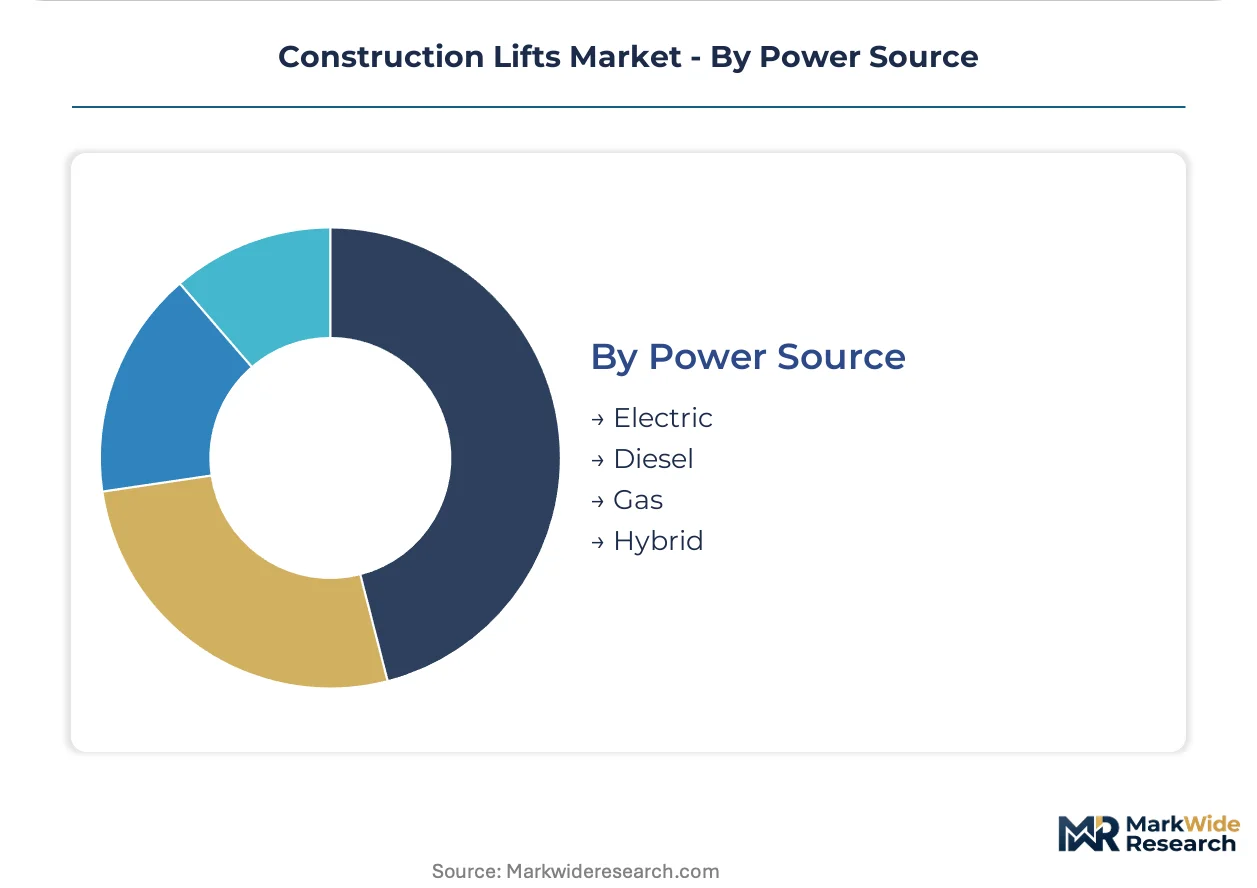
Energy architecture determines operational envelope: electric systems face runtime and capacity ceilings, while combustion units confront emission ordinances in urban zones.
- Electric:Battery-powered drivetrains eliminate exhaust emissions for indoor operation and urban job sites where municipal ordinances restrict combustion equipment. China's tier-one megacities are accelerating specification as infrastructure modernization programs align with national dual carbon goals and local air quality enforcement.
- Hybrid:Dual diesel-electric architectures switch power modes based on environment, bridging emission-restricted urban zones and off-grid rural sites without fleet duplication. These configurations are gaining share fastest among German rental operators managing mixed urban-peripheral project portfolios.
- Diesel:Internal combustion engines sustain heavy-load capacity and extended runtime for unimproved sites lacking grid access.
- Gas:Propane or natural gas alternatives occupy niche indoor-outdoor transitional applications.
Electric systems dominate new urban specifications. Hybrid architectures are where technology investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India and China exhibit the highest price elasticity, prioritizing rental access over capital ownership, while German and US purchasers absorb premium pricing for certified equipment and integrated service bundles.
United States
Commercial high-rise development in New York and Chicago drives fleet renewal demand among rental operators. OSHA aerial lift certification requirements exceed training pipeline capacity, constraining deployment velocity. Dallas-Fort Worth and Atlanta construction corridors concentrate equipment utilization among multi-site general contractors.
Germany
Industrial facility modernization and renewable energy infrastructure sustain steady equipment replacement cycles. CE marking requirements and EU Machinery Directive conformity assessments filter non-compliant suppliers from procurement channels. Bavaria and North Rhine-Westphalia anchor rental fleet concentration among mid-sized contractors seeking flexible access.
China
Tier-one megacity infrastructure programs in Shanghai, Beijing, and Shenzhen accelerate fleet turnover and technology refresh demand. SAMR-administered GB standards for construction machinery safety govern domestic market access. Yangtze River Delta and Pearl River Delta clusters concentrate manufacturing scale and rental service expansion.
India
Urban vertical development in Mumbai and Bangalore intensifies equipment rental demand as developers seek capital-light operating structures. National building code enforcement tightens safety equipment specifications for high-rise construction. Hyderabad, Chennai, and Pune present underpenetrated secondary markets as commercial real estate spreads beyond established metros.
United Arab Emirates
Expo legacy infrastructure and hospitality sector expansion sustain elevated construction activity in Dubai and Abu Dhabi. Local municipal authorities enforce equipment safety inspection protocols aligned with international standards. Saudi Arabia's giga-project pipeline pulls regional fleet capacity northward, tightening UAE equipment availability during peak construction windows.
Construction Lifts Market Vendor Landscape
German engineering specialists and North American platform manufacturers split the market along certification-intensity and fleet-scale vectors. Structure consolidates toward established players with documented conformity procedures and telematics-integrated service networks. Three archetypes dominate: premium-tier engineering houses with heritage positioning, scale-driven rental fleet suppliers, and domestic champions serving protected procurement channels. Competitive moves concentrate on hybrid powertrain convergence and outcome-based contract bundling to capture lifetime customer value.
Within the premium-tier engineering segment, GEDA GmbH and Alimak Group AB exemplify heritage-positioned specialists whose German and Swedish origins signal conformity pedigree. JLG Industries anchors North American aerial platform supply through extensive dealer networks. CABR Construction Machinery Technology Co. Ltd occupies the scale-driven domestic champion position within China's infrastructure cycle, representing manufacturers whose geographic concentration aligns with protected public procurement preferences.
| Leading Market Players |
|---|
| Alimak Group AB |
| Fraco Products Ltd. |
| XL Industries |
| CABR Construction Machinery Technology Co. Ltd |
| Electroelsa Srl |
| GEDA GmbH |
| Maber |
| STROS - Sedlcanské strojírny, a. s. |
| JLG Industries |
| Others |
Supply Flow & Price Mechanics
The Yangtze River Delta manufacturing cluster anchors global lift fabrication capacity, with its steel-forging and hydraulic component ecosystems granting tier-one producers outsized pricing leverage over downstream rental operators. OEMs in this corridor exploit scale efficiencies to compress per-unit costs, while European engineering houses offset manufacturing premiums through bundled certification and aftermarket service tiers.
Pricing Analysis
Aftermarket service contracts now generate the dominant share of lifetime customer value across the construction lifts industry. Three-tier pricing structure across premium, standard, and economy levels stratifies by CE marking pedigree and telematics integration depth. Cost compression in the standard tier intensifies as Chinese manufacturers expand export capacity. Rental fleet operators exhibit the highest price sensitivity, while German industrial contractors absorb premium positioning for documented conformity procedures.
Supply Chain Analysis
Steel plate, high-grade aluminum extrusions, and precision hydraulic systems feed from concentrated supply bases in China, Germany, and South Korea. Raw material price volatility in structural metals and battery-grade lithium compounds creates margin instability for fabricators locked into long-term equipment leases. Single-source vulnerability around German-engineered safety control systems threatens production continuity. Distribution runs through authorized dealer networks in North America and direct-to-fleet relationships in Asia-Pacific markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telescopic handler maintenance contracts and predictive analytics subscriptions are expanding faster than new equipment sales, reframing competitive advantage around recurring revenue capture. Hardware margins are compressing toward commodity levels while service attach rates determine enterprise value.
For Market Incumbents: Insulate premium positioning by deepening captive supply of safety-critical control systems and accelerating CE marking investments ahead of EU Machinery Directive enforcement waves. Battery-electric conversion programs represent the priority R&D allocation to preempt emission ordinance expansion. Channel control through exclusive dealer territories in secondary Indian cities defends against Chinese scale entrants. For New Entrants and Emerging Players: Hybrid powertrain retrofit kits for aging diesel fleets in Southeast Asian construction corridors represent the most penetrable entry point. Outcome-based rental contracts for mid-rise commercial developments in Hyderabad and Chennai bypass capital-intensive manufacturing scale requirements. Partnership with established European certification bodies accelerates market access without multi-year conformity assessment timelines. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among telematics-integrated rental fleet operators with documented uptime guarantee programs. Long-term viability hinges on service network density rather than manufacturing asset intensity. Acquisition targets should demonstrate backward integration into critical hydraulic component supply. Watch for inflection when hybrid powertrain penetration crosses threshold mass in German municipal procurement channels.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Real-time fleet monitoring by JLG Industries compresses downtime and enables predictive maintenance revenue streams. |
| Hybrid Powertrain Development | Dual diesel-electric architectures by GEDA GmbH bridge emission-restricted urban zones and off-grid rural sites. |
| CE Marking Acceleration | Expedited conformity assessment procedures filter non-compliant suppliers from European procurement channels. |
| Secondary City Rental Expansion | Hyderabad and Chennai penetration captures India's spreading commercial real estate development beyond established metros. |
| Aftermarket Service Bundling | Outcome-based contracts with uptime guarantees capture lifetime value from risk-averse contractors in volatile project pipelines. |
Methodological Framework
A standing panel of rental fleet operations directors, OEM procurement managers, construction site safety officers, and aftermarket service heads provided ongoing calibration against field conditions. Primary interview intelligence combined with customs trade records, EU Machinery Directive conformity databases, and SAMR GB standard filings. Bottom-up equipment shipment tracking and top-down construction spending analysis were triangulated to validate volume estimates.
Scenario bracketing around steel price volatility bands and battery energy density improvement curves anchored the projection framework across the analysis window. Segmentation modeling incorporated product type, power source architecture, end-user operating model, and regional regulatory cluster. CAGRs derived from fitted growth curves against historical replacement cycle data and infrastructure investment pipelines. Fleet telematics adoption rates and certified operator training capacity constraints fed industry-specific forecast adjustments.
Stress conditions across aluminum input cost spikes, EU conformity assessment timeline extensions, and Indian rental market penetration ceilings were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about infrastructure modernization program continuity and emission ordinance enforcement intensity. Cross-checking against national construction equipment registration databases and major rental operator fleet disclosure filings is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Belt Scales Market
Material Handling Equipment
Material Handling Automation Market
Material Handling Equipment
Freight Elevators Market
Material Handling Equipment
Centrifugal Industrial Dryer Market
Material Handling Equipment
Container Handling Equipment Market
Material Handling Equipment
US and Mexico Metal Stamping Market
Material Handling Equipment
Spring Shackles Market
Material Handling Equipment
Material Handling Equipment Market
Material Handling Equipment
Modular Self-Contained Aisle and Racking Systems Market
Material Handling Equipment
Asia-Pacific Conveyors Market
Material Handling Equipment
Portable Forklift Ramps Market
Material Handling Equipment
High Pressure Grease Hose Market
Material Handling Equipment
Global Conveyors Market
Material Handling Equipment
Industrial Elevator Market
Material Handling Equipment
Conveyors and Belt Loaders Market
Material Handling Equipment
Dump Tubs Market