
 Arc Welding Equipment Market | 2026-2036
Arc Welding Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Arc Welding Equipment Market Analysis
Multi-source procurement for power electronics and torch assemblies is recalibrating how welding equipment manufacturers manage component risk and cost volatility. The Lincoln Electric Company leverages its captive wire production and regional service density to sustain margin stability across North American fabrication shops. Fronius International anchors its position through Austrian-engineered inverter architectures and energy-efficiency leadership in pulsed MIG/MAG systems. ESAB competes via integrated digital welding management platforms that extend beyond hardware into weld-data analytics.
Arc welding equipment encompasses power sources, wire feeders, torches, and consumables engineered to join metals through controlled electrical arcs reaching temperatures above 6,500°F. Shielded Metal Arc Welding retains dominance in field construction and repair applications where portability and minimal shielding-gas logistics matter most. Flux-Cored Arc Welding is accelerating in shipyard and heavy structural fabrication, driven by deep-penetration performance and all-position operability in wind-exposed environments. Automatic Machines command premium positioning in automotive assembly lines, where repeatability tolerances below 0.1 mm justify capital intensity.
OSHA workplace exposure limits and EPA air-quality standards shape ventilation and fume-extraction requirements for domestic fabrication facilities. The EU's F-Gas Regulation and CE marking under the Machinery Directive constrain refrigerant-cooled system designs and electromagnetic compatibility thresholds for European imports. Stakeholders must monitor how NHTSA vehicle-lightweighting mandates and corresponding aluminum-intensive body architectures redirect welding-technology investment toward pulse-arc and laser-hybrid process development.
Market Dynamics
Automotive OEMs are consolidating welding automation programs in-house, compressing vendor relationships from multi-supplier networks to single-source partnerships for pulse-arc and laser-hybrid systems. This concentration is redistributing margin capture from equipment manufacturers toward captive engineering teams.
Growth Catalysts
- NHTSA vehicle-lightweighting mandates:Aluminum-intensive body architectures are redirecting capital toward pulse-arc process development in Detroit and Stuttgart manufacturing corridors.
- EU F-Gas Regulation:Refrigerant-cooled system constraints are accelerating inverter efficiency investments across Austrian and German engineering centers.
- Shipyard automation:Flux-cored arc welding demand is climbing in Korean and Japanese heavy structural fabrication exposed to wind-driven environments.
Market Restraints
- Copper and silicon steel input volatility:Transformer core materials face price swings tied to Chilean mining output and Chinese smelter capacity.
- IGBT module supply concentration:Power semiconductor sourcing clusters in Japanese and German foundries, creating single-point vulnerability for inverter manufacturers.
- CE marking electromagnetic compatibility thresholds:European Machinery Directive compliance adds six-to-nine month certification friction for non-EU equipment entrants.
Strategic Opportunities
- Indian PLI scheme for automotive:Domestic welding equipment production incentives are opening localized supply positions for MIG/MAG system assemblers.
- Weld-data analytics convergence:IoT sensor architectures are merging with quality assurance software to create recurring revenue streams beyond hardware sales.
- Brazilian offshore wind fabrication:Emerging shipyard demand for subsea joint integrity is creating specification openings for hyperbaric welding systems.
Industry Challenges
- Certified welding engineer scarcity:AWS D1.1 and EN ISO 9606-1 qualification pipelines are failing to match robotic cell deployment rates in automotive assembly plants.
- Legacy analog system integration:Digital inverter retrofits face communication protocol mismatches with 1990s-era factory automation networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Arc Welding Equipment Market |
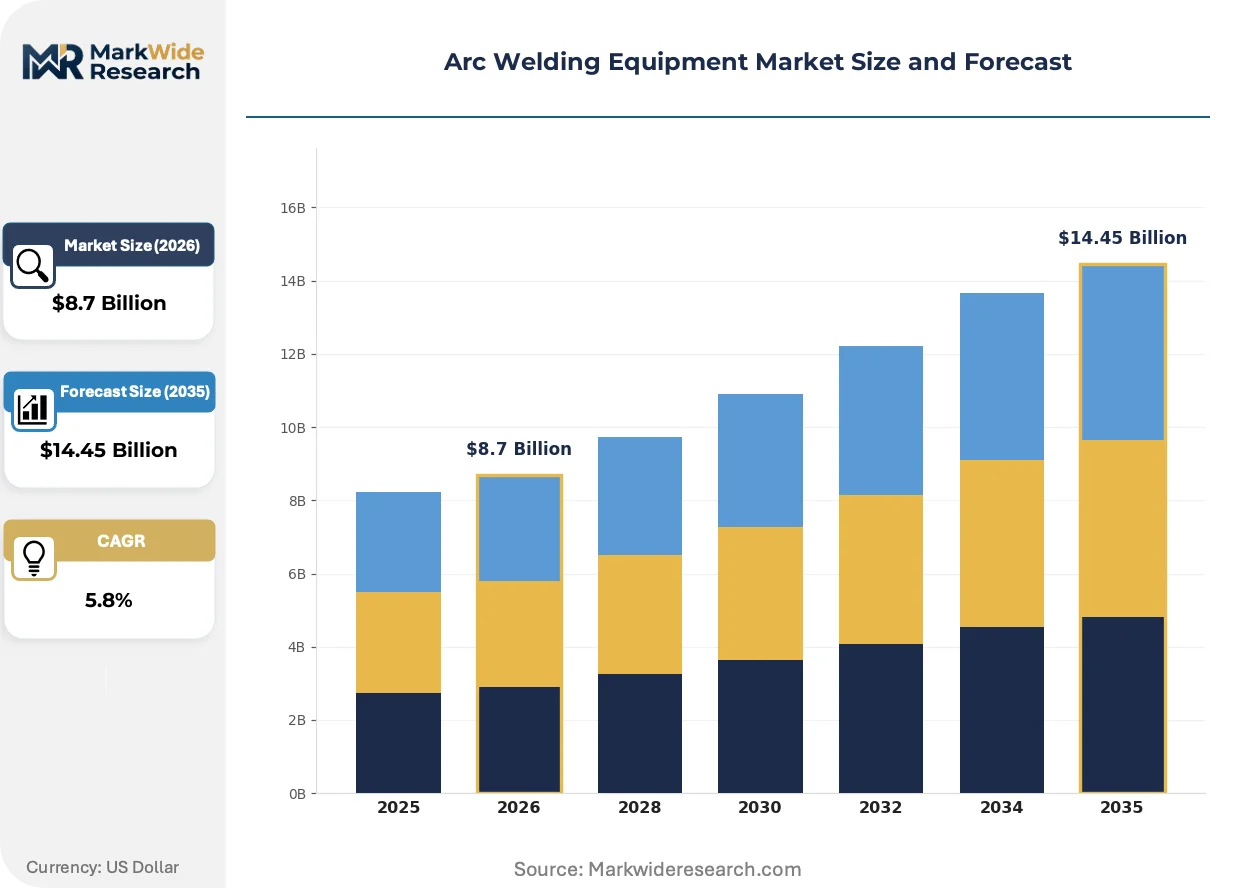
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Welding Machines, Semi-Automatic Systems, Automatic Machines, Plasma Arc Equipment Application: Aerospace Manufacturing, Automotive Assembly, Construction Works, Metal Fabrication Technology: Gas Tungsten Arc Welding, Shielded Metal Arc Welding, Submerged Arc Welding, Flux-Cored Arc Welding End User: Manufacturing Firms, Construction Companies, Automotive OEMs, Maintenance Providers |
| Companies Covered | Daihen, Kobe Steel, The Lincoln Electric Company, Jinan Huaao Electric Welding Machine, Panasonic Welding Systems, ESAB, Fronius International, OTC Daihen, Miller Electric Mfg., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Arc Welding Equipment Market Emerging Trajectories
Process control digitization and energy efficiency mandates are compressing equipment replacement cycles while elevating software-integrated platforms over standalone hardware sales.
Laser-hybrid welding is converging with conventional arc processes to enable single-pass joining of aluminum-steel dissimilar metal combinations. Automotive OEMs in Germany and Japan are piloting these cells for battery tray and closure panel production. The technology is compressing cycle times by eliminating secondary grinding operations while demanding recalibrated technician training curricula.
OSHA workplace exposure limits for manganese and hexavalent chromium are tightening ventilation requirements in US fabrication facilities. EPA air-quality enforcement in California and Texas is driving fume-extraction system retrofits among job shops with fewer than fifty welders. Smaller operators are responding through equipment leasing arrangements that bundle extraction hardware with power source rentals.
Service unbundling is fragmenting traditional equipment-plus-maintenance contracts into discrete software subscriptions, spare part marketplaces, and remote diagnostics fees. Automotive tier-one suppliers in Michigan and Bavaria are driving this decomposition to align welding costs with specific vehicle program lifecycles. The shift is most visible in high-mix, low-volume electric vehicle prototype shops where capital flexibility outweighs ownership economics.
Arc Welding Equipment Market Segmentation
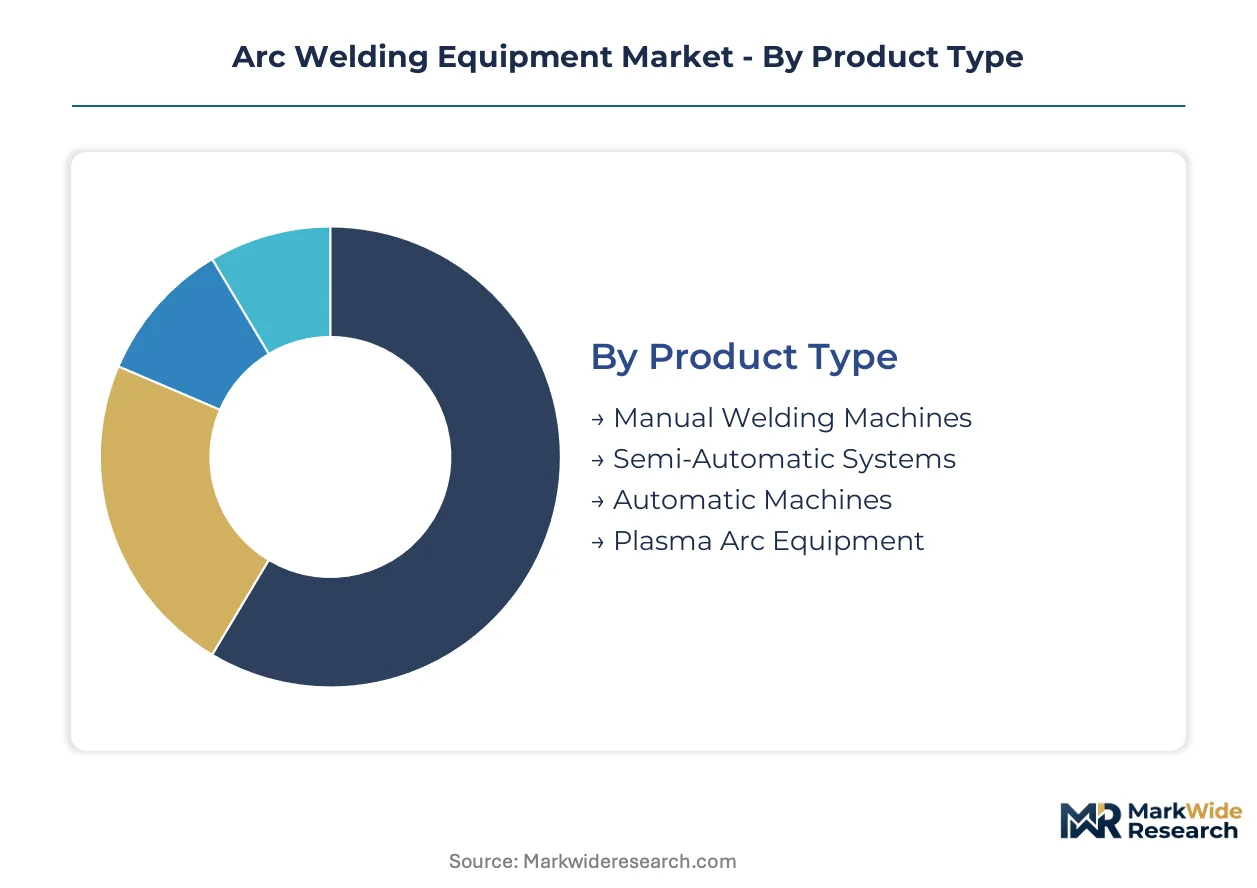
Segmentation in arc welding equipment reveals how technical specifications, automation levels, and end-use intensity create divergent margin profiles and replacement cycles across supplier portfolios. Equipment manufacturers configure R&D pipelines and service networks around these divisions rather than pursuing undifferentiated market coverage.
Product Type:
Automation intensity and operator skill requirements define the product architecture and pricing architecture across equipment categories.
- Automatic Machines:Robotic cells integrate seam-tracking sensors and adaptive arc control for automotive body-in-white lines where 0.1 mm repeatability tolerances justify seven-figure capital deployment. Demand concentrates in Stuttgart and Detroit manufacturing corridors as NHTSA lightweighting mandates accelerate aluminum-intensive platform launches.
- Semi-Automatic Systems:Wire feeder integration with programmable power sources bridges manual skill gaps in high-mix fabrication environments. Metal fabrication job shops in Texas and Ohio are standardizing on these configurations to reduce certified welder dependency amid AWS D1.1 qualification pipeline constraints.
- Manual Welding Machines:Portable inverter units dominate field construction and repair mobilization where shielding gas logistics prove impractical.
- Plasma Arc Equipment:Constricted arc precision serves aerospace alloy cutting and specialized gouging applications requiring minimal heat-affected zones.
Automatic Machines lead on scale; Semi-Automatic Systems lead on momentum.
Application:
End-use sector specifications dictate arc process selection, duty cycle requirements, and aftermarket service intensity.
- Automotive Assembly:Pulse-arc and laser-hybrid cells execute aluminum-steel dissimilar metal joining for battery tray and closure panel production. German and Japanese OEMs are piloting single-pass processes that eliminate secondary grinding operations while demanding recalibrated technician training curricula.
- Construction Works:Flux-cored and shielded metal arc systems dominate structural steel erection where wind exposure and site mobility constrain gas-shielded process adoption. Korean shipyards are automating heavy structural fabrication with all-position flux-cored systems for offshore wind subsea joint integrity.
- Aerospace Manufacturing:Gas tungsten arc precision welding of titanium and nickel superalloys requires chamber environments and x-ray inspection protocols.
- Metal Fabrication:Job shops serving industrial OEMs balance equipment flexibility against program-specific fixture investments.
Automotive Assembly commands premium positioning; Construction Works expands most quickly.
Technology:
Heat input control, shielding mechanism, and deposition rate differentiate process selection across material thickness and joint geometry requirements.
- Flux-Cored Arc Welding:Tubular wire with internal flux formulation enables deep penetration and all-position operability without external shielding gas logistics. Korean and Japanese heavy structural fabrication exposed to wind-driven environments are accelerating adoption for shipyard automation programs.
- Shielded Metal Arc Welding:Consumable electrode with extruded flux coating remains dominant in field construction and repair where portability and minimal equipment footprint matter most. EPA air-quality enforcement in California and Texas is driving fume-extraction retrofits among operators using these processes.
- Gas Tungsten Arc Welding:Non-consumable tungsten electrode delivers precision control for thin-section aerospace and instrumentation applications.
- Submerged Arc Welding:Granular flux blanket enables high-deposition longitudinal seams in pressure vessel and pipe mill production.
Shielded Metal Arc Welding retains installed base dominance; Flux-Cored Arc Welding gains share fastest.
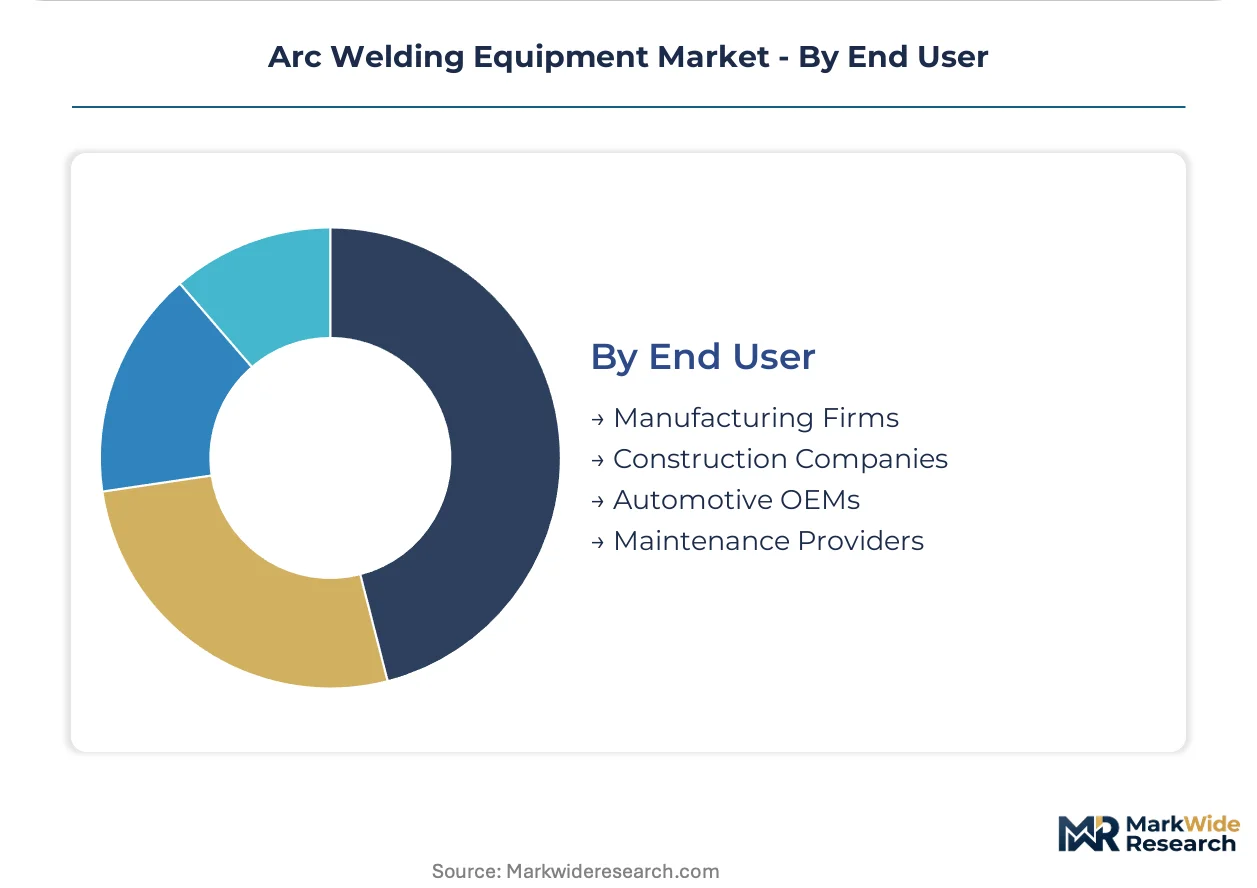
End User:
Capital deployment patterns and lifecycle cost accounting separate procurement behavior across customer categories.
- Automotive OEMs:In-house welding automation consolidation is compressing vendor relationships from multi-supplier networks to single-source partnerships for pulse-arc and laser-hybrid systems. This concentration redistributes margin capture from equipment manufacturers toward captive engineering teams in Michigan and Bavaria.
- Manufacturing Firms:Tier-one suppliers and industrial OEMs are driving service unbundling to align welding costs with specific vehicle program lifecycles through software subscriptions and remote diagnostics fees rather than traditional equipment-plus-maintenance contracts.
- Construction Companies:Project-based procurement favors equipment leasing arrangements that bundle extraction hardware with power source rentals for capital flexibility.
- Maintenance Providers:Repair and overhaul operations prioritize portable equipment interoperability across legacy and digital inverter platforms.
Automotive OEMs drive specification standards; Manufacturing Firms show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart's automotive manufacturing corridor concentrates pulse-arc and laser-hybrid welding demand as German OEMs consolidate in-house automation programs. Equipment procurement patterns diverge sharply between mature manufacturing basins and emerging fabrication centers.
Germany
Automotive body-in-white lines in Baden-Württemberg and Bavaria drive specification standards for 0.1 mm repeatability robotic cells. The EU F-Gas Regulation constrains refrigerant-cooled system designs, accelerating inverter efficiency investments across Austrian and German engineering centers. Munich and Stuttgart host concentrated pilot programs for aluminum-steel dissimilar metal joining in battery tray production.
United States
NHTSA vehicle-lightweighting mandates redirect capital toward pulse-arc process development across Michigan and Ohio manufacturing corridors. OSHA workplace exposure limits for manganese and hexavalent chromium tighten ventilation requirements in Texas and California fabrication facilities. Detroit-area tier-one suppliers are driving service unbundling into discrete software subscriptions and remote diagnostics fees.
Japan
Shipyard automation programs in Nagasaki and Yokohama accelerate flux-cored arc welding adoption for heavy structural fabrication. METI industrial efficiency standards shape power semiconductor sourcing strategies for inverter manufacturers. Kobe and Osaka anchor concentrated demand for all-position operability systems in wind-exposed offshore environments.
South Korea
Hyundai Heavy Industries and Samsung Heavy Industries drive specification openings for hyperbaric welding systems in Ulsan and Geoje shipyards. The country's national industrial regulator enforces electromagnetic compatibility thresholds that add certification friction for non-domestic equipment entrants. Busan-Ulsan corridor concentrates emerging demand for subsea joint integrity in offshore wind fabrication.
India
The PLI scheme for automotive manufacturing opens localized supply positions for MIG/MAG system assemblers in Maharashtra and Tamil Nadu. BIS certification requirements and DGFT import regulations shape equipment qualification timelines for European and Japanese manufacturers. Pune and Chennai manufacturing clusters show steepest expansion trajectory among emerging fabrication centers.
Arc Welding Equipment Market Vendor Landscape
Global majors compete with regional champions across automation intensity and service network density, producing a tiered structure where scale-driven portfolios coexist with specialized process expertise. The vendor base organizes around three strategic archetypes: integrated automation platforms, component specialists with captive wire production, and regional fabricators with dense aftermarket service. Dominant competitive moves include backward integration into power semiconductor sourcing and geographic expansion through localized assembly partnerships.
Among Japanese industrial conglomerates, Daihen and Kobe Steel exemplify the integrated automation archetype, occupying positions that span power source manufacturing through robotic system integration. The Lincoln Electric Company anchors the North American fabrication equipment tier, representing the regional champion model with concentrated service density across Midwest job shops. Fronius International sits within the European engineering-led segment, exemplifying Austrian-engineered inverter architectures and energy-efficiency positioning in pulsed MIG/MAG systems.
| Leading Market Players |
|---|
| Daihen |
| Kobe Steel |
| The Lincoln Electric Company |
| Jinan Huaao Electric Welding Machine |
| Panasonic Welding Systems |
| ESAB |
| Fronius International |
| OTC Daihen |
| Miller Electric Mfg. |
| Others |
Supply Flow & Price Mechanics
Performance divergence between CE-marked European systems and uncertified Asian imports creates a bifurcated market where aluminum-welding capability and fume-extraction bundling command 40-60% premiums, while commodity inverter units compete on copper and silicon steel input costs alone. This tier split manifests in procurement patterns: automotive OEMs in Stuttgart and Detroit negotiate single-source partnerships for pulse-arc cells, whereas Texas job shops lease portable equipment with extraction hardware bundled for capital flexibility.
Pricing Analysis
Copper and silicon steel input volatility passes through unevenly across equipment tiers, with transformer core materials facing price swings tied to Chilean mining output and Chinese smelter capacity. Three-tier pricing structure across premium CE-certified, standard industrial-grade, and economy portable levels differentiates primarily by electromagnetic compliance thresholds and arc stability specifications. Cost compression in economy inverter units is intensifying because IGBT module supply concentrates in Japanese and German foundries, creating margin pressure for non-integrated assemblers. Construction companies exhibit highest price sensitivity through project-based leasing arrangements, while automotive OEMs prioritize repeatability tolerances over unit economics.
Supply Chain Analysis
Multi-source procurement mandates from tier-one automotive suppliers require dual qualification of power semiconductor vendors, forcing inverter manufacturers to maintain relationships with both Japanese and German IGBT foundries despite concentration risks. Geographic supply concentration centers on China for wire feed assemblies, Austria and Germany for inverter architectures, and Japan for robotic integration components. Raw material dependencies span copper transformer cores, silicon steel laminations, and tungsten electrodes. Single-source vulnerability in power electronics creates exposure to foundry capacity constraints. Distribution runs through regional service networks anchored by captive parts inventories and field technician density.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where NHTSA vehicle-lightweighting mandates and EU F-Gas Regulation compliance are redirecting procurement toward pulse-arc and laser-hybrid specifications that command premium positioning and sustained replacement demand.
For Market Incumbents: Anchor market position through backward integration into power semiconductor sourcing and captive wire production, mirroring Lincoln Electric's regional service density model. Defend against emerging IoT-native competitors by accelerating weld-data analytics platform development. Certification investment in CE marking and NHTSA compliance protocols creates switching costs that protect automotive OEM relationships from Asian price competition. For New Entrants and Emerging Players: Regional distributors with dense aftermarket service networks represent the most viable channel for penetrating India's PLI-subsidized automotive manufacturing clusters in Maharashtra and Tamil Nadu. White-space targets include hyperbaric welding systems for Brazilian offshore wind fabrication and fume-extraction bundling for California EPA-enforced job shops. Equipment-as-a-service leasing models align with construction company procurement preferences for capital flexibility. For Investors and Strategic Acquirers: Consolidation pressure builds where regional champions lack software-integrated platforms to compete with ESAB's digital welding management offerings. Long-term viability favors vendors with captive component production and recurring revenue streams beyond hardware sales. Acquisition target archetype: mid-cap specialists with dense European or North American service networks and unexploited IoT sensor architectures. Signal to watch: automotive OEM in-sourcing rates for robotic cell engineering versus equipment procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Power Semiconductors | IGBT sourcing control reduces exposure to Japanese and German foundry capacity constraints. |
| Weld-Data Analytics Platform Development | IoT sensor convergence with quality assurance software creates recurring revenue beyond hardware. |
| CE Marking and F-Gas Compliance Investment | EU Machinery Directive certification opens specification access to Stuttgart automotive corridors. |
| Localized Assembly Partnerships in India | PLI scheme qualification enables participation in Maharashtra and Tamil Nadu automotive clusters. |
| Equipment-as-a-Service Leasing Models | Bundled extraction hardware rentals align with Texas and California job shop capital constraints. |
Methodological Framework
Multiple input streams — primary interviews with welding equipment procurement managers, plant engineers at automotive tier-one suppliers, and aftermarket service heads; secondary validation through SEC filings of listed manufacturers, customs trade data for copper and silicon steel imports, and EPA air-quality enforcement records — were reconciled through bottom-up equipment shipment analysis and top-down end-use demand estimation. Triangulation across stakeholder perspectives and documentary sources addressed data gaps in private company operations and regional market fragmentation.
Data-stream reconciliation anchored volume projections to automotive production schedules, shipyard automation program announcements, and construction spending indices across the analysis window. Segmentation modeling incorporated automation intensity, arc process technology, end-use sector specifications, and regional regulatory clusters. CAGRs derived from equipment replacement cycle compression, energy efficiency mandate impacts, and aluminum-intensive platform penetration rates. Industry-specific forecast inputs included NHTSA lightweighting compliance timelines and EU F-Gas Regulation implementation phases.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to copper price volatility, IGBT foundry capacity allocation, and automotive OEM in-sourcing decisions for robotic cell engineering. Deviation in NHTSA mandate enforcement intensity or EU refrigerant-cooled system restrictions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Global Cone Crusher Market
Construction Equipment
Asia-Pacific Mobile Light Tower Market
Construction Equipment
Europe Excavator and Loaders Market
Construction Equipment
High Pressure Washer Market
Construction Equipment
Construction Equipment Tire Market
Construction Equipment
Log Splitters Rental Market
Construction Equipment
Cold Planers Market
Construction Equipment
Global Hydraulic Hammer Market
Construction Equipment
Backhoes Market
Construction Equipment
Street Cleaning Machine Market
Construction Equipment
Earthing Equipment Market
Construction Equipment
India Construction Equipment Market
Construction Equipment
Plasma Cutting Machine Market
Construction Equipment
Down-The-Hole (DTH) Hammer Bits Market
Construction Equipment
Gear Shaping Machine Market
Construction Equipment
North America Mobile Crane Market