
 Boring Bar Market | 2026-2036
Boring Bar Market Size, Share, and Industry Trends Forecast 2026-2036
Boring Bar Market Outlook
Modular quick-change boring bar systems are repositioning buyer preferences toward configurable tool assemblies that reduce setup time. Sandvik Coromant leverages its modular CoroTurn platform to dominate high-volume automotive contracts. Kennametal Inc. anchors its position through carbide material science leadership in heavy-duty roughing applications. Ceratizit S.A. differentiates via specialized solid carbide bars for Swiss-type lathes.
A boring bar is a single-point cutting tool mounted on a lathe or milling machine, typically manufactured from high-speed steel, solid carbide, or carbide-tipped construction with shank diameters ranging from 6 mm to 100 mm, designed to enlarge or finish pre-drilled holes to precise tolerances. Solid boring bars command the largest volume share due to their stiffness in deep-hole applications, though hollow boring bars with through-tool coolant delivery represent the fastest-expanding configuration as manufacturers prioritize chip evacuation and thermal stability. Carbide material grades capture premium positioning in aerospace and hardened steel machining, while high-speed steel sustains cost-sensitive general engineering demand.
ISO 13399 tool data exchange standards and the EU Machinery Directive shape product interoperability requirements across European supply chains, while OSHA machine guarding regulations in the US influence bar retention and spindle interface designs. China's GB standards for cutting tool geometries affect export qualification protocols for multinational suppliers. Stakeholders must monitor how digital tool libraries and automated presetting systems redefine the competitive boundary between commodity bar suppliers and precision tooling partners.
Market Dynamics
ISO 13399 digital tool data standards and Industry 4.0 digital twin integration are compressing procurement cycles and redefining supplier qualification criteria across precision manufacturing supply chains. Automotive powertrain machining specifications now mandate seamless CAD/CAM interoperability.
Growth Catalysts
- EU Machinery Directive compliance:CE marking requirements for tool retention and spindle interface safety are accelerating replacement demand in European precision manufacturing corridors.
- Carbide material advancement:Automotive OEMs in Germany's Stuttgart-Aachen corridor are specifying carbide boring bars for high-volume powertrain machining operations.
- Through-tool coolant delivery:Hollow boring bar configurations with internal coolant channels are capturing preference in deep-hole applications requiring chip evacuation.
Market Restraints
- Tungsten carbide powder volatility:Raw material concentration in Chinese processing facilities creates input cost instability for solid carbide bar manufacturers.
- High-speed steel substitution ceiling:Cost-sensitive general engineering segments in emerging manufacturing economies sustain demand for lower-performance tooling alternatives.
- OSHA machine guarding retrofit costs:US spindle interface redesign requirements impose compliance burdens on legacy equipment operators.
Strategic Opportunities
- Swiss-type lathe specialization:Solid carbide micro-boring bars for medical device and watchmaking precision machining represent underserved application white space.
- Digital tool library integration:Cloud-based presetting data exchange with CAM software vendors creates channel innovation potential.
- China GB standard export alignment:Cutting tool geometry certification harmonization opens qualification pathways for multinational suppliers.
Industry Challenges
- CNC programming skill scarcity:Shortage of operators capable of optimizing digital twin parameters for modular quick-change systems constrains adoption velocity.
- Multi-standard certification timelines:Simultaneous ISO 13399, CE marking, and GB compliance testing extends product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Boring Bar Market |
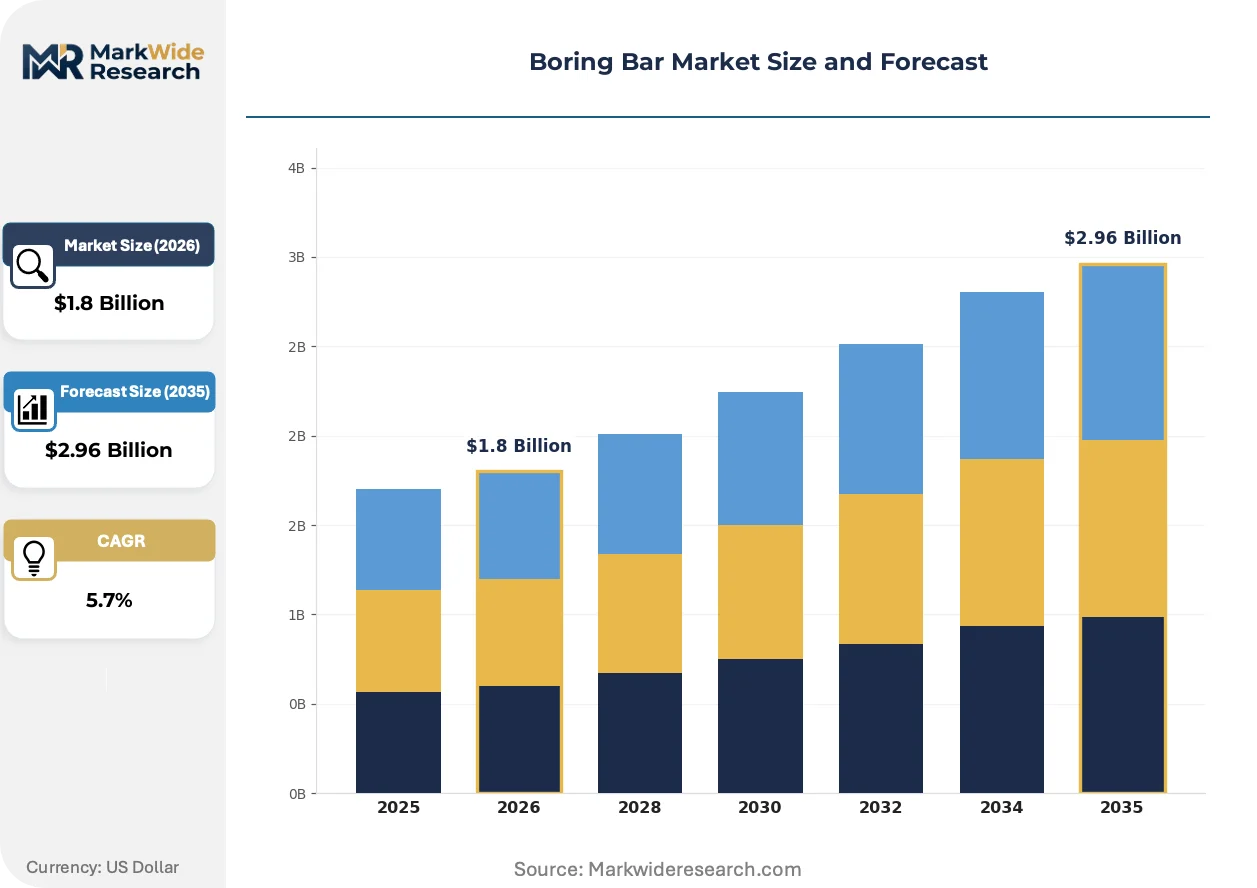
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hollow Boring Bars, Solid Boring Bars, Micro Boring Bars, Step Boring Bars Material: High-Speed Steel, Carbide, Cobalt, Ceramic Application: Aerospace, Automotive, Construction, Oil & Gas End User: Manufacturers, Engineering Firms, Machine Shops, CNC Operators |
| Companies Covered | Sandvik Coromant, Kennametal Inc., Ceratizit S.A., ISCAR Ltd., Guhring KG, BIG KAISER Precision Tooling Inc., Mitsubishi Materials Corporation, Allied Machine & Engineering Corp., Seco Tools AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Boring Bar Market Strategic Shifts
Digital thread integration from tool design through spindle interface is collapsing traditional procurement boundaries between commodity suppliers and precision partners. Three concurrent developments are restructuring competitive positioning.
Modular quick-change boring bar platforms are electrifying setup workflow optimization. Automotive tier-one suppliers in Germany are deploying configurable CoroTurn-style assemblies to compress changeover intervals. This architecture is electrifying the historical trade-off between tooling flexibility and repeatability precision.
REACH substance restriction protocols are forcing reformulation of coating chemistries for carbide boring bars. Chromium and cobalt compound limitations are compelling suppliers to qualify alternative surface treatment technologies. Aerospace machining segments in France and Italy are accelerating adoption of compliant coating systems ahead of enforcement deadlines.
Buyer concentration among automotive OEMs is compressing supplier negotiation cycles and unbundling after-sales technical support from hardware pricing. Tier-one powertrain machinists in Germany and Japan are demanding standalone digital presetting subscriptions. This pattern is most visible in Stuttgart's precision manufacturing cluster and Toyota City supplier networks.
Boring Bar Market Segmentation
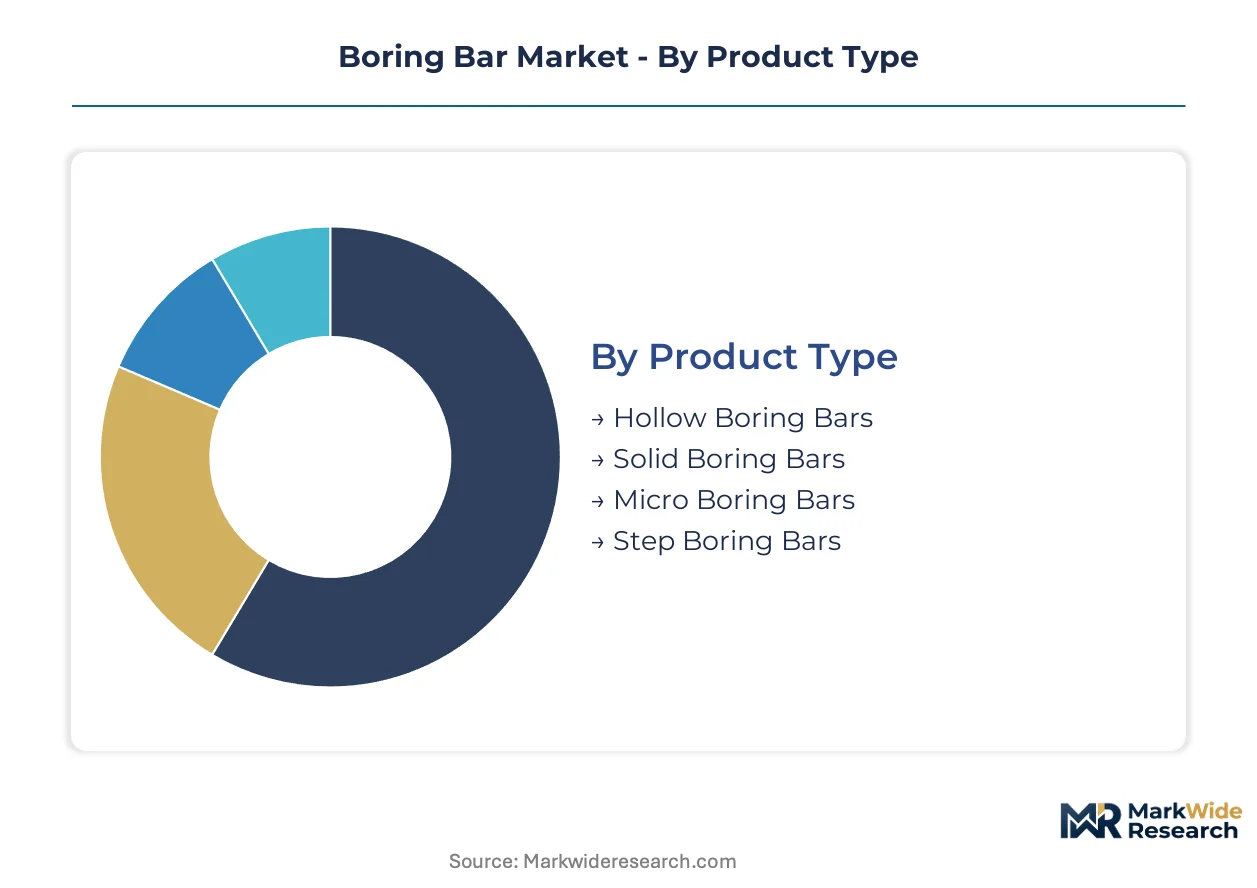
Boring bar procurement patterns diverge sharply across material grades, product architectures, and end-use precision requirements. Understanding these fault lines exposes where specification power concentrates and where substitution risks emerge.
Product Type:
Machine setup complexity and hole depth specifications drive buyer selection between rigid and coolant-through configurations.
- Hollow Boring Bars:Internal coolant channels enable through-tool delivery for chip evacuation in deep-hole applications. Demand clusters in automotive powertrain machining across Germany's Stuttgart-Aachen corridor where thermal stability mandates coolant integration.
- Solid Boring Bars:Monolithic construction delivers maximum stiffness for precision finishing operations. Aerospace OEMs in France specify solid carbide variants for tight-tolerance turbine component machining where deflection control outweighs coolant access.
- Micro Boring Bars:Swiss-type lathe operators in medical device manufacturing favor sub-6mm diameters for miniature component finishing.
- Step Boring Bars:Multi-diameter configurations reduce tool change frequency in high-volume construction equipment manufacturing.
Solid boring bars lead on scale; hollow boring bars lead on momentum.
Material:
Cost-per-cut economics and workpiece hardness determine material specification authority in buyer organizations.
- Carbide:Tungsten-carbide substrates dominate hardened steel machining above 45 HRC. German automotive tier-one suppliers mandate carbide grades for crankshaft and camshaft boring cycles.
- High-Speed Steel:M2 and M42 grades retain cost advantage in general engineering applications below 35 HRC. Machine shops in India specify HSS for prototype work where tool change frequency remains low.
- Cobalt:Enhanced red-hardness suits interrupted cuts in oil & gas valve body machining.
- Ceramic:Silicon nitride and whisker-reinforced alumina enable dry machining of cast iron at elevated speeds.
Carbide commands specification authority; ceramic climbs the fastest on thermal performance demands.
Application:
Precision tolerance bands and production volume requirements segment demand across discrete manufacturing verticals.
- Automotive:Powertrain machining specifications mandate ISO 13399-compliant digital tool data for CAM integration. OEMs in Japan's Toyota City supplier network require presetting data exchange compatibility.
- Aerospace:Titanium and nickel-alloy machining drives demand for vibration-damping bar geometries. French and Italian machining centers specify anti-vibration bars for wing spar finishing.
- Construction:Earthmoving equipment cylinder boring tolerates looser precision in favor of material removal rates.
- Oil & Gas:Downhole tool manufacturing requires corrosion-resistant coatings for sour service environments.
Automotive anchors volume concentration; aerospace shows steepest expansion trajectory on material advancement.
End User:
Technical capability depth and capital equipment sophistication determine service model expectations from tooling suppliers.
- Manufacturers:Captive machining operations with dedicated tooling engineers specify modular quick-change platforms. German automotive OEMs negotiate enterprise pricing for CoroTurn-style configurable assemblies.
- Machine Shops:Job-shop environments prioritize tool flexibility across mixed part portfolios. Independent operators in the US Midwest favor standard shank geometries for spindle compatibility.
- Engineering Firms:Prototype-to-production transitions drive rental and trial programs for unproven applications.
- CNC Operators:Programming skill scarcity constrains adoption of digital twin-integrated presetting systems in smaller operations.
Manufacturers lead on procurement scale; machine shops lead on supplier switching frequency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered precision metal-cutting tool standardization in the early twentieth century. Stuttgart's automotive machining corridors and Aachen's research institutes established the technical foundations that shaped boring bar specifications worldwide. This heritage continues to concentrate demand in specific manufacturing clusters across five key countries.
Germany
Automotive powertrain machining specifications from BMW, Mercedes-Benz, and Volkswagen mandate carbide boring bars with ISO 13399 digital tool data compatibility. REACH substance restrictions on cobalt and chromium compounds force coating chemistry reformulation ahead of enforcement deadlines. Stuttgart-Aachen precision manufacturing corridors anchor European demand for modular quick-change systems.
United States
Aerospace OEMs in Seattle and Wichita specify anti-vibration boring bars for titanium wing spar finishing operations. OSHA machine guarding regulations impose spindle interface redesign requirements that accelerate replacement cycles in legacy machining centers. Midwest job-shop concentrations in Illinois and Ohio favor standard shank geometries for spindle compatibility across mixed part portfolios.
China
Domestic electric vehicle manufacturers in Shanghai and Shenzhen are scaling captive machining operations for motor housing production. GB standards for cutting tool geometries affect export qualification protocols for multinational suppliers seeking market access. Yangtze River Delta machine tool builders integrate through-tool coolant delivery as standard configuration.
Japan
Toyota City supplier networks require presetting data exchange compatibility with CAM software for just-in-time powertrain machining. METI industrial standards promote digital twin integration across precision manufacturing supply chains. Nagoya-area machining centers specify vibration-damping bar geometries for nickel-alloy component finishing.
India
Cost-sensitive general engineering segments in Pune and Chennai sustain demand for high-speed steel alternatives below 35 HRC applications. BIS certification requirements for imported cutting tools create qualification barriers for uncertified suppliers. Gujarat automotive component clusters are transitioning toward carbide grades for crankshaft machining cycles.
Boring Bar Market Competitive Environment
Premium-margin players sit above commodity-margin players across material science depth and digital integration capability. Sandvik Coromant leverages modular platform architectures to dominate high-volume automotive contracts, while Kennametal anchors heavy-duty roughing segments through carbide substrate leadership. Three strategic archetypes define competitive positioning: integrated material-science specialists, modular system architects, and regional cost-optimized fabricators. Capacity expansion in Chinese tungsten processing and strategic partnerships for CAM software integration represent the dominant competitive moves reshaping supplier hierarchies.
Within the integrated specialist tier, Sandvik Coromant and Kennametal exemplify divergent positioning strategies—Sandvik through configurable quick-change platforms, Kennametal through substrate formulation depth. Ceratizit S.A. occupies a distinct position serving Swiss-type lathe precision machining segments. Among Japanese-headquartered material companies, Mitsubishi Materials Corporation represents scale-driven vertical integration into carbide powder production. These three anchors demonstrate how geographic origin and corporate structure correlate with archetype selection: Swedish-American conglomerates favor modular architectures, American specialists emphasize material science, European S.A. structures target niche precision segments, and Japanese corporations pursue captive raw material control.
| Leading Market Players |
|---|
| Sandvik Coromant |
| Kennametal Inc. |
| Ceratizit S.A. |
| ISCAR Ltd. |
| Guhring KG |
| BIG KAISER Precision Tooling Inc. |
| Mitsubishi Materials Corporation |
| Allied Machine & Engineering Corp. |
| Seco Tools AB |
| Others |
Value Chain & Pricing Dynamics
CNC programming specialists concentrated in Germany's Stuttgart-Aachen corridor command wage premiums that compress margin structures for precision boring bar suppliers serving automotive tier-one contracts. Labor-cost differentials between Western European tooling engineers and emerging-market machine shop operators sustain three-tier pricing spreads across premium carbide grades, standard HSS alternatives, and economy-tier imports.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ISO 13399-certified modular systems from conventional solid bars and unbranded imports. Price differentiation hinges on CE marking compliance and digital twin integration depth. Cost compression in the economy tier intensifies as Indian and Chinese fabricators scale tungsten carbide processing. Automotive OEM procurement teams show least price sensitivity; independent Midwest job shops exhibit highest elasticity.
Supply Chain Analysis
Domestic-content mandates in China's electric vehicle sector and India's PLI scheme for automotive components are reshaping sourcing patterns for multinational boring bar suppliers. Raw material supply concentrates in Chinese tungsten powder processing, German precision grinding equipment, and Japanese carbide substrate formulations. The chain draws from cobalt and chromium compounds subject to REACH restriction timelines. Single-source vulnerability runs through Yangtze River Delta tungsten concentrate refining. Distribution runs through authorized distributor networks serving captive OEM machining operations and independent job-shop channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The boring bar market functions as a geographic-arbitrage play where REACH compliance costs in Europe create 15-20% cost disadvantages against emerging-market competitors, while ISO 13399 digital certification requirements erect offsetting technical barriers to import substitution.
For Market Incumbents: Extend modular platform architectures into cloud-based presetting subscription services to capture recurring revenue streams. Defend against Chinese carbide processors by deepening captive tungsten powder supply through backward integration into recycling operations. ISO 13399 certification investment remains the critical lever for locking in automotive OEM enterprise contracts. For New Entrants and Emerging Players: Digital tool library integration with CAM software vendors offers a technology-first wedge into underserved Swiss-type lathe segments. Medical device micro-boring applications in Switzerland and Japan present the most penetrable white space. Lead with trial-based rental programs targeting engineering firms in prototype-to-production transitions. For Investors and Strategic Acquirers: Valuations sit cheapest among regional cost-optimized fabricators lacking digital integration capability but holding established distributor relationships. Five-to-ten-year viability favors specialists with captive carbide material science and automotive qualification track records. Watch for inflection signals in METI or EU Machinery Directive enforcement tightening that would accelerate replacement demand cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tungsten Recycling | Secures carbide powder supply against Chinese concentrate volatility and REACH cobalt restrictions. |
| ISO 13399 Digital Twin Certification | Unlocks automotive OEM procurement gates in Germany's Stuttgart-Aachen manufacturing corridor. |
| Swiss-Type Lathe Micro-Bar Specialization | Captures medical device precision machining demand with limited incumbent competition. |
| Cloud-Based Presetting Subscription Launch | Separates software revenue from hardware pricing in Toyota City supplier networks. |
| GB Standard Export Alignment | Opens qualification pathways for Shanghai and Shenzhen electric vehicle machining operations. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged carbide materials scientists at German automotive tier-one suppliers, CNC programming leads in Stuttgart and Aachen machining centers, procurement managers at Japanese powertrain specialists, and aftermarket distribution heads in the US Midwest. Secondary validation drew from SEC filings of listed tooling manufacturers, German mechanical engineering association (VDMA) output statistics, Japanese machine tool order data, and EU REACH substance restriction enforcement notices. Bottom-up segment sizing triangulated against top-down industry value-chain estimates.
Segment-weighting approaches applied differential growth assumptions across material grades, product architectures, and end-use verticals throughout the forecast period. The analytical framework modeled carbide versus HSS substitution elasticities, hollow versus solid bar adoption curves, and automotive versus aerospace demand divergence. CAGRs derived from regression analysis against machine tool investment cycles and powertrain production volume projections. Industry-specific inputs included tungsten carbide powder price indices and ISO 13399 adoption rates across CAM software platforms.
The model holds under stable regulatory enforcement timelines and continued automotive powertrain machining demand; deviation in REACH substance restriction acceleration or electric vehicle platform standardization would shift material grade mix assumptions. Forecasts reflect documented base-case assumptions regarding tungsten supply concentration and digital tool data interoperability progress. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Self-Driving Dumpers Machine Market
Construction Equipment
Fogging Machine Market
Construction Equipment
Down-The-Hole (DTH) Hammer Bits Market
Construction Equipment
Construction Power Rental Market
Construction Equipment
Stud Welding Machine Market
Construction Equipment
US Welding Consumables Market
Construction Equipment
Autonomous Cranes Market
Construction Equipment
Global Excavators Market
Construction Equipment
Fixed Crane Market
Construction Equipment
Rotary Blasthole Drilling Rig Market
Construction Equipment
Solar Pile Driving Equipment Market
Construction Equipment
Portable Chamfering Machines Market
Construction Equipment
Compact Power Equipment Rental Market
Construction Equipment
Turkey Construction Equipment Market
Construction Equipment
Europe Used Construction Machinery Market
Construction Equipment
Commercial Sanitizing Equipment Market