
 Australia and New Zealand Industrial Fasteners Market | 2026-2036
Australia and New Zealand Industrial Fasteners Market Size, Share, and Industry Trends Forecast 2026-2036
Australia and New Zealand Industrial Fasteners Market Intelligence
Local manufacturing capacity in Australia for specialized, high-specification fasteners is shifting due to intense price competition from large-scale Asian imports. Specialist firms like Prendergast Fasteners PTY Ltd. leverage custom fabrication capabilities to serve niche mining and defense applications. Allthread Industries sustains its market position through a dedicated focus on construction and engineering-grade threaded rods and anchor bolts. Meanwhile, a major distributor like ITW Proline differentiates with its broad channel access and branded product portfolio across both countries.
Australia and New Zealand industrial fasteners are mechanical devices designed to create non-permanent joints, manufactured to precise tolerances under standards like ISO 9001. These components, often made from high-tensile carbon steel or corrosion-resistant 316 stainless steel, must withstand specific shear and tensile loads in demanding industrial settings. Standard bolts and screws constitute the largest product volume, driven by the high-volume needs of the construction end-user segment. Higher-margin opportunities are found in stainless steel and other specialized alloy fasteners required by the region's marine, food processing, and chemical industries.
Product compliance is primarily governed by Standards Australia, which sets material, dimensional, and performance benchmarks for fasteners used in critical applications like structural steelwork. In New Zealand, the Building Code provides the legal framework, referencing specific standards to ensure fasteners meet durability and safety requirements. These regulations create a quality floor that can protect local manufacturers against some sub-standard imports. Navigating the dual pressures of import competition and evolving local compliance standards remains the central strategic challenge for all market participants.
Market Dynamics
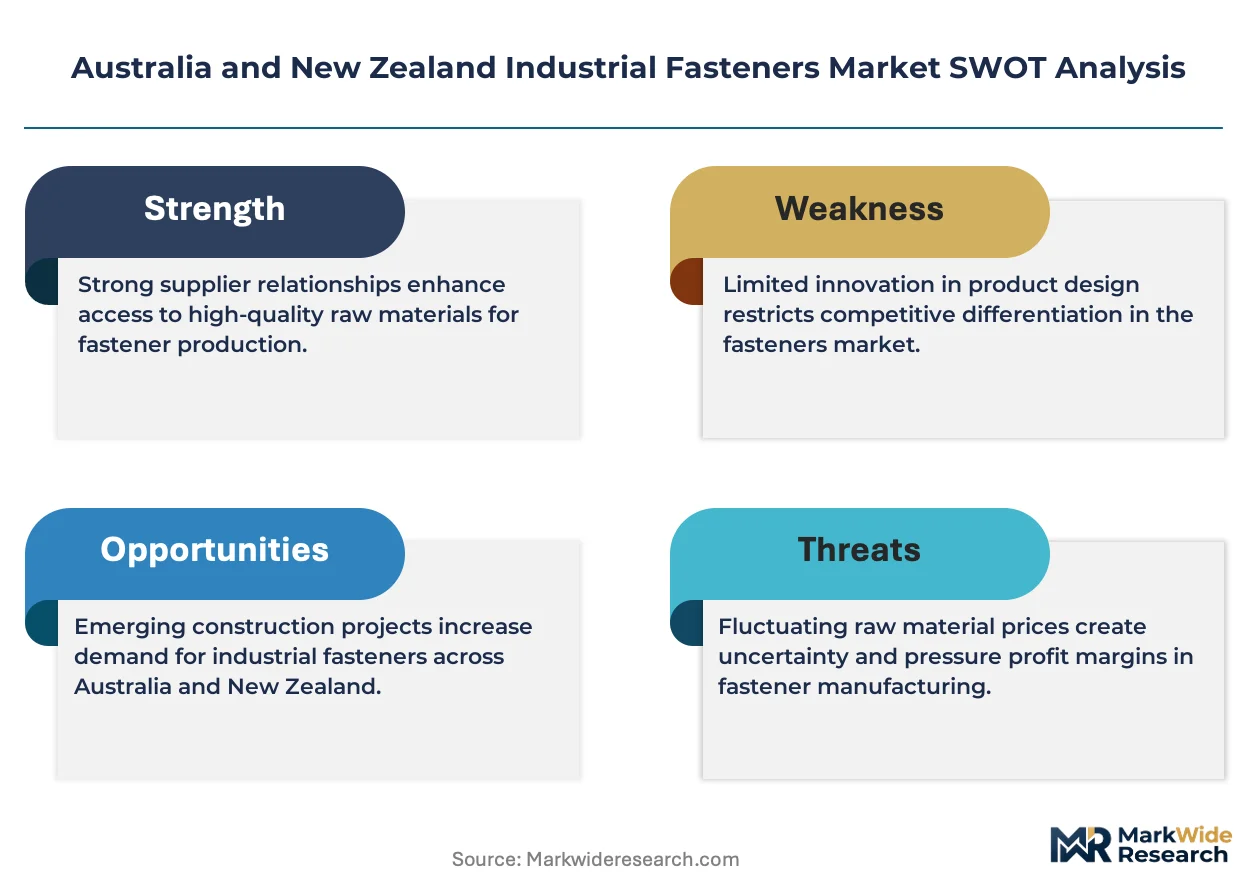
The central structural force shaping the market is the competitive friction between low-cost Asian imports and the value proposition of locally-made, standards-compliant fasteners. This dynamic is driven by stringent performance requirements from Australia and New Zealand's critical infrastructure and mining sectors.
Growth Catalysts
- Infrastructure Investment:Government-backed public works and transport projects, particularly in Western Australia, create sustained demand for high-tensile structural bolts and specialized anchoring systems that meet regional engineering specifications.
- Regulatory Mandates:Strict adherence to Australian Standards like AS 1252 for structural bolting assemblies creates a quality floor, favoring suppliers who can demonstrate full compliance and traceability against lower-quality imports.
- Renewable Energy Projects:The construction of wind and solar farms across both countries requires large volumes of specialized, corrosion-resistant fasteners designed to withstand long-term exposure in harsh outdoor environments.
Market Restraints
- Input Cost Volatility:Fluctuations in the price of high-grade carbon steel and 316 stainless steel, the primary raw materials, directly impact the cost structure of local manufacturers, making it difficult to compete on price with large-scale Asian producers.
- Import Dependence:The market's reliance on Asia for the supply of standard, high-volume fasteners creates vulnerability to shipping delays, geopolitical tensions, and currency fluctuations, impacting overall supply chain stability.
- Threat of Substitution:In certain non-critical building and manufacturing applications, the performance of structural adhesives and advanced welding techniques presents a viable alternative to mechanical fasteners, capping demand in some segments.
Strategic Opportunities
- Niche Sector Specialization:There is an opportunity to supply high-specification, custom-fabricated fasteners for Australia's growing defense, aerospace, and advanced manufacturing sectors, which prioritize performance and traceability over cost.
- Advanced Material Adoption:Developing and distributing fasteners made from specialized alloys, superalloys, or polymer composites can open high-margin opportunities in corrosive marine and chemical processing environments, especially around coastal industrial zones.
- Digital Integration:Offering digital services such as Building Information Modeling (BIM) object libraries for fastener products allows suppliers to integrate earlier into the design and specification process for major construction projects.
Industry Challenges
- Skilled Labor Shortages:A persistent lack of skilled machinists, toolmakers, and quality assurance technicians in Australia constrains the capacity of local firms to expand custom fabrication and high-tolerance manufacturing operations.
- Compliance Burden:Navigating and maintaining certification for the evolving set of material and performance benchmarks under Standards Australia and the New Zealand Building Code requires significant and continuous investment.
- Logistical Complexity:Managing inventory and ensuring timely delivery across the vast geography of Australia and between the two nations presents a significant logistical challenge, adding cost and complexity for distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia and New Zealand Industrial Fasteners Market |
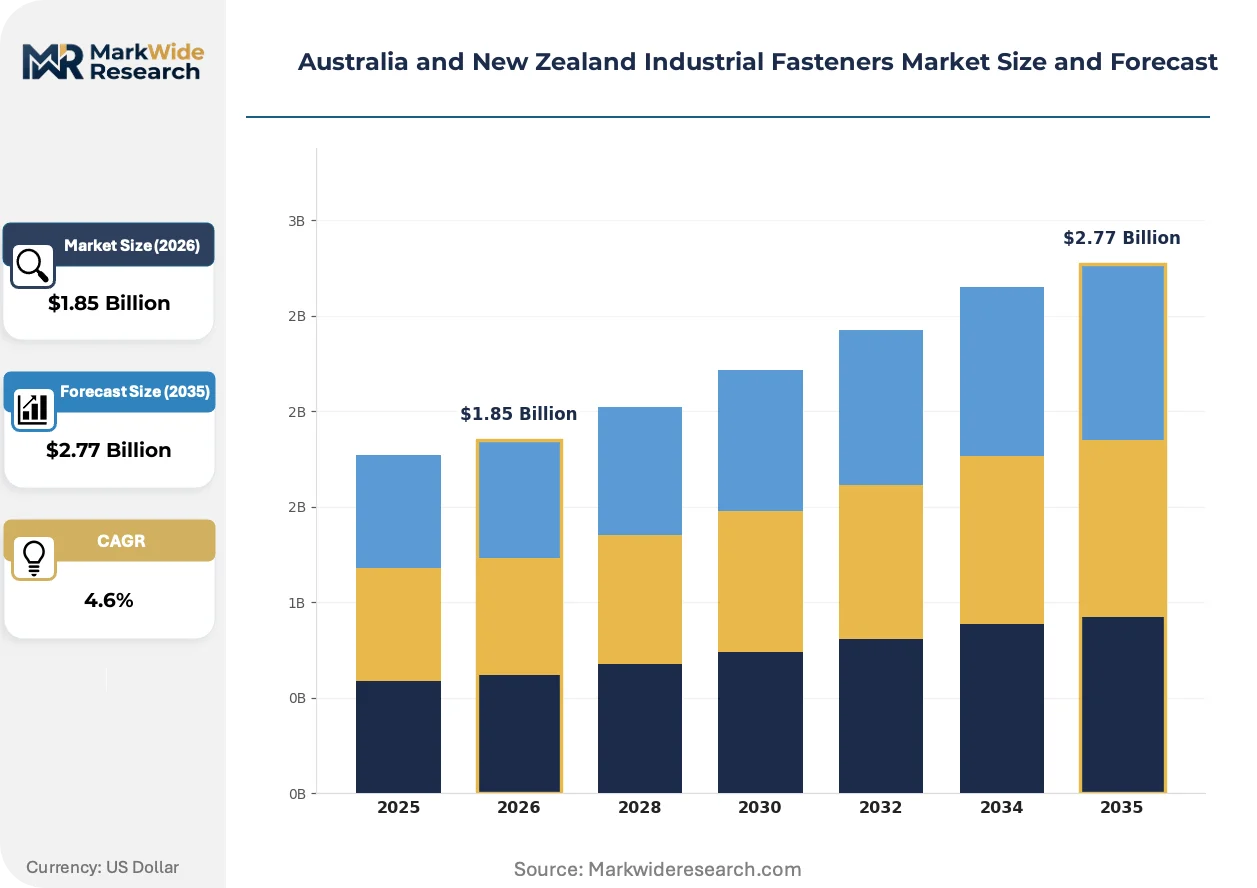
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.77 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bolts, Nuts, Screws, Rivets Material: Steel, Stainless Steel, Plastic, Aluminum End User: Construction, Automotive, Aerospace, Electronics Distribution Channel: Direct Sales, Retail, E-commerce, Wholesalers |
| Companies Covered | Prendergast Fasteners PTY Ltd., Allthread Industries, EJOT, CMI Fasteners Ltd., South Australian Fasteners Engineers PTY Ltd., Australian Fasteners, ITW Proline, ARP Fasteners, Bolts and Nuts Fasteners Pty Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia and New Zealand Industrial Fasteners Market Strategic Shifts & Innovations
Product innovation and supply chain strategy in the Australia and New Zealand fastener market are adapting to simultaneous pressures. These include the need for proven performance in harsh environments and the economic reality of globalized supply chains.
Additive manufacturing, particularly selective laser melting for metal alloys, enables rapid prototyping and small-batch production of custom fasteners. Niche adopters in Australian mining and defense are using this for non-standard repair components and specialized fixtures. This capability is decentralizing the creation of unique parts, reducing dependence on overseas custom fabrication for low-volume, high-urgency needs.
Heightened scrutiny under Standards Australia frameworks, especially for structural bolts in commercial and public infrastructure, is compelling a market-wide focus on compliance. The direct consequence is an increased burden of proof on all suppliers, requiring robust testing and documentation for imported and local products alike. Construction contractors in Sydney and Melbourne are leading this shift, demanding full traceability records.
Consolidation of suppliers is a defining behavioral shift among major end-users in construction and resources. Large contractors are streamlining their procurement by partnering with fewer full-service distributors who manage inventory and provide technical support. This trend is particularly evident in Western Australia’s mining sector and for infrastructure projects in Auckland.
Australia and New Zealand Industrial Fasteners Market Segmentation
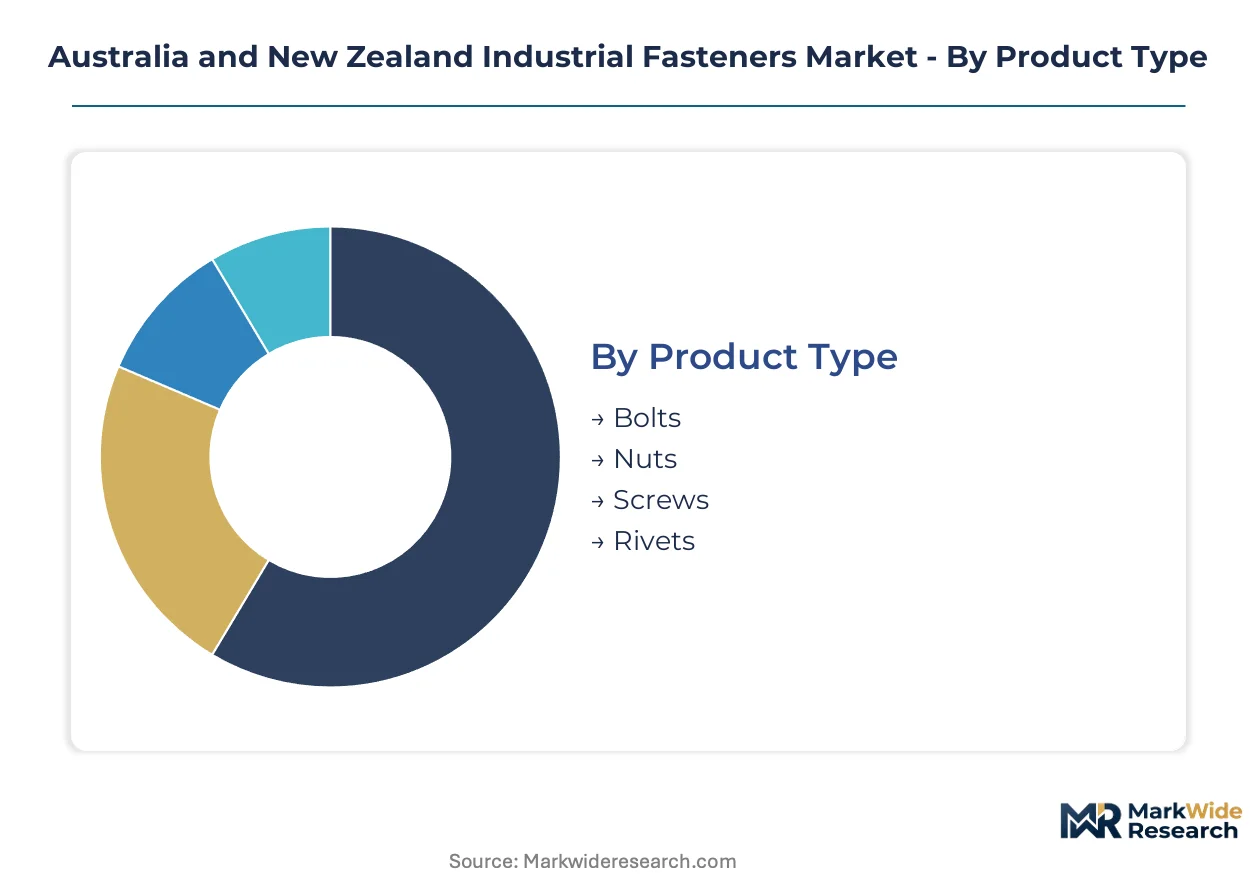
The Australia and New Zealand industrial fasteners market is categorized to reveal distinct demand patterns and supply chain dynamics across various product types, materials, end-user applications, and distribution channels. This granular segmentation helps in understanding where value is created and how competitive forces manifest within the region.
Product Type:
Supply concentration heavily influences the product type landscape, with standard fasteners dominating volume but specialized components offering higher margins. Manufacturers and distributors often focus on specific product categories to leverage economies of scale or cater to niche requirements.
- Bolts:These mechanical fasteners create non-permanent joints, often featuring external threads and requiring a nut for assembly. High-tensile bolts meeting Australian Standards like AS 1252 are critical for large-scale infrastructure projects in Western Australia and commercial building developments in Auckland.
- Screws:Characterized by helical ridges, screws are driven into materials to form their own threads or mate with pre-tapped holes. Construction activities in Sydney and Melbourne drive high-volume demand for various screw types in both structural and non-structural applications.
- Nuts:Internally threaded fasteners designed to mate with bolts, providing clamping force. They are essential companions to bolts across all industrial applications.
- Rivets:Permanent mechanical fasteners used to join two or more plates or sheets of material. They find applications in aerospace and certain manufacturing sectors.
Bolts absorb the bulk of installed capacity; screws are expanding most quickly.
Material:
Cost tiering distinguishes the materials used in industrial fasteners, reflecting performance requirements against raw material price volatility. Material choice directly impacts durability, strength, and suitability for specific environments within the region.
- Steel:This category encompasses various grades of carbon steel, known for its high strength and cost-effectiveness. High-tensile carbon steel fasteners are the backbone of the construction and mining sectors across Australia and New Zealand due to their load-bearing capabilities.
- Stainless Steel:Valued for superior corrosion resistance, particularly grades like 316, making it suitable for harsh environments. Demand for stainless steel fasteners is concentrated in the region's marine, food processing, and chemical industries, especially along coastal areas.
- Plastic:Lightweight and corrosion-resistant, plastic fasteners are used in applications where electrical insulation or non-conductivity is required. They are commonly found in electronics and light assembly.
- Aluminum:Offers a high strength-to-weight ratio and good corrosion resistance, making it suitable for aerospace and lightweight structural applications.
Material selection is largely dictated by application environment and specific performance requirements.
End User:
Application diversity drives demand across various end-user segments, each with unique fastener specifications and procurement patterns. The industrial landscape of Australia and New Zealand influences the relative importance of each sector.
- Construction:This segment includes residential, commercial, and infrastructure projects, requiring a vast array of standard and high-specification fasteners. Government-backed public works and transport projects in Western Australia create sustained demand for specialized anchoring systems and structural bolts.
- Automotive:Fasteners are integral to vehicle assembly, maintenance, and repair, demanding high precision and reliability. Local automotive aftermarket and repair services in both countries rely on a consistent supply of standard and specialized fasteners.
- Aerospace:Requires extremely high-performance, lightweight, and traceable fasteners for critical structural and assembly applications. Niche defense and specialized manufacturing in Australia are key consumers.
- Electronics:Utilizes small, precise fasteners for assembly of electronic components and devices. This segment often demands non-conductive or miniature fasteners.
The construction sector remains the dominant end-user, absorbing the largest volume of industrial fasteners.
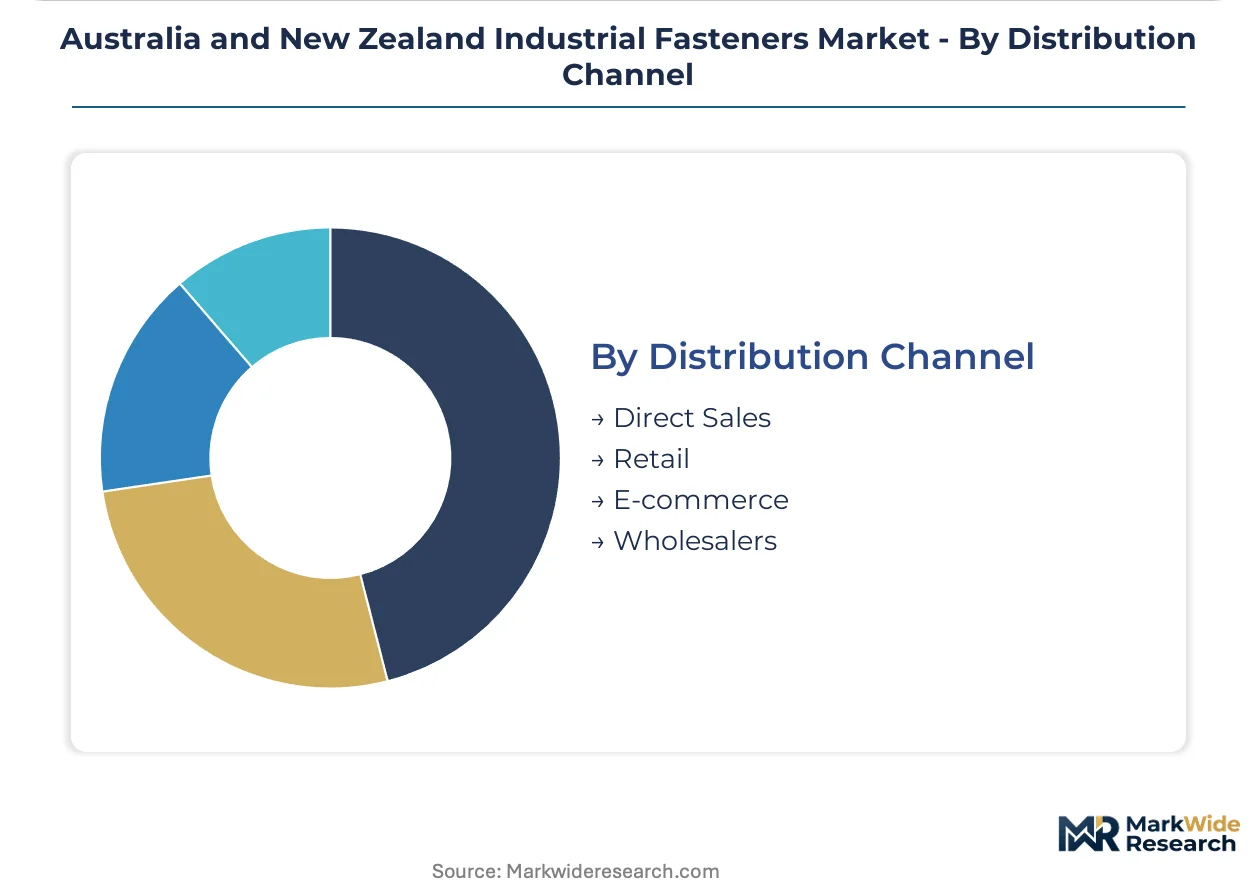
Distribution Channel:
Customer type heavily influences the chosen distribution channels, ranging from direct engagement for large industrial clients to retail for smaller-scale purchases. The vast geography of Australia and New Zealand shapes logistical strategies for distributors.
- Direct Sales:Involves manufacturers selling directly to large industrial clients, original equipment manufacturers (OEMs), or major project contractors. This channel is crucial for supplying custom-fabricated or high-specification fasteners for mining and defense applications.
- Wholesalers:These intermediaries purchase in bulk from manufacturers and distribute to smaller businesses, retailers, and contractors. Wholesalers play a critical role in inventory management and timely delivery across the dispersed regions of Australia and New Zealand.
- Retail:Caters to smaller businesses, tradespeople, and individual consumers through hardware stores and specialized fastener outlets. This channel focuses on convenience and accessibility for common fastener types.
- E-commerce:Online platforms provide a broad reach and convenience for purchasing various fasteners, particularly for standard products and smaller orders. This channel is gaining traction for its efficiency and competitive pricing.
Traditional wholesale channels continue to move the highest volumes, while direct sales cater to high-value, specialized projects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia's significant iron ore and other mineral resources underpin the region's industrial fastener market, providing essential raw materials for steel production. Demand for fasteners across Australia and New Zealand stems from robust infrastructure development and a growing construction sector. Stringent material specifications and performance requirements shape product selection.
Western Australia
Western Australia's extensive mining operations and government-backed public works projects create substantial demand for high-tensile structural bolts. Adherence to Australian Standards (AS) for structural integrity ensures quality in these critical applications. Major infrastructure projects in Perth and regional mining hubs drive sustained procurement of specialized anchoring systems.
New South Wales
New South Wales experiences strong demand for various screws and bolts from its large construction sector, encompassing both commercial and residential building. Standards Australia frameworks mandate specific performance benchmarks for fasteners used in structural steelwork. Construction contractors in Sydney lead the shift towards demanding full traceability records for all fastener components.
Victoria
Victoria's commercial building developments and transport infrastructure upgrades require significant volumes of standard and specialized fasteners. The state's building regulations, referencing Australian Standards, ensure fasteners meet durability and safety requirements. Melbourne's expanding urban landscape and public transport projects generate consistent demand for compliant fastening solutions.
Auckland
Auckland's commercial building developments and infrastructure projects are key demand drivers for industrial fasteners in New Zealand. The New Zealand Building Code provides the legal framework, referencing specific standards for fastener performance. Major infrastructure projects in Auckland are consolidating procurement by partnering with fewer full-service distributors.
Christchurch
Christchurch's ongoing reconstruction efforts and new commercial developments sustain demand for a diverse range of fasteners. Compliance with the New Zealand Building Code is paramount, ensuring all components meet required safety and durability criteria. Commercial building developments in Christchurch contribute to the regional demand for high-tensile fasteners.
Australia and New Zealand Industrial Fasteners Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue specialized, high-specification fastener solutions. The market exhibits a tiered structure, from high-volume standard product suppliers to niche custom fabricators. Three strategic archetypes define the competitive landscape: large distributors with broad portfolios, specialized manufacturers focusing on high-performance applications, and commodity suppliers competing on price. Companies primarily engage in portfolio diversification and strategic partnerships to strengthen their market positions.
Specialists in custom fabrication and high-specification fasteners include Prendergast Fasteners PTY Ltd., leveraging unique capabilities for niche mining and defense applications. Allthread Industries exemplifies a manufacturer focused on construction and engineering-grade threaded rods and anchor bolts, sustaining its market position through product specialization. Meanwhile, ITW Proline, a major distributor, anchors its position with extensive channel access and a branded product portfolio across both Australia and New Zealand.
| Leading Market Players |
|---|
| Prendergast Fasteners PTY Ltd. |
| Allthread Industries |
| EJOT |
| CMI Fasteners Ltd. |
| South Australian Fasteners Engineers PTY Ltd. |
| Australian Fasteners |
| ITW Proline |
| ARP Fasteners |
| Bolts and Nuts Fasteners Pty Ltd. |
| Others |
Cost & Logistics Intelligence
A clear divergence exists between the commodity pricing of standard fasteners from Asian imports and the premium commanded by specialized, standards-compliant fasteners. This bifurcation influences both pricing models and supply chain structures across Australia and New Zealand.
Pricing Analysis
Warranty and technical service bundling differentiates pricing for specialized fasteners, contrasting with the unbundled, transactional pricing of commodity imports. Project-based and transactional pricing structures dominate, with price differentiation driven by certification levels like AS 1252 compliance and after-sales support. Pricing pressure stems from intense competition from high-volume Asian producers. Construction contractors for standard items are highly price-sensitive, while defense and aerospace prioritize performance and traceability over cost.
Supply Chain Analysis
Regional distribution centers and wholesaler networks form the backbone of fastener supply across Australia and New Zealand, managing inventory for dispersed end-users. The supply chain draws heavily from Asia for standard, high-volume products, while specialized fasteners are sourced locally. Raw material dependencies include high-grade carbon steel and 316 stainless steel. Import dependence creates vulnerability to shipping delays and geopolitical tensions, impacting supply stability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Australia and New Zealand industrial fasteners market is fundamentally a cost-of-compliance story, where adherence to Australian Standards like AS 1252 establishes a critical barrier-to-entry. This regulatory moat favors local manufacturers and compliant importers, protecting against sub-standard products.
For Market Incumbents: Acquire specialized manufacturing capabilities to counter intense price competition from Asian imports. Invest in advanced materials R&D for corrosive marine and chemical processing environments, diversifying beyond steel. Strengthen channel control by offering comprehensive technical support and inventory management services to major contractors. This strategy mitigates the threat of substitution from adhesives and advanced welding techniques.
For New Entrants and Emerging Players: Channel partners, particularly full-service distributors, offer new entrants a pathway to market penetration by leveraging existing logistics networks. Target niche applications in defense and aerospace requiring high-specification, custom-fabricated fasteners where performance outweighs cost. Develop digital services like BIM object libraries to integrate into major construction projects earlier in the design and specification process. This approach bypasses direct competition with high-volume standard product suppliers.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized manufacturers and custom fabricators given the increasing demand for high-specification, compliant fasteners. The long-term viability of the market is anchored by sustained infrastructure investment and stringent regulatory mandates. Target firms with proprietary technology in advanced materials or established custom fabrication capabilities for defense and mining. The signal to watch is the continued consolidation of procurement by major end-users, favoring integrated suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Niche Fabricators | Secures specialized capabilities for defense and aerospace applications. |
| Investment in Digital Integration | Streamlines specification processes for major construction projects. |
| Expansion of Advanced Material Offerings | Captures higher-margin opportunities in corrosive environments. |
| Formation of Long-Term Supply Agreements | Ensures stable procurement for critical infrastructure developments. |
| Certification and Traceability System Upgrades | Reinforces compliance with Australian Standards like AS 1252. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, providing foundational market intelligence. This was combined with primary interviews conducted with procurement managers, engineering consultants, product development leads, and quality assurance officers across the region. The approach integrated bottom-up market sizing with top-down validation, triangulating data points for robust analysis.
Market volume and value were modeled at a granular level across product types, material compositions, end-user segments, and distribution channels over the projection horizon. Compound Annual Growth Rates were derived from an analysis of historical trends and projected future demand drivers. Key forecast inputs included infrastructure project pipelines, raw material price trends, and evolving regulatory compliance costs.
Caveats apply where significant shifts in raw material prices or geopolitical events could materially alter the market outlook. Forecasts reflect assumptions regarding infrastructure spending and regulatory stability over the analysis window. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Apron Feeder Market
Material Handling Equipment
Conveyor Sprocket Market
Material Handling Equipment
Portable Loading Ramps Market
Material Handling Equipment
Global Refuse Compactor Market
Material Handling Equipment
Chain-Driven Roller Conveyors Market
Material Handling Equipment
Helical Gear Market
Material Handling Equipment
Cable Conduit Market
Material Handling Equipment
Pipe Jacking Machines Market
Material Handling Equipment
Low-Level Order Picker Pallet Truck Market
Material Handling Equipment
Shiplifts & Transfer Systems Market
Material Handling Equipment
North America Screw Conveyor Market
Material Handling Equipment
Global Rolling Mill Rolls Market
Material Handling Equipment
Copper and Aluminum Welding Bar Market
Material Handling Equipment
United States Automated Material Handling Market
Material Handling Equipment
Industrial Piggable Wye Fitting Market
Material Handling Equipment
Industrial Sheaves and Pulleys Market