
 Assembly Machine Market | 2026-2036
Assembly Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Assembly Machine Market Analysis
Direct sales channels for large-format assembly systems is reshaping how capital equipment reaches factory floors. Siemens leverages vertical integration across control hardware and software stacks to dominate turnkey line deployments. FANUC sustains manufacturing scale through captive servo motor and reducer production in Japan. ABB competes by extending its robot portfolio into collaborative variants tailored for electronics manufacturers.
An assembly machine constitutes programmable equipment that positions, joins, fastens, or tests components through servo-electric, pneumatic, or hydraulic actuation, typically achieving repeatability tolerances of ±0.02 mm for precision manufacturing. These systems execute welding, adhesive dispensing, screwdriving, and inspection sequences to transform discrete parts into finished subassemblies across industrial production environments. Robotic arms capture the largest value share as six-axis articulated units handle complex orientation tasks in automotive body shops. Electric drive technology leads growth trajectories as manufacturers abandon pneumatic infrastructure to cut energy consumption and improve positional accuracy. Vision systems embedded in quality control stations represent the fastest-expanding segment as inline defect detection replaces offline sampling protocols.
The EU Machinery Directive mandates conformity assessments for safety-related control systems, compelling European vendors to certify interlocking and emergency-stop architectures before market entry. OSHA lockout/tagout standards in the United States shape maintenance access panel designs and energy isolation requirements for serviced equipment. Japan's METI promotes next-generation production systems through JIS B 8433 robot safety standards that align with international harmonization efforts. Stakeholders must monitor evolving cybersecurity annexes to machinery directives as networked assembly lines expose operational technology layers to remote intrusion risks.
Market Dynamics
Electric drive architectures are displacing pneumatic actuation across automotive and electronics assembly lines, forcing capital equipment vendors to retool product portfolios and service networks around servo-electric platforms.
Growth Catalysts
- EU Machinery Directive:Mandatory conformity assessments for safety-related control systems compel European OEMs to upgrade legacy lines with certified robotic interlocks and emergency-stop architectures.
- Battery pack assembly:Electric vehicle manufacturers in Germany, Japan, and the United States require retooled production lines with precision joining equipment for cell-to-module integration.
- Servo-electric actuation:Energy efficiency mandates and positional accuracy requirements in precision electronics manufacturing accelerate abandonment of compressed-air infrastructure.
Market Restraints
- Captive reducer supply:Japanese manufacturers maintain in-house production of precision harmonic drives, limiting second-source availability for European and North American system integrators.
- Rare earth magnet costs:Neodymium price volatility in Chinese spot markets injects uncertainty into permanent magnet servo motor cost structures.
- ISO 10218 compliance timelines:Extended certification cycles for collaborative robot safety functions delay product launches by 8-14 months.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for automotive and electronics manufacturing attract greenfield assembly machine deployments to Gujarat and Tamil Nadu industrial corridors.
- Vision-guided cobots:Convergence of machine vision and force-limited robotics opens electronics subassembly tasks previously reserved for manual operators.
- Direct OEM channel:Large-format automotive lines increasingly bypass distributors for factory-direct procurement, compressing channel margins and capturing installation service revenue.
Industry Challenges
- Mechatronics talent scarcity:Shortages of technicians fluent in both mechanical maintenance and PLC programming extend commissioning timelines and inflate service costs.
- Legacy system integration:Brownfield automotive plants require custom gateway hardware to bridge proprietary fieldbus protocols with modern Ethernet-based control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Assembly Machine Market |
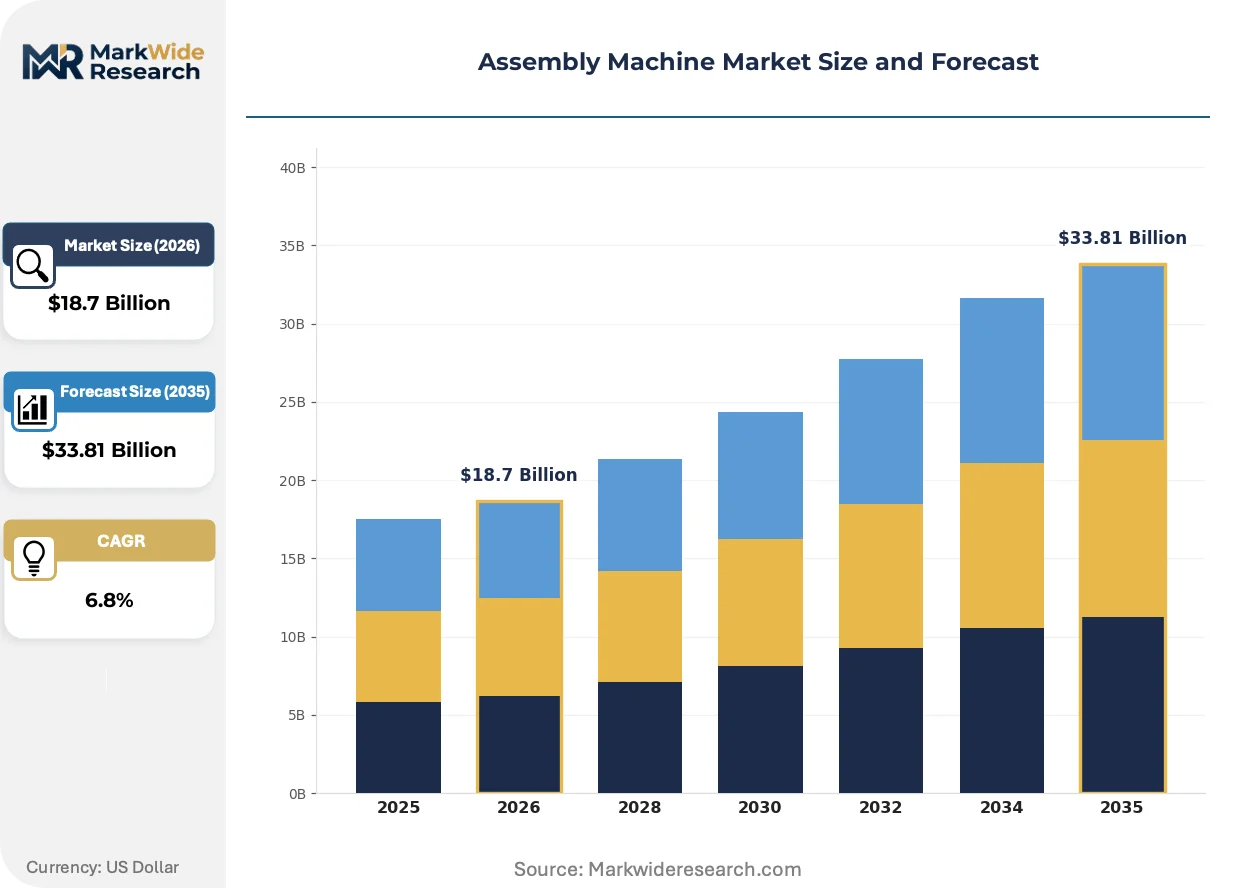
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic Arms, Conveyor Systems, Automated Guided Vehicles, Vision Systems Technology: Electric, Pneumatic, Hydraulic, Hybrid End User: Automotive OEMs, Electronics Manufacturers, Consumer Goods Producers, Aerospace Application: Assembly Lines, Packaging, Quality Control, Product Testing |
| Companies Covered | Siemens, Topbest, DMG MORI, EMAG, Rockwell Automation, FANUC, MAZAK, GROB, ABB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Assembly Machine Market Emerging Trajectories
Digital twin technology is compressing commissioning timelines and enabling remote diagnostic capabilities across distributed production networks. Three developments are accelerating adoption.
Digital twin software is virtualizing physical assembly line behavior before hardware deployment. Automotive OEMs in Germany and the United States now require virtual commissioning for all greenfield body shop investments. This capability is compressing startup timelines and reducing on-site debugging labor by enabling offline program validation.
Japan's METI has harmonized JIS B 8433 robot safety standards with ISO technical specifications, streamlining export certification for domestic manufacturers. This regulatory convergence reduces redundant testing costs for vendors serving multiple jurisdictions. European and Asian system integrators are accelerating procurement of Japanese-certified collaborative units as cross-border compliance friction diminishes.
Automotive OEMs are unbundling after-sales service contracts from initial equipment purchases, selecting third-party maintenance providers based on response time guarantees rather than manufacturer affiliation. Tier-1 suppliers in Stuttgart and Detroit are piloting this model for non-critical joining stations. This behavior is compressing incumbent service margins while creating openings for independent technical service specialists with multi-brand expertise.
Assembly Machine Market Segmentation
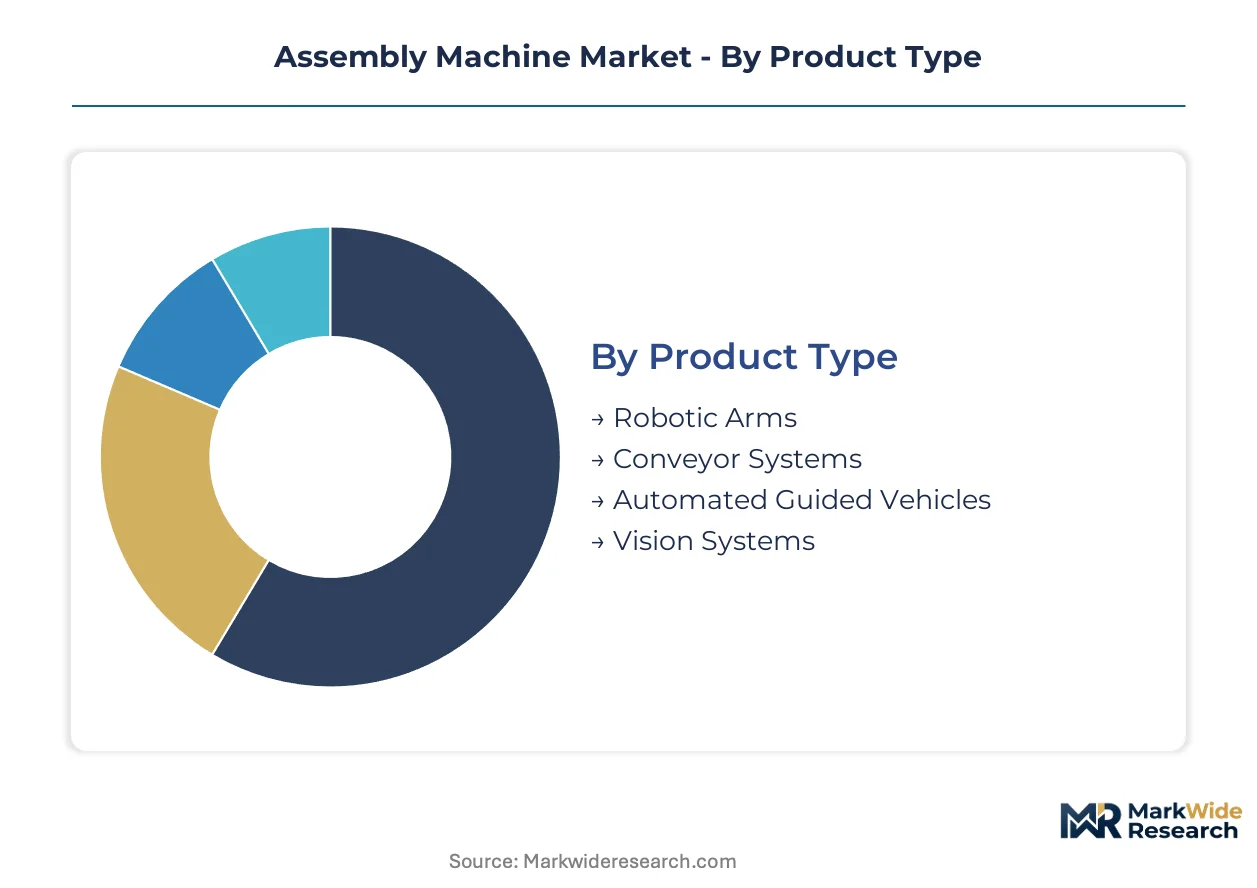
Segmentation in assembly machines reveals how capital equipment vendors align technical architectures with distinct production environments. Procurement patterns diverge sharply between high-volume automotive body shops and precision electronics cleanrooms, forcing suppliers to maintain parallel development tracks.
Product Type:
Mature formats dominate installed base volumes while emerging configurations capture greenfield investment.
- Robotic Arms:Six-axis articulated units with servo-electric actuation achieve ±0.02 mm repeatability for welding and joining operations. Automotive OEMs in Germany and Japan specify these for body-in-white construction, though harmonic drive supply constraints from Japanese captive manufacturers limit second-source availability.
- Vision Systems:Embedded camera arrays with machine learning defect classification execute inline quality control at production speed. Electronics manufacturers in the United States and South Korea are replacing offline sampling protocols with 100% inspection coverage, compressing cycle times and reducing scrap rates.
- Conveyor Systems:Belt and pallet-based transport infrastructure links discrete workstations across automotive and consumer goods facilities.
- Automated Guided Vehicles:Laser-guided and vision-navigated mobile platforms relocate work-in-process inventory between assembly stations.
Robotic arms handle the majority of throughput; vision systems are gaining share fastest as inline inspection replaces legacy sampling methods.
Technology:
Cost tier stratification separates premium electric platforms from legacy pneumatic infrastructure.
- Electric:Servo motor and ball screw architectures deliver programmable positioning with energy recovery capabilities. Precision electronics manufacturers in Japan and Germany mandate electric actuation for sub-micron assembly tasks, driven by ISO 50001 energy management requirements and compressed-air infrastructure abandonment.
- Pneumatic:Compressed-air cylinders and valves remain prevalent in cost-sensitive consumer goods packaging applications where positional tolerance requirements exceed ±0.5 mm.
- Hydraulic:High-force actuation for metal forming and heavy component pressing in aerospace structural assembly.
- Hybrid:Combined electric-pneumatic systems bridge legacy infrastructure with modern control architectures in brownfield automotive plants.
Electric platforms command premium positioning; hybrid configurations serve as the transition pathway for pneumatic-dependent facilities.
End User:
Application complexity and capital intensity create distinct customer archetypes with divergent procurement behaviors.
- Automotive OEMs:Multi-billion dollar vehicle programs require turnkey line integration with virtual commissioning protocols. German and United States headquarters locations concentrate decision authority, though battery pack assembly for electric vehicles is dispersing procurement to cell manufacturing sites in Hungary and South Carolina.
- Electronics Manufacturers:High-mix, low-volume production demands rapid changeover capability and collaborative robot deployment. South Korean and Taiwanese contract manufacturers are expanding cleanroom assembly capacity for semiconductor packaging equipment.
- Consumer Goods Producers:Standardized packaging and filling operations prioritize equipment reliability and spare parts availability over technical sophistication.
- Aerospace:Low-volume, high-precision structural assembly with extensive certification documentation and traceability requirements.
Automotive OEMs represent the largest contract value concentration; electronics manufacturers are expanding procurement fastest as reshoring initiatives accelerate.
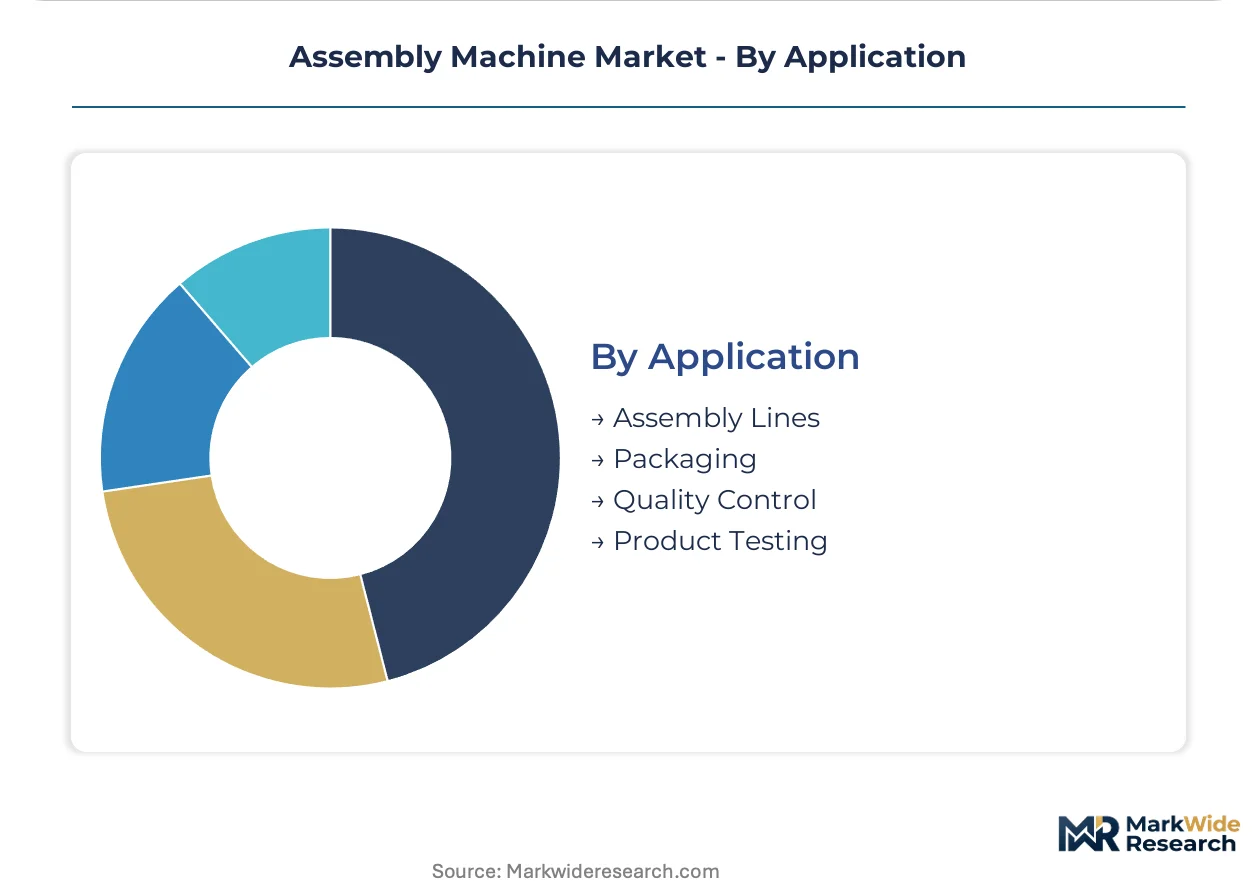
Application:
Volume scale separates continuous-flow production environments from discrete batch operations.
- Assembly Lines:Synchronized workstations with programmable logic controllers execute sequenced joining, fastening, and handling operations. Automotive body shops in Stuttgart and Detroit require 24/7 operational availability with sub-60-second takt times.
- Quality Control:Automated dimensional verification and surface defect detection with statistical process control integration. German automotive suppliers are mandating 100% inline inspection for safety-critical brake and steering components.
- Packaging:End-of-line carton forming, filling, and palletizing for consumer goods distribution.
- Product Testing:Functional verification stations for electronics and aerospace components prior to shipment release.
Assembly lines absorb the majority of capital expenditure; quality control applications are climbing the fastest as regulatory documentation requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput underwrites Germany's role as the primary European entry point for precision servo motors and harmonic drive reducers essential to assembly machine supply chains.
Germany
Automotive OEMs in Stuttgart and Munich drive demand for turnkey body-in-white lines with virtual commissioning protocols. The EU Machinery Directive mandates conformity assessments for safety-related control systems, compelling vendors to certify robotic interlocks before market entry. Battery pack assembly for electric vehicles is dispersing procurement to cell manufacturing sites in Lower Saxony.
United States
Detroit-area automotive headquarters anchor capital investment in large-format assembly systems with 24/7 operational requirements. OSHA lockout/tagout standards shape maintenance access panel designs and energy isolation requirements for serviced equipment. South Carolina's emerging battery corridor attracts greenfield servo-electric line deployments from European and Asian system integrators.
Japan
Captive production of precision harmonic drives and servo motors sustains manufacturing scale for domestic robotic arm vendors. METI harmonized JIS B 8433 robot safety standards with ISO technical specifications, streamlining export certification. Nagoya's precision engineering cluster concentrates R&D investment in next-generation collaborative robot architectures.
China
MIIT's industrial robot promotion policies accelerate domestic substitution in automotive welding applications. GB standards for robotic safety functions are converging with ISO technical specifications, reducing compliance friction for multinational vendors. The Yangtze River Delta's electronics manufacturing belt demands vision-guided cobots for high-mix semiconductor packaging tasks.
India
The PLI scheme for automotive and electronics manufacturing attracts greenfield assembly machine deployments to Gujarat and Tamil Nadu industrial corridors. BIS certification requirements for industrial machinery create compliance timelines that favor established vendors with local technical service networks. Pune's automotive supplier ecosystem is retooling for electric vehicle component assembly with precision joining equipment.
Assembly Machine Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in captive reducer and servo motor production. The vendor base concentrates around German-Japanese-American technology clusters with limited second-source availability for precision motion components. Three archetypes dominate: turnkey line builders with vertical software stacks, captive component manufacturers with downstream robot assembly, and independent vision system integrators. Competitive moves center on backward integration into servo motor production and geographic expansion through India PLI-linked joint ventures.
Among Germany-based industrial conglomerates, Siemens and DMG MORI occupy positions as turnkey platform providers. Japanese specialists FANUC and Yaskawa (via its MAZAK affiliation) exemplify the captive component archetype with in-house harmonic drive and reducer production. Rockwell Automation represents the North American control architecture approach, competing through integrated safety systems and Ethernet-based fieldbus protocols rather than mechanical component dominance.
| Leading Market Players |
|---|
| Siemens |
| Topbest |
| DMG MORI |
| EMAG |
| Rockwell Automation |
| FANUC |
| MAZAK |
| GROB |
| ABB |
| Others |
Supply Flow & Price Mechanics
Overcapacity in China's servo motor foundries is compressing margins for European and Japanese system integrators while simultaneously creating procurement leverage for automotive OEMs with multi-year equipment contracts. This utilization imbalance feeds directly into pricing posture: suppliers with captive reducer production maintain premium positioning, while those dependent on spot-market magnet sourcing absorb cost volatility.
Pricing Analysis
Volume-discount tiering separates turnkey line builders from component vendors, with automotive OEMs capturing 15-25% contract reductions against list pricing for multi-station body shop deployments. Price differentiation hinges on ISO 10218 safety certification tier and captive harmonic drive supply. Cost compression in mid-range electric actuation is intensifying because Chinese domestic manufacturers are undercutting European servo platforms on raw magnet costs. Tier-1 automotive suppliers exhibit highest price sensitivity due to unbundling of service contracts, while aerospace manufacturers prioritize certification documentation over unit economics.
Supply Chain Analysis
Tariff exposure between China and the United States dominates risk planning for permanent magnet servo motor procurement, with European vendors accelerating dual-sourcing strategies to circumvent duty uncertainty. Component supply concentrates in Japan for precision harmonic drives, China for rare earth processing, and Germany for control hardware engineering. The assembly machine supply chain rests on neodymium magnet spot markets, precision bearing steel from Swedish specialty mills, and FPGA chipsets from Taiwanese foundries. Single-source vulnerability in Japanese captive reducer production creates bottleneck risk for six-axis articulated units. Distribution runs through direct OEM channels for large-format automotive lines and specialized system integrators for electronics cleanroom deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The assembly machine market functions as a defensive-moat story where regulatory certification entrenchment creates switching costs that lock in incumbent positions across multi-year automotive platform cycles.
For Market Incumbents: Entrench position by deepening backward integration into servo motor production to offset rare earth price volatility, and by securing JIS B 8433/ISO 10218 dual-certification for collaborative robot portfolios before emerging Chinese vendors achieve compliance parity. The threat of domestic Chinese substitution under MIIT industrial robot policies demands preemptive certification investment rather than reactive margin defense. For New Entrants and Emerging Players: Build out technical service networks in India's Gujarat and Tamil Nadu industrial corridors to capture PLI-linked greenfield deployment demand, targeting electronics subassembly applications where vision-guided cobot specifications remain undefined. The most penetrable white space sits in aftermarket service unbundling, where independent multi-brand maintenance providers can undercut OEM service contracts on response-time guarantees. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-entrenchment play because EU Machinery Directive conformity assessment timelines and ISO 10218 certification cycles create 8-14 month barriers that favor established vendors with documented safety architectures. Acquisition targets should prioritize captive reducer manufacturers or vision system integrators with automotive-qualified defect classification algorithms. The signal to watch is battery pack assembly line procurement dispersal to cell manufacturing sites in Hungary and South Carolina, which indicates geographic demand fragmentation favoring localized system integrators.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Servo Motor Production | Backward integration into permanent magnet motor manufacturing insulates FANUC and Yaskawa from Chinese rare earth spot volatility. |
| ISO 10218 Dual Certification | Harmonized JIS B 8433 compliance streamlines export access for Japanese collaborative robot vendors into European automotive markets. |
| India PLI Joint Ventures | Greenfield assembly machine deployments in Gujarat industrial corridors capture production-linked incentive contracts for automotive and electronics manufacturing. |
| Digital Twin Virtual Commissioning | Automotive OEMs in Stuttgart and Detroit now mandate offline program validation, compressing startup timelines for body-in-white line builders. |
| Vision System Acquisition | Machine learning defect classification capabilities in South Korean electronics cleanrooms command premium positioning in inline quality control replacement cycles. |
Methodological Framework
A spread of perspectives from automotive OEM procurement directors, Tier 1 supplier plant engineers, system integrator technical leads, and aftermarket service specialists converged on the working assumptions for this analysis. Primary fieldwork combined structured interviews with secondary validation through SEC 10-K filings, customs trade data for servo motor and reducer imports, EU Machinery Directive conformity assessment databases, and METI industrial robot shipment statistics. Bottom-up equipment deployment estimates triangulated against top-down automotive production forecasts across the analysis window.
Demand-supply-balance framing anchored the forecast framework, with segmentation across robotic arm configurations, actuation technology tiers, end-user industry archetypes, and application environments modeled throughout the projection horizon. CAGRs derived from equipment replacement cycles, greenfield capacity expansion announcements, and regulatory compliance upgrade mandates. Industry-specific inputs included battery pack assembly line procurement dispersal patterns and electronics reshoring initiative tracking for semiconductor packaging equipment.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by Chinese domestic robot vendors or accelerated rare earth magnet recycling breakthroughs would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Extrusion Equipment Market
Construction Equipment
Crane Aftermarket Market
Construction Equipment
LAMEA Water Pump Market
Construction Equipment
France Construction Equipment Market
Construction Equipment
Snow Removal Equipment Market
Construction Equipment
Saudi Arabia Completion Equipment and Services Market
Construction Equipment
Grout Bags Market
Construction Equipment
Truck Mounted Concrete Pump Market
Construction Equipment
Industrial Steam Washer Market
Construction Equipment
Road Marking Equipment Market
Construction Equipment
Plasma Cutting Equipment Market
Construction Equipment
Concrete Demolition Professional Equipment Market
Construction Equipment
Fully Automatic Metal Band Saw Machine Market
Construction Equipment
Log Splitters Rental Market
Construction Equipment
4-Wheel Sit-Down Counterbalance Forklift Market
Construction Equipment
Vertical Grinding Mills Market