
 Shotcrete Sprayer Market | 2026-2036
Shotcrete Sprayer Market Size, Share, and Industry Trends Forecast 2026-2036
Shotcrete Sprayer Market Analytics
A widening capital-intensity divergence between integrated manufacturers and assembly-dependent competitors is rotating competitive advantage toward firms controlling pump engineering and nozzle robotics in-house. Putzmeister leverages its German engineering base to sustain premium positioning in hydraulic wet-mix systems across European tunneling projects. Normet anchors its Nordic mining heritage to dominate battery-electric and diesel-hydraulic sprayer fleets in underground operations. Sika AG extends its chemicals-to-equipment vertical scope to compete on binder-integrated system sales rather than hardware alone.
Shotcrete sprayers are pressure-driven concrete placement machines that pneumatically or hydraulically project wet or dry cementitious mixtures through a delivery hose and nozzle at velocities exceeding 100 meters per second, forming structural linings, ground support layers, or erosion-resistant surfaces against rock or soil substrates. Wet-mix technology leads installed base volumes due to lower rebound rates and consistent compressive strength in permanent tunnel linings, while robotic sprayers represent the fastest-growing product category as labor costs and safety liabilities push operators toward tele-remote and autonomous boom control. Hydraulic drive systems occupy the dominant technology position in heavy mining applications, though electric and battery-electric configurations are gaining share where ventilation-constrained environments restrict diesel emissions.
OSHA silica exposure limits and MSHA diesel particulate standards in the United States compel fleet upgrades toward enclosed-cab robotic systems with integrated dust suppression, while EU F-Gas Regulation and CE machinery directives accelerate electric drivetrain adoption across European tunneling contracts. Australia's national mine safety frameworks and state-level coal and metalliferous regulations similarly mandate operator isolation technologies that favor remote-controlled sprayer deployment. Stakeholders must weigh captive maintenance infrastructure against OEM service networks as equipment electrification outpaces technician training pipelines.
Market Dynamics
Mechanized fleet conversion in underground construction is compressing operator labor pools while elevating equipment complexity, forcing contractors to restructure capex planning around robotic wet-mix platforms and tele-remote boom architectures.
Growth Catalysts
- EU Green Deal carbon benchmarks:Tunneling contractors across Germany, Austria, and Switzerland are retiring diesel-hydraulic fleets ahead of schedule to meet procurement criteria mandating lower embodied carbon in infrastructure projects.
- Robotic wet-mix technology:Mining operators in Australia and Brazil are accelerating adoption of autonomous nozzle control systems to reduce silica exposure liability and rebound material waste in permanent ground support applications.
- Underground mining depth extension:Metalliferous operations in Western Australia and Canada's Sudbury Basin are driving demand for battery-electric sprayer configurations as ventilation economics deteriorate at depths exceeding 1,500 meters.
Market Restraints
- High-alloy steel supply concentration:Pump cylinder and wear plate fabrication depends on Swedish and Finnish specialty steel mills, exposing OEMs to input cost volatility and extended lead times during energy price spikes.
- MSHA diesel particulate standards:US underground coal operators face fleet upgrade mandates that compress replacement cycles before full depreciation, straining capital allocation across multi-site contracting businesses.
- Shotcrete rebound material handling:Dry-mix systems retain 15-25% rebound rates versus sub-10% for wet-mix, creating waste disposal cost penalties that disadvantage legacy installed bases in environmental compliance jurisdictions.
Strategic Opportunities
- Battery-electric drivetrain convergence:Integration of lithium-iron-phosphate powertrains with regenerative hydraulics is opening tunneling contracts in EU urban cores where diesel bans are advancing.
- Peru and Chile copper expansion:Greenfield underground projects in the Andean belt present untapped demand for enclosed-cab robotic sprayers as national mine safety frameworks tighten operator isolation requirements.
- Tele-remote operation platforms:5G-enabled boom control is creating aftermarket service revenue streams through software subscription models that decouple equipment sales from maintenance profitability.
Industry Challenges
- Electrification technician scarcity:Battery management system diagnostics and high-voltage safety protocols outpace vocational training pipeline output, extending equipment downtime during fault conditions.
- CE machinery directive certification timelines:Robotic safety system validation for autonomous nozzle positioning requires 18-24 month approval cycles that delay product launches behind competitor entries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shotcrete Sprayer Market |
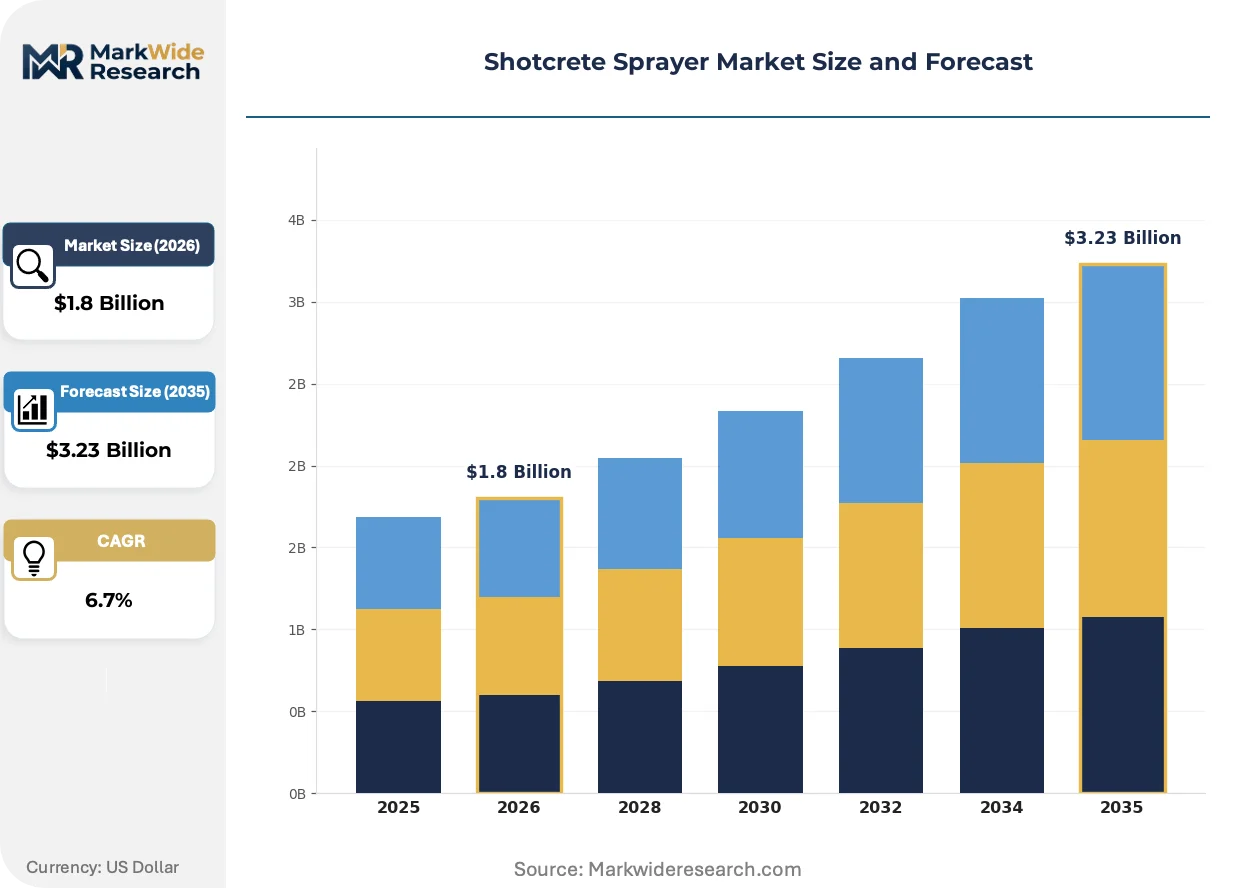
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wet Mix, Dry Mix, Robotic, Manual Technology: Air-Driven, Electric, Hydraulic, Pneumatic End User: Construction, Mining, Tunneling, Rehabilitation Application: Infrastructure, Ground Support, Pool Construction, Slope Stabilization |
| Companies Covered | Putzmeister, Normet, Sika AG, CIFA, Gengli, MacLean Engineering, Reed, Epiroc, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shotcrete Sprayer Market Evolving Landscape
Digital twin integration and additive manufacturing are compressing prototyping cycles for nozzle wear components while predictive maintenance algorithms reshape service contract structures across mining and tunneling fleets.
Advanced sensor fusion for real-time slump monitoring is miniaturizing. Optical flow meters and microwave moisture analyzers embedded directly at the nozzle tip enable closed-loop water addition without operator intervention. Scandinavian tunneling contractors are piloting these systems on hydropower cavern projects. The technology is miniaturizing quality control infrastructure from batch plant laboratories to point-of-application feedback loops, reducing specification deviation claims.
EU F-Gas Regulation phase-down schedules are accelerating refrigerant transition in enclosed-cab climate systems. OEMs must redesign thermal management architectures using CO2 or hydrocarbon alternatives before 2027 compliance deadlines. Battery-electric sprayer variants for European urban tunneling contracts are most affected, with German manufacturers advancing prototype testing ahead of Austrian and Swiss certification requirements.
Equipment-as-a-service contracting is displacing outright purchase models in mid-tier mining operations. Contractors in Brazil's Carajás mineral province now lease robotic wet-mix fleets with bundled maintenance and remote diagnostics, transferring residual value risk to OEM balance sheets. This shift concentrates bargaining power among fleet aggregators and compresses margin capture for standalone equipment vendors lacking captive financing arms.
Shotcrete Sprayer Market Segmentation
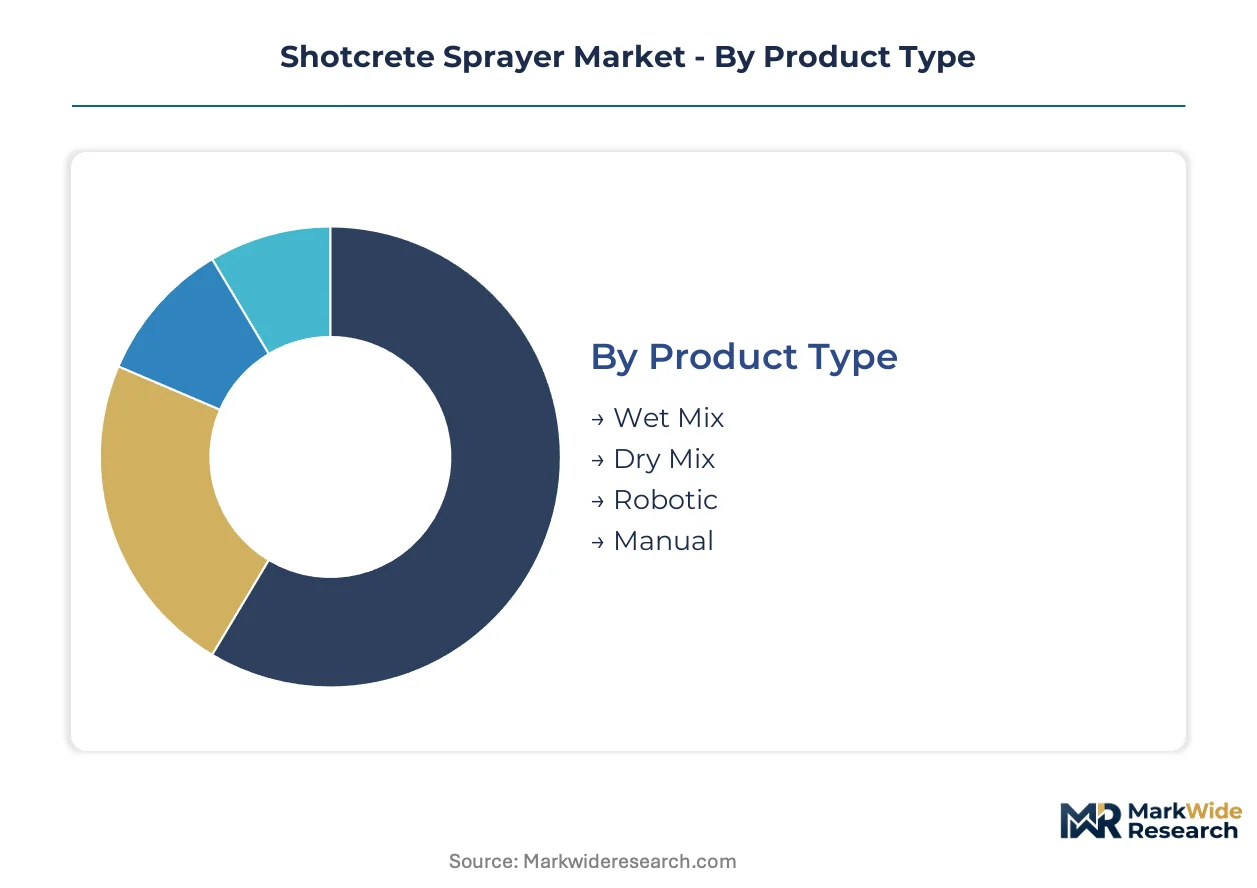
Shotcrete sprayer procurement patterns diverge sharply across product architectures and powertrain technologies, with wet-mix platforms displacing dry-mix legacy fleets in permanent lining applications while electrification reshapes total cost of ownership calculations.
Product Type:
Substitution pressure from robotic automation and wet-mix chemistry improvements is compressing margins for manual and dry-mix equipment, forcing OEMs to reposition legacy portfolios toward repair markets.
- Wet Mix:Pre-blended cementitious slurry pumped through delivery hoses at controlled water-cement ratios achieves sub-10% rebound rates in tunnel lining applications. German and Austrian tunneling contractors specify wet-mix systems for permanent structural support under EU Green Deal procurement criteria favoring lower embodied carbon.
- Robotic:Tele-remote boom architectures with autonomous nozzle positioning reduce silica exposure liability while enabling 24-hour continuous operation in ventilation-constrained environments. Australian metalliferous mines and Brazilian Carajás operations are accelerating fleet conversion to robotic wet-mix platforms.
- Dry Mix:Pneumatic conveyance of dry cement and aggregate with water injection at the nozzle retains niche demand in remote access rehabilitation where batch plant infrastructure is absent.
- Manual:Hand-held spraying equipment persists in pool construction and small-scale slope stabilization where capital constraints limit mechanized fleet investment.
Wet Mix retains volume leadership; Robotic holds the steepest expansion curve.
Technology:
Cost tier stratification separates premium hydraulic mining systems from economy pneumatic units, with electric drivetrains capturing mid-market tunneling contracts.
- Hydraulic:High-pressure piston pumps deliver consistent material flow at depths exceeding 1,500 meters where electric powertrains face thermal management constraints. Western Australian underground operations specify hydraulic wet-mix sprayers for battery-electric conversion readiness.
- Electric:Grid-tied or battery-electric configurations eliminate diesel particulate emissions in urban tunneling contracts across EU urban cores with advancing diesel bans. CO2-based thermal management redesigns are accelerating ahead of F-Gas Regulation deadlines.
- Pneumatic:Compressed air-driven rotor systems dominate dry-mix applications in developing market rehabilitation projects with limited electrical infrastructure.
- Air-Driven:Venturi-effect material conveyance persists in specialty pool construction and decorative shotcrete where low capital outlay outweighs rebound efficiency penalties.
Hydraulic dominates mining revenue; Electric is gaining share fastest in tunneling procurement.
End User:
Application maturity varies dramatically, with mining and tunneling commanding specification-grade equipment while rehabilitation tolerates legacy platform redeployment.
- Mining:Metalliferous and coal operations demand enclosed-cab robotic systems with integrated dust suppression to comply with MSHA silica exposure limits and national mine safety frameworks. Sudbury Basin and Western Australian deep operations are driving battery-electric configuration demand.
- Tunneling:Urban infrastructure projects across Germany, Austria, and Switzerland mandate lower embodied carbon equipment under EU Green Deal procurement criteria, favoring wet-mix robotic fleets with tele-remote capability.
- Construction:Commercial and residential building applications utilize manual and semi-mechanized sprayers for architectural concrete and specialty finishes.
- Rehabilitation:Bridge repair and structural retrofit projects absorb redeployed dry-mix equipment from retiring mining fleets.
Mining commands premium pricing; Tunneling shows the steepest technology upgrade trajectory.
Application:
Customer type concentration separates specification-driven infrastructure procurement from price-sensitive specialty construction.
- Ground Support:Permanent rock bolting and shotcrete lining in underground excavations demands wet-mix robotic systems with real-time slump monitoring. Scandinavian hydropower cavern projects are piloting optical flow meter and microwave moisture analyzer integration at the nozzle tip.
- Infrastructure:Roadway, railway, and utility tunnel projects specify CE-certified equipment with autonomous safety systems validated under machinery directive protocols.
- Slope Stabilization:Highway cut and landslide remediation applications utilize mobile wet-mix units with rapid deployment booms.
- Pool Construction:Residential and commercial aquatic facilities employ manual spraying equipment for curved shell geometry access.
Ground Support leads equipment utilization intensity; Infrastructure drives the steepest regulatory compliance investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. Australian and Brazilian mining operators absorb premium equipment costs for safety compliance, while Southeast Asian contractors prioritize capital efficiency over automation features.
Germany
Tunneling contractors in Bavaria and Baden-Württemberg are retiring diesel-hydraulic fleets ahead of schedule. EU Green Deal procurement criteria now mandate embodied carbon thresholds for infrastructure equipment. Stuttgart-based engineering clusters are validating battery-electric wet-mix prototypes for urban tunneling contracts.
Australia
Western Australian deep metalliferous operations are driving battery-electric sprayer demand as ventilation economics deteriorate below 1,500 meters. The country's national mine safety frameworks mandate operator isolation technologies. Perth equipment dealers are consolidating tele-remote fleet servicing capabilities for Pilbara and Kalgoorlie operations.
Brazil
Carajás mineral province contractors are accelerating robotic wet-mix adoption to reduce silica exposure liability. ANVISA occupational health standards are tightening enforcement across Pará state mining jurisdictions. Belo Horizonte equipment lessors are bundling maintenance contracts with autonomous nozzle control systems.
United States
Underground coal operators in Appalachia and the Powder River Basin face compressed replacement cycles under MSHA diesel particulate standards. OSHA silica exposure limits are pushing fleet upgrades toward enclosed-cab robotic systems. Pittsburgh-area contractors are piloting 5G-enabled boom control for continuous operation models.
Switzerland
Alpine tunneling projects along the Gotthard and Lötschberg corridors specify wet-mix robotic systems under strict CE machinery directives. Swissmedic-aligned occupational safety protocols exceed baseline EU requirements for operator cab air quality. Zurich equipment distributors are specializing in F-Gas Regulation-compliant thermal management retrofits.
Shotcrete Sprayer Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with hydraulic wet-mix engineering and nozzle robotics capabilities separating premium positioning from assembly-dependent competition. The vendor base clusters around three strategic archetypes: German-engineered tunneling specialists, Nordic mining heritage operators, and chemicals-to-equipment vertical integrators. Competitive moves concentrate on battery-electric drivetrain convergence and tele-remote platform development rather than capacity expansion.
Among European-based integrated manufacturers, Putzmeister and Normet exemplify divergent specialization strategies—one anchoring German tunneling engineering, the other leveraging Nordic underground mining heritage. Sika AG occupies a distinct position as a chemicals-to-equipment vertical integrator competing on binder-integrated system architectures rather than hardware alone. These three represent the dominant competitive archetypes reshaping procurement criteria across EU Green Deal infrastructure contracts and deep mining operations.
| Leading Market Players |
|---|
| Putzmeister |
| Normet |
| Sika AG |
| CIFA |
| Gengli |
| MacLean Engineering |
| Reed |
| Epiroc |
| BASF SE |
| Others |
Value Network & Pricing Analysis
EU F-Gas Regulation phase-down schedules gate both thermal management system qualification and price tier differentiation, compressing margins for OEMs lacking CO2-based climate control architectures while rewarding early certifiers with premium positioning in urban tunneling contracts.
Pricing Analysis
Aftermarket service revenue streams anchor lifetime value capture as equipment-as-a-service contracting displaces transactional sales. Three-tier pricing structure across premium, standard, and economy levels separates hydraulic wet-mix mining systems from pneumatic dry-mix rehabilitation units. Cost compression in mid-tier electric configurations is intensifying because battery management system diagnostics outpace technician training pipelines. Small-scale slope stabilization contractors exhibit highest price sensitivity, while deep metalliferous operators absorb premium costs for enclosed-cab robotic compliance.
Supply Chain Analysis
Sweden and Finland anchor specialty steel production for pump cylinder and wear plate fabrication, with German engineering clusters supplying precision hydraulic components. High-alloy steel feedstock draws from Scandinavian mills, while lithium-iron-phosphate cells for battery-electric variants rest on East Asian cell manufacturing. Single-source vulnerability concentrates in Swedish specialty steel during energy price spikes. Distribution runs through Perth and Belo Horizonte equipment dealers bundling tele-remote servicing with fleet leases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Underground construction capital expenditure cycles are recovering as EU Green Deal infrastructure procurement accelerates fleet replacement timelines.
For Market Incumbents: Compound service revenue capture through predictive maintenance software subscriptions that decouple hardware sales from profitability. Deepen backward integration into nozzle robotics engineering to defend against assembly-dependent competitors. Prioritize CE machinery directive certification investment to preempt 18-24 month validation delays behind rival product launches. For New Entrants and Emerging Players: CE marking fast-track pathways for autonomous nozzle positioning systems open white-space entry in Peruvian and Chilean copper expansion projects. Target Brazilian Carajás mineral province equipment leasing where bundled maintenance contracts transfer residual value risk from contractors. Pursue 5G-enabled boom control as the go-to-market angle for tele-remote aftermarket service differentiation. For Investors and Strategic Acquirers: EU Green Deal carbon benchmark enforcement reshapes the acquisition landscape toward battery-electric drivetrain capabilities. Long-term viability centers on OEMs controlling captive financing arms for equipment-as-a-service aggregation. Monitor technician training pipeline output as the inflection signal for electrification deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Battery-Electric Drivetrain Convergence | EU urban diesel bans in Stuttgart and Zurich tunneling contracts mandate zero-emission configurations. |
| Tele-Remote Platform Development | 5G-enabled boom control creates recurring software revenue streams for Perth equipment dealers. |
| Backward Integration into Nozzle Robotics | In-house pump engineering separates German tunneling specialists from assembly-dependent competitors. |
| CE Machinery Directive Certification | Robotic safety system validation gates product launches in Austrian and Swiss infrastructure procurement. |
| Equipment-as-a-Service Contracting | Leasing models with bundled maintenance transfer residual value risk to OEM balance sheets in Brazil. |
Research Methodology
A standing panel of tunneling project managers, mine maintenance directors, OEM aftermarket service heads, and equipment procurement officers provided ongoing calibration across primary fieldwork and secondary validation. Trade data from customs records, EU machinery directive filings, MSHA compliance databases, and national mine safety framework updates anchored supply-side triangulation. Bottom-up fleet deployment counts and top-down infrastructure investment flows were cross-referenced for consistency.
Output validation against external benchmarks confirmed projection alignment across wet-mix versus dry-mix technology splits, hydraulic-electric-pneumatic powertrain shares, and mining-tunneling-rehabilitation end-use segmentation. CAGRs were derived from installed base turnover rates and replacement cycle compression under regulatory mandates. Battery-electric configuration adoption curves and robotic wet-mix penetration timelines served as industry-specific forecast inputs across the analysis window.
Underlying assumptions cover EU Green Deal procurement enforcement continuity, MSHA diesel particulate standard adherence, and ventilation economics deterioration at depth, with deviation risk concentrated in specialty steel supply disruptions and technician training pipeline bottlenecks. Recalibration cycles align with material shifts in carbon benchmark stringency and autonomous safety system validation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Global Riveting Equipment Market
Construction Equipment
Europe Multi Attachment Loaders Market
Construction Equipment
Static and Rotating Equipment Market
Construction Equipment
Heavy Construction Equipment Rental Market
Construction Equipment
Wood Chipper Machines Market
Construction Equipment
Aerial Work Platform (AWP) Market
Construction Equipment
Crossover Ladder Market
Construction Equipment
Manual Welding Positioner Market
Construction Equipment
Press Fit Machines Market
Construction Equipment
Thailand Construction Equipment Market
Construction Equipment
Global Cone Crusher Market
Construction Equipment
Bulldozer Rental Market
Construction Equipment
Engine Driven Welders Market
Construction Equipment
Europe Used Construction Machinery Market
Construction Equipment
Drilling Machine Market
Construction Equipment
China Elevator Ropes Market