
 Global Cone Crusher Market | 2026-2036
Global Cone Crusher Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cone Crusher Market Foresight
The EU Green Deal's embedded carbon thresholds for heavy machinery is shifting procurement criteria across European quarrying and mining operations. Metso Corporation leverages its aftermarket services network to sustain long-term customer relationships in mineral processing. Sandvik AB anchors its competitive position through advanced automation integration in cone crusher control systems. Terex Corporation differentiates via modular plant configurations that reduce site installation timelines for infrastructure developers.
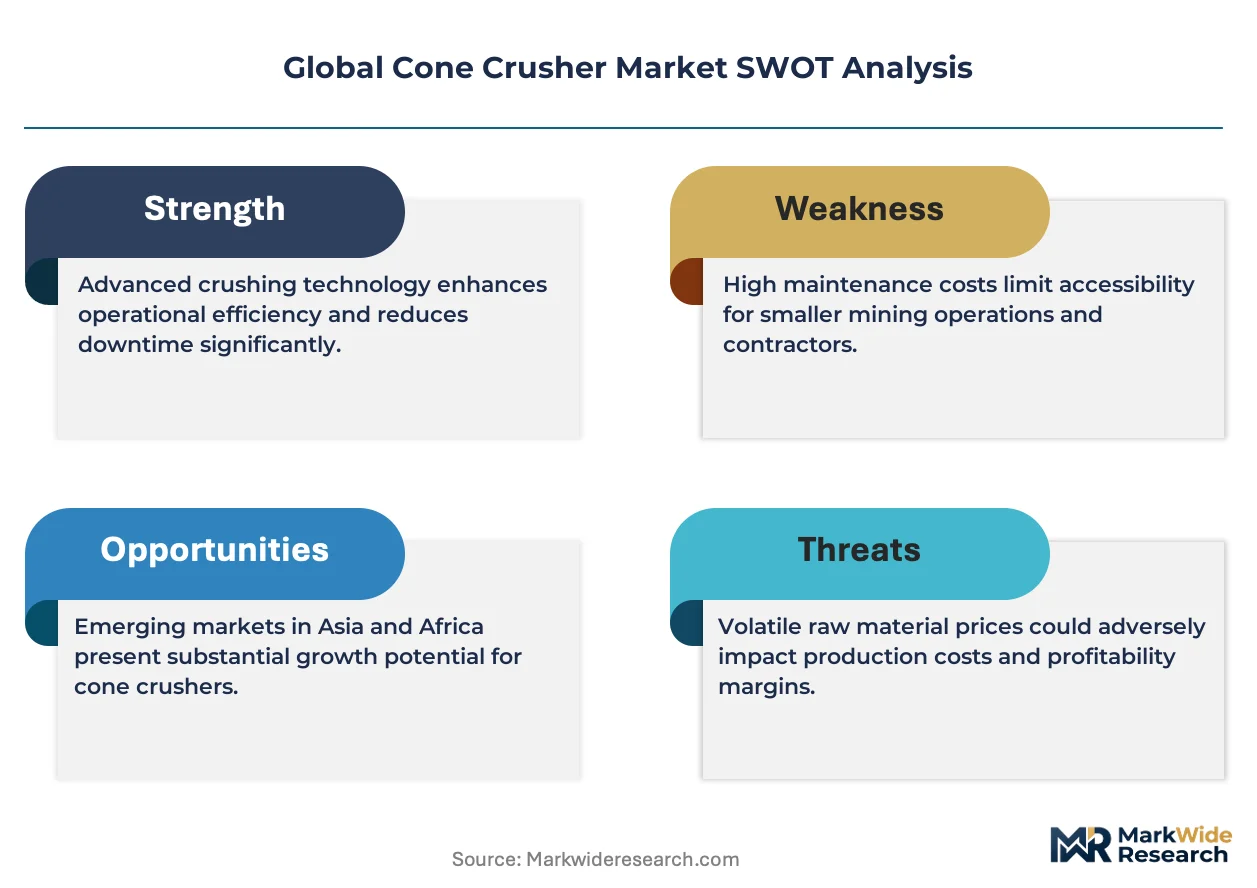
A cone crusher is a compression-type machine that reduces material by squeezing it between an eccentrically gyrating spindle and a concave hopper, with discharge openings typically adjustable between 5 mm and 100 mm depending on application requirements. Its primary industrial purpose is secondary and tertiary crushing of hard, abrasive ores and rocks to specified gradations for downstream processing. Hydraulic cone crushers command premium positioning due to their overload protection and automated setting adjustment capabilities that minimize unplanned downtime. Quarry operators represent the most active end-user category as aggregate specifications tighten for road and rail base materials across jurisdictions.
EPA Tier 4 Final emissions regulations in the United States and REACH compliance requirements in Europe constrain engine and lubricant specifications for mobile crushing installations. India's CEA efficiency mandates and China's MEE dust control standards are reshaping product certification requirements for equipment imports. Brazil's ANVISA-aligned industrial safety protocols and Australia's WHS regulations add layered compliance complexity for multinational suppliers. Stakeholders must monitor evolving carbon border adjustment mechanisms and local content rules that could redirect supply chain investments toward regional manufacturing footprints.
Market Dynamics
Electrification mandates from the EU Green Deal and EPA Tier 4 Final standards are compressing diesel-hydraulic equipment lifecycles while accelerating capital redeployment toward hybrid drive architectures across quarrying and mining installations.
Growth Catalysts
- Highway construction programs:India's Bharatmala project and Brazil's federal highway concessions are expanding aggregate processing capacity requirements for secondary crushing equipment.
- EU Green Deal decarbonization thresholds:Embedded carbon limits for heavy machinery procurement are redirecting quarry operator capital toward electrified cone crusher configurations with lower lifecycle emissions.
- Automated setting adjustment:Hydraulic overload protection systems are minimizing unplanned downtime in hard rock applications, improving equipment utilization rates for tertiary crushing circuits.
Market Restraints
- Steel alloy input volatility:Manganese steel liner plate costs fluctuate with commodity pricing, compressing margin predictability for equipment manufacturers.
- Engine supplier concentration:EPA Tier 4 Final and EU Stage V compliant diesel powertrain availability concentrates among three European and Japanese suppliers, creating procurement bottlenecks.
- Jaw crusher substitution:Primary crushing applications in softer rock deposits increasingly specify jaw crushers with lower capital intensity, limiting cone crusher penetration in certain quarry segments.
Strategic Opportunities
- Indonesia mining license expansion:Nickel and copper concession allocations are accelerating equipment procurement for mineral processing infrastructure in Sulawesi and Papua.
- Modular plant configurations:Containerized crushing circuits reduce site installation timelines from weeks to days, opening contractor rental and short-term project markets.
- CEA efficiency mandates:India's Central Electricity Authority standards for motor-driven equipment create certification-driven preference shifts toward high-efficiency drive systems.
Industry Challenges
- Automation integration complexity:Retrofitting IoT-enabled crusher control systems into legacy plant architectures requires specialized commissioning expertise that remains scarce in emerging markets.
- REACH lubricant compliance:Extended certification timelines for biodegradable hydraulic fluids delay product launches in European quarrying operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cone Crusher Market |
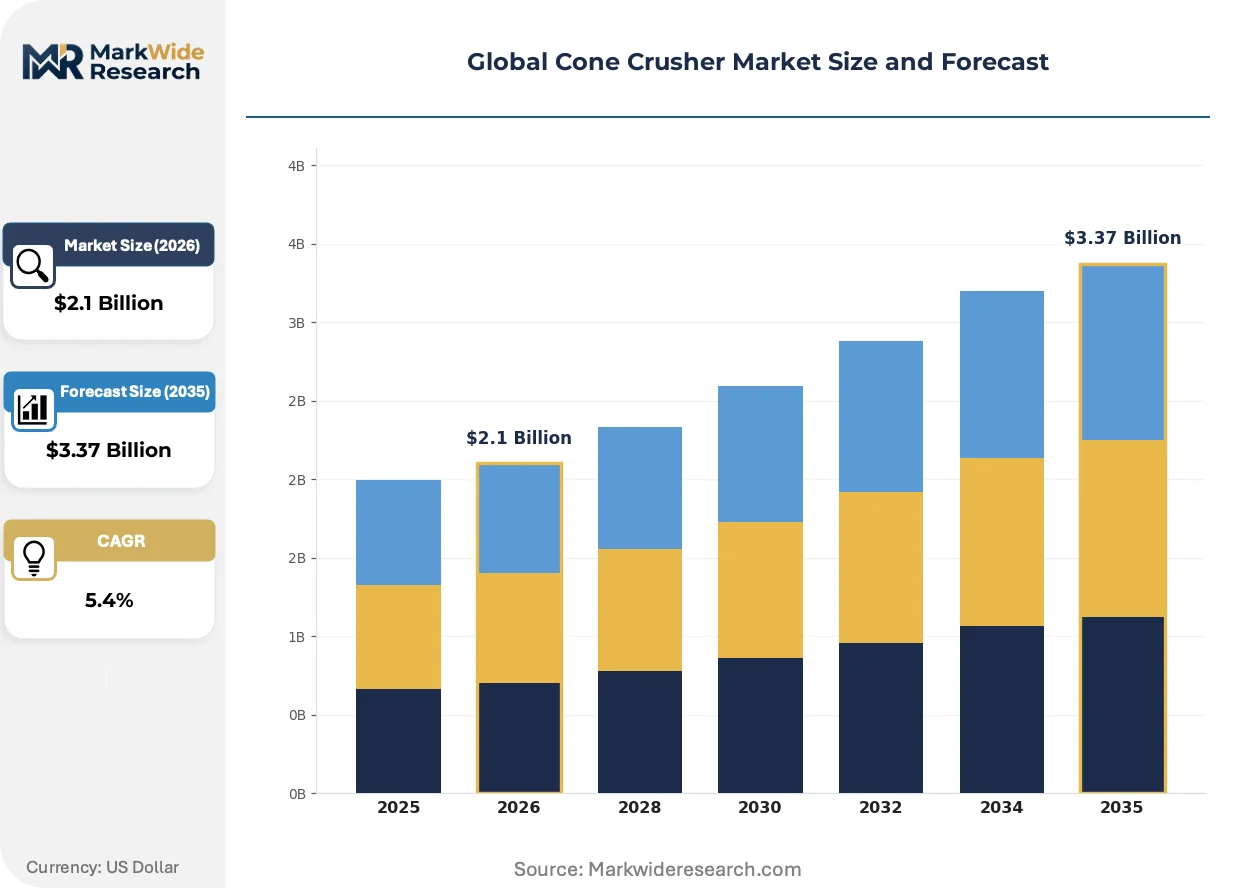
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.37 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Cone Crushers, Short Head Cone Crushers, Symons Cone Crushers, Hydraulic Cone Crushers, Spring Cone Crushers Technology: Hydraulic System, Mechanical System, Electrohydraulic System, Hydraulic Hydroset, Lubrication System Application: Mining, Quarrying, Construction Aggregates, Metallurgy, Chemical Industry End User: Mineral Processing Firms, Quarry Operators, Infrastructure Developers, Metal Extractors |
| Companies Covered | Metso Corporation, Sandvik AB, Terex Corporation, Thyssenkrupp AG, FLSmidth & Co. A/S, McCloskey International, Astec Industries Inc., Keestrack, Puzzolana, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cone Crusher Market Shifts & Advancements
Digital twin architectures and predictive maintenance platforms are absorbing capital allocation that previously targeted mechanical reliability improvements, compressing the innovation cycle from hardware to software-defined crushing optimization.
Variable frequency drive technology is absorbing the functional role of mechanical clutch systems in cone crusher power transmission. Quarry operators in Australia and Canada are specifying VFD-equipped installations to match crusher throughput with variable feed rates from upstream screening circuits. This transition is absorbing maintenance budget allocations previously directed toward mechanical wear component replacement.
REACH compliance requirements for lubricant formulations are constraining hydraulic fluid specifications across European installations. Equipment manufacturers must validate biodegradable alternatives that maintain viscosity stability across temperature ranges while satisfying ECHA substance restrictions. Mobile crushing contractors in Germany and Scandinavia face extended procurement cycles as they await certified fluid approvals for fleet standardization.
After-sales service unbundling is fragmenting the traditional bundled maintenance contract model. Indonesian and Brazilian mining operators are negotiating component-level service agreements separately from equipment supply, compressing OEM service revenue per unit. Equipment lessors in these markets are building in-house technical capabilities to capture margin previously retained by manufacturer service networks.
Global Cone Crusher Market Segmentation
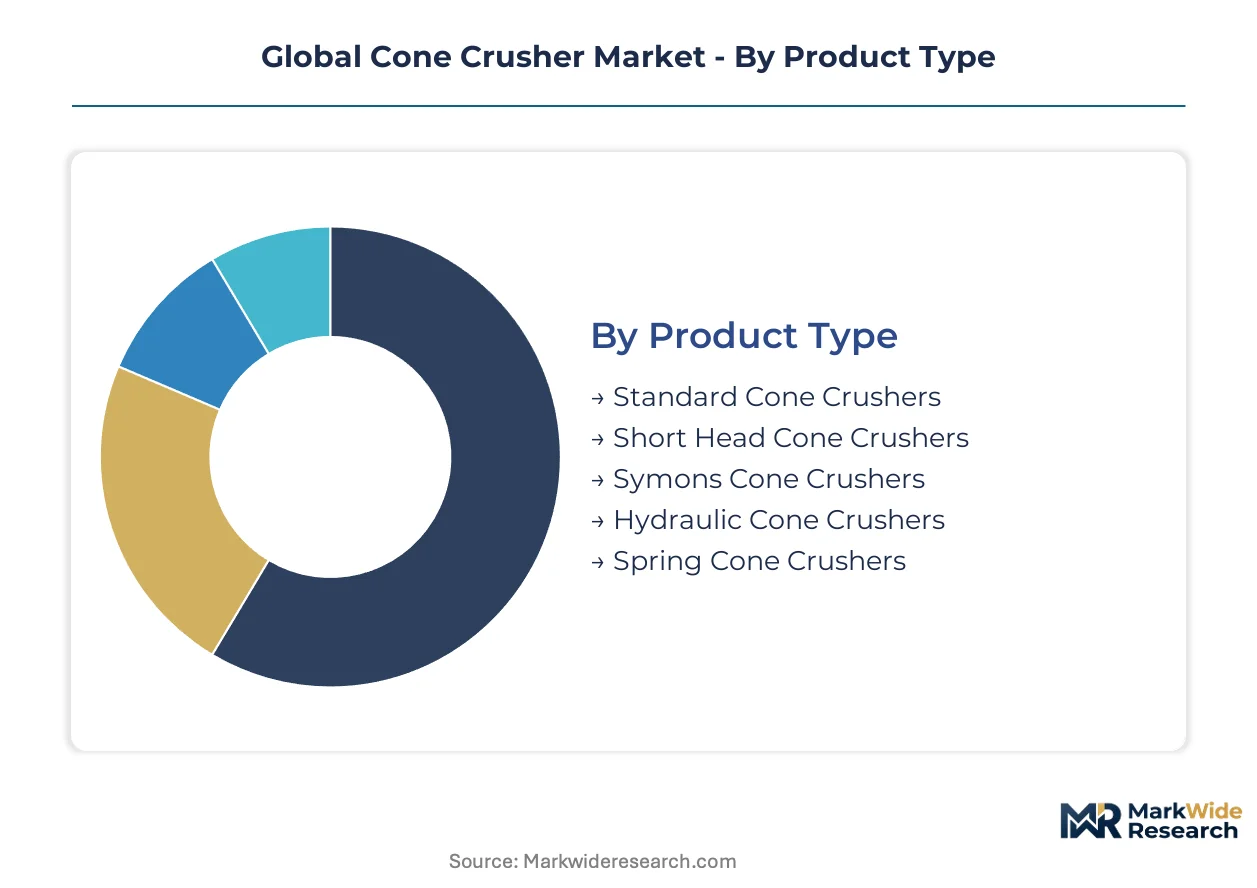
Cone crusher procurement patterns diverge sharply between standardized fleet replacements and engineered-to-order installations. Specification complexity rises with application severity, compressing supplier margins on commodity units while preserving premium pricing for customized crushing circuits.
Product Type:
Customization intensity spans from standardized spring designs to fully engineered hydraulic architectures with automated control integration.
- Hydraulic Cone Crushers:Automated setting adjustment and overload protection systems minimize unplanned downtime in hard rock tertiary circuits. Demand concentrates among Australian and Canadian quarry operators specifying VFD-equipped installations for variable feed rate matching.
- Standard Cone Crushers:Fixed mechanical configurations dominate high-volume aggregate production where feed characteristics remain consistent. Infrastructure developers in India and Brazil specify these units for highway construction programs requiring rapid deployment and lower capital intensity.
- Short Head Cone Crushers:Finer discharge gradations serve specialized mineral processing circuits.
- Symons Cone Crushers:Legacy design specifications persist in North American retrofit markets.
- Spring Cone Crushers:Mechanical overload protection suits emerging market budgets with limited maintenance infrastructure.
Most installed capacity flows through Standard Cone Crushers. Expansion is steepest in Hydraulic Cone Crushers.
Technology:
Cost tier differentiation separates commodity mechanical systems from integrated electrohydraulic architectures with predictive maintenance capability.
- Electrohydraulic System:Variable frequency drive integration enables real-time throughput optimization against upstream screening variability. Mining operators in Indonesia and Chile specify these configurations for nickel and copper processing circuits where feed consistency fluctuates.
- Hydraulic System:Conventional hydraulic power transmission remains the default specification for mobile crushing contractors prioritizing field serviceability. Brazilian federal highway concession projects standardize on these systems for fleet commonality across dispersed sites.
- Mechanical System:Direct drive architectures suit fixed plant installations with stable grid power.
- Hydraulic Hydroset:Automated CSS adjustment commands premium positioning in Scandinavian quarrying operations.
- Lubrication System:REACH-compliant biodegradable fluid specifications constrain European procurement cycles.
Technology selection tracks application maturity. Electrohydraulic adoption is climbing the fastest in greenfield mining investments.
Application:
Volume concentration in construction aggregates contrasts with margin concentration in metallurgical processing where specification tolerance tightens.
- Mining:Hard rock comminution circuits demand abrasion-resistant manganese steel configurations with extended liner life. Nickel and copper extractors in Indonesia's Sulawesi concessions specify hydraulic overload protection for uncrushable object events.
- Quarrying:Road base aggregate production drives the highest equipment turnover rates. India's Bharatmala project and Brazil's federal concessions are accelerating secondary crusher procurement for granite and basalt processing.
- Construction Aggregates:Specification-grade concrete aggregate requires precise gradation control.
- Metallurgy:Iron ore pellet feed preparation demands consistent particle size distribution.
- Chemical Industry:Fertilizer and industrial mineral applications specify corrosion-resistant liner materials.
Application mix varies by geography. Quarrying commands the largest installed base. Mining is gaining share fastest in Southeast Asian nickel expansion.
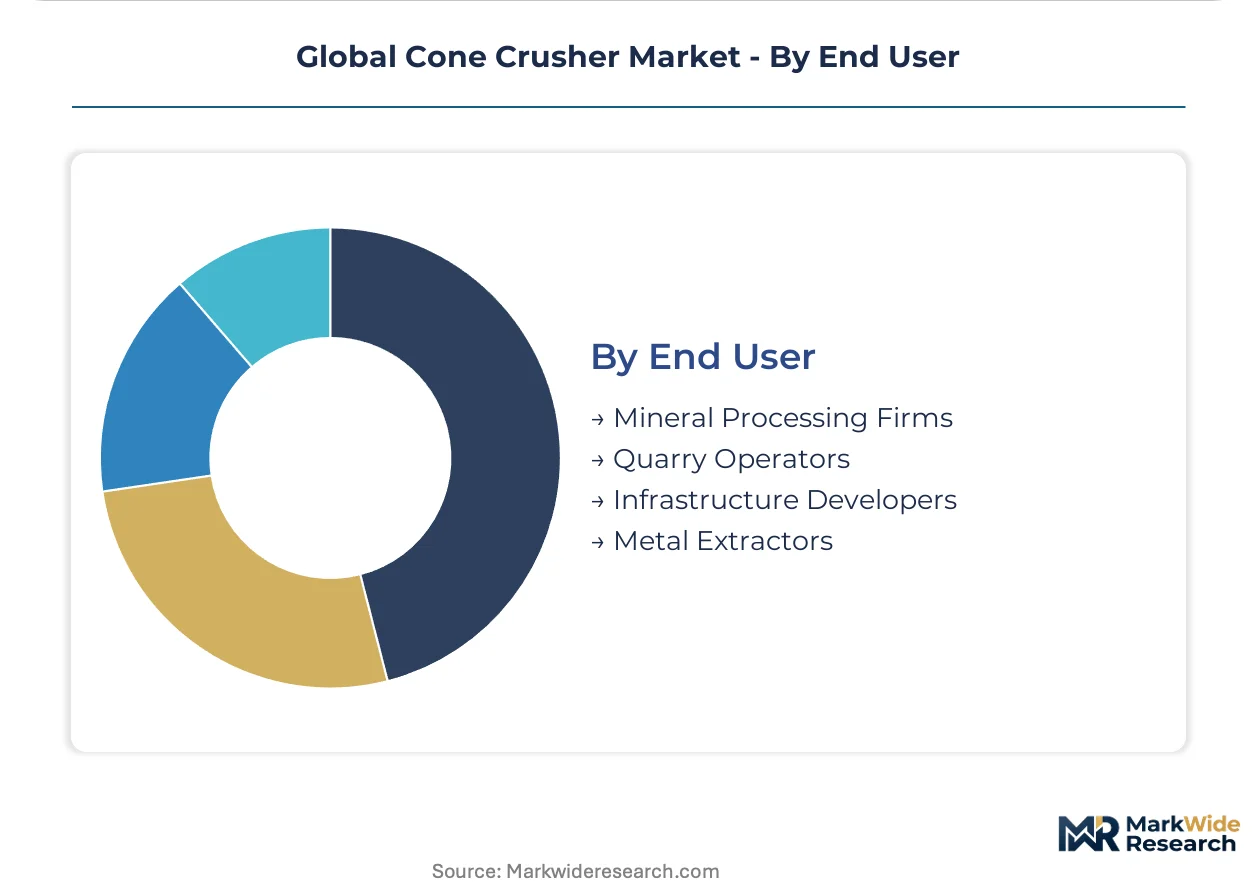
End User:
Customer type determines procurement modality, with mineral processing firms favoring long-term service contracts and infrastructure developers prioritizing capital efficiency.
- Quarry Operators:Fleet standardization across multiple sites drives preference for modular plant configurations with containerized installation. German and Scandinavian contractors negotiate component-level service agreements separate from equipment supply.
- Infrastructure Developers:Project-based procurement cycles compress decision timelines. India's highway construction programs specify rapid-deployment crushing circuits with minimized civil works requirements.
- Mineral Processing Firms:Integrated operations favor bundled maintenance contracts with OEM service networks.
- Metal Extractors:Copper and nickel producers in Indonesia and Chile specify automation-ready architectures for remote operation.
End user concentration sits with Quarry Operators. Procurement complexity is expanding most quickly among Infrastructure Developers with modular rental requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The cone crusher industry traces its modern scaling to Swedish and German engineering origins in the mid-20th century, with subsequent manufacturing expansion into North American and Asian production corridors. Equipment procurement patterns now diverge sharply between mature regulatory environments and emerging infrastructure investment cycles.
United States
Aggregate producers in Texas and Florida are replacing diesel-hydraulic fleets ahead of EPA Tier 4 Final compliance deadlines. The EPA's embedded emissions thresholds for federal highway projects are redirecting capital toward electrified crushing circuits. Quarry clusters around Atlanta and Phoenix specify automated setting adjustment to minimize downtime in granite processing.
Germany
REACH lubricant compliance requirements are extending procurement cycles for biodegradable hydraulic fluid validation. The EU Green Deal's carbon border adjustment mechanisms are pressuring equipment lessors in Bavaria and North Rhine-Westphalia to standardize on lower-lifecycle-emission configurations. Stuttgart-based engineering firms integrate predictive maintenance platforms into retrofit crushing circuits.
China
MEE dust control standards and dual carbon goals are reshaping import certification requirements for mineral processing equipment. Manufacturing clusters in Jiangsu and Shandong provinces supply standardized spring cone crushers for Belt and Road infrastructure projects across Southeast Asia. Zhengzhou and Shanghai house the dominant domestic fabrication capacity for quarry-grade installations.
India
The Bharatmala highway program and CEA efficiency mandates are accelerating secondary crusher procurement for granite and basalt aggregate production. Quarry operators in Karnataka and Tamil Nadu specify rapid-deployment modular configurations to minimize civil works timelines. Mumbai-based infrastructure developers negotiate component-level service agreements separate from equipment supply.
Brazil
Federal highway concession allocations are expanding aggregate processing capacity requirements in Minas Gerais and São Paulo states. ANVISA-aligned industrial safety protocols add compliance complexity for multinational equipment suppliers. Rio de Janeiro-based mining contractors specify hydraulic overload protection for nickel and copper processing circuits in emerging concessions.
Global Cone Crusher Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent value capture models. The vendor base concentrates among integrated engineering conglomerates with captive foundry capacity and specialized crushing equipment divisions. Three strategic archetypes dominate: full-line mineral processing houses, modular plant specialists, and regional fabrication champions serving emerging market price sensitivity. Consolidation pressure operates through aftermarket service network expansion and control system intellectual property acquisition rather than pure manufacturing scale.
Among Nordic engineering conglomerates, Metso Corporation and Sandvik AB exemplify the full-line archetype with integrated aftermarket service networks. Terex Corporation occupies a position within the North American modular plant configuration tier. Thyssenkrupp AG anchors German engineering heritage in heavy industrial crushing applications. FLSmidth & Co. A/S represents Danish specialization in mineral processing circuit integration. These named entities illustrate competitive positioning without implying specific strategic actions or market shares.
| Leading Market Players |
|---|
| Metso Corporation |
| Sandvik AB |
| Terex Corporation |
| Thyssenkrupp AG |
| FLSmidth & Co. A/S |
| McCloskey International |
| Astec Industries Inc. |
| Keestrack |
| Puzzolana |
| Others |
Supply & Pricing Matrix
Variable frequency drive adoption in cone crusher power transmission is simultaneously compressing mechanical component costs and shifting procurement concentration toward electrohydraulic system suppliers with integrated VFD capabilities. This technology transition is redistributing margin capture from traditional clutch manufacturers to drive system integrators while concentrating buyer leverage among Australian and Canadian quarry operators specifying real-time throughput optimization.
Pricing Analysis
Three-tier pricing structure across premium electrohydraulic, standard hydraulic, and economy mechanical configurations dominates equipment transactions. Price differentiation hinges on automation integration depth and CEA efficiency certification grade for Indian procurement. Cost compression in standard hydraulic tiers is intensifying because manganese steel liner plate volatility compresses manufacturer margins. Infrastructure developers in Brazil and India exhibit highest price sensitivity, while Indonesian nickel extractors prioritize overload protection premiums over capital outlay minimization.
Supply Chain Analysis
Regional distribution centers in Germany, China, and the United States anchor hub-and-spoke patterns for spare parts fulfillment. Manufacturing concentration rests on Swedish and German engineering heritage for precision components, Chinese fabrication capacity for standardized units, and Indian assembly operations for emerging market price points. Manganese steel alloy sourcing draws from South African and Gabonese ore deposits, creating single-source vulnerability for liner plate production. Distribution runs through OEM captive networks and independent aftermarket distributors serving mobile crushing contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through aftermarket service unbundling and premium-tier electrohydraulic conversion, justified by automation integration premiums that offset mechanical component commoditization.
For Market Incumbents: Acquire predictive maintenance software platforms to defend against unbundling pressure from Indonesian and Brazilian mining operators negotiating component-level service agreements separately from equipment supply. Build backward integration into manganese steel foundry capacity to insulate liner plate cost volatility. Prioritize EPA Tier 4 Final and EU Stage V certification investment to maintain engine supplier relationships amid procurement bottlenecks.
For New Entrants and Emerging Players: Launch via modular plant rental models targeting India's Bharatmala highway contractors with rapid-deployment crushing circuits that minimize civil works timelines. Penetrate the containerized installation segment where established OEMs lack fleet standardization flexibility. Exploit white space in REACH-compliant biodegradable hydraulic fluid integration for German and Scandinavian quarry operators facing extended procurement cycles.
For Investors and Strategic Acquirers: Roll-up economics work for regional aftermarket service specialists because OEM service revenue per unit is fragmenting across component-level agreements. Target mid-cap distributors with captive technical capabilities in Indonesia and Brazil where in-house maintenance teams are capturing margin previously retained by manufacturer networks. Watch automation integration complexity as the inflection signal—scarcity of IoT-enabled crusher control commissioning expertise in emerging markets indicates consolidation opportunity.
| Strategic Initiative | Industry Significance |
|---|---|
| Electrohydraulic System Integration | VFD-equipped installations command premium positioning in Australian and Canadian variable feed rate applications. |
| Backward Integration into Foundry Capacity | Captive manganese steel liner production insulates margin compression from commodity alloy volatility. |
| Modular Plant Configuration Expansion | Containerized crushing circuits open contractor rental markets in India's Bharatmala infrastructure program. |
| Predictive Maintenance Platform Acquisition | Software-defined optimization absorbs capital allocation previously targeting mechanical reliability improvements. |
| REACH-Compliant Fluid Certification | Biodegradable hydraulic validation accelerates procurement cycles for German and Scandinavian fleet standardization. |
Research Methodology
Direct dialogue with quarry operations managers, mineral processing plant engineers, aftermarket service directors, and infrastructure procurement leads grounded primary intelligence. Secondary validation drew from EPA emissions filings, EU ETS compliance databases, Indian CEA efficiency certifications, and customs trade records for crushing equipment imports. Bottom-up equipment deployment tallies triangulated against top-down aggregate demand modeling from highway construction and mining concession allocations.
Bottom-up volume estimates by product type, technology tier, application severity, and end-user procurement modality fed into analytical framework construction across the analysis window. Segmentation modeling incorporated drive system architecture, automation integration depth, and regional regulatory cluster variations. CAGRs derived from equipment replacement cycle compression under electrification mandates and greenfield mining investment trajectories in nickel and copper extraction.
Forecast precision tightens around the base case; tail outcomes carry wider variance under manganese steel price spikes, engine supplier concentration disruptions, or accelerated EU carbon border adjustment implementation. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Construction Power Rental Market
Construction Equipment
Europe Construction Equipment Rental Market
Construction Equipment
Separation Machinery Market
Construction Equipment
Cable Winches Market
Construction Equipment
Grout Bags Market
Construction Equipment
Spray Washer Market
Construction Equipment
North America Welding Equipment Market
Construction Equipment
Brazil Metal Fabrication Equipment Market
Construction Equipment
Bitumen Testing Equipment Market
Construction Equipment
Stamping Machines Market
Construction Equipment
Excavator Wheels Market
Construction Equipment
Electrofusion Welding Machines Market
Construction Equipment
South Korea Aerial Work Platform (AWP) Rental Market
Construction Equipment
North America Mini and Midi Horizontal Directional Drilling Market
Construction Equipment
Street Cleaning Machine Market
Construction Equipment
Thailand Construction Equipment Market