
 Biopatches Market | 2026-2036
Biopatches Market Size, Share, and Industry Trends Forecast 2026-2036
Biopatches Market Insights
North American contract manufacturers is recalibrating cleanroom capacity to meet surging biopatch substrate orders. Abbott Laboratories anchors its position through backward integration into biodegradable polymer sourcing. Philips competes by leveraging its diagnostic imaging heritage to bundle sensor-enabled patches with enterprise software.
Biopatches are adhesive dermal substrates, typically 50-200 microns thick, engineered from silicone or polyurethane matrices with integrated conductive traces or drug reservoirs for localized therapeutic delivery or physiological monitoring. Smart Biopatches now command premium positioning as cardiac and glucose monitoring applications migrate from clinic to home settings, while Hydrogel Biopatches sustain volume leadership in wound healing due to superior moisture retention and biocompatibility profiles. The Application dimension shows Chronic Pain Management representing the fastest-expanding margin pool as opioid-sparing protocols gain clinical traction.
The FDA's breakthrough device designation pathway accelerates market access for novel sensor-integrated platforms, while the EU MDR's post-market surveillance requirements force manufacturers to maintain clinical follow-up registries. ISO 10993 biocompatibility testing standards govern material selection across all commercial jurisdictions, creating compliance barriers for new entrants. Stakeholders must decide whether to prioritize regulatory harmonization investments or pursue geography-specific certification strategies.
Market Dynamics
The EU Medical Device Regulation's tightened clinical evidence requirements are forcing manufacturers to rebuild post-market surveillance infrastructure, while Medicare reimbursement pathways in the United States accelerate ambulatory adoption of sensor-integrated platforms.
Growth Catalysts
- Medicare Remote Patient Monitoring Reimbursement:The Centers for Medicare & Medicaid Services expanded CPT codes for continuous physiological monitoring, enabling hospital-at-home programs to procure smart biopatches at scale.
- EU MDR Post-Market Surveillance Mandate:Germany's university hospitals now require sensor-enabled patches with embedded clinical registries to satisfy tightened clinical evidence requirements for Class IIa and above devices.
- Biodegradable Polymer Maturation:Advances in polylactic acid and polycaprolactone substrates reduce environmental liability while extending wear time for chronic pain management applications.
Market Restraints
- Conductive Ink Supply Concentration:Silver nanowire production concentrates in East Asian chemical processors, exposing contract manufacturers to input volatility and dual-use export controls.
- ISO 10993 Testing Burden:Cytotoxicity and sensitization protocols for novel hydrogel formulations extend certification timelines by 14-18 months for new entrants.
- Reusable Patch Substitutes:Traditional Holter monitors and continuous glucose monitors with replaceable sensors retain cost advantages in price-sensitive institutional procurement.
Strategic Opportunities
- India's PLI Scheme for Medical Devices:Production-linked incentives for electronics manufacturing services create localized substrate fabrication capacity for export to Middle Eastern and African markets.
- Opioid-Sparing Protocol Expansion:Transdermal lidocaine and capsaicin reservoirs gain formulary inclusion in US accountable care organizations seeking to reduce post-surgical opioid dispensing.
- AI-Enabled Predictive Analytics Convergence:Machine learning models trained on patch-derived physiological signals enable early deterioration alerts, creating software-recurring revenue streams alongside hardware sales.
Industry Challenges
- Cleanroom Technician Scarcity:Contract manufacturers in Massachusetts and North Carolina compete for operators qualified in ISO 14644 Class 7 environments capable of handling 50-micron substrate tolerances.
- Legacy EHR Integration Complexity:Hospital IT departments face middleware development costs to normalize biopatch data streams into Epic and Cerner workflows, delaying pilot-to-scale transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biopatches Market |
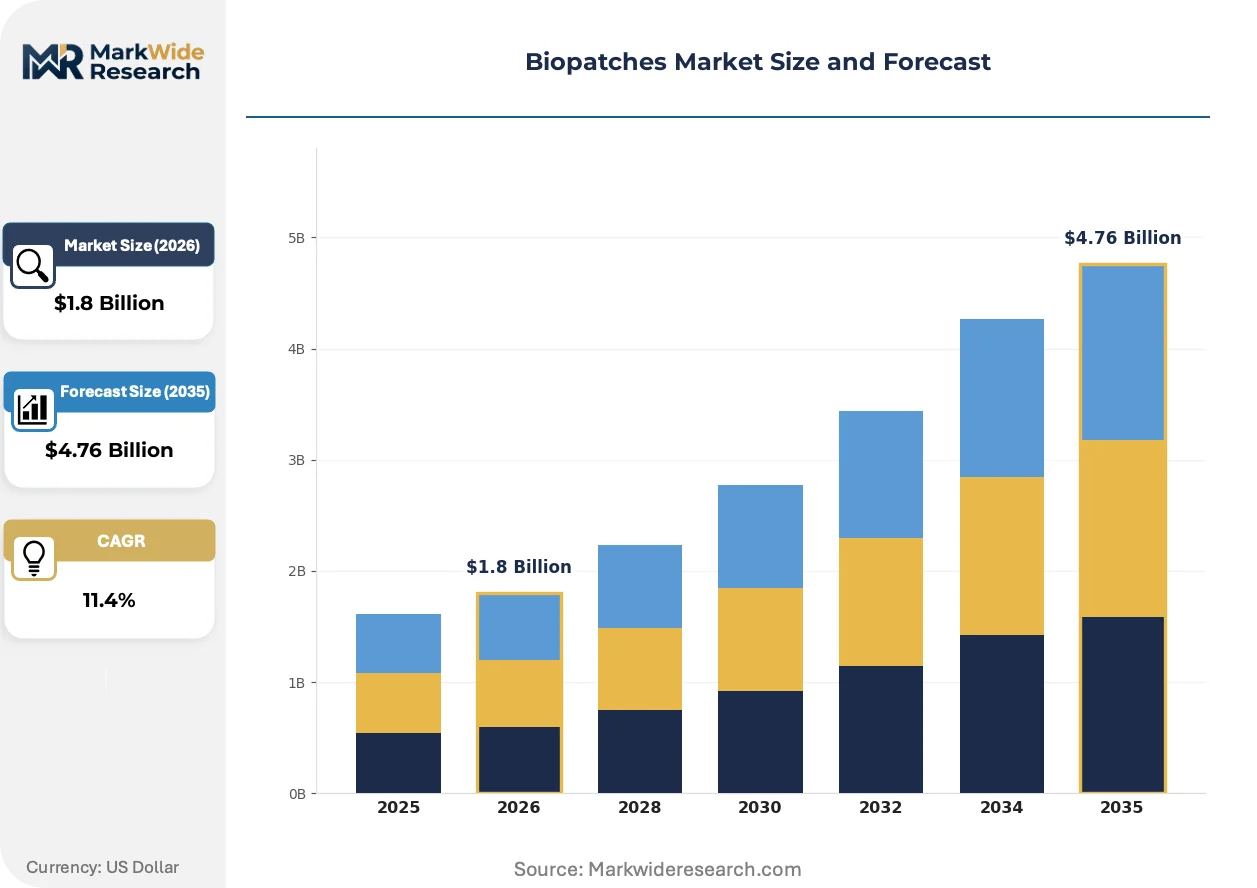
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional Biopatches, Smart Biopatches, Hydrogel Biopatches, Patch with Sensor Application: Wound Healing, Drug Delivery, Chronic Pain Management, Infection Control End User: Hospitals, Home Care, Clinics, Ambulatory Surgical Centers Material: Silicone, Gelatin, Polyurethane, Biodegradable Polymers |
| Companies Covered | 3M, Koninklijke Philips, GE Healthcare, MC10, iRhythm Technologies, Insulet Corporation, Abbott Laboratories, Johnson & Johnson, Samsung Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biopatches Market Trends and Innovations
Biopatch architecture is converging toward multifunctional platforms that merge therapeutic delivery with continuous monitoring, compressing the distinction between drug-device combination products and standalone diagnostics.
Microfluidic sampling technology is automating interstitial fluid extraction for real-time biomarker analysis. Academic medical centers in California and Texas are piloting glucose-lactate dual-analyte patches for sepsis surveillance in oncology wards. This convergence is automating the shift from scheduled laboratory draws to continuous metabolic monitoring, reducing inpatient length-of-stay for high-risk surgical populations.
REACH restrictions on persistent organic pollutants are compelling European substrate suppliers to reformulate silicone adhesives. The European Chemicals Agency's 2023 amendment to Annex XVII limits certain phthalate plasticizers in dermal contact applications. German and Dutch manufacturers are responding by accelerating bio-based polyurethane development, with first commercial volumes expected for wound healing segments.
Hospital procurement committees are consolidating vendor relationships around enterprise platform contracts rather than point-product purchasing. Integrated delivery networks in Florida and Pennsylvania now require biopatch suppliers to bundle hardware, cloud analytics, and clinical decision support under multi-year agreements. This preference consolidation most visibly disadvantages single-product startups lacking software development capabilities.
Biopatches Market Segmentation
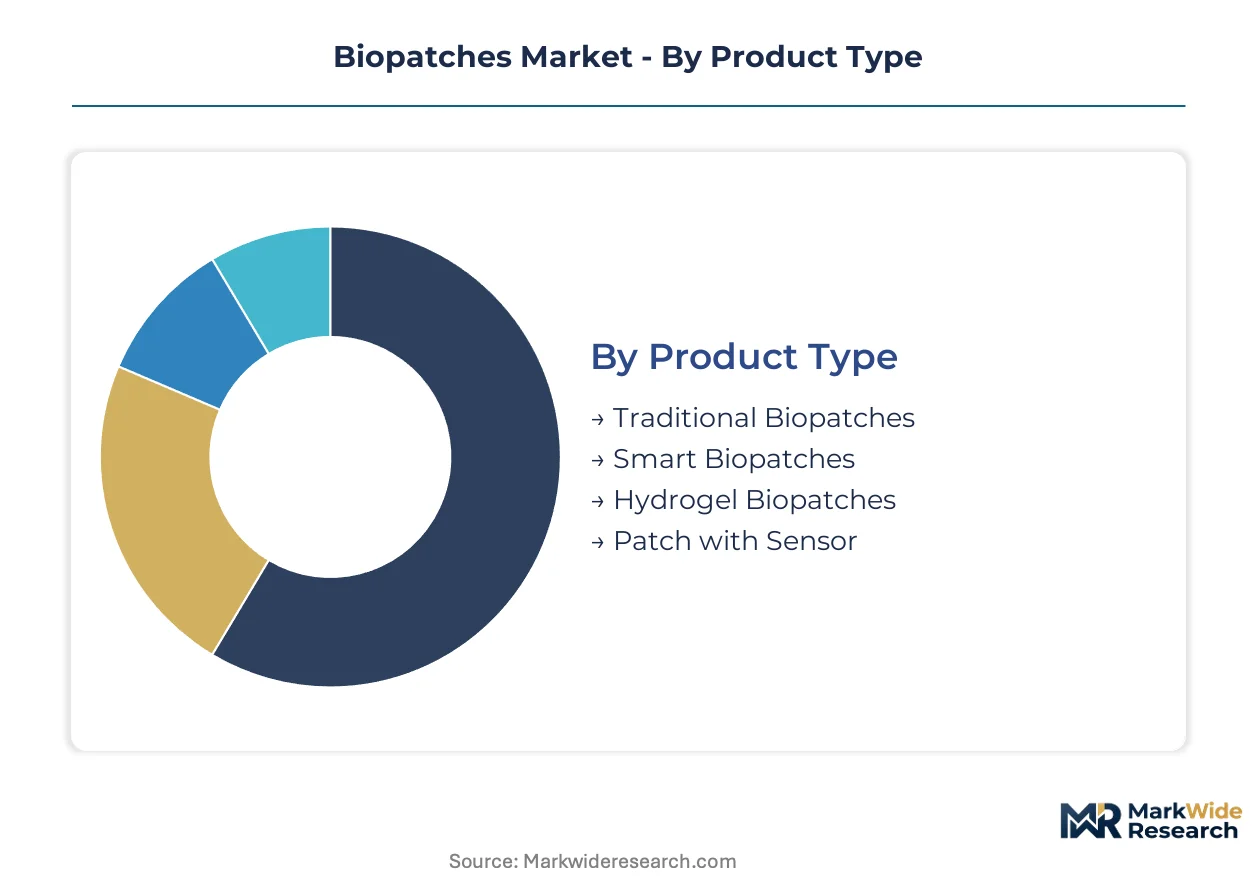
Biopatch purchasing decisions pivot on whether facilities are replacing legacy adhesive substrates or upgrading to sensor-integrated platforms. Upgrade cycles vary dramatically by care setting, with hospital systems consolidating around enterprise contracts while home care channels fragment across specialized suppliers.
Product Type:
Replacement dynamics differ sharply between commodity substrates and connected platforms, as reimbursement pathways and clinical evidence requirements reshape procurement priorities.
- Smart Biopatches:These integrate conductive traces, microprocessors, and wireless transmitters within 50-200 micron silicone or polyurethane matrices for real-time physiological streaming. Medicare CPT code expansion for remote patient monitoring is accelerating hospital-at-home procurement in the United States, though EU MDR clinical evidence requirements extend certification timelines for new entrants.
- Hydrogel Biopatches:Cross-linked polymer networks with 60-90% water content deliver superior moisture retention and biocompatibility for extended wear. Volume leadership persists in wound healing applications across German university hospitals, where post-surgical monitoring protocols favor hydrogel moisture management over sensor integration for standard cases.
- Traditional Biopatches:Passive adhesive substrates without electronic components serve cost-sensitive institutional procurement.
- Patch with Sensor:Single-analyte detection platforms for glucose or cardiac markers occupy a transitional technology position.
Volume placements concentrate in Hydrogel Biopatches; the faster expansion belongs to Smart Biopatches.
Application:
Clinical workflow integration determines margin capture, with applications requiring continuous monitoring commanding premium pricing over episodic interventions.
- Chronic Pain Management:Transdermal reservoirs of lidocaine, capsaicin, or fentanyl alternatives deliver localized analgesia through 72-hour wear cycles. US accountable care organizations are expanding formulary inclusion for opioid-sparing protocols, driving procurement volume as surgical networks seek to reduce post-operative dispensing.
- Wound Healing:Moisture-retentive substrates with exudate management layers dominate standard-of-care protocols in post-acute settings. German and Dutch hospital procurement committees specify bio-based polyurethane alternatives as REACH Annex XVII restrictions phase out legacy phthalate plasticizers.
- Drug Delivery:Controlled-release matrices for hormones, nicotine, or cardiovascular agents serve established therapeutic categories.
- Infection Control:Antimicrobial-impregnated substrates with silver or iodine reservoirs address surgical site prophylaxis.
Revenue concentration sits with Wound Healing; Chronic Pain Management is climbing the fastest.
End User:
Capital intensity and regulatory exposure separate institutional procurement from consumer-directed channels, with reimbursement policy as the decisive segmentation variable.
- Hospitals:Integrated delivery networks in Florida and Pennsylvania consolidate vendor relationships around enterprise platform contracts bundling hardware, cloud analytics, and clinical decision support. Epic and Cerner middleware integration requirements favor established suppliers with dedicated health IT engineering teams.
- Home Care:Direct-to-patient distribution channels bypass institutional procurement committees, though Medicare reimbursement pathways determine addressable market scale. Continuous glucose and cardiac monitoring applications are migrating fastest to this channel as remote patient monitoring CPT codes mature.
- Clinics:Physician office laboratories and specialty practices favor single-analyte platforms with minimal IT infrastructure requirements.
- Ambulatory Surgical Centers:Same-day discharge protocols drive demand for 24-48 hour post-operative monitoring substrates.
Procurement volume aggregates in Hospitals; Home Care is expanding most quickly.
Material:
Environmental liability and wear-time extension are reshaping substrate selection, with biodegradable alternatives displacing conventional petroleum-derived matrices in premium applications.
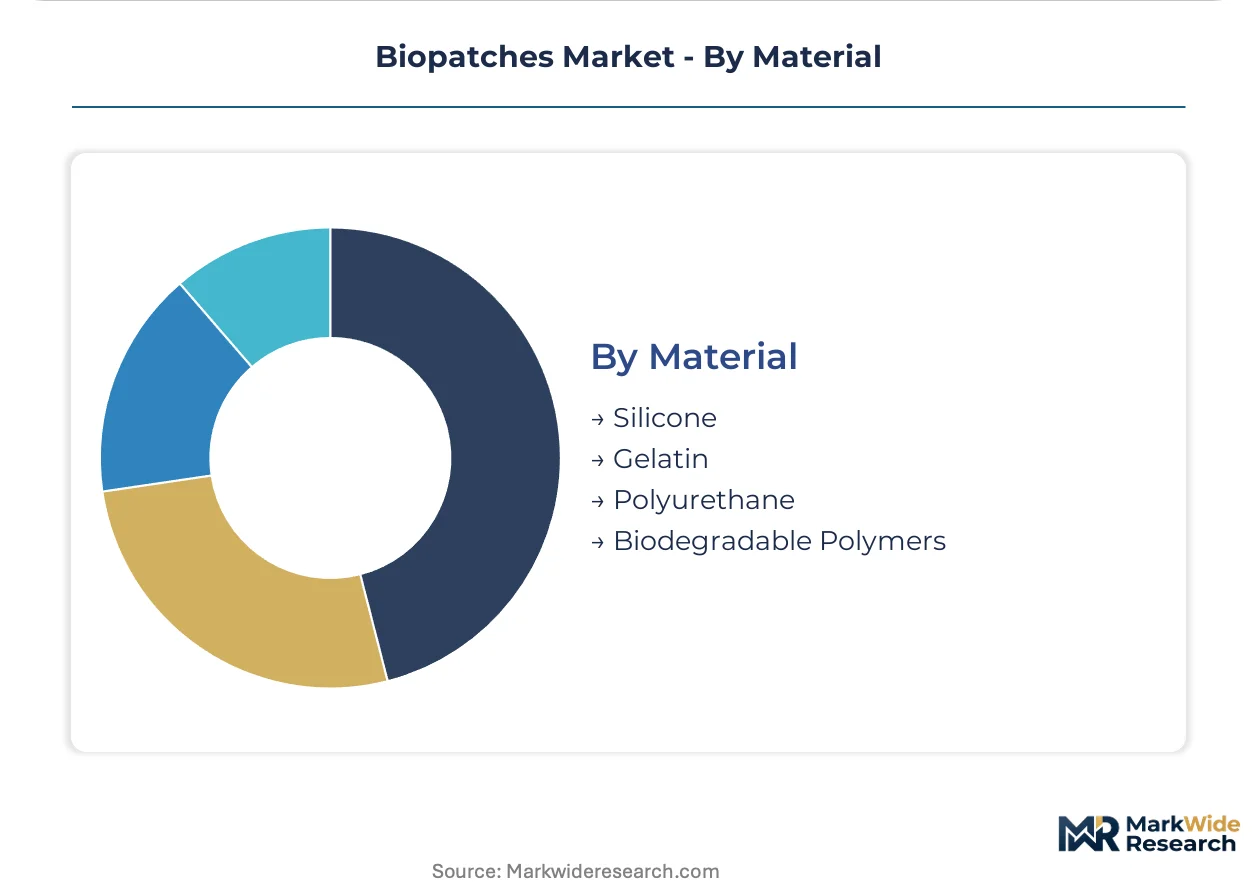
- Biodegradable Polymers:Polylactic acid and polycaprolactone substrates degrade through hydrolysis within 30-90 days, eliminating retrieval procedures and reducing environmental liability. Abbott Laboratories anchors supply security through backward integration into polymer sourcing, while REACH restrictions accelerate European manufacturer migration from silicone alternatives.
- Silicone:Medical-grade polydimethylsiloxane adhesives deliver 7-14 day wear times with minimal skin irritation. Massachusetts and North Carolina contract manufacturers face ISO 14644 Class 7 cleanroom technician scarcity as production scales to meet sensor-integrated substrate demand.
- Polyurethane:Breathable film-backed substrates balance moisture vapor transmission with liquid barrier properties.
- Gelatin:Collagen-derived matrices serve hemostatic and wound scaffolding applications with limited wear-time requirements.
Silicone retains volume leadership; Biodegradable Polymers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silver nanowire production concentrates in East Asian chemical processors, exposing contract manufacturers to input volatility while Medicare reimbursement pathways and EU MDR requirements reshape demand geography across the United States, Germany, India, China, and Japan.
United States
Medicare CPT code expansion for remote patient monitoring accelerates hospital-at-home procurement of sensor-integrated platforms. FDA breakthrough device designation pathways compress market access timelines for novel cardiac and glucose monitoring substrates. Massachusetts and North Carolina contract manufacturers compete for ISO 14644 Class 7 cleanroom technicians as production scales to meet 50-micron substrate tolerances.
Germany
University hospitals expand procurement of smart biopatches for post-surgical monitoring to satisfy EU MDR tightened clinical evidence requirements for Class IIa and above devices. REACH Annex XVII restrictions on phthalate plasticizers compel substrate suppliers to reformulate silicone adhesives toward bio-based polyurethane alternatives. The Baden-Württemberg industrial cluster anchors biodegradable polymer development for wound healing applications.
India
Production-linked incentives for electronics manufacturing services create localized substrate fabrication capacity targeting Middle Eastern and African export markets. CDSCO medical device regulations harmonize with ISO 10993 biocompatibility testing standards, extending certification timelines for hydrogel formulations. Karnataka and Telangana host emerging cleanroom facilities serving contract manufacturing demand.
China
Dual carbon goals and environmental liability reduction drive polylactic acid and polycaprolactone substrate adoption for extended wear applications. NMPA medical device registration requirements govern conductive trace integration within silicone matrices. The Yangtze River Delta concentrates silver nanowire processing capacity, exposing downstream fabricators to dual-use export control exposure.
Japan
PMDA regulatory frameworks emphasize post-market surveillance infrastructure alignment with global ISO standards for chronic pain management applications. METI industrial policy supports microfluidic sampling technology development for real-time biomarker analysis. The Kanto region around Tokyo anchors diagnostic imaging heritage convergence with sensor-enabled patch platforms.
Biopatches Market Competitive Landscape
Global majors compete with regional champions across regulatory compliance and health IT integration capabilities. The vendor base organizes around three tiers: diversified conglomerates with backward polymer integration, diagnostic imaging heritage players bundling enterprise software, and specialized sensor-integrated platform developers. Competitive moves concentrate on strategic partnerships with integrated delivery networks and capacity expansion into India's PLI-subsidized manufacturing zones.
Among diversified healthcare conglomerates, 3M and Abbott Laboratories exemplify scale-driven substrate suppliers with captive supply chain control over biodegradable polymer sourcing. Koninklijke Philips occupies a position bridging diagnostic imaging heritage with enterprise software bundling strategies. These three anchors represent distinct competitive archetypes: materials science depth, vertical integration, and platform ecosystem integration.
| Leading Market Players |
|---|
| 3M |
| Koninklijke Philips |
| GE Healthcare |
| MC10 |
| iRhythm Technologies |
| Insulet Corporation |
| Abbott Laboratories |
| Johnson & Johnson |
| Samsung Electronics |
| Others |
Pricing and Supply Chain Analysis
Smart-hydrogel performance divergence splits procurement committees between premium sensor-integrated platforms and commodity moisture-retentive substrates, with EU MDR certification tiers determining both price premiums and supplier qualification hurdles. German university hospitals pay substantial uplifts for embedded clinical registry capabilities, while cost-sensitive ambulatory surgical centers in Florida and Pennsylvania source traditional substrates through group purchasing organizations.
Pricing Analysis
Warranty and cloud analytics bundling separates enterprise platform contracts from transactional hardware sales, with multi-year agreements commanding 40-60% price premiums over spot procurement. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 10993 biocompatibility certification depth and FDA breakthrough device designation status. Cost compression in traditional substrates is intensifying because reusable Holter monitors retain institutional preference for episodic monitoring. Ambulatory surgical centers exhibit highest price sensitivity; integrated delivery networks with dedicated health IT engineering teams show lowest.
Supply Chain Analysis
ISO 14644 Class 7 cleanroom qualification gates substrate fabrication capacity, with Massachusetts and North Carolina contract manufacturers competing for qualified technicians. Silver nanowire production concentrates in China, South Korea, and Japan, exposing downstream fabricators to dual-use export control exposure. Biodegradable polymer feedstock draws from polylactic acid and polycaprolactone suppliers in Germany and the Netherlands. Single-source vulnerability concentrates in East Asian conductive ink processors. Distribution runs through integrated delivery network enterprise contracts and specialized medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where EU MDR post-market surveillance mandates create barrier-to-entry moats for manufacturers with established clinical follow-up registries.
For Market Incumbents: Lock in supply security through backward integration into biodegradable polymer sourcing, mirroring Abbott Laboratories' captive supply strategy. Expand ISO 14644 Class 7 cleanroom capacity in Massachusetts and North Carolina before technician scarcity worsens. Defend against single-product startups by bundling hardware, cloud analytics, and clinical decision support under multi-year enterprise contracts with integrated delivery networks.
For New Entrants and Emerging Players: Begin with India's PLI-subsidized manufacturing zones to establish substrate fabrication capacity for Middle Eastern and African export markets. Target chronic pain management applications in US accountable care organizations seeking opioid-sparing protocols, as transdermal lidocaine and capsaicin reservoirs gain formulary inclusion. Pursue direct-to-patient distribution channels bypassing institutional procurement committees.
For Investors and Strategic Acquirers: Re-rating potential sits with diagnostic imaging heritage players given convergence with sensor-enabled patch platforms and enterprise software bundling strategies. Long-term viability favors manufacturers with demonstrated EU MDR compliance infrastructure and Epic-Cerner middleware integration capabilities. Watch AI-enabled predictive analytics convergence as the inflection indicator for software-recurring revenue multiples.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerates market access timelines for novel cardiac monitoring substrates in US hospital-at-home programs. |
| EU MDR Post-Market Surveillance Infrastructure | Creates compliance moat for Class IIa and above devices through embedded clinical registries. |
| Backward Integration into Biodegradable Polymers | Secures polylactic acid and polycaprolactone supply chains against REACH restriction volatility. |
| Hospital System Enterprise Contracting | Consolidates vendor relationships around bundled hardware, cloud analytics, and clinical decision support. |
| AI-Enabled Predictive Analytics Development | Enables early deterioration alerts and software-recurring revenue streams alongside hardware sales. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with hospital procurement managers, biomedical engineers, GPO contracts managers, and regulatory affairs leads at substrate manufacturers. FDA 510(k) filings, EU MDR technical documentation, CMS Medicare reimbursement databases, and ISO 10993 biocompatibility testing records provided validation layers. Bottom-up demand modeling across end-user segments triangulated against top-down market sizing from trade association aggregates.
Granularity-level modeling operated at product type, application, end user, material, and regional regulatory cluster dimensions across the analysis window. CAGRs derived from segment-level volume trajectories weighted by reimbursement pathway maturity and certification timeline differentials. Forecast inputs incorporated Medicare CPT code expansion schedules, EU MDR transition deadlines, and India's PLI scheme capacity buildout timelines.
Underlying measurement precision varies by segment; smart biopatches with established reimbursement pathways carry tighter precision than emerging microfluidic sampling applications. Forecasts reflect assumptions regarding regulatory harmonization progress and cleanroom technician availability. A model refresh is warranted upon material change in FDA breakthrough device designation velocity or EU MDR enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Chronic Wound Care Market
Wound Care
Asia Pacific Negative Pressure Wound Therapy Market
Wound Care
Smart Bandages and Smart Wound Dressings Market
Wound Care
Japan Wound Care Management Devices Market
Wound Care
Pressure Bandages Market
Wound Care
Wound Closure Devices Market
Wound Care
Autologous Wound Patches Market
Wound Care
Vascular Dressings Market
Wound Care
Non-Invasive Surgical Wound Closure Market
Wound Care
Enzymatic Wound Debridement Market
Wound Care
Infectious Wound Care Management Market
Wound Care
Single-Use Negative Pressure Wound Therapy Devices Market
Wound Care
Burn Care Centers Market
Wound Care
Advanced Wound Therapy Devices Market
Wound Care
Venous Leg Ulcer (VLU) Treatment Market
Wound Care
Anti-Biofilm Wound Dressing Market