
 Europe Negative Pressure Wound Therapy Market | 2026-2036
Europe Negative Pressure Wound Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Negative Pressure Wound Therapy Market Intelligence
Buyer concentration across European hospital procurement consortia is broadening as national purchasing alliances consolidate tender volumes while independent homecare agencies fragment the post-acute channel. Smith & Nephew plc leverages its direct-to-institutional sales infrastructure across the United Kingdom and Germany. Medela AG anchors its position through specialized negative pressure pumps engineered for ambulatory settings. Molnlycke Health Care AB competes via integrated wound dressing portfolios paired with therapy devices.
Negative Pressure Wound Therapy applies sub-atmospheric pressure through sealed foam or gauze dressings to accelerate granulation tissue formation, typically operating at continuous or intermittent pressures between 50 and 125 mmHg. The primary commercial purpose centers on reducing edema, promoting perfusion, and enabling faster closure of acute and chronic wounds in surgical and outpatient environments. Portable NPWT systems capture expanding margin pools as homecare reimbursement expands across European social insurance frameworks. Single-use NPWT devices represent the fastest-growing product configuration, driven by infection control priorities and simplified logistics in long-term care facilities. Digital Monitoring Systems within the technology dimension attract R&D investment as remote pressure verification and adherence tracking align with value-based procurement criteria.
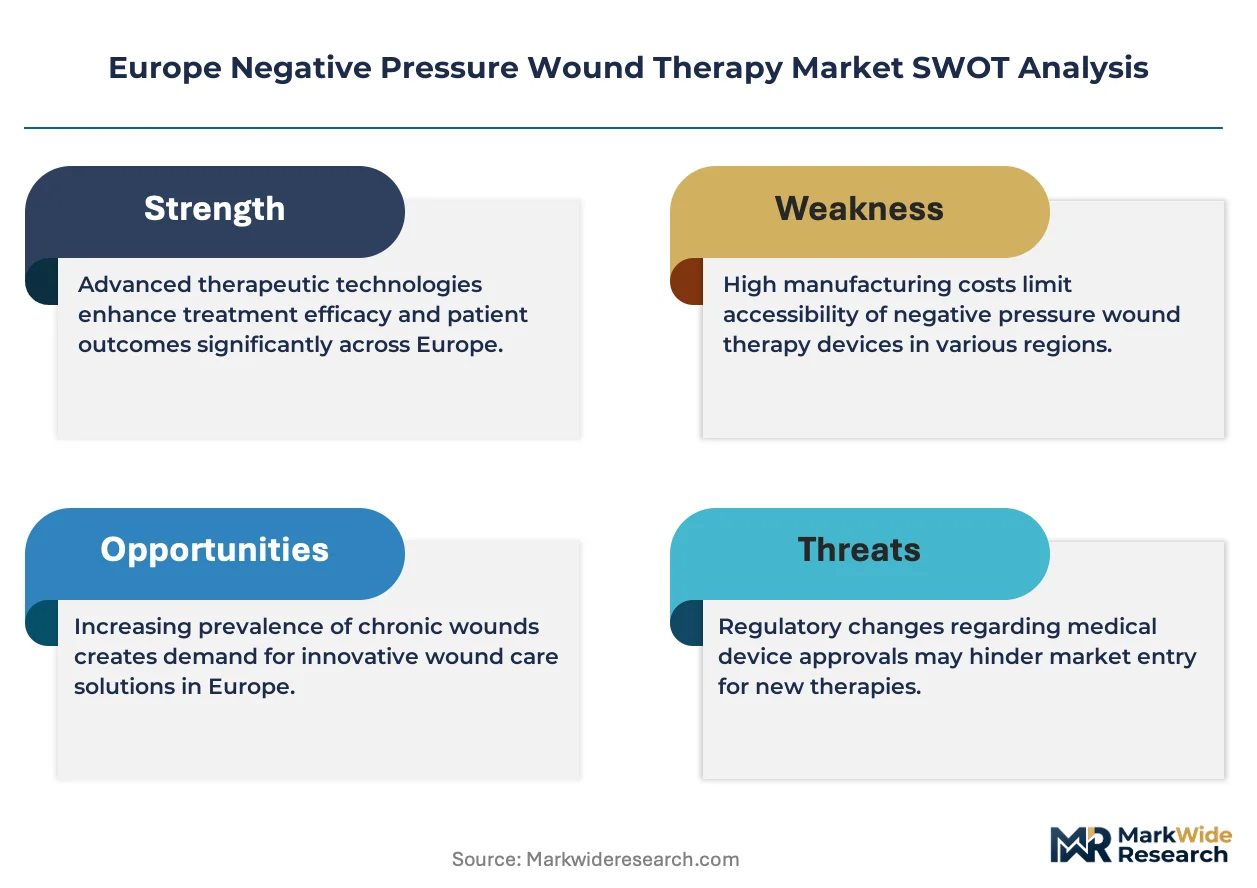
The EU Medical Device Regulation and CE marking framework impose escalating clinical evidence requirements on active wound therapy devices, extending approval timelines and favoring established manufacturers with robust quality management systems. Germany's national reimbursement authority, the G-BA, shapes demand through its innovation funding pathway for outpatient NPWT, while France's ANSM enforces post-market surveillance standards that influence product design specifications. Stakeholders must monitor how evolving HTA assessments across European sickness funds recalibrate the cost-effectiveness threshold for disposable versus reusable system configurations.
Market Dynamics
The EU Medical Device Regulation is compressing approval timelines for active wound therapy devices while simultaneously elevating clinical evidence thresholds, forcing manufacturers to restructure quality management systems and regulatory affairs staffing.
Growth Catalysts
- Outpatient reimbursement expansion:Germany's G-BA innovation funding pathway now covers portable NPWT for homecare settings, accelerating procurement volumes outside hospital walls.
- Infection control mandates:Long-term care facilities across France and the Netherlands are prioritizing single-use disposable systems to reduce cross-contamination risks in multi-patient environments.
- Granulation acceleration protocols:Continuous sub-atmospheric pressure therapy between 50-125 mmHg is displacing conventional moist wound healing in post-surgical recovery pathways.
Market Restraints
- Polymer supply concentration:Medical-grade polyurethane foam for sealed dressings relies heavily on German and Belgian chemical processors, creating input vulnerability.
- CE marking timeline extension:The EU MDR's enhanced clinical evaluation requirements for active devices have lengthened conformity assessment durations by 12-18 months.
- Conventional moist therapy substitution:Advanced hydrocolloid and alginate dressings retain cost advantages for superficial wounds in budget-constrained Southern European markets.
Strategic Opportunities
- Polish and Romanian homecare penetration:These markets show sub-15% NPWT utilization rates for chronic venous ulcers despite expanding social insurance coverage.
- Digital pressure monitoring convergence:Integration of Bluetooth-enabled pressure sensors with electronic health record systems enables remote adherence verification.
- Reusable pump refurbishment channels:Circular economy incentives under the EU Green Deal support certified remanufacturing programs for hospital-grade devices.
Industry Challenges
- Clinical evidence generation capacity:The EU MDR's requirement for prospective clinical data on active wound devices strains biostatistics and regulatory affairs talent pools.
- Multi-site quality system harmonization:Manufacturers must synchronize ISO 13485-compliant processes across distributed production facilities while maintaining batch traceability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Negative Pressure Wound Therapy Market |
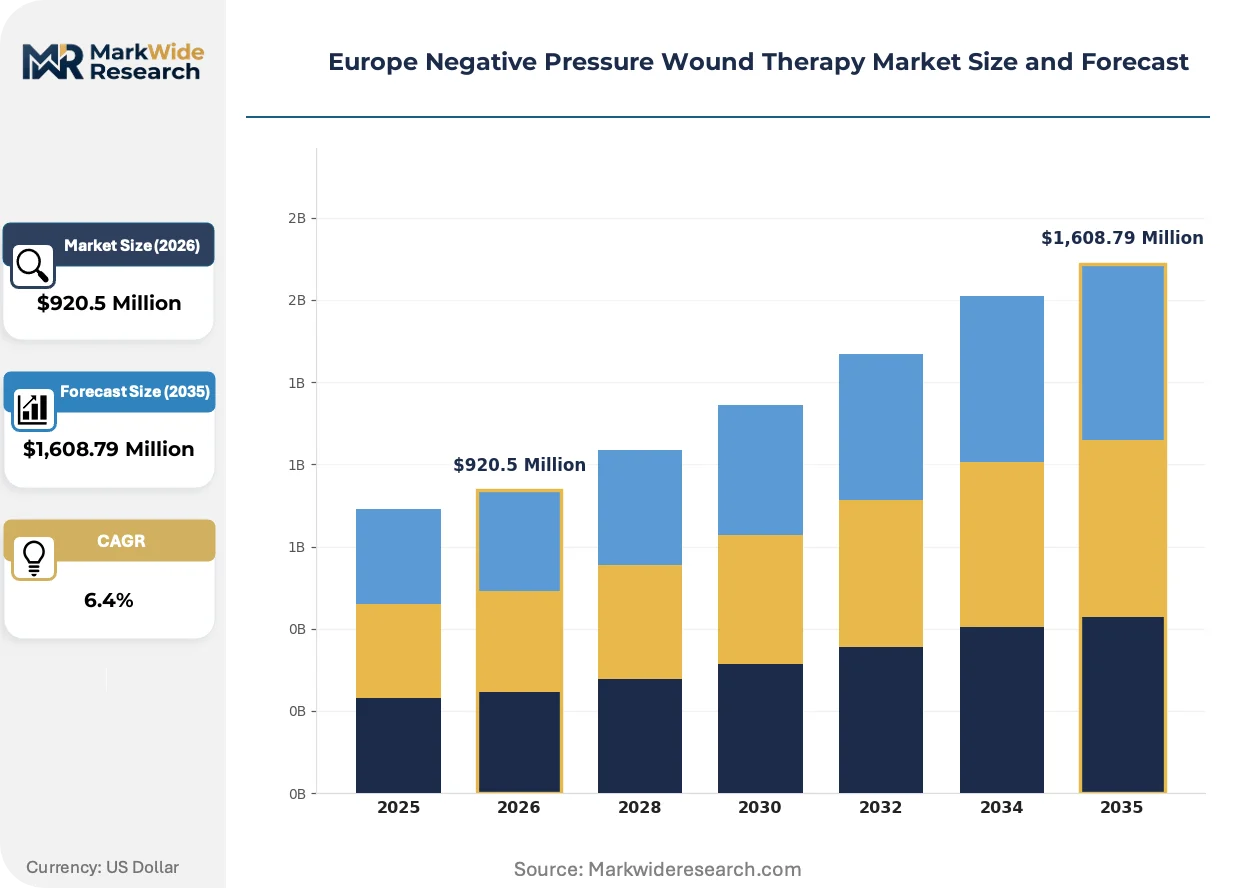
| Market Size in 2026 | $920.5 Million |
| Market Size in 2035 | $1,608.79 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
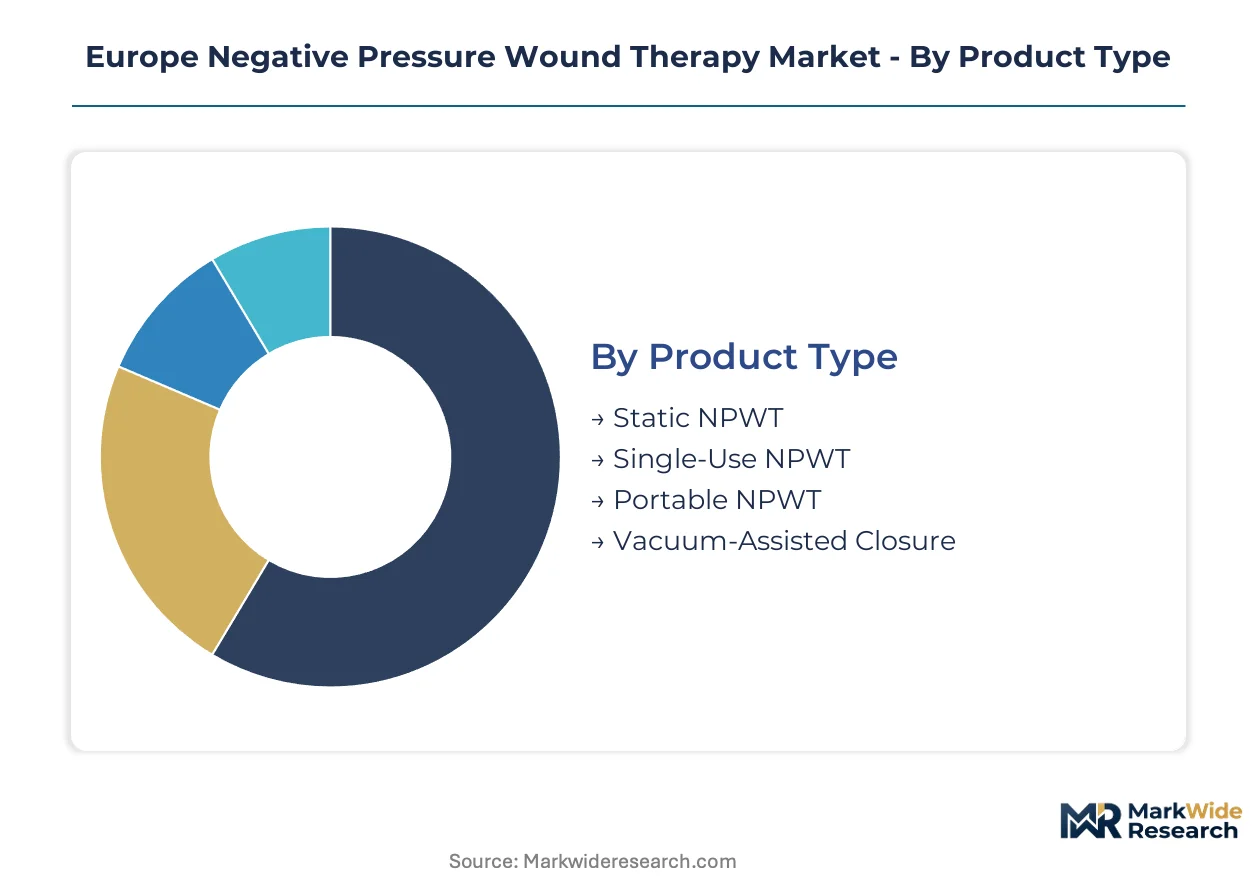
| Segmentation | Product Type: Static NPWT, Single-Use NPWT, Portable NPWT, Vacuum-Assisted Closure End User: Hospitals, Homecare, Specialty Clinics, Long-Term Care Facilities Application: Surgical Wounds, Chronic Wounds, Traumatic Wounds, Burn Wounds Technology: Electromechanical Systems, Disposable Systems, Digital Monitoring Systems, Manual Systems |
| Companies Covered | Cardinal Health, Inc., Medela AG, Smith & Nephew plc, Paul Hartmann, Talley Group Limited, ConvaTec Inc., 3M, DeRoyal Industries, Inc., Molnlycke Health Care AB, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Negative Pressure Wound Therapy Market Strategic Shifts & Innovations
Three interconnected developments are restructuring how negative pressure therapy reaches patients: hardware miniaturization, regulatory data requirements, and procurement centralization. Each trend carries distinct implications for product development timelines and commercial access strategies.
Single-use disposable NPWT devices are electrifying competitive dynamics by collapsing the traditional capital equipment leasing model. Homecare agencies in Germany and the United Kingdom are adopting these systems at twice the rate of reusable alternatives. This shift is compressing service revenue streams while expanding consumable margin pools for manufacturers with integrated dressing portfolios.
The EU Medical Device Regulation's post-market surveillance obligations now mandate systematic clinical follow-up for active wound therapy devices. Manufacturers must establish prospective registries tracking device-related adverse events across multiple member states. Class III device categories face the steepest compliance burden, with notified bodies requiring real-world evidence generation plans as a condition of CE certificate renewal.
Hospital procurement consortia in France, Italy, and Spain are consolidating tender volumes through national purchasing alliances. Independent homecare agencies respond by fragmenting the post-acute channel through direct manufacturer relationships. This bifurcation is most visible in Germany, where regional hospital networks negotiate centralized contracts while municipal nursing services maintain decentralized sourcing autonomy.
Europe Negative Pressure Wound Therapy Market Segmentation
NPWT purchasing patterns diverge sharply between capital-intensive reusable systems and high-margin disposable alternatives. Understanding these splits enables manufacturers to align R&D investment with reimbursement pathways and channel economics.
Product Type:
Volume concentrates in reusable pump configurations, while premium expansion flows toward single-use and portable formats.
- Static NPWT:Stationary pump-and-canister systems deliver continuous sub-atmospheric pressure through wall-mounted or bedside units. Hospital procurement consortia in Germany and France favor these configurations for inpatient surgical wards where power reliability outweighs mobility requirements.
- Single-Use NPWT:Fully disposable devices integrate miniature pumps with sealed dressing assemblies, eliminating cross-contamination risks and capital depreciation. Long-term care facilities across the Netherlands and Belgium are adopting these systems fastest as infection control mandates tighten.
- Portable NPWT:Battery-powered compact units enable ambulatory therapy during patient mobility. Germany's G-BA innovation funding pathway specifically covers these devices for homecare reimbursement.
- Vacuum-Assisted Closure:Proprietary branded systems with specialized foam configurations and controlled pressure algorithms. These retain pricing power in post-acute settings where clinical protocol standardization matters.
Mature deployment sits with Static NPWT. Newer deployment is concentrated in Single-Use NPWT.
End User:
Channel bifurcation separates centralized hospital purchasing from fragmented homecare sourcing.
- Hospitals:Acute care institutions with centralized procurement through national purchasing alliances. These buyers prioritize device durability, training infrastructure, and service contracts over per-unit cost.
- Homecare:Municipal nursing services and independent agencies managing post-acute wound protocols outside institutional walls. Reimbursement density in Germany and the United Kingdom drives volume here.
- Specialty Clinics:Outpatient wound care centers with focused chronic wound caseloads. These facilities balance clinical autonomy against budget constraints from regional health authorities.
- Long-Term Care Facilities:Nursing homes and rehabilitation centers with multi-patient environments and elevated infection risks. Single-use NPWT adoption is climbing the fastest in this channel.
Procurement centralization dominates hospital purchasing. Sourcing fragmentation characterizes homecare agency buying.
Application:
Wound severity and reimbursement coding determine therapy intensity and device selection.
- Surgical Wounds:Post-operative incisions and dehisced closures requiring immediate granulation support. These cases drive highest utilization in German and French hospital systems with established enhanced recovery protocols.
- Chronic Wounds:Venous leg ulcers, diabetic foot ulcers, and pressure injuries with extended healing timelines. Poland and Romania show sub-15% NPWT penetration for these indications despite expanding social insurance coverage.
- Traumatic Wounds:Acute injuries from accidents or surgical debridement requiring rapid edema reduction. Emergency department adoption varies by national trauma network configuration.
- Burn Wounds:Partial-thickness and full-thickness thermal injuries where NPWT stabilizes wound beds before grafting. Specialized burn centers in Sweden and Italy maintain dedicated protocols.
Reimbursement maturity anchors surgical wound applications. Penetration gaps persist in chronic wound management.
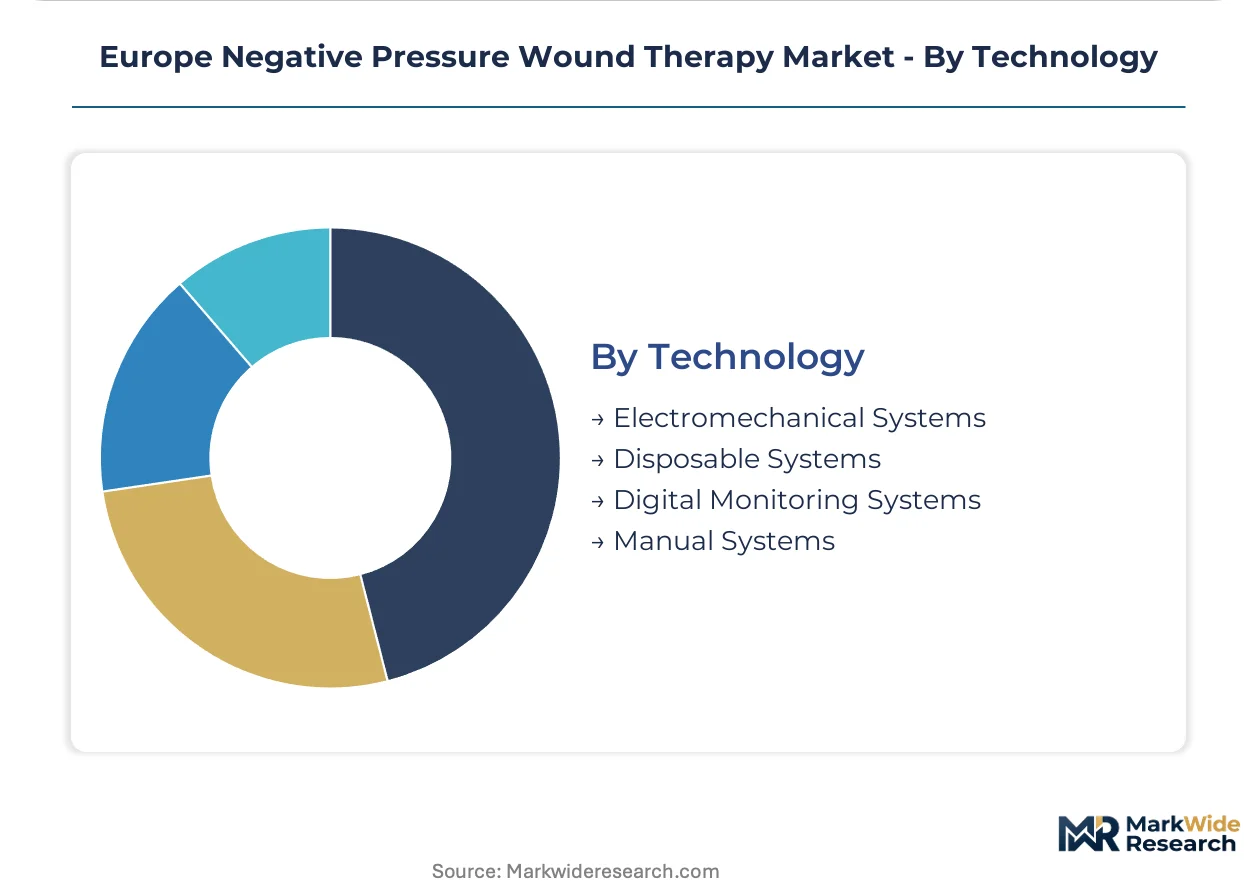
Technology:
Mechanical sophistication separates premium digital systems from basic manual alternatives.
- Electromechanical Systems:Programmable pumps with pressure modulation, alarm functions, and canister monitoring. These dominate hospital tenders where clinical staff require real-time feedback.
- Disposable Systems:Single-use mechanical or battery-powered devices without repair infrastructure. Manufacturing scale economies in German chemical processing clusters support cost reduction.
- Digital Monitoring Systems:Bluetooth-enabled pressure sensors with electronic health record integration and remote adherence tracking. EU MDR post-market surveillance requirements are accelerating R&D here.
- Manual Systems:Basic vacuum generation through hand pumps or simple mechanical suction without electronic components. Budget-constrained Southern European markets retain these for superficial wounds.
Electromechanical platforms retain installed base dominance. Digital Monitoring Systems are gaining share fastest among technology categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for negative pressure wound therapy concentrates in Germany, where chronic wound prevalence and dense reimbursement infrastructure create the continent's highest procurement volumes. Hospital procurement consortia and homecare agencies across the region are diverging in their sourcing strategies as post-acute protocols shift toward outpatient settings.
Germany
The G-BA innovation funding pathway now reimburses portable NPWT for homecare, accelerating volumes outside hospital walls. The EU MDR compliance burden falls heaviest here due to the density of active device manufacturers requiring notified body oversight. Manufacturing clusters in North Rhine-Westphalia and Baden-Württemberg host specialized pump assembly operations serving institutional buyers.
United Kingdom
NHS procurement frameworks consolidate tender volumes through national purchasing alliances, compressing margins for reusable system suppliers. The Medicines and Healthcare products Regulatory Agency enforces post-market surveillance aligned with EU MDR standards despite Brexit. London and the Southeast concentrate specialty clinic demand where outpatient wound protocols drive portable device adoption.
France
ANSM post-market surveillance standards influence product design specifications for active wound devices entering the market. Regional hospital networks negotiate centralized contracts while independent homecare agencies maintain fragmented sourcing relationships. The Île-de-France region anchors demand through acute care institutions with established enhanced recovery after surgery protocols.
Netherlands
Long-term care facilities prioritize single-use disposable systems to meet tightening infection control mandates in multi-patient environments. The Dutch Healthcare Authority shapes reimbursement density for outpatient NPWT through its tariff-setting mechanisms. Eindhoven's medical technology corridor supports component supply for sealed dressing assemblies.
Poland
Sub-15% NPWT utilization rates for chronic venous ulcers persist despite expanding social insurance coverage, creating penetration headroom. The Office for Registration of Medicinal Products, Medical Devices and Biocidal Products administers conformity assessment timelines that lag Western European benchmarks. Warsaw and Krakow concentrate emerging homecare agency networks adopting portable therapy protocols.
Europe Negative Pressure Wound Therapy Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue single-use disposable configurations and digital monitoring integration. The vendor base stratifies across three maturity levels: multinational wound care conglomerates with direct-to-institutional infrastructure, mid-scale specialists in ambulatory pump engineering, and regional distributors assembling hybrid portfolios. Competitive positioning hardens around M&A activity targeting dressing technology capabilities and strategic partnerships with hospital procurement consortia.
Among diversified health care conglomerates, 3M and Cardinal Health, Inc. occupy positions spanning multiple wound therapy modalities. Smith & Nephew plc exemplifies the institutional-direct archetype through its United Kingdom and Germany sales infrastructure. Medela AG anchors the specialized pump engineering segment with focused expertise in ambulatory system design. Molnlycke Health Care AB represents integrated portfolio players pairing dressing assemblies with therapy devices.
| Leading Market Players |
|---|
| Cardinal Health, Inc. |
| Medela AG |
| Smith & Nephew plc |
| Paul Hartmann |
| Talley Group Limited |
| ConvaTec Inc. |
| 3M |
| DeRoyal Industries, Inc. |
| Molnlycke Health Care AB |
| Others |
Cost & Logistics Intelligence
Biomedical engineering talent clusters in Germany's North Rhine-Westphalia and Baden-Württemberg regions feed labor-cost differentials into three-tier spreads separating premium electromechanical systems from standard portable units and economy manual alternatives.
Pricing Analysis
Volume concentrates in reusable pump configurations while margin expansion flows toward single-use disposable formats. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked Class III devices with full clinical evidence packages from basic systems meeting minimum MDR requirements. Price differentiation rests on certification tier and after-sales service bundling. Cost compression in the standard tier is intensifying because hospital procurement consortia are consolidating tender volumes through national purchasing alliances. Homecare agencies show highest price sensitivity due to fragmented sourcing and municipal budget constraints, while specialized burn centers demonstrate lowest sensitivity where clinical protocol standardization dominates procurement criteria.
Supply Chain Analysis
ISO 13485 certification and MDR technical documentation requirements gate component supply, concentrating qualified suppliers in Germany, Belgium, and the Netherlands. Medical-grade polyurethane foam for sealed dressings draws from German and Belgian chemical processors, while miniature pump assemblies source from Swiss and German precision manufacturing clusters. Single-source vulnerability sits with specialized medical-grade polymer suppliers serving dressing assembly operations. Distribution runs through hospital procurement consortia in France and Italy alongside direct manufacturer relationships with independent homecare agencies in Germany and the United Kingdom.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Notified body capacity constraints for MDR conformity assessments prop pricing power for manufacturers with existing CE certificates, creating supply-constrained conditions favoring incumbents over new entrants awaiting approval timelines.
For Market Incumbents: Deploy backward integration into medical-grade foam production to secure input supply against Belgian and German chemical processor concentration. Consolidate service revenue streams through long-term hospital system partnerships before single-use disposables collapse the capital equipment leasing model. Channel control represents the critical lever as procurement centralization accelerates across France, Italy, and Spain. For New Entrants and Emerging Players: Capture chronic venous ulcer applications in Poland and Romania where sub-15% NPWT utilization rates persist despite expanding social insurance coverage. Digital pressure monitoring integration with electronic health record systems offers the most penetrable technology wedge. A direct-to-homecare-agency go-to-market angle bypasses consolidated hospital procurement barriers. For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale pump engineering specialists given G-BA innovation funding pathway expansion into homecare reimbursement. Long-term viability frames around 5-10 year regulatory compliance moats rather than short-term volume capture. Dressing technology capabilities represent the priority acquisition archetype. The signal to watch is MDR certificate renewal rates among second-tier manufacturers as real-world evidence requirements escalate.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | MDR compliance timelines compress competitive windows for active wound device categories. |
| Hospital System Partnership | NHS and German regional networks consolidate procurement through national purchasing alliances. |
| Software Companion Development | Bluetooth-enabled pressure sensors align with EU MDR post-market surveillance obligations. |
| Reimbursement Strategy | G-BA innovation funding pathway shapes portable NPWT adoption in German homecare settings. |
| Backward Integration | Captive supply of medical-grade polyurethane foam reduces Belgian and German processor dependency. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and regulatory affairs specialists at notified bodies combined with secondary validation from EU MDR submission databases, hospital procurement records, and national sickness fund reimbursement tariffs. Bottom-up device shipment modeling and top-down healthcare expenditure triangulation reconciled volume estimates.
Data-stream reconciliation across manufacturer shipment reports, import-export statistics, and reimbursement claim volumes informed the analytical framework. Segmentation dimensions modeled include product type, end user channel, wound application severity, and technology sophistication tier across the projection horizon. CAGRs derived from fitted growth curves applied to base-year estimates. Industry-specific forecast inputs incorporated G-BA reimbursement pathway expansion rates and MDR certificate renewal timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to notified body capacity expansion and polymer supply chain disruptions. Forecasts reflect assumptions regarding reimbursement stability and regulatory compliance cost trajectories. A model refresh is warranted upon material change in MDR implementation enforcement or G-BA tariff adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Post-Operative Wound Treatment Market
Wound Care
Next Generation Wound Closure Device Market
Wound Care
Liquid Bandages Market
Wound Care
North America Negative Pressure Wound Therapy Market
Wound Care
Wound Measurement Devices Market
Wound Care
Bioadhesive Wound Care Market
Wound Care
Global Burn Care Market
Wound Care
Europe Compression Bandages Market
Wound Care
Bioactive Wound Care Market
Wound Care
Wound Contact Layer Dressing Market
Wound Care
Europe Advanced Wound Care Market
Wound Care
Enzymatic Wound Debridement Market
Wound Care
Asia Pacific Negative Pressure Wound Therapy Market
Wound Care
Maggot Debridement Market
Wound Care
Wound Care Centers Market
Wound Care
Topical Wound Agents Market