
 Interactive Wound Dressing Market | 2026-2036
Interactive Wound Dressing Market Size, Share, and Industry Trends Forecast 2026-2036
Interactive Wound Dressing Market Outlook
The EU Medical Device Regulation is consolidating the cost-of-entry calculus for interactive wound dressing manufacturers seeking CE marking in Europe. Smith & Nephew plc leverages its regulatory affairs infrastructure to sustain market access across multiple notified body jurisdictions. Mölnlycke Health Care AB anchors its competitive position through specialized hydrocolloid manufacturing scale in Scandinavia. 3M Company differentiates via technology leadership in electrotherapy-integrated dressing platforms.
Interactive wound dressings comprise advanced materials—hydrocolloids, alginates, foams, and films—engineered with bioactive or sensor-enabled layers that respond to wound exudate, pH shifts, or infection biomarkers, primarily serving chronic wound management and post-surgical recovery. Hydrocolloid dressings dominate current volume due to established reimbursement pathways, while smart bandages with wearable sensors represent the fastest-expanding technology segment as remote patient monitoring protocols mature. Burn care applications command premium pricing, though chronic wounds generate the largest aggregate margin pool through recurring replacement cycles.
FDA 510(k) clearance requirements and the EU MDR's clinical evidence standards shape product development timelines and commercialization costs for manufacturers targeting transatlantic distribution. Japan's PMDA and South Korea's MFDS impose additional biocompatibility testing protocols that filter out smaller entrants lacking dedicated regulatory teams. Stakeholders must monitor evolving digital health reimbursement codes that determine whether sensor-embedded dressings receive separate payment from standard wound care supplies.
Market Dynamics
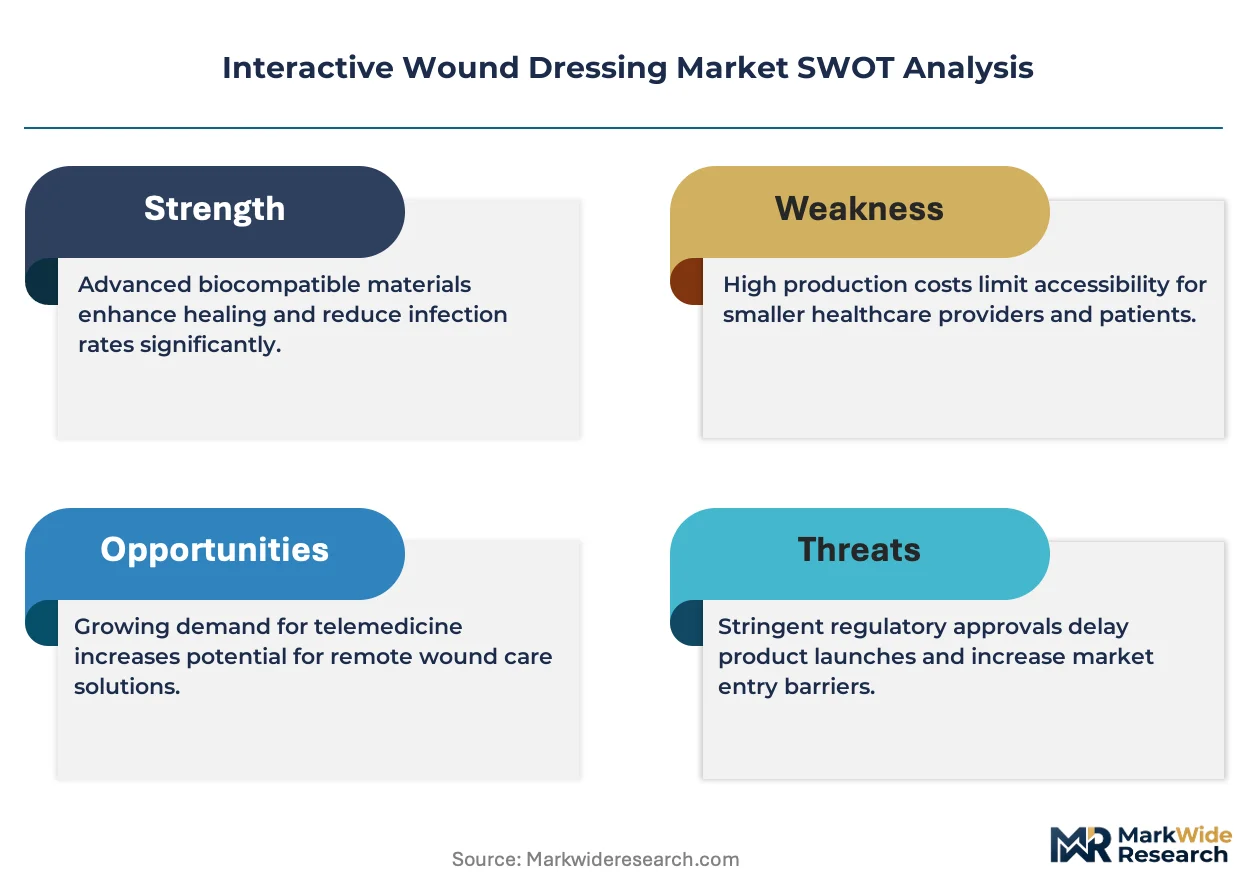
Hospital procurement consolidation across Germany and sensor-embedded dressing reimbursement uncertainty are compressing commercial timelines for interactive wound dressing manufacturers while accelerating platform-level competition.
Growth Catalysts
- EU MDR Clinical Evidence Standards:The EU Medical Device Regulation's tightened biocompatibility testing requirements for antimicrobial coatings is filtering out subscale competitors and concentrating market share among established notified body relationships.
- Home Care Sensor Adoption:Smart bandages with wearable sensors are expanding into home care settings as remote patient monitoring protocols mature and reimbursement pathways for digital wound management stabilize.
- German Hospital Procurement Consolidation:Technology-integrated wound management platforms are capturing preference in Germany's consolidated hospital procurement landscape, favoring vendors with full-stack platform capabilities over single-product suppliers.
Market Restraints
- Silver Price Volatility:Antimicrobial coating formulations dependent on silver nanoparticles face margin compression from precious metal input cost swings, forcing reformulation toward copper-based alternatives.
- Notified Body Capacity Bottleneck:EU MDR transition has thinned the pool of designated conformity assessment bodies, extending CE marking timelines and freezing commercialization schedules for mid-tier manufacturers.
- Hydrogel Substitution Pressure:Conventional hydrogel dressings with passive moisture management continue capturing price-sensitive chronic wound segments, limiting premium pricing capture for sensor-enabled alternatives.
Strategic Opportunities
- Burn Care Premium Segmentation:Specialized burn centers in the United States and Germany command pricing multiples for bioactive dressings with integrated pain management layers, creating margin pools distinct from commodified chronic wound supplies.
- Japan PMDA Digital Health Pathway:Japan's Pharmaceuticals and Medical Devices Agency has established accelerated review tracks for software-as-medical-device wound monitoring, opening regulatory arbitrage for sensor-embedded platforms ahead of EU MDR harmonization.
- Post-Acute Care Channel Expansion:Skilled nursing facilities are emerging as a direct procurement channel bypassing traditional hospital supply chain intermediaries, enabling manufacturer-direct relationships with volume commitment structures.
Industry Challenges
- Biocompatibility Testing Talent Scarcity:ISO 10993-5 cytotoxicity assessment expertise is concentrated among contract research organizations with 18-month backlogs, delaying product iteration cycles for antimicrobial coating developers.
- Sensor-Dressing Integration Complexity:Embedding flexible electronics into hydrocolloid substrates without compromising exudate management performance requires novel manufacturing processes with unproven scale economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Interactive Wound Dressing Market |
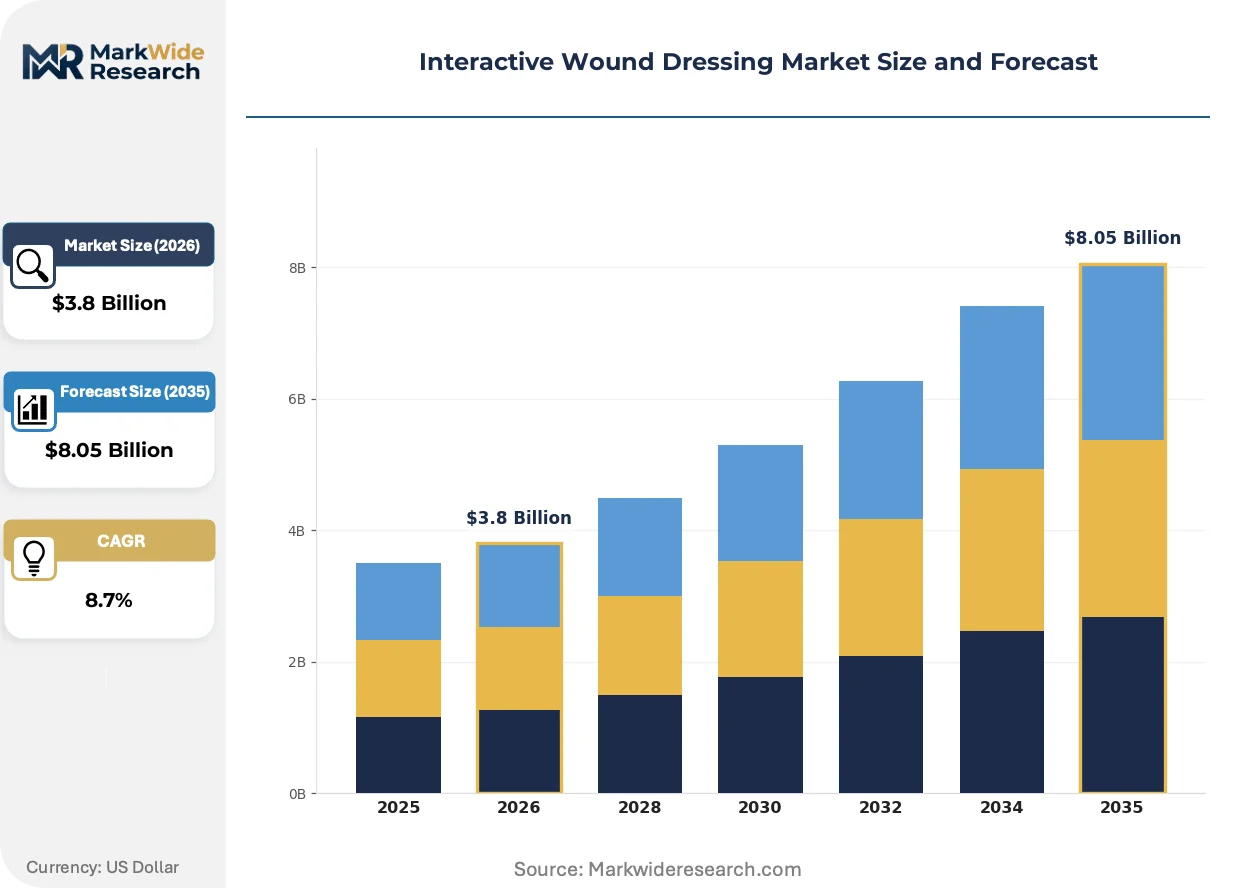
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrocolloid Dressings, Alginate Dressings, Foam Dressings, Film Dressings Technology: Electrotherapy, Smartphones, Wearable Sensors, Smart Bandages End User: Hospitals, Home Care, Clinics, Nursing Facilities Application: Chronic Wounds, Surgical Wounds, Traumatic Wounds, Burn Care |
| Companies Covered | Smith & Nephew plc, Mölnlycke Health Care AB, 3M Company, ConvaTec Group PLC, Coloplast A/S, Cardinal Health, B. Braun Melsungen AG, Medline Industries, Paul Hartmann AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Interactive Wound Dressing Market Strategic Shifts
Electrotherapy integration and real-time biomarker sensing are collapsing the distinction between passive wound coverage and active therapeutic intervention, restructuring competitive advantage around data platform ownership rather than material formulation alone.
Printed graphene biosensors are automating pH and infection biomarker detection within dressing substrates, enabling continuous wound monitoring without patient intervention. Burn centers in Germany and the United States are piloting these platforms for post-graft surveillance, compressing clinical visit frequency and shifting reimbursement logic toward episode-based wound management. The technology is automating clinical decision support by feeding real-time exudate chemistry data directly into electronic health record systems.
REACH Annex XVII restrictions on antimicrobial substance release are forcing reformulation of silver-based coatings toward bound-cation technologies with lower environmental leach rates. Manufacturers serving EU distribution must resubmit technical documentation under updated substance restrictions, disproportionately burdening mid-tier suppliers with limited regulatory affairs infrastructure. Hydrocolloid segments with legacy silver formulations face accelerated obsolescence timelines as notified bodies enforce stricter environmental risk assessments.
Hospital-at-home programs are unbundling wound care supply procurement from traditional group purchasing organization contracts, enabling direct manufacturer relationships with home health agencies. This channel shift is most visible in United States Medicare Advantage networks and Dutch home nursing cooperatives, where sensor-embedded dressings are priced as remote monitoring services rather than disposable supplies. The restructuring compresses distributor margins while opening subscription-based revenue models for technology-integrated platform vendors.
Interactive Wound Dressing Market Segmentation
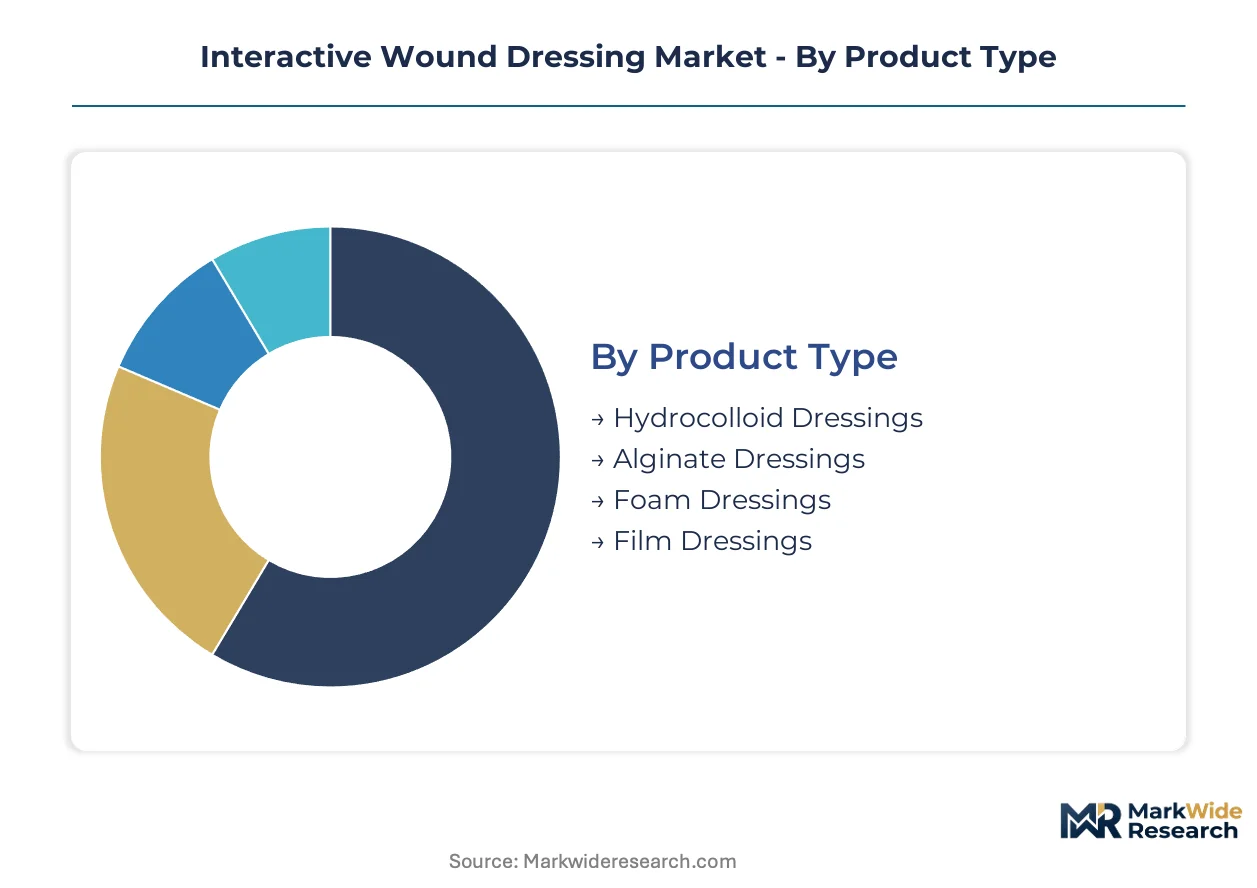
Segmentation in interactive wound dressings reveals how capital deployment, regulatory pathways, and reimbursement logic fragment commercial opportunity. Manufacturers must align R&D intensity and go-to-market infrastructure with specific segment requirements rather than pursuing horizontal coverage.
Product Type:
Hydrocolloid and alginate formulations demand the heaviest upfront manufacturing investment due to specialized coating lines and sterile packaging infrastructure.
- Hydrocolloid Dressings:These gelatin-forming composites combine pectin, gelatin, and carboxymethylcellulose with an adhesive elastomer layer. Hospital procurement networks in Germany favor hydrocolloids for their established reimbursement codes and predictable exudate absorption profiles in pressure ulcer management.
- Alginate Dressings:Derived from brown seaweed calcium salts, these dressings gel on contact with wound fluid while maintaining structural integrity. Burn centers in the United States command premium pricing for alginates with integrated pain management layers, though silver-based antimicrobial variants face REACH Annex XVII reformulation pressure.
- Foam Dressings:Polyurethane matrices with hydrophilic cores manage moderate-to-heavy exudate in post-surgical recovery.
- Film Dressings:Semi-permeable polyurethane membranes enable moisture vapor transmission while blocking bacterial ingress.
Hydrocolloid dressings absorb the bulk of installed capacity; alginate dressings are expanding most quickly.
Technology:
Technology segmentation tracks how digital integration intensity shapes development timelines and regulatory complexity.
- Electrotherapy:Integrated microcurrent generators accelerate cellular migration through bioelectrical stimulation. 3M Company's platform leadership in this segment reflects decades of materials science investment combined with FDA 510(k) clearance expertise for active therapeutic devices.
- Smart Bandages:Flexible substrate-embedded biosensors automate pH and infection biomarker detection without patient intervention. Japan's PMDA accelerated review tracks for software-as-medical-device wound monitoring are drawing development investment toward this segment ahead of EU MDR harmonization.
- Wearable Sensors:Discrete monitoring modules transmit exudate chemistry data to electronic health record systems.
- Smartphones:Companion applications for image capture and wound documentation support remote clinical decision-making.
Smart bandages capture the steepest expansion trajectory as hospital-at-home programs unbundle procurement from traditional group purchasing organization contracts.
End User:
End user segmentation determines channel economics, with direct manufacturer relationships replacing distributor intermediaries in specific settings.
- Hospitals:Consolidated procurement in Germany and the United States favors full-stack platform vendors over single-product suppliers, compressing commercial timelines for mid-tier manufacturers lacking integrated wound management systems.
- Home Care:Medicare Advantage networks and Dutch home nursing cooperatives are pricing sensor-embedded dressings as remote monitoring services rather than disposable supplies, enabling subscription-based revenue models.
- Clinics:Outpatient wound care centers prioritize rapid application products with minimal training requirements.
- Nursing Facilities:Skilled nursing facilities are emerging as a direct procurement channel with volume commitment structures that bypass hospital supply chain intermediaries.
Hospitals retain the largest aggregate margin pool through recurring replacement cycles; home care is gaining share fastest as remote patient monitoring protocols mature.
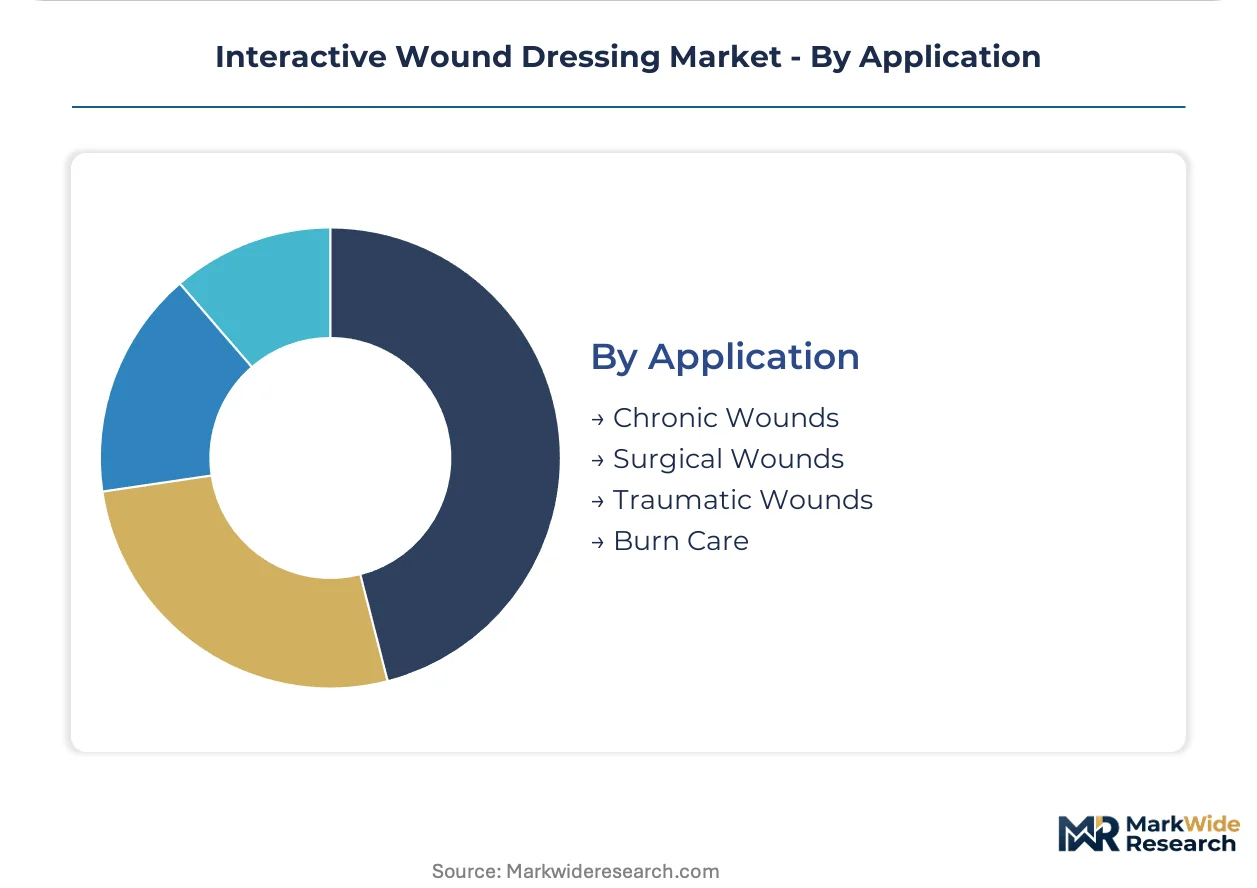
Application:
Application segmentation separates episodic acute care from chronic recurring revenue models with divergent pricing power.
- Chronic Wounds:Diabetic foot ulcers, venous leg ulcers, and pressure injuries generate recurring replacement cycles with the largest aggregate margin pool. Germany's hospital procurement consolidation particularly concentrates demand for technology-integrated platforms in this segment.
- Burn Care:Specialized centers command pricing multiples for bioactive dressings with integrated pain management and infection monitoring layers. Post-graft surveillance applications in Germany and the United States are piloting printed graphene biosensors for continuous monitoring.
- Surgical Wounds:Post-operative incision management prioritizes moisture balance and scar minimization.
- Traumatic Wounds:Emergency and military applications demand rapid deployment formats with extended wear duration.
Chronic wounds anchor manufacturer revenue stability; burn care commands the highest per-unit pricing multiples.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's MedTech cluster zones around Tübingen and Aachen concentrate sensor-embedded dressing R&D through tax-advantaged research parks. The United States, Japan, and South Korea anchor parallel development corridors shaped by distinct reimbursement and regulatory pathways.
United States
Medicare Advantage networks are unbundling wound care procurement from traditional group purchasing organization contracts. FDA 510(k) clearance requirements for electrotherapy-integrated devices filter out smaller entrants lacking dedicated regulatory teams. Boston's medical device corridor hosts multiple firms piloting printed graphene biosensors for post-graft surveillance.
Germany
Hospital procurement consolidation across North Rhine-Westphalia and Bavaria favors full-stack platform vendors over single-product suppliers. EU MDR biocompatibility testing requirements for antimicrobial coatings are concentrating market share among established notified body relationships. The Tübingen medical technology cluster anchors specialized hydrocolloid manufacturing scale serving consolidated hospital networks.
Japan
PMDA accelerated review tracks for software-as-medical-device wound monitoring are drawing development investment ahead of EU MDR harmonization. METI funding programs support flexible electronics integration into dressing substrates. The Kansai region's materials science infrastructure supports novel manufacturing process development for sensor-dressing integration.
South Korea
MFDS biocompatibility testing protocols filter out smaller entrants lacking dedicated regulatory affairs infrastructure. Government-backed digital health initiatives accelerate remote patient monitoring protocol adoption. Seoul's biomedical engineering clusters concentrate wearable sensor module development for continuous exudate chemistry monitoring.
United Kingdom
NHS England procurement frameworks are restructuring toward episode-based wound management reimbursement. MHRA post-Brexit regulatory pathways diverge from EU MDR timelines, creating parallel conformity assessment requirements. London's health technology accelerators support hospital-at-home program expansion with direct manufacturer-home health agency relationships.
Interactive Wound Dressing Market Competitive Environment
United States and German producers anchor the premium technology tier; Scandinavian and Japanese specialists hold differentiated positions in material formulation and sensor integration. The vendor base stratifies across three tiers: multinational conglomerates with full-stack platform capabilities, mid-cap regional specialists with notified body relationships, and emerging sensor-technology firms seeking regulatory arbitrage. Strategic archetypes include regulatory infrastructure owners, manufacturing scale operators, and digital health platform builders. Competitive moves concentrate on M&A for sensor technology access and capacity expansion in hydrocolloid substrate production.
Among established platform operators, Smith & Nephew plc and Mölnlycke Health Care AB exemplify the regulatory infrastructure archetype through sustained market access across multiple notified body jurisdictions. 3M Company occupies a position representing technology leadership in active therapeutic device categories. These three entities anchor the competitive landscape through divergent strategic postures: regulatory affairs scale, specialized manufacturing concentration, and electrotherapy platform development respectively.
| Leading Market Players |
|---|
| Smith & Nephew plc |
| Mölnlycke Health Care AB |
| 3M Company |
| ConvaTec Group PLC |
| Coloplast A/S |
| Cardinal Health |
| B. Braun Melsungen AG |
| Medline Industries |
| Paul Hartmann AG |
| Others |
Value Chain & Pricing Dynamics
ISO 10993-5 cytotoxicity assessment specialists in Massachusetts and Baden-Württemberg command wage premiums that propagate through three-tier pricing structures separating sensor-integrated platforms from passive hydrocolloid alternatives. Labor-cost differentials between EU MDR-notified body jurisdictions and non-designated manufacturing zones widen spreads between premium-certified and economy-tier dressings.
Pricing Analysis
Short lead-time premiums for CE-marked antimicrobial coatings under EU MDR compressed timelines separate urgent procurement pricing from standard contract terms. Subscription-based revenue models for sensor-embedded platforms stratify across premium, standard, and economy tiers based on data analytics bundling and remote monitoring service levels. Cost compression in silver-based formulations is intensifying because REACH Annex XVII reformulation requirements force technical documentation resubmission. Hospital procurement committees in Germany exhibit lowest price sensitivity for burn care bioactive dressings with integrated pain management, while Dutch home nursing cooperatives prioritize per-unit economy in chronic wound segments.
Supply Chain Analysis
CE marking and FDA 510(k) qualification gating concentrates hydrocolloid substrate production in Germany, the United States, and Japan through sterile packaging infrastructure requirements. Flexible electronics for smart bandages draw from South Korean sensor module foundries, Scandinavian pectin suppliers, and Japanese graphene printing specialists. Single-source vulnerability pervades notified body capacity for EU MDR antimicrobial coating assessments. Distribution runs through hospital group purchasing organizations in consolidated German networks, with direct manufacturer relationships emerging in Medicare Advantage and Dutch home nursing channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Medical Device Regulation's clinical evidence standards for antimicrobial coatings erect a cost-of-compliance moat that filters subscale competitors and entrenches established notified body relationships as durable competitive advantages.
For Market Incumbents: Anticipate hydrogel substitution pressure in price-sensitive chronic wound segments by accelerating electrotherapy platform differentiation and securing backward integration into hydrocolloid substrate production. Lock in notified body capacity reservations ahead of EU MDR transition bottlenecks. Defend margin position through burn care premium segmentation with integrated pain management layers that command pricing multiples insulated from commodity dressing competition. For New Entrants and Emerging Players: Capture Japan PMDA accelerated review tracks for software-as-medical-device wound monitoring ahead of EU MDR harmonization, leveraging regulatory arbitrage to establish sensor-embedded platform credibility. Skilled nursing facilities as direct procurement channels offer penetrable white-space bypassing hospital supply chain intermediaries. Partner with home health agencies on subscription-based remote monitoring service models rather than competing on per-unit disposable supply pricing. For Investors and Strategic Acquirers: Re-rating potential sits with digital health platform builders given hospital-at-home program expansion and unbundling of wound care procurement from traditional group purchasing organization contracts. Long-term viability over a multi-year horizon favors sensor-dressing integration specialists with proven manufacturing scale economics. Watch for inflection in digital health reimbursement code finalization that determines separate payment eligibility for sensor-embedded dressings.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evidence standards filter subscale competitors through notified body capacity bottlenecks. |
| Hospital System Partnership | Consolidated German procurement networks favor full-stack platform vendors with integrated wound management capabilities. |
| Software Companion Development | PMDA accelerated review tracks for SaMD wound monitoring enable regulatory arbitrage ahead of EU harmonization. |
| Reimbursement Strategy | Digital health code finalization determines separate payment eligibility for sensor-embedded remote monitoring services. |
| Backward Integration | In-house hydrocolloid substrate production secures margin control against silver price volatility and coating reformulation costs. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs combined with primary interviews across regulatory affairs directors, hospital procurement managers, biomedical engineers, and GPO contracts managers. FDA 510(k) clearance databases, EU MDR notified body designation lists, CMS Medicare reimbursement schedules, and hospital procurement contract repositories provided validation layers. Bottom-up segment sizing and top-down macroeconomic reconciliation triangulated volume and value estimates.
Data-stream reconciliation across product type, technology integration intensity, end-user channel, and application severity dimensions structured the analytical framework throughout the projection horizon. CAGRs derived from segment-level growth trajectory modeling incorporating EU MDR transition timelines, digital health reimbursement pathway maturation, and hospital procurement consolidation patterns. Sensor-dressing integration cost curves and flexible electronics manufacturing scale economics informed technology adoption assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to notified body capacity expansion, digital health reimbursement code finalization, and silver nanoparticle substitution economics. Forecasts reflect documented assumptions regarding EU MDR enforcement consistency and hospital-at-home program penetration rates. A model refresh is warranted upon material change in FDA software-as-medical-device guidance or EU MDR substance restriction amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Wound Closure and Advanced Wound Care Market
Wound Care
Philippines Wound Care Market
Wound Care
Biopatches Market
Wound Care
Advanced Wound Care Market
Wound Care
Topical Wound Agents Market
Wound Care
Europe Compression Bandages Market
Wound Care
Wound Retractor Market
Wound Care
Global Surgical Drains/Wound Drainage Market
Wound Care
Wound Healing Supplement Market
Wound Care
Maggot Debridement Market
Wound Care
Wound Care Sealants Market
Wound Care
Hydrocolloid Dressing Market
Wound Care
Wound Cleanser Products Market
Wound Care
Wound Irrigation Devices Market
Wound Care
Asia Pacific Wound Care Biologics Market
Wound Care
Europe Negative Pressure Wound Therapy Market