
 Advanced Wound Management Market | 2026-2036
Advanced Wound Management Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced Wound Management Market Analysis
Software-enabled remote monitoring for negative pressure wound therapy is consolidating the service layer around device utilization rather than unit sales alone. Smith & Nephew leverages connected therapy platforms to sustain recurring revenue from hospital accounts. Mölnlycke Health Care AB anchors its position through direct-to-facility logistics networks across Nordic and Continental European markets. Coloplast differentiates via specialized ostomy and wound care integration that extends clinician training touchpoints beyond product delivery.
Advanced wound management encompasses dressings, grafts, negative pressure systems, and antiseptic solutions engineered with hydrocolloid, foam, alginate, or collagen matrices to maintain moist healing environments, manage exudate, and accelerate tissue regeneration in chronic, surgical, burn, and traumatic wound indications. Negative pressure wound therapy commands premium positioning due to capital equipment attachment and disposable cartridge replenishment cycles that generate sustained margin pools. Foam and alginate technologies lead material innovation for moderate-to-heavy exudate applications, while hydrocolloid dressings occupy mature, cost-sensitive segments in clinic and long-term care settings where reimbursement pressure limits pricing flexibility.
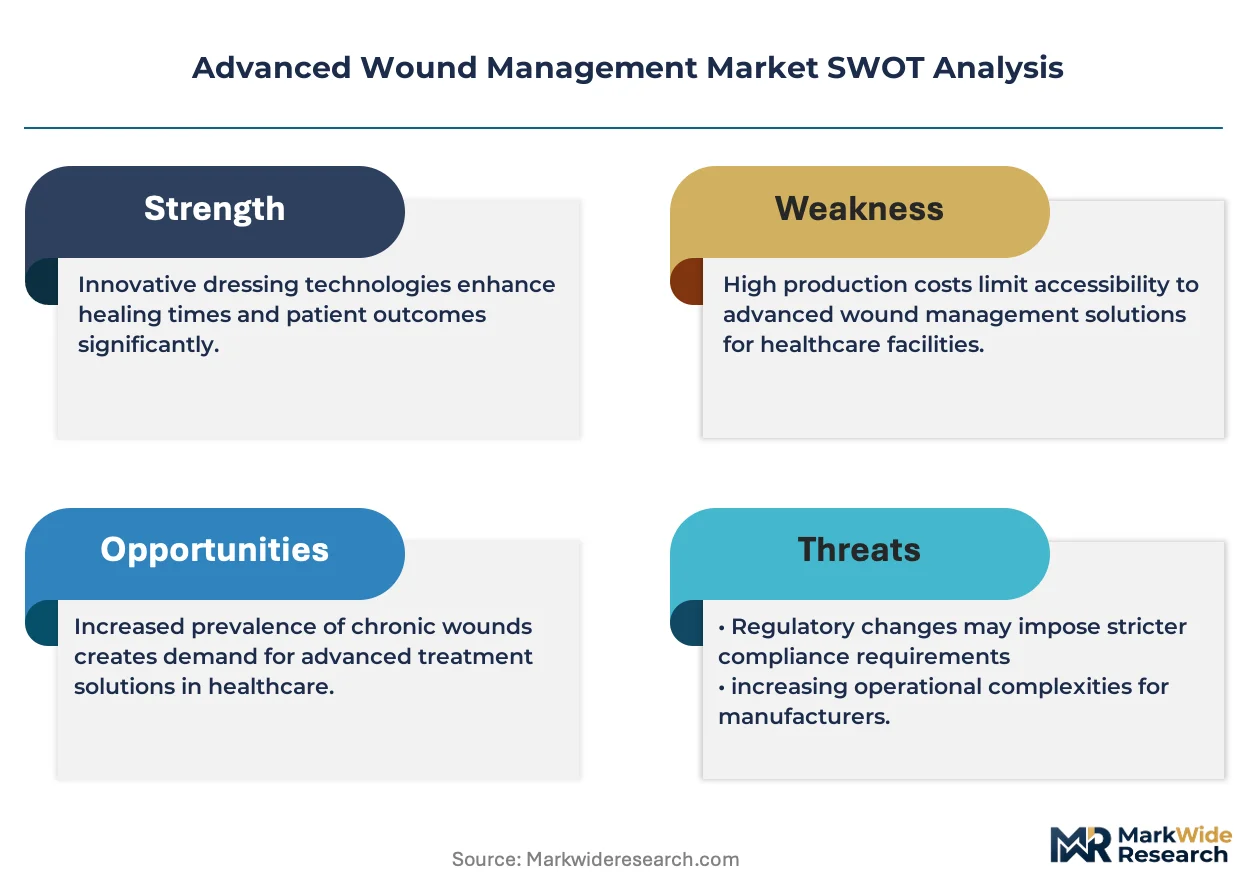
The FDA's 510(k) framework and the EU Medical Device Regulation (MDR) impose divergent evidentiary requirements that shape product development timelines and market access costs for manufacturers seeking dual-territory approval. Health Technology Assessment bodies in Germany and Japan further condition reimbursement on demonstrated cost-effectiveness against standard-of-care comparators, compressing margins for undifferentiated offerings. Stakeholders must monitor how post-market surveillance obligations under MDR Article 83 reshape competitive economics for legacy product portfolios.
Market Dynamics
The migration from passive dressings to bioactive materials is compressing product lifecycles and forcing manufacturers to restructure R&D portfolios around regenerative substrates rather than commodity absorbency.
Growth Catalysts
- Chronic wound protocol expansion:Hospital procurement teams are mandating advanced dressing categories for diabetic foot ulcer and pressure injury pathways, pulling alginate and collagen matrices into standard order sets.
- FDA 510(k) pathway for combination products:The streamlined clearance mechanism for drug-device hybrids accelerates commercialization timelines for antimicrobial-impregnated dressings and growth-factor delivery systems.
- Aging demographics:Germany, Japan, and the United States face concentrated demand pressure as populations over 65 drive incident rates for venous leg ulcers and surgical site complications.
Market Restraints
- Reimbursement compression:Health Technology Assessment bodies in Germany and Japan condition coverage on cost-effectiveness against standard-of-care hydrocolloids, squeezing margins for novel bioactives.
- Supply concentration in collagen sourcing:Bovine and porcine tissue processors cluster in specific geographic corridors, exposing manufacturers to raw material volatility and ethical sourcing scrutiny.
- Technical limitation in exudate prediction:Dressing selection algorithms lack real-time wound fluid analytics, causing mismatches between material absorbency and actual patient needs.
Strategic Opportunities
- Remote monitoring integration:Software-enabled negative pressure systems are expanding into home care settings, creating recurring revenue streams beyond device placement.
- EU MDR Article 83 post-market surveillance:The intensified clinical follow-up mandate favors manufacturers with robust real-world evidence infrastructure, disadvantaging legacy commodity suppliers.
- Underpenetrated outpatient surgical centers:Ambulatory facilities in the United States lack standardized advanced dressing protocols, representing white space for procedure-specific kit bundling.
Industry Challenges
- Biomaterial characterization expertise:The shift toward living-cell matrices and engineered skin substitutes demands competencies in tissue engineering that traditional dressing manufacturers lack.
- Dual-territory approval complexity:Divergent evidentiary requirements between FDA 510(k) and EU MDR timelines force parallel development tracks, inflating regulatory affairs overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced Wound Management Market |
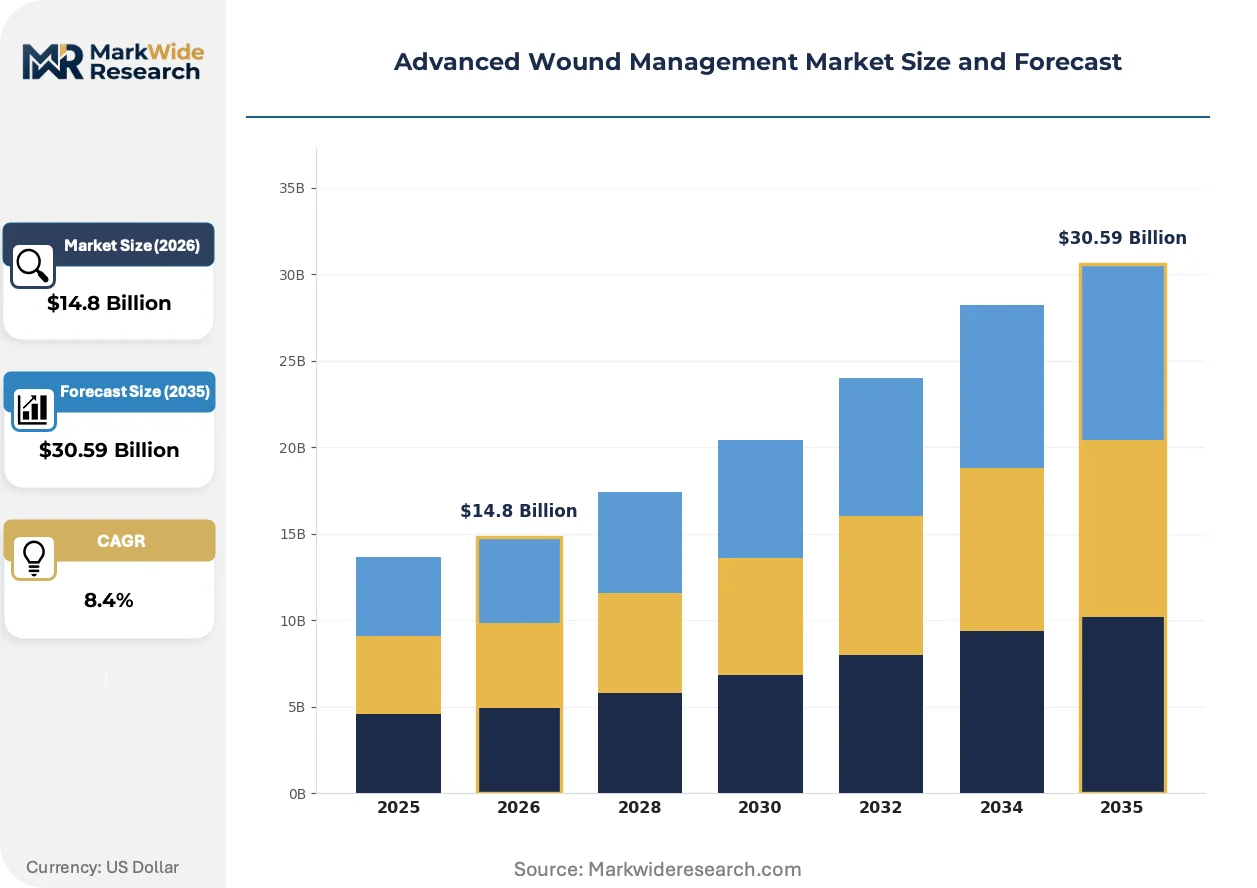
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $30.59 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dressings, Grafts, Antiseptics, Negative Pressure Wound Therapy End User: Hospitals, Home Care, Clinics, Long-term Care Facilities Technology: Hydrocolloid, Foam, Alginate, Collagen Application: Chronic Wounds, Surgical Wounds, Burns, Traumatic Wounds |
| Companies Covered | 3M, Smith & Nephew, ConvaTec, Mölnlycke Health Care AB, B. Braun Melsungen AG, Coloplast, Integra LifeSciences, Cardinal Health, Medline Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced Wound Management Market Emerging Trajectories
Material science convergence with digital health infrastructure is redefining how wound closure products generate value, shifting competitive advantage from absorption capacity to healing acceleration metrics.
Antimicrobial silver and iodine delivery systems are expanding into chronic wound protocols previously reserved for systemic antibiotics. Long-term care facilities and home health agencies are adopting these dressings at accelerating rates to reduce hospitalization triggers. The technology is expanding into reimbursement frameworks as payors recognize reduced infection-related readmission costs.
EU MDR implementation is fragmenting competitive economics across European markets. The regulation imposes clinical investigation requirements for legacy product renewals that many mid-tier manufacturers cannot absorb. Class III device categories face the steepest compliance cost escalation, prompting portfolio rationalization toward higher-margin bioactive segments.
Hospital supply chains are consolidating vendor relationships around full-line wound care suppliers capable of delivering dressings, negative pressure systems, and clinician education through single-source contracts. Integrated delivery networks in the United States are displacing fragmented purchasing across individual facility departments. Germany's hospital procurement cooperatives demonstrate the most advanced form of this concentration, leveraging volume aggregation to extract service-layer concessions.
Advanced Wound Management Market Segmentation
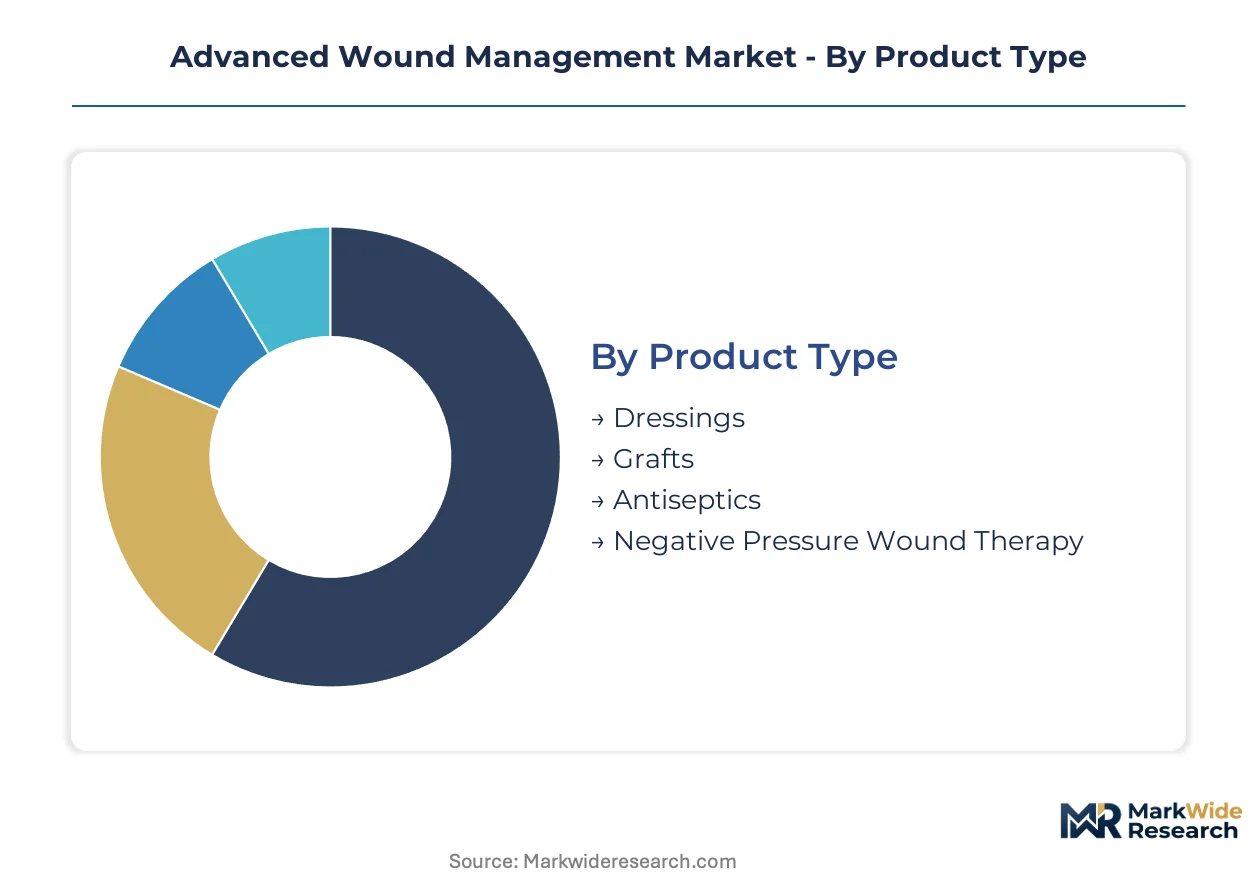
Segmentation in advanced wound management reveals how procurement decisions diverge between acute care systems seeking protocol standardization and outpatient settings prioritizing cost flexibility. Technology selection increasingly correlates with exudate management requirements rather than wound etiology alone.
Product Type:
Standardization pressure from hospital procurement teams is compressing SKU diversity, while bioactive segments command premium positioning through regenerative claims.
- Dressings:Hydrocolloid, foam, alginate, and collagen variants constitute the volume base, with alginate and collagen matrices pulling into chronic wound order sets as hospitals mandate advanced categories for diabetic foot ulcer protocols.
- Grafts:Engineered skin substitutes and biological matrices demand tissue engineering competencies that traditional manufacturers lack, concentrating supply among regenerative medicine specialists with captive bioprocessing infrastructure.
- Antiseptics:Silver and iodine delivery systems are expanding into long-term care to reduce hospitalization triggers.
- Negative Pressure Wound Therapy:Capital equipment attachment and disposable cartridge replenishment generate sustained margin pools through recurring revenue models.
Leading the category by volume: Dressings. Growing fastest: Negative Pressure Wound Therapy.
End User:
Procurement authority is migrating from individual clinicians to centralized supply chains, reshaping how manufacturers structure account relationships across facility types.
- Hospitals:Integrated delivery networks in the United States and procurement cooperatives in Germany are consolidating vendor relationships around full-line suppliers capable of delivering dressings, devices, and clinician education through single-source contracts.
- Home Care:Software-enabled remote monitoring for negative pressure systems is expanding service layers beyond device placement, creating recurring revenue streams as patients transition from acute settings.
- Clinics:Cost-sensitive segments limit pricing flexibility where reimbursement pressure constrains advanced dressing adoption.
- Long-term Care Facilities:Antimicrobial dressing adoption is accelerating to manage infection risk and avoid costly transfers.
Dominant by procurement value: Hospitals. Expanding most quickly: Home Care.
Technology:
Material innovation is shifting competitive advantage from absorption capacity to healing acceleration metrics, compressing lifecycles for commodity absorbency products.
- Collagen:Matrices derived from bovine and porcine tissue anchor bioactive positioning but expose manufacturers to raw material volatility and ethical sourcing scrutiny as supply concentrates in specific geographic corridors.
- Alginate:Seaweed-derived fibers excel in moderate-to-heavy exudate applications, with demand concentrating in hospital protocols for pressure injuries and venous leg ulcers.
- Foam:Polyurethane structures dominate negative pressure wound therapy interfaces and heavy exudate management.
- Hydrocolloid:Mature technology occupies cost-sensitive clinic and long-term care segments where reimbursement limits pricing flexibility.
Highest margin capture: Collagen. Steepest volume expansion: Alginate.
Application:
Wound etiology is becoming less deterministic of product selection than exudate profile and healing phase, blurring traditional category boundaries.
- Chronic Wounds:Diabetic foot ulcers and venous leg ulcers drive alginate and collagen matrix demand as aging populations in the United States, Germany, and Japan strain reimbursement systems.
- Surgical Wounds:Ambulatory surgical centers in the United States lack standardized advanced dressing protocols, representing white space for procedure-specific kit bundling.
- Burns:Specialized centers require engineered skin substitutes with higher regulatory evidentiary burdens.
- Traumatic Wounds:Emergency settings prioritize rapid exudate control over regenerative acceleration.
Largest addressable population: Chronic Wounds. Fastest protocol evolution: Surgical Wounds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of advanced wound dressings clusters in Germany and the United States, while consumption concentrates in aging populations across Japan and Western Europe. Supply chain proximity to collagen processors and medical device hubs shapes production geography. Demand patterns diverge sharply between acute care systems and home care transitions.
United States
Medicare reimbursement pressure for chronic wound protocols drives hospital procurement consolidation around advanced alginate and collagen matrices. The FDA's 510(k) clearance pathway accelerates commercialization timelines for antimicrobial-impregnated combination products. Minneapolis and Chicago anchor major medical device logistics networks serving integrated delivery networks.
Germany
Hospital procurement cooperatives leverage volume aggregation to extract service-layer concessions from full-line wound care suppliers. The EU Medical Device Regulation imposes clinical investigation requirements for legacy product renewals that compress margins for undifferentiated offerings. The Rhine-Ruhr corridor concentrates bioprocessing infrastructure for engineered skin substitutes.
Japan
PMDA cost-effectiveness assessments condition reimbursement coverage on demonstrated outcomes against standard-of-care hydrocolloids. METI initiatives promote domestic production of bioactive materials to reduce import dependency for chronic wound protocols. The Kansai region hosts specialized centers for diabetic foot ulcer management driving protocol innovation.
United Kingdom
NHS supply chain consolidation favors vendors capable of delivering dressings, negative pressure systems, and clinician education through single-source contracts. MHRA post-Brexit regulatory divergence creates parallel compliance tracks for manufacturers seeking dual UK-EU market access. The Greater Manchester cluster concentrates wound care research translation facilities.
France
ANSM oversight of combination products shapes development timelines for drug-device hybrids targeting surgical site infection prevention. Regional hospital groups in Île-de-France standardize advanced dressing protocols for pressure injury pathways. Lyon hosts specialized burn centers requiring engineered matrices with elevated regulatory evidentiary burdens.
Advanced Wound Management Market Vendor Landscape
Top-tier vendors anchor hospital procurement networks, while mid-cap specialists occupy bioactive material niches. The vendor base stratifies across full-line suppliers with service integration capabilities and focused technology developers with captive bioprocessing assets. Three archetypes dominate: integrated medical device conglomerates, regenerative medicine specialists, and distribution-heavy supply chain operators. Competitive moves concentrate on M&A for tissue engineering competencies and strategic partnerships for remote monitoring platform integration.
Within the integrated device tier, Smith & Nephew and Mölnlycke Health Care AB exemplify vendors consolidating service layers around connected therapy platforms and direct-to-facility logistics networks. Coloplast occupies a position bridging ostomy specialization with wound care integration. These three anchors represent distinct geographic footprints and service model architectures rather than interchangeable commodity positioning.
| Leading Market Players |
|---|
| 3M |
| Smith & Nephew |
| ConvaTec |
| Mölnlycke Health Care AB |
| B. Braun Melsungen AG |
| Coloplast |
| Integra LifeSciences |
| Cardinal Health |
| Medline Industries |
| Others |
Supply Flow & Price Mechanics
Hospital procurement consolidation around single-source contracts for advanced dressing categories is forcing manufacturers to absorb service-layer costs while defending bioactive material premiums. This buyer concentration reshapes supplier economics, compressing margins on commodity hydrocolloids while sustaining pricing power for collagen matrices with regenerative claims.
Pricing Analysis
Margin tightening in standard dressing tiers reflects Health Technology Assessment benchmarking against hydrocolloid baselines in Germany and Japan. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and clinical evidence depth. Cost-down pressure on alginate and foam segments accelerates because procurement cooperatives extract volume concessions for protocol-standardized order sets. Long-term care facilities exhibit highest price sensitivity; hospital systems with GPO contracts demonstrate lowest.
Supply Chain Analysis
CE marking and FDA 510(k) qualification gates concentrate bioprocessing infrastructure in Germany, the United States, and Denmark. Raw material sourcing draws from bovine and porcine tissue processors clustered in Midwestern US corridors and Northern European abattoir networks, with seaweed-derived alginate anchored in Norwegian and French coastal harvesting operations. Single-source vulnerability in collagen supply exposes manufacturers to ethical sourcing scrutiny and geographic concentration risk. Distribution runs through direct-to-facility logistics networks serving integrated delivery networks and hospital procurement cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Advanced wound management sits in a technology-transition phase where bioactive materials displace passive absorbency products, compressing lifecycles for commodity dressings while regenerative substrates command sustained premiums.
For Market Incumbents: Extend connected therapy platform capabilities to capture recurring revenue from remote monitoring services beyond device placement. Deepen backward integration into captive collagen bioprocessing to secure raw material supply against ethical sourcing volatility. Anchor hospital procurement relationships through clinician education bundling that raises switching costs for integrated delivery networks. For New Entrants and Emerging Players: Direct-to-clinic digital channels offer lower barrier entry for antimicrobial-impregnated dressing categories bypassing consolidated GPO contracts. Target ambulatory surgical centers in the United States with procedure-specific kit bundling where standardized advanced dressing protocols remain underdeveloped. Emphasize FDA 510(k) pathway speed-to-market against EU MDR clinical investigation burdens. For Investors and Strategic Acquirers: The window for entry favors regenerative medicine specialists with captive tissue engineering infrastructure and real-world evidence generation capabilities. Long-term viability hinges on post-market surveillance compliance under EU MDR Article 83 that disadvantages legacy commodity suppliers. Watch for inflection in hospital procurement cooperative tender awards signaling consolidation winners.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical investigation requirements compress margins for undifferentiated legacy portfolios. |
| Hospital System Partnership | Single-source contracts with integrated delivery networks lock in recurring revenue streams. |
| Software Companion Development | Remote monitoring integration for negative pressure systems extends service layers beyond device sales. |
| Backward Integration | In-house collagen bioprocessing secures supply against geographic concentration and ethical scrutiny. |
| Reimbursement Strategy | Health Technology Assessment alignment in Germany and Japan conditions market access on cost-effectiveness. |
Methodological Framework
FDA 510(k) filings, EU MDR technical documentation, and hospital procurement databases formed the secondary backbone for market sizing and competitive positioning. Primary interviews with hospital purchasing committee members, GPO contracts managers, biomedical engineers, and regulatory affairs leads at wound care manufacturers were combined with secondary validation. Bottom-up triangulation across product-level shipment data and top-down reconciliation against national reimbursement statistics anchored volume estimates.
Historical trendline analysis of dressing category adoption rates informed projection assumptions across the analysis window. Segmentation modeling captured product type, end-user facility tier, material technology, and wound application dimensions. CAGRs were derived from curve-fitting procedures applied to protocol penetration data and demographic demand drivers including diabetic foot ulcer incidence and surgical site complication rates.
Inputs from CMS Medicare claims and NHS supply chain disclosures were available through the study window; gaps in real-world evidence for bioactive healing acceleration introduce uncertainty bands around premium segment forecasts. A model refresh is warranted upon material change in EU MDR post-market surveillance enforcement or major hospital procurement cooperative restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Wound Healing Nutrition Market
Wound Care
Wound Closure Devices Market
Wound Care
Global Traditional Wound Management Market
Wound Care
Wound Healing Market
Wound Care
Philippines Wound Care Market
Wound Care
Wound Closure and Advanced Wound Care Market
Wound Care
Advanced Wound Dressings Market
Wound Care
Wound Cleanser Products Market
Wound Care
Anti-Biofilm Wound Dressing Market
Wound Care
Wound Biologics Market
Wound Care
Autologous Wound Patches Market
Wound Care
Wound Drainage Devices Market
Wound Care
North America Advanced Wound Care Market
Wound Care
Biopatches Market
Wound Care
Interactive Wound Dressing Market
Wound Care
Global Silver Wound Dressing Market